
 Sparkling Coffee Market | 2026-2036
Sparkling Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Sparkling Coffee Market Intelligence
Ready-to-drink formulation and direct-to-consumer branding is rewriting the profit structure for traditional coffee roasters. Stumptown Coffee Roasters leverages its established brand equity in specialty coffee to penetrate this new segment. Paulig operates with significant scale in European production and distribution networks. In contrast, Slingshot Coffee Co. specializes in unique flavor profiles and artisanal production methods, targeting a niche consumer base.
Sparkling coffee is a cold-brewed coffee beverage, carbonated and often infused with nitrogen to produce a creamy head and smooth mouthfeel. The product is positioned as a functional, low-sugar alternative to traditional soft drinks and energy drinks. Aluminum cans represent the dominant packaging type, valued for their portability and recyclability. While supermarkets remain a core distribution channel, flavored product types are seeing rapid expansion through online retail platforms.
Labeling standards from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate clear nutritional information. Regulations in countries like India, overseen by FSSAI, control caffeine content and additive use, directly influencing product formulation. Navigating the complex web of international food safety standards is critical for market participants. The key challenge for brands is balancing innovative flavor development with these diverse regulatory requirements.
Market Dynamics
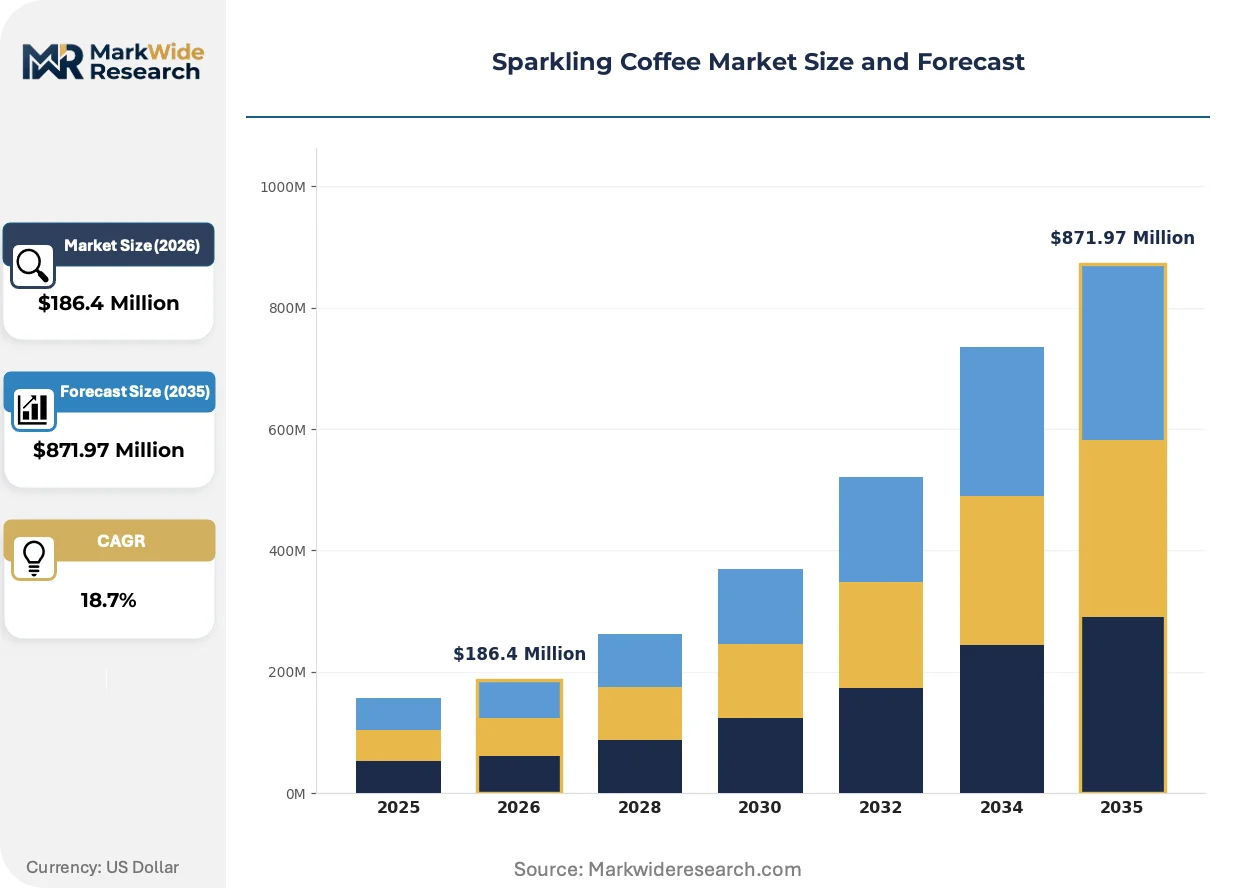
The convergence of health-consciousness and convenience culture is the central force shaping the sparkling coffee market. Consumer demand for functional beverages that offer benefits beyond simple refreshment, specifically low-sugar and natural energy, is driving product formulation and channel strategy.
Growth Catalysts
- Functional Beverage Demand:A pronounced consumer shift away from high-sugar sodas and toward functional alternatives is a primary catalyst. This trend is particularly strong among health-aware millennials in developed economies seeking natural energy sources.
- Processing Innovations:Advances in nitrogen infusion and cold brew extraction methods enhance the product's sensory attributes, creating a smoother mouthfeel and reducing acidity. These technologies improve the overall consumer experience and differentiate the product.
- Direct-to-Consumer Channels:The expansion of online retail and subscription models provides brands with a direct path to consumers. This channel bypasses traditional retail gatekeepers, enabling niche and artisanal producers to build a customer base.
Market Restraints
- Higher Production Costs:The cold brew process is more time- and resource-intensive than producing traditional coffee or soft drinks. This elevated cost structure results in a premium price point, which can limit broader market adoption.
- Coffee Bean Price Volatility:The market is directly exposed to fluctuations in the global price of coffee beans. Climate change, crop diseases, and geopolitical instability in key growing regions like Brazil and Vietnam create significant input cost uncertainty.
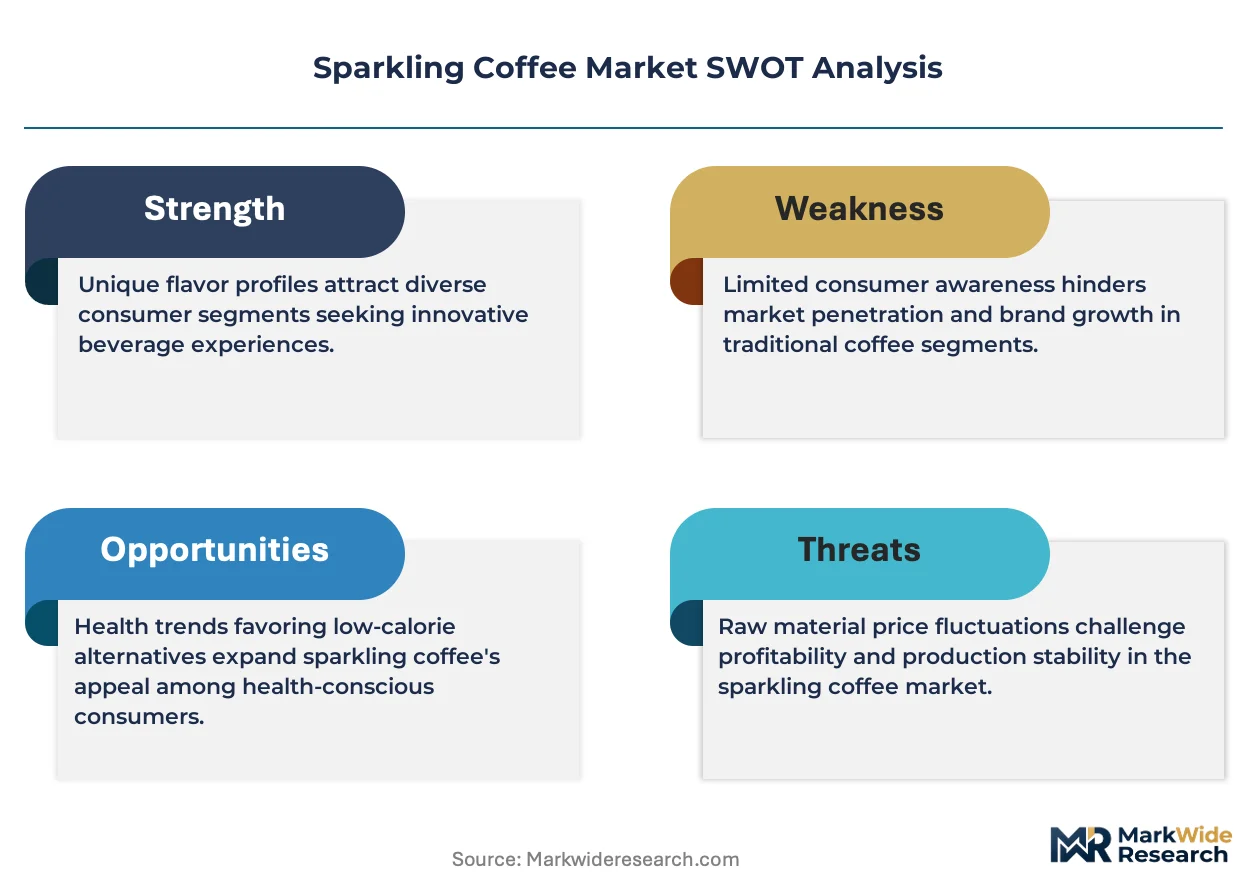
- Limited Consumer Awareness:Despite growth, sparkling coffee remains a niche category. Educating consumers about the product's taste profile and benefits requires significant marketing investment to overcome ingrained preferences for conventional coffee and sodas.
Strategic Opportunities
- Geographic Expansion:Significant opportunity exists in markets with established coffee cultures but low sparkling coffee penetration. Countries in the Asia-Pacific region, such as Japan and South Korea, represent promising targets for market entry.
- Functional Ingredient Infusion:Incorporating ingredients like adaptogens, nootropics, or CBD can broaden the product's appeal. This strategy targets consumers seeking beverages with specific wellness benefits beyond caffeine-based energy.
- Food Service Partnerships:Collaborations with restaurants, cafes, and corporate offices offer a new distribution avenue. On-tap sparkling coffee can serve as a novel, premium non-alcoholic beverage option in these settings.
Industry Challenges
- Regulatory Compliance:Adhering to a patchwork of international food safety regulations presents a major hurdle. Navigating disparate rules on caffeine limits and additives from bodies like the US FDA, EFSA in Europe, and India's FSSAI complicates formulation and labeling.
- Scaling Production:Maintaining the quality and unique flavor profiles of artisanal production while scaling up to meet mass-market demand is a significant operational challenge. It requires substantial capital investment in specialized equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sparkling Coffee Market |
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $871.97 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeinated, Decaffeinated, Flavored, Organic End User: Retail Consumers, Coffee Shops, Restaurants, Beverage Distributors Packaging Type: Cans, Bottles, Tetra Packs, Kegs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Slingshot Coffee Co., Union Coffee, DrinkVIVIC, Nongfu Spring, Upruit, MATCHLESS COFFEE SODA, Paulig, Stumptown Coffee Roasters, Keepers Sparkling Coffee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sparkling Coffee Market Strategic Shifts & Innovations
The market is defined by the fusion of coffee culture with the functional beverage movement. This evolution is recasting coffee from a traditional hot beverage into a sophisticated, ready-to-drink cold refreshment, creating new consumption occasions and consumer expectations.
Advanced cold brew extraction technology allows for a smoother, less acidic coffee base. Beverage producers are adopting this method to create a more palatable foundation for carbonation and flavor infusion. This combination of cold brew and nitrogen infusion is rendering obsolete traditional hot-brewing and simple carbonation methods, which can produce a harsh, acidic taste in a cold coffee format.
New front-of-pack labeling mandates from regulators are influencing product design and marketing. Rules from the US Food and Drug Administration (FDA) and similar transparency initiatives from the European Food Safety Authority (EFSA) compel clear disclosure of sugar and calorie content. This regulatory pressure benefits sparkling coffee, which is typically formulated with low or no sugar, by creating a clear point of differentiation on the shelf against traditional soft drinks.
Consumer purchasing behavior is moving towards direct-to-consumer (DTC) subscription services. This model bypasses the competitive landscape of traditional retail, allowing brands to build direct relationships and secure recurring revenue. The shift is most prominent among urban consumers in the United States and United Kingdom who prioritize convenience and the discovery of novel, artisanal brands not widely available in supermarkets.
Sparkling Coffee Market Segmentation
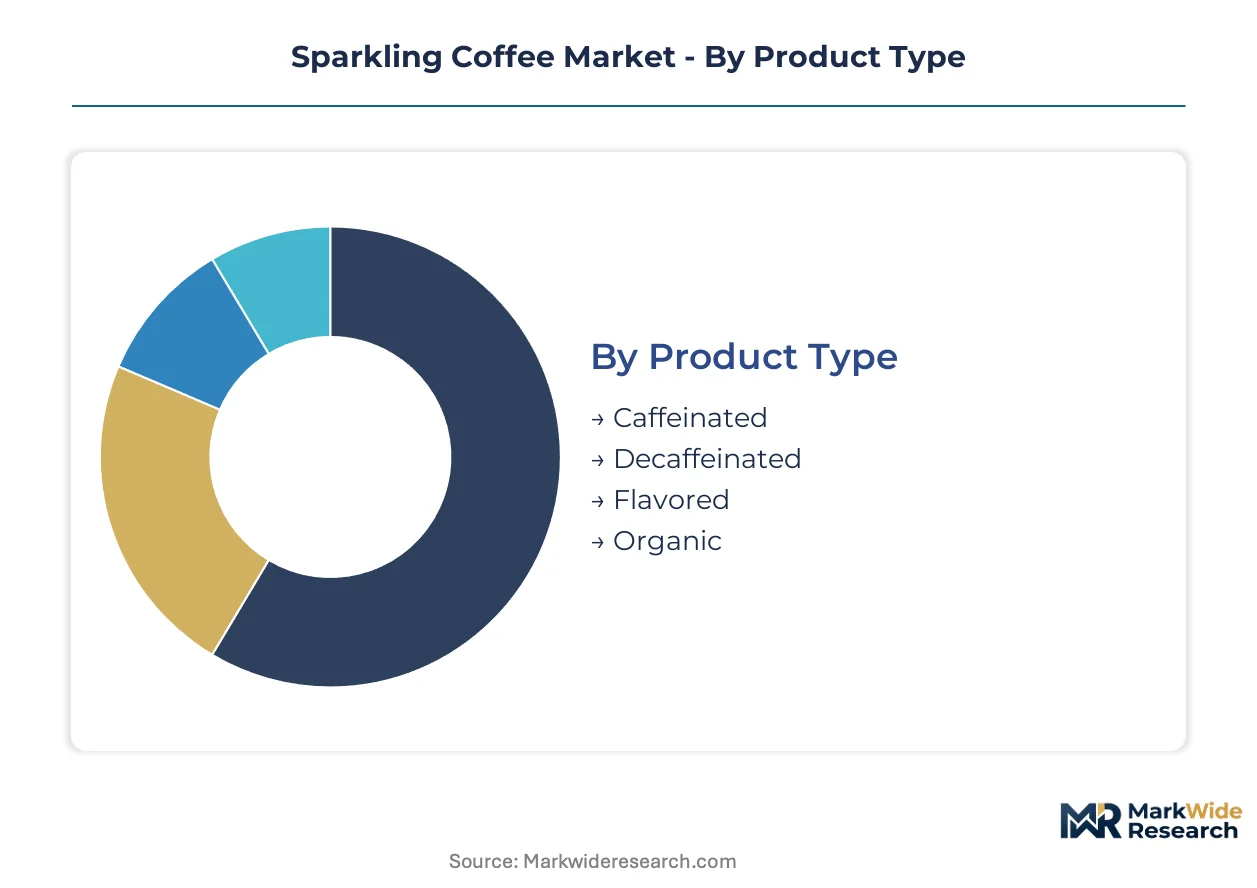
The sparkling coffee market stratifies across various dimensions, reflecting diverse consumer preferences and operational models. Understanding these segments allows market participants to tailor product development, marketing strategies, and distribution networks effectively. Strategic differentiation within these categories is crucial for capturing specific consumer niches and driving market expansion.
Product Type:
The product type segmentation highlights the various functional and experiential use-cases for sparkling coffee consumers.
- Caffeinated:This segment comprises sparkling coffee beverages formulated to deliver a stimulating energy boost. Demand concentrates among health-aware millennials in developed economies seeking natural energy sources, often replacing traditional soft drinks or energy drinks.
- Flavored:This segment includes sparkling coffee products infused with various natural or artificial flavors, enhancing the taste profile beyond traditional coffee. Consumer demand is expanding rapidly through online retail platforms, particularly in the United States and the United Kingdom, as brands innovate with unique taste combinations.
- Decaffeinated:These products offer the refreshing experience of sparkling coffee without the stimulating effects of caffeine.
- Organic:This category features sparkling coffee made from organically certified coffee beans and other ingredients.
Established volume favors Caffeinated products; emerging adoption favors Flavored variants.
End User:
Consumer type defines distinct purchasing behaviors and consumption occasions across the sparkling coffee market.
- Retail Consumers:This segment represents individuals purchasing sparkling coffee for personal consumption through various channels, primarily supermarkets and online platforms. Demand is driven by the desire for convenient, low-sugar, functional beverages as alternatives to traditional soft drinks.
- Coffee Shops:These establishments serve sparkling coffee as a premium, ready-to-drink or on-tap option, often leveraging existing coffee culture. The segment provides a crucial avenue for product sampling and brand building, particularly in urban centers like those in Germany and the United States.
- Restaurants:Food service establishments offer sparkling coffee as a non-alcoholic beverage option, complementing meal offerings.
- Beverage Distributors:These entities manage the logistics and supply chain for sparkling coffee products, connecting producers with various retail and food service outlets.
Growth centers on Retail Consumers, while Coffee Shops provide a critical platform for product legitimacy and experience.
Packaging Type:
Material choice and format significantly influence product portability, shelf life, and environmental impact within the market.
- Cans:Aluminum cans represent the dominant packaging type for sparkling coffee, favored for their portability, recyclability, and ability to protect product integrity from light and oxygen. This format is ubiquitous in supermarkets and convenience stores across the United States and European markets.
- Bottles:This segment includes glass or PET plastic bottles, often used for premium or artisanal sparkling coffee offerings that emphasize visual appeal. Bottles cater to consumers seeking a more traditional beverage experience, particularly in specialty stores and cafes.
- Tetra Packs:These multi-layered cartons offer extended shelf life and are sometimes used for ambient-stable sparkling coffee products.
- Kegs:Large format kegs enable on-tap sparkling coffee service in food service settings like cafes and corporate offices.
Cans dominate market share due to convenience and recyclability, with Kegs expanding in food service applications.
Distribution Channel:
Market access pathways determine how sparkling coffee products reach their target consumers, influencing brand visibility and sales volume.
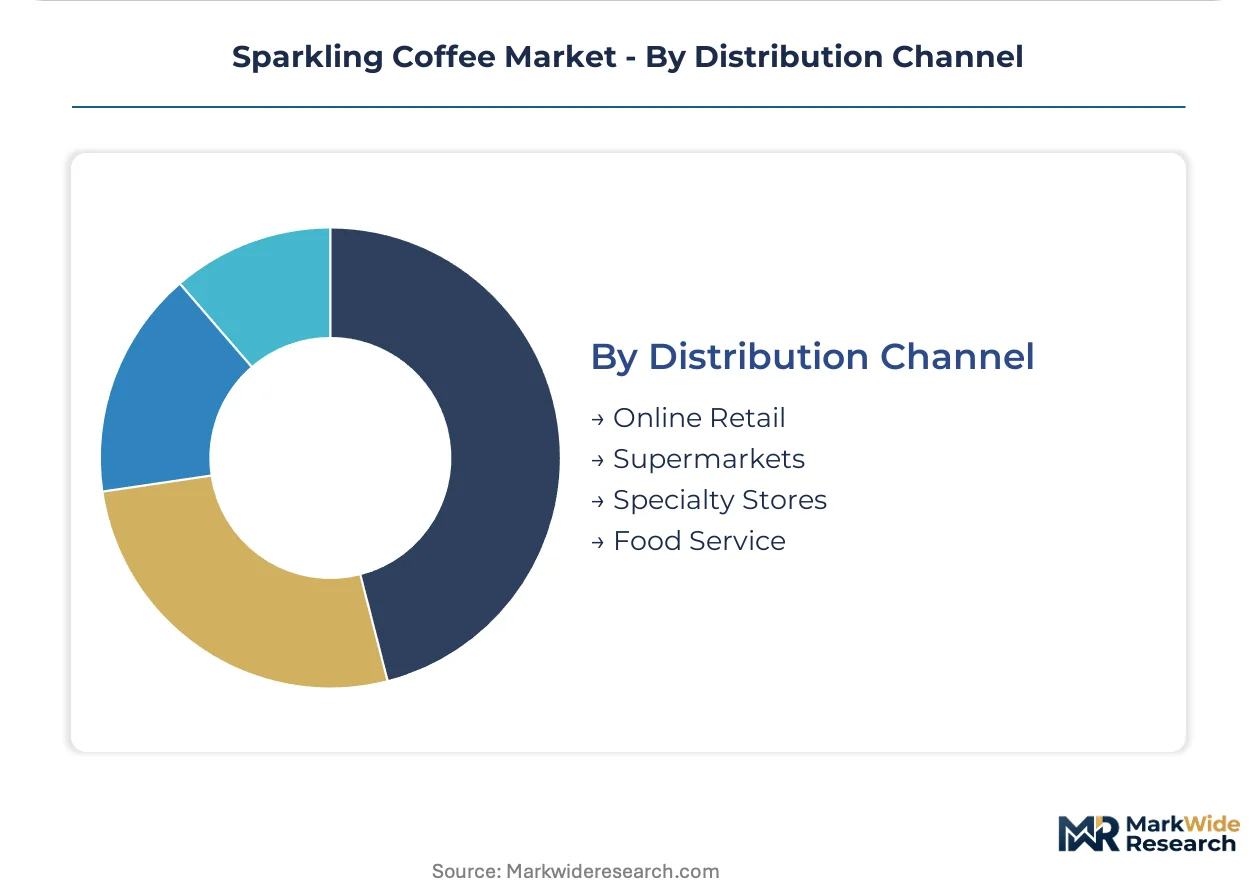
- Supermarkets:These large-format retail stores remain a core distribution channel, providing broad consumer access and visibility for established sparkling coffee brands. Supermarket placement is critical for reaching a mass market in countries like Germany and the United Kingdom.
- Online Retail:This channel includes e-commerce platforms and brand-specific direct-to-consumer (DTC) websites, facilitating convenient purchasing and subscription models. Online retail is driving rapid expansion for flavored product types and niche artisanal brands, particularly among urban consumers in the United States.
- Specialty Stores:These outlets, including gourmet food shops and health food stores, cater to consumers seeking unique or premium sparkling coffee options.
- Food Service:This channel encompasses cafes, restaurants, and corporate cafeterias that serve sparkling coffee, often as a premium non-alcoholic beverage.
The market relies heavily on Supermarkets for volume, but Online Retail offers significant expansion opportunities for niche brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sparkling coffee consumption patterns vary significantly across global markets, driven by differing consumer preferences and regulatory environments. Retail consumers in developed economies like the United States increasingly seek low-sugar, functional alternatives to traditional soft drinks. European markets show strong demand for premium, ready-to-drink options in coffee shops, while Asian markets present growth opportunities for innovative beverages.
United States
Health-conscious millennials drive demand for functional, low-sugar sparkling coffee, replacing traditional soft drinks. FDA labeling standards mandate clear nutritional information on product packaging, benefiting low-sugar options. Online retail platforms in urban centers like New York and Los Angeles see rapid expansion of flavored variants and direct-to-consumer models.
Germany
The market benefits from established coffee cultures and a preference for premium non-alcoholic beverages in cafes. EFSA regulations influence product formulation, particularly regarding approved additives and caffeine content. Coffee shops in Berlin and Munich provide critical platforms for product legitimacy and brand experience, introducing new consumers.
British
Consumers prioritize convenience and novel, artisanal brands, driving expansion through online retail channels. Front-of-pack labeling initiatives align with EU transparency requirements, highlighting low-sugar benefits as a key differentiator. Urban consumers in London and Manchester actively engage with direct-to-consumer subscription services for unique product discovery.
Japan
Significant opportunities exist in this market, leveraging its sophisticated coffee culture and high demand for innovative, ready-to-drink beverages. METI encourages food innovation and new product development within the beverage sector, supporting new product launches. Major cities like Tokyo and Osaka are promising targets for market entry and product testing among discerning consumers.
India
FSSAI regulations control caffeine content and additive use, directly influencing product formulation and ingredient choices. Consumers in metropolitan areas like Mumbai and Bangalore are exploring new beverage categories beyond traditional options. The demand for functional beverages is gradually increasing, driven by rising health awareness and disposable incomes.
Sparkling Coffee Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the sparkling coffee market. The market structure exhibits a tiered competitive landscape, with established coffee brands alongside specialized artisanal producers and large beverage conglomerates. Three strategic archetypes emerge: traditional coffee roasters extending into RTD, multinational beverage companies, and niche craft beverage companies. Competitive moves include portfolio diversification into functional beverages, strategic partnerships for enhanced distribution, and targeted geographic expansion into underpenetrated markets.
On the established brand equity vector, Stumptown Coffee Roasters exemplifies traditional coffee roasters leveraging their reputation for specialty coffee. This company extends its well-recognized brand into the ready-to-drink sparkling coffee segment, targeting consumers familiar with premium coffee experiences. In contrast, Paulig operates with significant scale, anchoring a strong presence within European production and distribution networks, enabling broad market reach. Slingshot Coffee Co. represents the artisanal segment, specializing in unique flavor profiles and craft production methods. This niche player targets a discerning consumer base seeking innovative and high-quality sparkling coffee experiences, often through direct-to-consumer channels.
| Leading Market Players |
|---|
| Slingshot Coffee Co. |
| Union Coffee |
| DrinkVIVIC |
| Nongfu Spring |
| Upruit |
| MATCHLESS COFFEE SODA |
| Paulig |
| Stumptown Coffee Roasters |
| Keepers Sparkling Coffee |
| Others |
Cost & Logistics Intelligence
Brazil's dominant coffee bean production capacity significantly influences global raw material pricing, which in turn impacts the final cost structure of sparkling coffee products.
Pricing Analysis
Long-term offtake agreements for green coffee beans stabilize input costs for large-scale sparkling coffee producers. Price differentiation stems from brand premium, artisanal production quality, and specialized flavor profiles. Pricing pressure is generally upward due to volatile coffee bean prices and higher cold brew processing costs. Retail consumers seeking functional beverages demonstrate moderate price sensitivity, while niche consumers for unique artisanal blends exhibit lower sensitivity and accept premium pricing.
Supply Chain Analysis
Coffee bean price volatility, driven by climate change and geopolitical instability in Brazil and Vietnam, represents a significant supply chain risk for sparkling coffee producers. The market depends on a consistent supply of high-quality coffee beans, carbonation gases, and aluminum cans. Distribution runs through a dual model, with supermarkets handling mass volume and online retail platforms expanding reach for specialty products. Scaling production while maintaining artisanal quality presents an operational challenge.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sparkling coffee market is at a platform-economics inflection point, as direct-to-consumer online retail platforms reshape traditional distribution ecosystems. This shift enables niche brands to directly engage consumers and build recurring revenue streams.
For Market Incumbents: Entrench existing market share by leveraging established brand equity and optimizing large-scale European distribution networks. Incumbents must invest in advanced cold brew extraction technologies to counter emerging artisanal competitors. Diversifying into adjacent functional beverage categories offers a strategic defense against evolving consumer preferences. Controlling supermarket shelf space remains critical for volume protection.
For New Entrants and Emerging Players: Build out niche market positions through innovative flavor development and artisanal production methods. The most penetrable segment lies with urban consumers in the United States and United Kingdom, accessible via direct-to-consumer channels. Targeting functional ingredient infusion, such as adaptogens, offers a distinct go-to-market angle. Strategic food service partnerships can also introduce novel on-tap sparkling coffee experiences.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cold brew and nitrogen infusion firms with scalable production capabilities. The long-term viability of the sparkling coffee market is strong, driven by sustained functional beverage demand. Acquisition targets include artisanal brands with unique flavor profiles and robust direct-to-consumer subscriber bases. The signal to watch is the rapid expansion of on-tap sparkling coffee in corporate offices and cafes.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Broadens appeal beyond traditional coffee consumers seeking new beverage options. |
| Direct-to-Consumer Expansion | Establishes direct customer relationships and secures recurring revenue streams. |
| Advanced Cold Brew Investment | Enhances product quality and reduces acidity for a smoother taste profile. |
| Geographic Market Entry | Captures demand in underpenetrated Asian markets like Japan and South Korea. |
| Functional Ingredient Integration | Targets wellness-focused consumers seeking specific health benefits beyond caffeine. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with industry stakeholders. This included brand managers, specialized coffee roasters, retail buyers, and food service managers. Secondary validation drew from FDA filings, EFSA reports, FSSAI regulations, and relevant trade association publications. The analysis employed bottom-up and top-down triangulation to ensure data accuracy.
The forecast calibration approach integrated historical data with projected market drivers across the analysis window. Segmentation dimensions modeled included product type, end user, packaging type, distribution channel, and regional regulatory frameworks. Compound Annual Growth Rates were derived from an assessment of these drivers and their anticipated impact. Industry-specific inputs included coffee bean price projections and consumer health-consciousness indices.
Sensitivities concentrate around coffee bean supply shocks and evolving food safety regulations. Forecasts reflect assumptions regarding consumer health trends and market adoption rates across various geographies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Fruit Extract Market
Coffee
Global Nespresso Capsules Market
Coffee
Australia Coffee Market
Coffee
Cold Brew Coffee Market
Coffee
US Coffee Roaster Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Reusable Coffee Cup Market
Coffee
Specialty Coffee Market
Coffee
US Coffee Machine Market
Coffee
North America Specialty Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Coffee Bags Market
Coffee
Brazil Ready-To-Drink (RTD) Coffee Market
Coffee
Raw Coffee Beans Market
Coffee
Portable Espresso Machines Market
Coffee
Office Coffee Service (OCS) Market