
 Infused Fruits Jellies Market | 2026-2036
Infused Fruits Jellies Market Size, Share, and Industry Trends Forecast 2026-2036
Infused Fruits Jellies Market Analysis
Asset-light co-manufacturing partnerships are reshaping competitive entry in infused fruit jellies, allowing regional brands to scale without capital-intensive production facilities. The Hershey Company leverages its established North American distribution infrastructure to secure shelf placement across mainstream retail channels. HARIBO GmbH & Co. KG anchors its position through proprietary starch molding expertise adapted for fruit-infused formulations. Ferrara Candy Company specializes in seasonal and gift-oriented packaging configurations that command premium price points in specialty retail.
Infused fruits jellies comprise fruit-derived gelling systems—typically pectin or carrageenan matrices—suspended with concentrated fruit essences, natural colorants, and controlled moisture content between 15-25 percent, produced via vacuum cooking to preserve volatile aromatic compounds for bakery, confectionery, and foodservice applications. The organic product type segment sustains the fastest expansion as consumers trade up from conventional formulations, while the sugar-free category occupies a narrower but higher-margin niche driven by diabetic and ketogenic dietary protocols. Glass jar packaging dominates premium positioning in specialty stores and farmers' markets, whereas pouch formats are accelerating in online retail channels where shipping weight and breakage risk determine fulfillment economics.
FDA oversight of food additive petitions and GRAS self-affirmation processes shapes ingredient innovation timelines for US-facing suppliers, while EFSA's evolving guidance on novel food classifications creates compliance complexity for botanical and exotic fruit infusions entering European markets. The EU Green Deal's packaging waste directives are forcing transitions from single-use plastic containers toward recyclable or refillable alternatives, with France's AGEC law accelerating this shift through extended producer responsibility mandates. Stakeholders must monitor divergence between US and European clean-label standards, as regulatory asymmetry threatens to fragment product development roadmaps and duplicate certification costs across Atlantic supply chains.
Market Dynamics
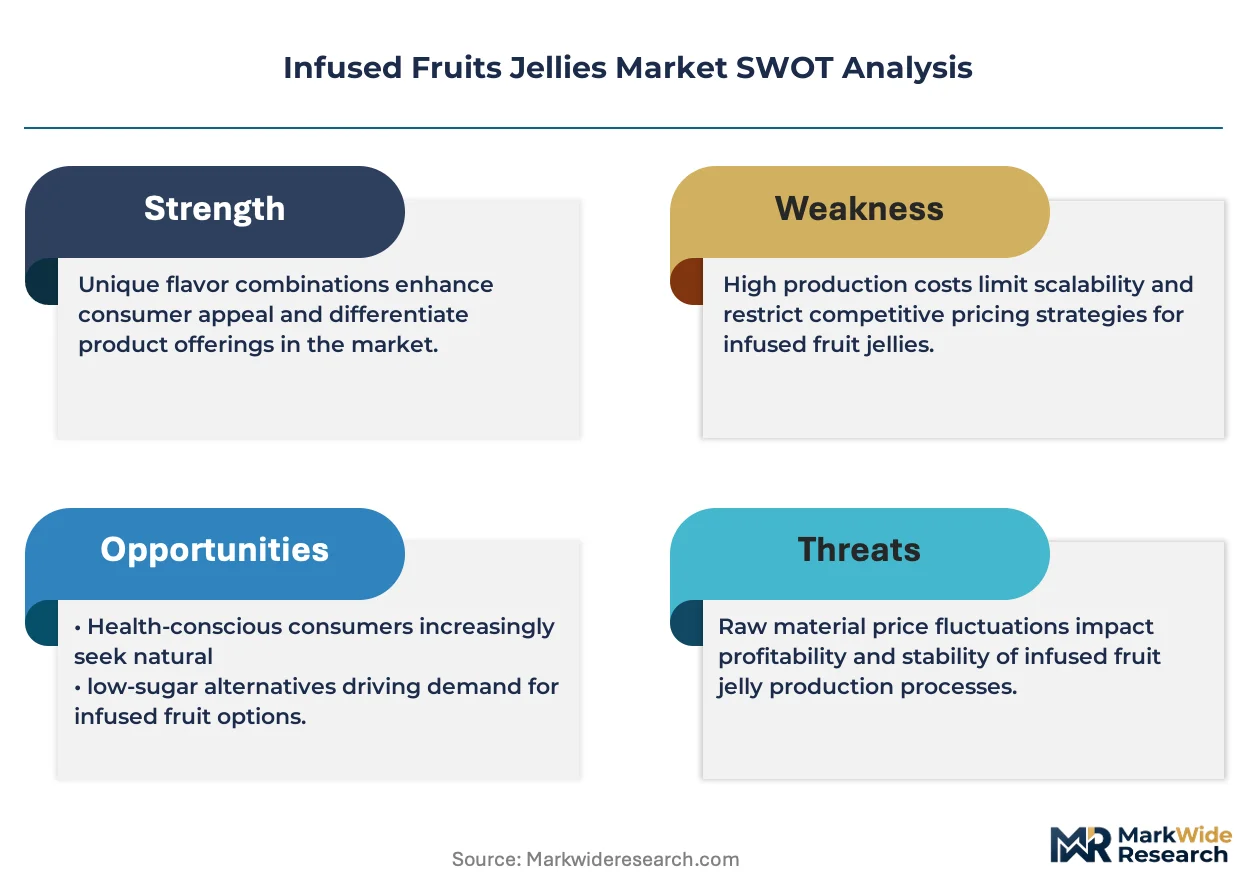
Clean-label formulation mandates from FDA and EFSA are forcing manufacturers to strip synthetic additives from pectin-based gelling systems, compressing R&D timelines and elevating natural ingredient sourcing costs across supply chains. This regulatory compression is reshaping competitive entry barriers and procurement patterns simultaneously.
Growth Catalysts
- EFSA Novel Food Classifications:Streamlined approval pathways for exotic fruit infusions accelerate European market entry for botanical-forward formulations.
- Foodservice Premiumization:Boutique hotels and artisanal bakeries in France anchor signature menu procurement, creating pull-through demand for small-batch producers.
- Vacuum Cooking Technology:Preservation of volatile aromatic compounds enables cleaner-label products without synthetic flavor masking agents.
Market Restraints
- Pectin Supply Concentration:Citrus peel and apple pomace sourcing clusters in Spain and Italy create input cost volatility during harvest disruptions.
- EU Green Deal Packaging Directives:Mandatory transitions from single-use plastics force capital-intensive retooling for jar and pouch manufacturers.
- Clean-Label Cost Premium:Natural colorant and stabilizer substitutions add 15-30% to raw material baskets versus synthetic alternatives.
Strategic Opportunities
- France's AGEC Law:Extended producer responsibility mandates create first-mover advantage for refillable glass systems in premium channels.
- Ketogenic Dietary Protocols:Sugar-free formulations using allulose and monk fruit open margin-rich positioning in diabetic and low-carb consumer segments.
- Online Retail Pouch Formats:Lightweight, breakage-resistant packaging aligns with direct-to-consumer fulfillment economics and subscription model growth.
Industry Challenges
- GRAS Self-Affirmation Timelines:FDA food additive petition processes delay ingredient innovation launches by 18-24 months for US-facing suppliers.
- Flavor Chemist Talent Scarcity:Formulation expertise bridging natural fruit chemistry and industrial gelling science commands premium compensation in competitive labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infused Fruits Jellies Market |
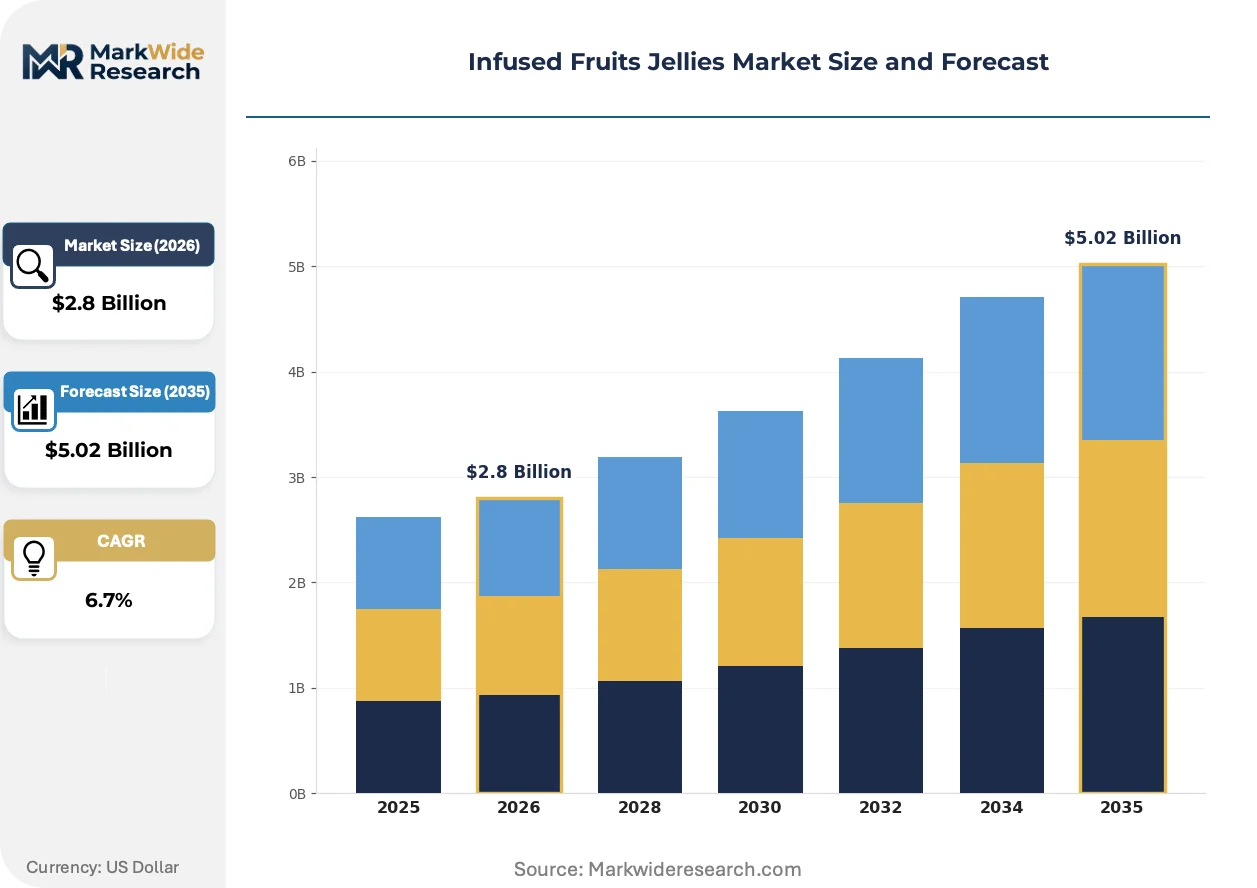
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Sugar-Free, Low-Calorie Flavor Profile: Strawberry, Raspberry, Mango, Mixed Berry Packaging Type: Glass Jar, Plastic Container, Squeeze Bottle, Pouch Sales Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets |
| Companies Covered | The Hershey Company, Ferrara Candy Company, HARIBO GmbH & Co. KG, Jelly Belly Candy Company, Perfetti Van Melle, Mars, Incorporated, Cloetta, Impact Confections, Just Born, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infused Fruits Jellies Market Emerging Trajectories
Formulation science and packaging engineering are converging to address the tension between shelf stability demands and clean-label ingredient decks. Three distinct vectors are compressing traditional production paradigms.
Low-temperature vacuum infusion technology is collapsing the traditional trade-off between thermal pasteurization intensity and volatile flavor retention. Artisanal producers in Provence and the Rhône Valley are adopting these systems to preserve terroir-specific aromatic signatures in PDO fruit varieties. The compression of flavor loss rates is enabling single-origin positioning previously impossible at commercial scale.
France's AGEC anti-waste law is accelerating packaging format experimentation through extended producer responsibility thresholds. Manufacturers must now internalize end-of-life costs for containers, driving rapid adoption of refillable glass deposit systems and aluminum tube alternatives. Premium specialty retail channels in Paris and Lyon are piloting returnable jar programs that shift compliance burden upstream to producers.
Boutique hospitality procurement teams are consolidating supplier relationships around co-manufacturing partnerships that eliminate captive production assets. Foodservice operators in coastal Mediterranean markets now specify custom flavor profiles without vertical integration into jelly manufacturing. This disintermediation of production capacity is concentrating margin capture with brand owners while fragmenting manufacturing across regional toll producers.
Infused Fruits Jellies Market Segmentation
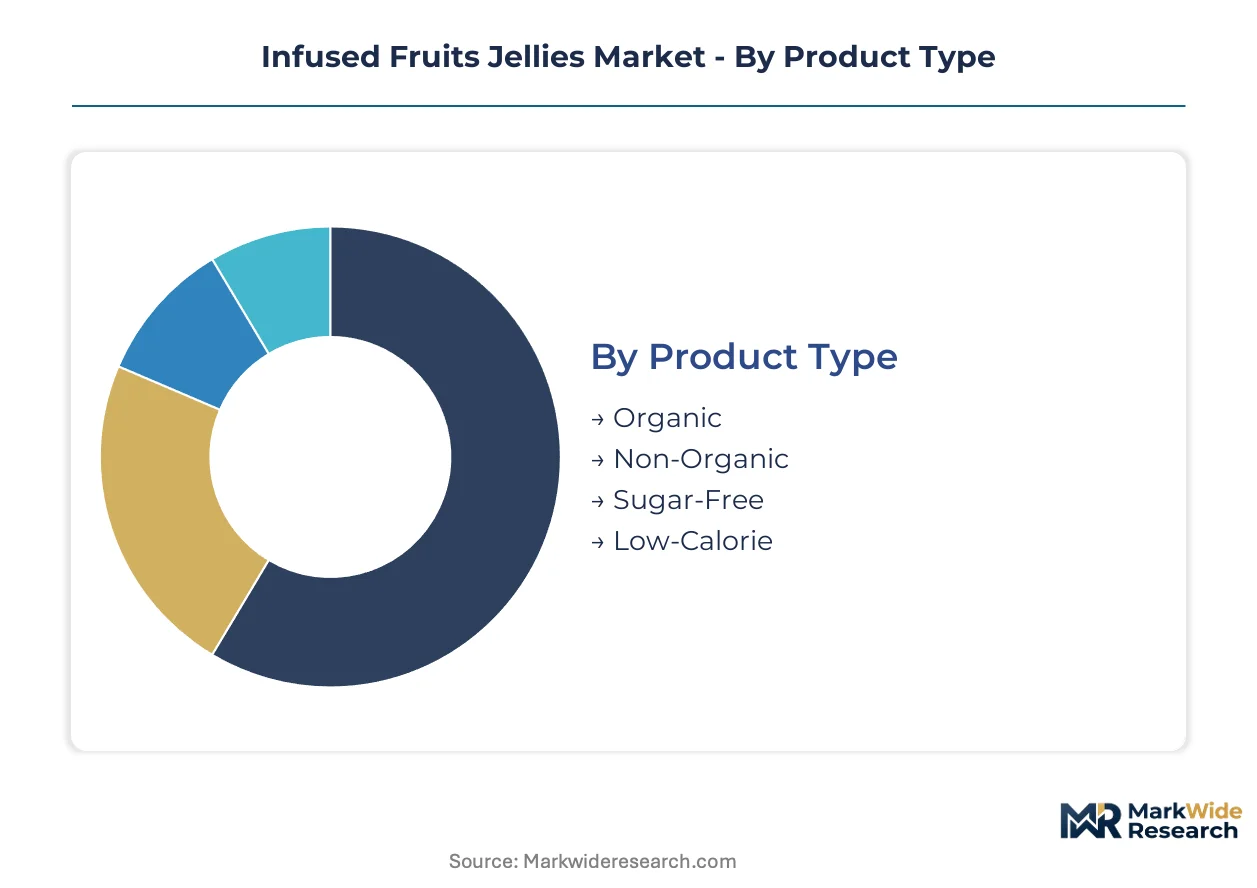
Segmentation in infused fruits jellies separates procurement velocity from margin architecture. Product type determines regulatory compliance burden, while packaging format dictates channel economics and breakage risk in fulfillment.
Product Type:
Cycle times vary sharply across this category, with organic formulations requiring extended certification audits and sugar-free variants iterating faster on sweetener blends.
- Organic:Certified fruit sourcing and pectin extraction from organic citrus peel constrain batch throughput. Demand clusters in French PDO fruit conservatories where terroir positioning commands shelf placement premiums in specialty retail.
- Sugar-Free:Allulose and monk fruit formulations target ketogenic and diabetic dietary protocols with higher margin capture. Procurement is accelerating through direct-to-consumer subscription channels where repeat purchase rates exceed conventional formats.
- Non-Organic:Conventional fruit concentrates and standard pectin gelling systems dominate foodservice bulk procurement.
- Low-Calorie:Reduced-sugar formulations using alternative sweeteners occupy mid-tier positioning between conventional and sugar-free tiers.
Non-Organic anchors the volume base while Sugar-Free gains share at the steepest rate.
Flavor Profile:
Cost tiers separate commodity fruit purees from single-origin essences, with regional harvest timing creating input price volatility.
- Strawberry:The most standardized flavor profile with established year-round concentrate supply. Demand concentrates in mass-market retail channels where familiar taste profiles minimize trial risk for mainstream consumers.
- Mango:Exotic fruit infusions face EFSA novel food classification complexity for European entry. Procurement is expanding in boutique hospitality applications where signature menu differentiation justifies premium positioning.
- Raspberry:Volatile aromatic compounds require vacuum cooking precision to preserve flavor integrity.
- Mixed Berry:Blended profiles offer sourcing flexibility during individual fruit harvest disruptions.
Strawberry maintains volume leadership while Mango climbs the fastest on premiumization tailwinds.
Packaging Type:
Customer type determines format selection, with gift purchasers favoring visual presentation and subscription buyers prioritizing shipping durability.
- Glass Jar:Premium positioning vehicle for farmers' markets and specialty stores. France's AGEC law mandates extended producer responsibility, driving refillable deposit system pilots in Paris and Lyon retail channels.
- Pouch:Lightweight, breakage-resistant format aligns with online retail fulfillment economics. Demand is accelerating in direct-to-consumer channels where shipping weight directly impacts unit economics.
- Plastic Container:EU Green Deal packaging waste directives are forcing transition toward recyclable alternatives.
- Squeeze Bottle:Foodservice portion-control applications favor this format for back-of-house efficiency.
Glass Jar dominates premium channel revenue while Pouch expands most quickly in digital commerce.
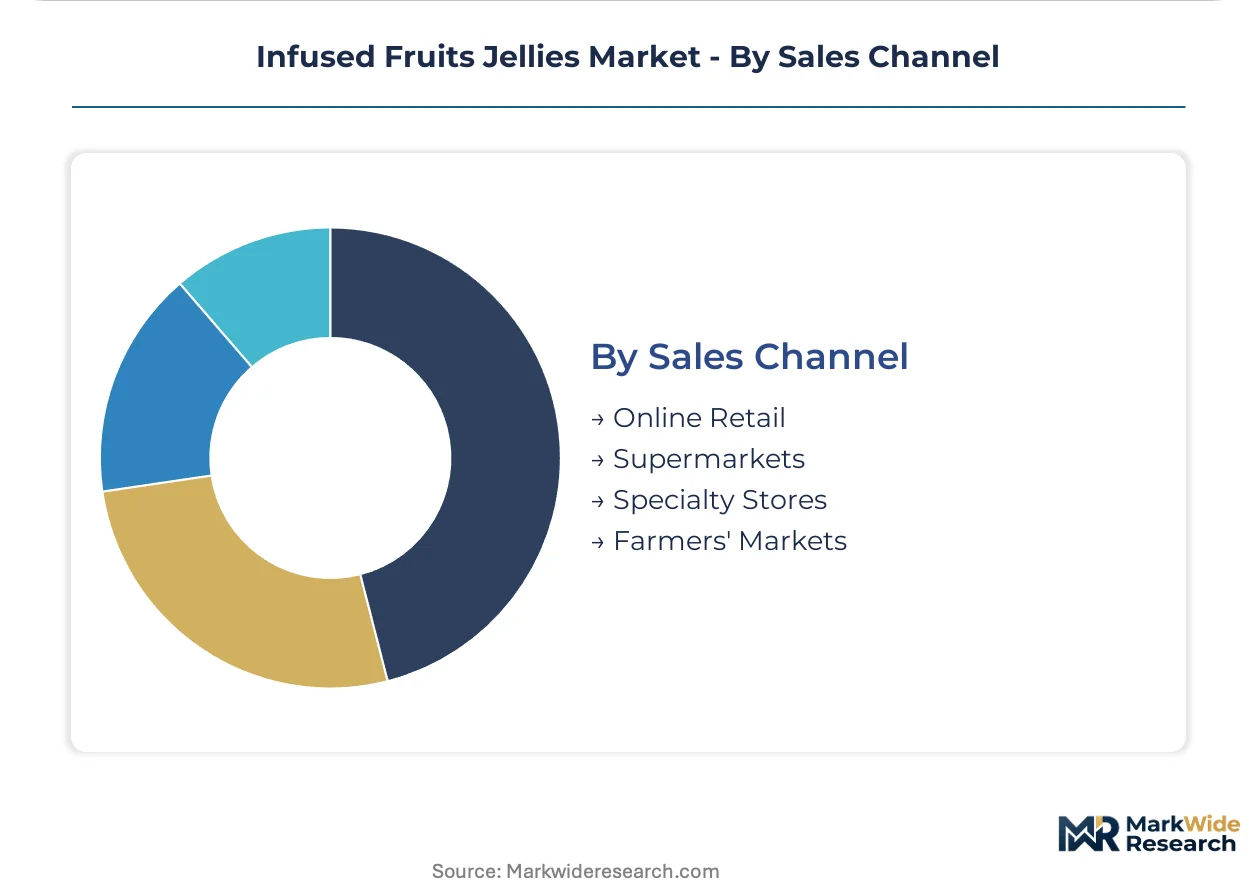
Sales Channel:
Supply concentration varies by channel, with supermarket placement requiring national distribution infrastructure and farmers' markets rewarding hyper-local production.
- Specialty Stores:Curated assortments and staff education support premium positioning for artisanal producers. Demand concentrates in French urban centers where regional fruit conservatories supply protected designation of origin varieties.
- Online Retail:Subscription model growth and pouch format compatibility reshape fulfillment economics. Procurement is shifting toward direct-to-consumer brands that bypass traditional wholesale markups.
- Supermarkets:Mainstream retail placement demands scale and slotting fee capacity.
- Farmers' Markets:Hyper-local production and seasonal harvest alignment characterize this channel.
Supermarkets anchor volume throughput while Online Retail captures the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in infused fruit jellies tilt toward surplus positions in European fruit conservatory zones while Asian manufacturing hubs absorb concentrate imports for re-export. France and Italy anchor net export positions through protected designation origin fruit varieties. The United States runs a modest trade deficit in premium artisanal formats.
France
Boutique hospitality procurement and artisanal bakery demand concentrate in Paris and Lyon retail corridors. The AGEC anti-waste law mandates extended producer responsibility for packaging, accelerating refillable glass deposit systems. Provence-Alpes-Côte d'Azur fruit conservatories supply protected designation of origin varieties to specialty channels.
Italy
Citrus peel and apple pomace pectin sourcing clusters anchor gelling system supply for European manufacturers. EFSA novel food classifications create compliance pathways for botanical infusions entering continental markets. Emilia-Romagna processing facilities specialize in vacuum cooking equipment for volatile aromatic preservation.
United States
Mainstream retail shelf placement and foodservice bulk procurement drive volume demand through national distribution networks. FDA GRAS self-affirmation processes shape ingredient innovation timelines for domestic suppliers. California fruit concentrate processors supply input materials to co-manufacturing partners across the Southwest.
Germany
Confectionery technology expertise and starch molding capabilities support private-label production for European retailers. EU Green Deal packaging waste directives force transitions from single-use plastics toward recyclable alternatives. Bavarian equipment manufacturers supply vacuum cooking systems to artisanal producers throughout the Alpine region.
Japan
Premium gift-oriented packaging configurations command price premiums in seasonal retail channels. METI standards for food additive labeling create transparent ingredient declaration requirements. Tokyo and Osaka metropolitan areas concentrate specialty retail demand for exotic fruit infusion varieties.
Infused Fruits Jellies Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in gelling matrices and flavor extraction. The vendor base organizes around three structural tiers: multinational confectionery houses with captive distribution, regional artisanal brands leveraging co-manufacturing partnerships, and private-label suppliers serving retail chains. Dominant competitive moves include portfolio diversification into clean-label formats and geographic expansion through asset-light licensing arrangements.
Among North American confectionery houses, The Hershey Company and Ferrara Candy Company exemplify platform integration strategies. The Hershey Company's established distribution infrastructure secures mainstream retail shelf placement across continental networks. Ferrara Candy Company occupies a position within seasonal and gift-oriented packaging segments. HARIBO GmbH & Co. KG anchors the European specialist tier through proprietary manufacturing expertise adapted for fruit-infused formulations.
| Leading Market Players |
|---|
| The Hershey Company |
| Ferrara Candy Company |
| HARIBO GmbH & Co. KG |
| Jelly Belly Candy Company |
| Perfetti Van Melle |
| Mars, Incorporated |
| Cloetta |
| Impact Confections |
| Just Born |
| Others |
Supply Flow & Price Mechanics
Provence-Alpes-Côte d'Azur fruit conservatories anchor premium raw material sourcing, concentrating terroir-specific aromatic inputs that translate into pricing power for PDO-certified producers. Vacuum cooking equipment clusters in Emilia-Romagna and Bavaria create downstream capacity bottlenecks that reshape procurement premiums across European supply chains.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade and volume scale, with organic PDO varieties commanding shelf placement premiums while conventional concentrates face cost compression from synthetic additive substitution mandates. Pricing pressure stems from clean-label reformulation costs, with natural colorant substitutions adding 15-30 percent to raw material baskets. Foodservice bulk procurement teams exhibit highest price sensitivity, whereas boutique hospitality operators in Paris and Lyon demonstrate lowest sensitivity due to menu differentiation requirements.
Supply Chain Analysis
Co-manufacturing partnerships concentrate production capacity across France, Italy, and Germany, with regional toll producers absorbing asset-light brand expansion. Pectin extraction draws from citrus peel clusters in Spain and apple pomace processing in Italy, creating input dependencies on Mediterranean harvest timing. Single-source vulnerability in exotic fruit concentrate supply threatens formulation continuity for mango and passion fruit infusions. Distribution runs through national retail networks for mainstream placement, while direct-to-consumer channels bypass wholesale markups via subscription pouch fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infused fruits jellies market sits in a cyclical recovery phase as post-pandemic foodservice premiumization and clean-label regulatory mandates converge to reset procurement baselines.
For Market Incumbents: Build formulation moats around proprietary vacuum cooking protocols for volatile aromatic preservation. Deepen backward integration into organic citrus peel sourcing in Spain to secure pectin supply against harvest disruption. Expand refillable glass deposit systems in French premium channels ahead of AGEC law enforcement timelines. For New Entrants and Emerging Players: Establish a beachhead in sugar-free ketogenic formulations where allulose and monk fruit sweeteners command margin-rich positioning. Target direct-to-consumer subscription channels with lightweight pouch formats that minimize shipping breakage risk. Leverage co-manufacturing partnerships in Emilia-Romagna to bypass capital-intensive production assets. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because asset-light brand owners are capturing margin while fragmenting manufacturing across regional toll producers. Acquisition targets should profile regional artisanal brands with established PDO fruit conservatory relationships and proven co-manufacturing frameworks. Monitor EFSA novel food classification timelines for exotic fruit infusions as inflection indicator for European market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Natural pectin and colorant substitutions satisfy FDA and EFSA additive restrictions without synthetic masking agents. |
| Refillable Glass Deposit System Launch | France's AGEC extended producer responsibility mandates create first-mover compliance advantage in Paris and Lyon retail. |
| Co-Manufacturing Partnership Expansion | Regional toll producers in Emilia-Romagna enable brand scaling without captive production facility capital deployment. |
| Sugar-Free Ketogenic Line Extension | Allulose and monk fruit formulations capture diabetic and low-carb dietary protocol demand through subscription channels. |
| Online Retail Pouch Format Rollout | Lightweight breakage-resistant packaging aligns with direct-to-consumer fulfillment economics and shipping weight optimization. |
Methodological Framework
Initial hypotheses were tested against primary input from brand managers at confectionery houses, category buyers at specialty retailers, foodservice procurement directors at boutique hotel chains, and supply planners at co-manufacturing facilities, then refined against secondary validation from FDA GRAS filings, EFSA novel food registers, EU Green Deal packaging directives, and customs trade data for fruit concentrate imports. Bottom-up volume estimates from segment-level procurement patterns were triangulated with top-down market sizing from production capacity assessments.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, packaging format, sales channel, and regional regulatory cluster. CAGRs were derived from weighted average growth contributions across organic, sugar-free, and conventional formulation tiers, with vacuum cooking technology adoption curves and clean-label reformulation compliance timelines serving as key forecast inputs.
Stress conditions across pectin supply disruption, EFSA novel food approval delays, and EU packaging waste directive enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about foodservice recovery velocity and consumer willingness-to-pay premiums for PDO-certified varieties. Quarterly review of harvest yield reports from Spanish citrus regions and EFSA classification queue progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia Pacific Chocolate Market
Confectionery
Brazil Chocolate Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Europe Confectionery Market
Confectionery
Sugar Free Candy Market
Confectionery
UK Chocolate Market
Confectionery
North America Compound Chocolate Market
Confectionery
Chocolate Confectionery Market
Confectionery
Dark Chocolate Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Green Tea Chocolate Market
Confectionery
Gummy Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Low Calorie Treats Market