
 Coffee Bags Market | 2026-2036
Coffee Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Bags Market Outlook
Premium barrier-grade specifications is redrawing competitive boundaries in coffee bag supply. Amcor plc leverages multi-layer laminate expertise to anchor North American specialty roaster contracts. Mondi PLC sustains European market presence through kraft-paper innovation and integrated pulp supply. MTPak Coffee Limited specializes in small-batch digitally printed pouches, competing for craft roaster loyalty across Asia-Pacific.
Coffee bags are multi-layer flexible containers engineered with oxygen transmission rates below 0.1 cc per square meter per day, typically combining polyethylene terephthalate, aluminum foil, and linear low-density polyethylene to preserve volatile aromatic compounds during twelve-month shelf lives. Stand-up pouches occupy the fastest-growing structural position as roasters prioritize shelf visibility and reduced freight cube; valve bags dominate volume among large-scale distributors requiring degassing functionality post-roast. Biodegradable material formulations attract R&D allocation despite current cost premiums, while plastic laminates retain margin concentration due to established converter infrastructure and print fidelity.
The EU PPWR and FDA food-contact substance regulations jointly shape material migration limits and recyclability mandates, forcing converters to validate alternative barrier chemistries. REACH compliance in Europe and state-level extended producer responsibility laws in California impose incremental testing burdens that favor mid-cap suppliers with dedicated regulatory teams. Stakeholders must monitor polymer substitution timelines and regional collection infrastructure maturity to calibrate capital deployment between conventional and next-generation barrier platforms.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to revalidate barrier chemistries ahead of 2030 recyclability mandates, compressing R&D timelines while specialty roasters demand shorter run lengths and faster turnaround.
Growth Catalysts
- Specialty Roaster Procurement:Premium single-origin offerings are capturing shelf space across retail channels, driving demand for valve-equipped and digitally printed pouches with 12-month oxygen barrier guarantees.
- REACH Compliance Infrastructure:Mid-cap suppliers with dedicated regulatory teams are securing European contracts as migration testing requirements intensify for aluminum-foil laminates.
- Stand-Up Pouch Adoption:Roasters in Germany, Italy, and the United States are prioritizing shelf visibility and reduced freight cube, accelerating format conversion from flat-bottom bags.
Market Restraints
- Aluminum Price Volatility:Multi-layer laminates depend on foil supply concentrated in Chinese smelters, exposing converters to input cost swings that squeeze margin on fixed-price annual contracts.
- Biodegradable Cost Premium:PLA and cellulose-based barrier films currently trade at 2-3x conventional polyethylene equivalents, limiting adoption beyond niche organic certification tiers.
- California EPR Burden:State-level extended producer responsibility laws impose incremental testing and reporting obligations that favor larger converters with compliance scale.
Strategic Opportunities
- Digital Print Convergence:HP Indigo and Xeikon press installations are enabling 500-unit minimum runs with 48-hour turnaround, unlocking micro-lot roaster segments previously served by generic stock bags.
- Compostable Channel Expansion:Certified home-compostable structures are penetrating Nordic retail chains ahead of EU single-use plastic directives, creating first-mover positioning for validated converters.
- Direct-to-Consumer Subscription:E-commerce coffee clubs in the United States and United Kingdom are specifying mailer-compatible pouch dimensions and tear-notch configurations absent from traditional wholesale specs.
Industry Challenges
- Barrier Chemist Scarcity:Formulation expertise spanning polymer science, migration modeling, and heat-seal rheology is concentrated among retiring specialists at legacy European converters.
- Validation Timeline Compression:Shelf-life testing protocols requiring six-month accelerated aging studies cannot keep pace with customer demands for 30-day sample turnaround on new laminate structures.
- Legacy Equipment Integration:Retrofitting gravure presses for water-based inks demands capital outlays that conflict with 5-year depreciation schedules at family-owned Midwest converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Bags Market |
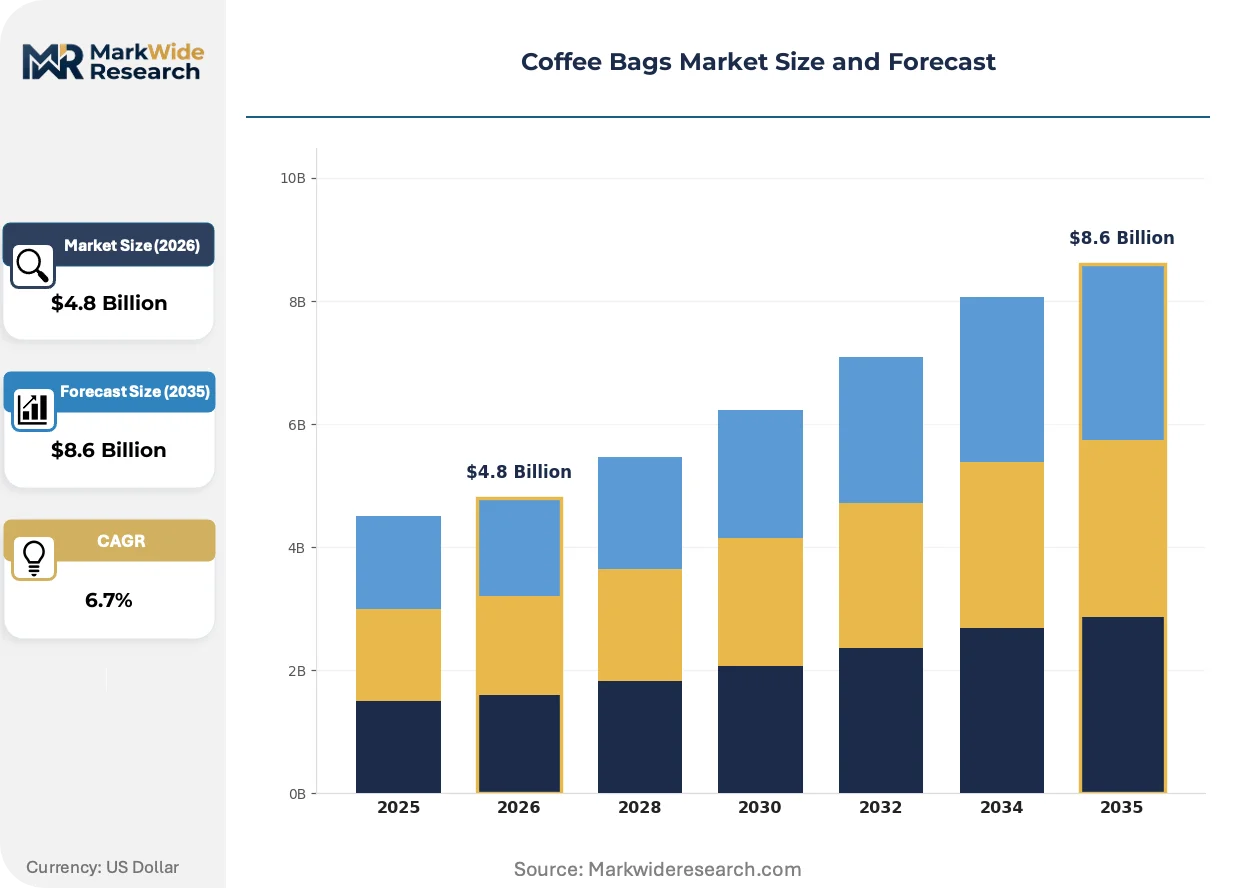
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flat Bags, Stand-Up Pouches, Valve Bags, Zipper Bags Material: Plastic, Paper, Biodegradable, Aluminum Closure Type: Zip Lock, Heat Seal, Tie, Clip End User: Retailers, Distributors, Roasters, Consumers |
| Companies Covered | Mondi PLC, American Plastics Company, Swiss Pac USA, Polysmarts Packaging, PBFY Packaging, CarePac Company, A-Pac Manufacturing Co., Inc., MTPak Coffee Limited, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Bags Market Strategic Shifts
Active barrier technologies and regulatory material bans are compressing development cycles while roasters experiment with format geometries and surface finishes previously reserved for premium snack categories.
High-barrier metallized polyethylene terephthalate is displacing aluminum foil in mid-tier roast applications where 6-month shelf life suffices. German and Italian specialty roasters are specifying this substrate for single-origin lines requiring matte visual texture. The technology is miniaturizing the addressable market for full-foil structures to ultra-premium reserve tiers and export shipments exceeding 9-month distribution cycles.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling converters to eliminate fluoropolymer grease barriers from kraft-paper laminates by 2025. Migration testing protocols at ECHA-accredited laboratories have expanded from 4 to 14 analytes, extending validation timelines. Nordic retail chains are responding fastest, demanding PFAS-free certifications ahead of legal deadlines to secure shelf positioning.
Roaster procurement departments are consolidating supplier panels from 12-15 converters to 3-4 strategic partners capable of managing regulatory documentation, digital asset libraries, and inventory programs simultaneously. This consolidation is displacing the spot-buy model that dominated 2015-2020 procurement. The shift is most visible among United States-based regional roasting groups with 5-15 million annual bag volumes seeking operational simplification.
Coffee Bags Market Segmentation
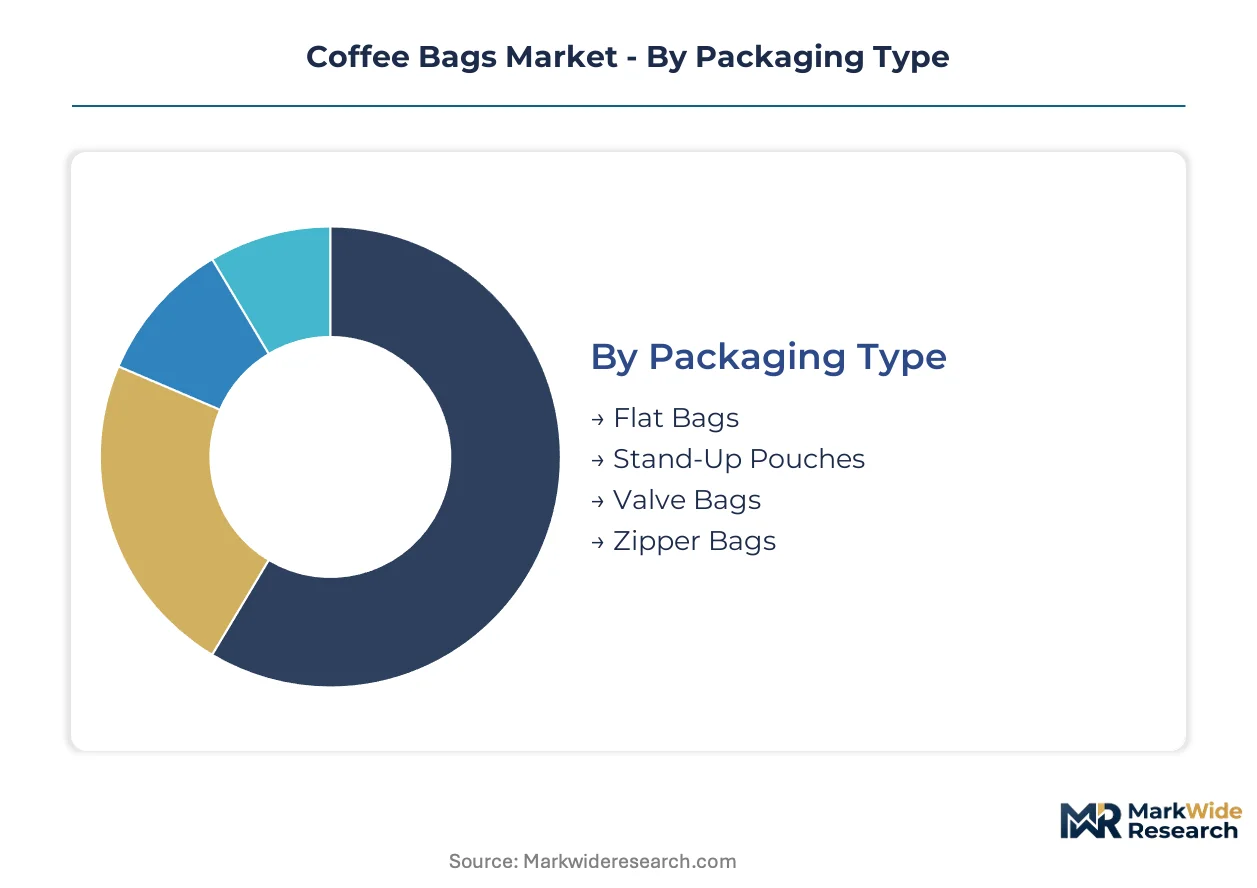
Coffee bag segmentation maps directly to shelf-life requirements, roast-to-retail timelines, and regulatory pressure points across the value chain. Material and format choices determine oxygen barrier performance, degassing functionality, and compliance posture under tightening packaging waste rules.
Packaging Type:
Margin pools concentrate in formats combining barrier performance with retail differentiation and freight efficiency.
- Valve Bags:One-way degassing valves release carbon dioxide from freshly roasted beans while blocking oxygen ingress. Large-scale distributors in Germany and the United States specify these for 12-month shelf-life guarantees on multi-origin blends. Roasters with 5-15 million annual bag volumes treat valve bags as the default procurement specification.
- Stand-Up Pouches:Gusseted bottom structures maximize shelf visibility and reduce freight cube by 30-40% versus flat alternatives. Italian and German specialty roasters are converting wholesale lines to this format ahead of retail reset cycles. The shift accelerates where direct-to-consumer subscription channels demand mailer-compatible dimensions.
- Flat Bags:Simple two-seam construction serves cost-sensitive commodity coffee tiers with shorter distribution cycles. These dominate institutional foodservice procurement where shelf presence matters less than unit economics.
- Zipper Bags:Reclosable track systems add consumer convenience premiums for retail-facing SKUs. Adoption clusters in United States grocery channels where household pantry storage duration drives repeat purchase metrics.
The dominant share belongs to Valve Bags, while Stand-Up Pouches are closing the gap fastest.
Material:
Cost tiers separate established multi-layer laminates from emerging biodegradable alternatives facing 2-3x price premiums.
- Plastic:Multi-layer polyethylene terephthalate and linear low-density polyethylene laminates deliver oxygen transmission rates below 0.1 cc per square meter per day. These structures anchor 12-month aromatic preservation for mass-market and premium tiers alike.
- Biodegradable:Polylactic acid and cellulose-based barrier films target organic certification tiers and Nordic retail chains ahead of EU single-use plastic directives. PLA formulations currently trade at multiples of conventional polyethylene equivalents, constraining volume to niche segments.
- Paper:Kraft-paper laminates with metallized or wax barriers serve roasters prioritizing tactile shelf differentiation and perceived sustainability. German converters lead integration of PFAS-free grease barriers under REACH Annex XVII timelines.
- Aluminum:Full-foil structures reserve for ultra-premium reserve tiers and export shipments exceeding 9-month distribution cycles. Chinese smelter concentration exposes converters to input cost volatility on fixed-price annual contracts.
Plastic laminates command the volume base, though Biodegradable structures are expanding most quickly among sustainability-positioned roasters.
Closure Type:
Application context determines whether hermetic seals or consumer convenience features justify incremental material cost.
- Heat Seal:Permanent fusion seams provide tamper evidence and maximum oxygen exclusion for wholesale distribution. These dominate roaster-to-distributor procurement where package opening signals transfer of custody.
- Zip Lock:Reclosable interlocking tracks extend freshness perception for retail consumers. United States grocery and specialty retail channels specify these for single-origin SKUs positioned above commodity tiers.
- Tie:Simple tin tie or wire-and-tag systems serve artisanal roasters with low-volume, high-SKU-count operations. Berlin and Hamburg roasting clusters favor these for aesthetic alignment with craft positioning.
- Clip:Detachable closure systems appear in gift and promotional packaging where reuse potential enhances brand touchpoint value.
Heat Seal closures hold the installed base, while Zip Lock configurations are gaining share fastest in retail-facing segments.
End User:
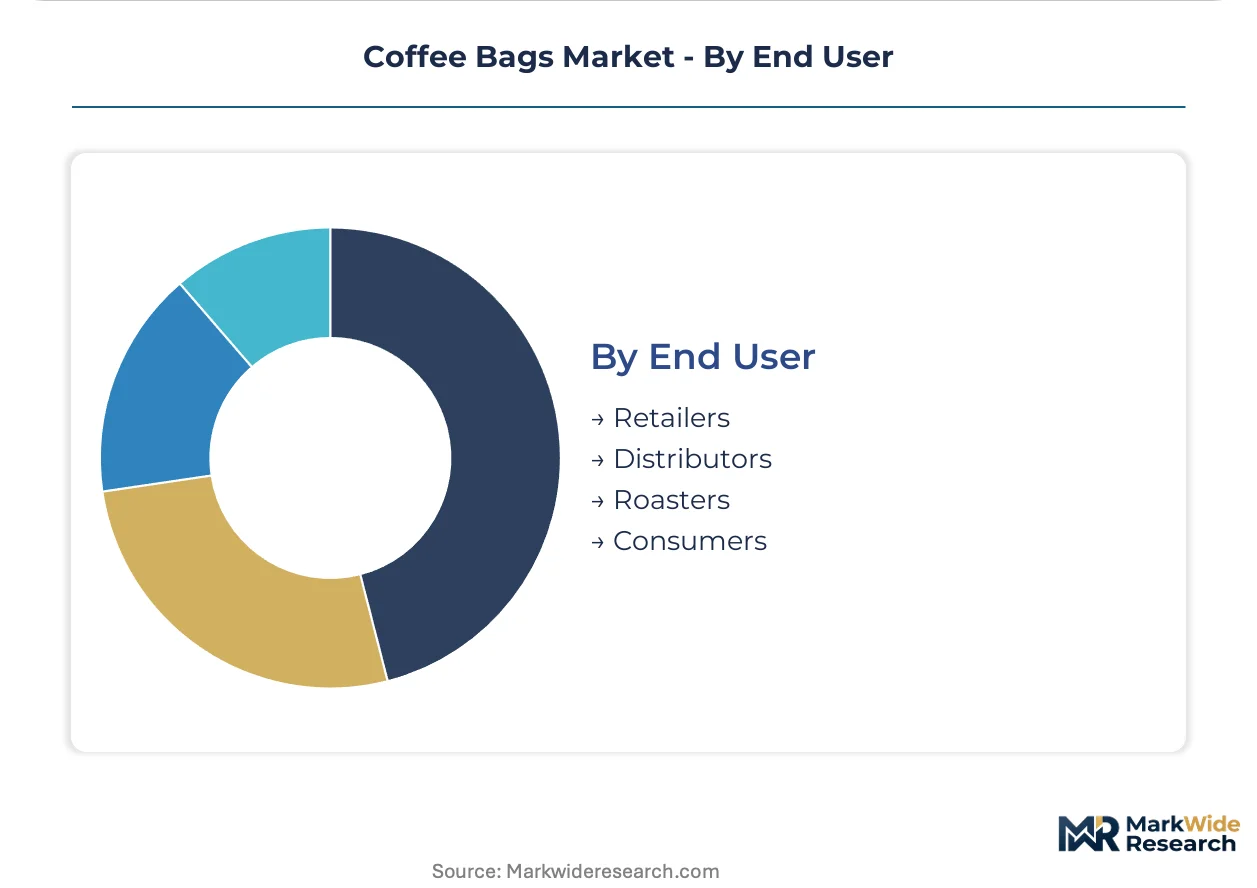
Customer type shapes order characteristics from minimum run lengths to regulatory documentation burdens.
- Roasters:Direct procurement from roasting operations concentrates demand for valve-equipped and digitally printed pouches with 48-hour turnaround capability. These buyers are consolidating supplier panels from 12-15 converters to 3-4 strategic partners.
- Retailers:Grocery and specialty chains specify certified home-compostable structures and PFAS-free documentation ahead of legal deadlines. Nordic retail chains demand these certifications earliest to secure shelf positioning.
- Distributors:Large-scale intermediaries prioritize 12-month oxygen barrier guarantees and inventory program flexibility. Their procurement treats coffee bags as a logistics input rather than a brand vehicle.
- Consumers:Direct-to-coffee-club subscribers in the United States and United Kingdom specify mailer-compatible dimensions and tear-notch configurations absent from traditional wholesale specifications.
Roasters represent the most influential demand segment, while Retailers are driving specification change fastest through sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in specialty coffee bag exports to Nordic and Alpine markets, while the United States and China absorb the largest import volumes of valve-equipped and digitally printed formats. Trade flows concentrate around converter clusters with integrated regulatory documentation capabilities.
Germany
Artisanal roasting clusters in Berlin and Hamburg drive procurement of valve-bag and stand-up pouch formats with 12-month oxygen barrier guarantees. The EU Packaging and Packaging Waste Regulation forces converters to revalidate barrier chemistries ahead of 2030 recyclability mandates. Baden-Württemberg hosts metallized PET innovation labs serving mid-tier roast applications.
United States
Regional roasting groups with 5-15 million annual bag volumes are consolidating supplier panels from 12-15 converters to 3-4 strategic partners. California's extended producer responsibility laws impose incremental testing and reporting obligations that favor larger converters with compliance scale. Pacific Northwest roasting clusters specify mailer-compatible pouch dimensions for direct-to-consumer subscription channels.
Italy
Specialty roasters are converting wholesale lines to stand-up pouch formats ahead of retail reset cycles, prioritizing shelf visibility and reduced freight cube. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances compel converters to eliminate fluoropolymer grease barriers from kraft-paper laminates by 2025. Northern Italian converter networks lead PFAS-free certification adoption for Nordic retail chain supply.
China
Domestic specialty coffee consumption is expanding fastest among tier-one cities, driving demand for digitally printed small-batch pouches with 48-hour turnaround capability. The national standardization administration is tightening food-contact substance migration limits for aluminum-foil laminates. Zhejiang and Jiangsu provinces concentrate converter capacity serving both domestic roasters and export markets.
United Kingdom
E-commerce coffee clubs specify tear-notch configurations and mailer-compatible dimensions absent from traditional wholesale specifications. The UK implementation of EU-derived packaging waste regulations is accelerating demand for certified home-compostable structures. London-based roasting operations are consolidating procurement around converters managing digital asset libraries and inventory programs simultaneously.
Coffee Bags Market Competitive Environment
Listed leaders compete with private specialists across regulatory documentation and digital print capability dimensions. The supplier base organizes into three tiers: integrated multinationals with polymer science depth, mid-cap regional converters with REACH compliance infrastructure, and small-batch digital specialists serving craft roaster loyalty. Consolidation pressures favor players managing regulatory documentation, digital asset libraries, and inventory programs simultaneously. Competitive moves center on M&A to capture compliance scale and strategic partnerships to access biodegradable material formulations.
Within the integrated multinational tier, Amcor plc and Mondi PLC exemplify scale-driven positions anchored by multi-layer laminate expertise and kraft-paper innovation respectively. MTPak Coffee Limited occupies a specialist position competing for craft roaster loyalty across Asia-Pacific through small-batch digitally printed pouch capability. These three entities represent the archetype spectrum from commodity-scale barrier production to micro-lot customization.
| Leading Market Players |
|---|
| Mondi PLC |
| American Plastics Company |
| Swiss Pac USA |
| Polysmarts Packaging |
| PBFY Packaging |
| CarePac Company |
| A-Pac Manufacturing Co., Inc. |
| MTPak Coffee Limited |
| Amcor plc |
| Others |
Value Chain & Pricing Dynamics
Metallized PET substitution for aluminum foil is redrawing supply geography toward German and Italian converter clusters while compressing pricing premiums on mid-tier barrier specifications. This material shift simultaneously loosens Chinese smelter dependency and intensifies competition among European laminate specialists.
Pricing Analysis
Specialty roasters anchor a three-tier pricing structure across premium, standard, and economy levels, with valve-equipped digitally printed pouches commanding spreads over commodity flat-bag equivalents. Price differentiation rests on oxygen barrier grade and REACH compliance documentation depth, with certified PFAS-free laminates extracting further premiums. Cost compression in standard-tier polyethylene structures is intensifying because Chinese resin oversupply is pressuring converter margins on fixed-price annual contracts. Distributor buyers exhibit highest price sensitivity due to volume procurement scale, while craft roasters prioritize turnaround speed over unit economics.
Supply Chain Analysis
China and Germany anchor global coffee bag converter capacity, with Zhejiang and Jiangsu provinces feeding both domestic specialty roasters and export markets while Baden-Württemberg hosts metallized PET innovation labs. Raw material dependencies draw from Saudi and Qatari polyethylene feedstock, Chinese aluminum smelter output, and Nordic kraft pulp supply. Single-source vulnerability concentrates in aluminum foil migration testing protocols, where ECHA-accredited laboratory capacity bottlenecks validation timelines. Distribution runs through roaster-direct procurement channels and consolidated supplier panels serving regional roasting groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coffee bags market sits in a cyclical recovery phase driven by specialty coffee consumption normalization post-pandemic disruption, with premium single-origin procurement resuming growth trajectories.
For Market Incumbents: Compound regulatory compliance scale by acquiring mid-cap converters with REACH infrastructure, while backward integration into metallized PET substrate production defends margin position against aluminum price volatility. Prioritize digital print press capacity in Germany and the United States to capture micro-lot roaster segments. For New Entrants and Emerging Players: Rapid-turnaround digital asset management represents a service-layer gap where incumbents under-serve craft roasters with sub-500-unit minimum runs. Penetrate Asia-Pacific specialty roasting clusters through 48-hour sample turnaround capability, leveraging HP Indigo press partnerships as primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors converters with integrated regulatory documentation and inventory program capabilities. Five-to-ten year viability hinges on PFAS-free certification positioning and compostable structure validation. Watch Nordic retail chain procurement mandates as inflection indicator for biodegradable material adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Barrier Certification | ECHA-accredited validation secures Nordic retail shelf positioning ahead of REACH deadlines. |
| Digital Print Press Installation | HP Indigo and Xeikon capacity unlocks micro-lot roaster segments with sub-500-unit minimums. |
| Compostable Structure Validation | Home-compostable certification penetrates EU retail chains ahead of single-use plastic directives. |
| Supplier Panel Consolidation | Strategic partnership density captures roaster procurement consolidation from 12-15 to 3-4 converters. |
| Metallized PET Substrate Integration | In-house metallized PET production reduces aluminum foil dependency and input cost volatility exposure. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade customs data, converter SEC filings, and EU regulatory registers. Primary interviews engaged specialty roaster procurement directors, flexible packaging plant managers, ECHA-accredited laboratory technical leads, and Nordic retail chain sustainability officers. Secondary validation drew from Packaging Europe regulatory tracking, FEFCO industry statistics, and REACH Annex XVII substance restriction updates. Bottom-up demand modeling triangulated against top-down converter capacity assessments.
Segmentation dimensions modeled span packaging type, material substrate, closure mechanism, and end-user archetype across the projection horizon. CAGRs derive from volume-weighted growth rates applied to segment-level baseline estimates. Forecast inputs incorporate specialty coffee consumption indices, EU PPWR implementation timelines, and digital print press installation counts.
Underlying assumptions cover sustained specialty roaster procurement consolidation and REACH compliance cost pass-through elasticity, with deviation risk concentrated in aluminum price volatility and biodegradable material cost convergence timelines. Recalibration cycles align with material shifts in EU packaging waste regulation enforcement and Nordic retail chain sustainability mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Smart Coffee Maker Market
Coffee
Vietnam Coffee Market
Coffee
Butter Coffee Market
Coffee
Adaptogen Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Global Portable Coffee Makers Market
Coffee
Specialty Coffee Market
Coffee
Caffeine Market
Coffee
Coffee Pods and Capsules Market
Coffee
Australia Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Global Nespresso Capsules Market
Coffee
Single Origin Coffee Market
Coffee
Asia Pacific Coffee Market
Coffee
Roast to Order Coffee Market
Coffee
Coffee Syrup Market