
 Reusable Coffee Cup Market | 2026-2036
Reusable Coffee Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Coffee Cup Market Insights
Barista training programs and cup-washing infrastructure labor is rotating toward reusable-compatible workflows in major café chains, expanding addressable volume for cup manufacturers. KeepCup leverages its origin in Melbourne's café culture to sustain design leadership across the Asia-Pacific. Hydro Flask anchors premium insulated positioning through material science R&D in vacuum-sealed construction. Frank Green differentiates via integrated payment-chip lids that compete with conventional loyalty programs.
A reusable coffee cup is a portable, multi-use beverage container engineered from food-grade materials such as borosilicate glass, 18/8 stainless steel, or medical-grade silicone, designed to replace single-use disposable cups through thermal insulation, leakproof sealing, and standardized sizing compatible with commercial espresso machines. Stainless steel variants dominate margin pools due to durability premiums and vacuum insulation performance, while silicone collapsible designs represent the fastest-growing design type as backpack commuters prioritize packability. Glass segments maintain steady office-channel demand where aesthetic transparency and microwave compatibility offset fragility trade-offs.
The EU Single-Use Plastics Directive and FDA food-contact material standards collectively shape product compliance pathways, with REACH chemical restrictions further constraining coating formulations available to European suppliers. BIS certification requirements in India and GB standards in China create divergent testing regimes that fragment manufacturing scale economics. Stakeholders must monitor how extended producer responsibility schemes in France, Germany, and Italy redefine cost allocation between cup brands and retail partners.
Market Dynamics
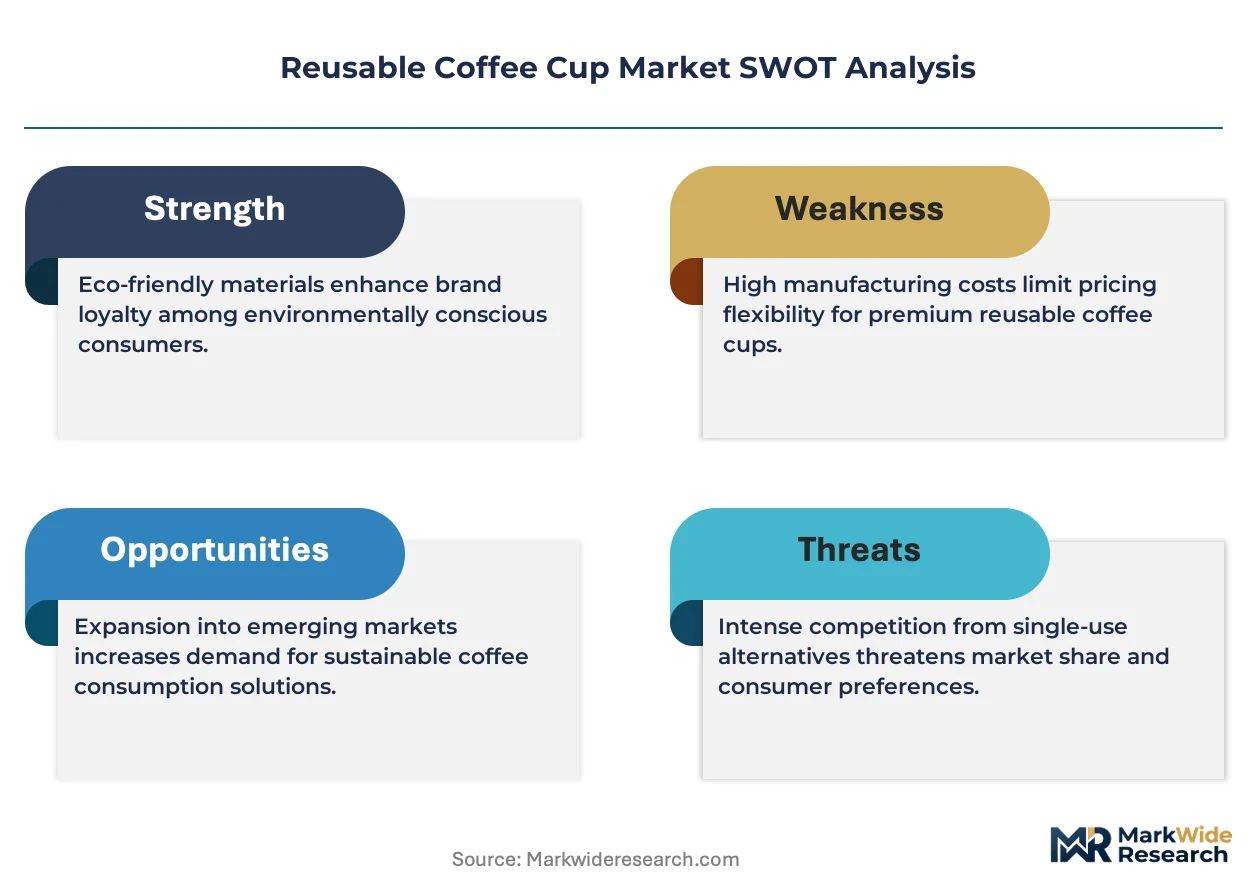
Café chains are rewiring operational workflows around reusable-compatible infrastructure, converting a consumer accessory category into a B2B procurement channel anchored by washing stations, staff retraining, and loyalty integration.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory reduction targets for disposable foodware are forcing foodservice operators across Germany, France, and Italy to source certified reusable alternatives, creating institutional procurement pull.
- Vacuum insulation engineering:Advances in double-wall stainless steel construction have extended thermal retention windows to 6-12 hours, satisfying commuter expectations previously met by disposable cups.
- Melbourne café culture:Dense urban coffee consumption in Australian cities normalizes bring-your-own-cup behavior, generating design feedback loops that propagate to European and North American markets.
Market Restraints
- Medical-grade silicone feedstock volatility:Collapsible cup manufacturers face input cost swings tied to petrochemical derivatives and specialized catalyst supply chains concentrated in East Asian chemical parks.
- REACH coating restrictions:ECHA chemical limitations constrain durable interior lining options for European-market stainless steel vessels, forcing reformulation cycles that extend product development timelines.
- Single-use paper cup residual cost advantage:Bulk disposable pricing at €0.02-0.05 per unit sustains operator inertia in price-sensitive QSR segments despite regulatory pressure.
Strategic Opportunities
- India BIS certification pathway:Formal standardization of food-contact reusables under Bureau of Indian Standards creates first-mover positioning for compliant exporters targeting metro café expansion in Mumbai and Bangalore.
- Integrated payment-chip lids:Convergence of NFC hardware and cup industrial design enables transaction-enabled vessels that bypass traditional loyalty card infrastructure.
- Corporate campus programs:ESG procurement mandates at technology and financial services firms are opening direct B2B channels that bypass retail fragmentation.
Industry Challenges
- Barista workflow retraining:Café staff must adapt to non-standardized cup dimensions, mouth diameters, and thermal masses that disrupt automated espresso machine calibration.
- Multi-jurisdiction certification stacking:Manufacturers targeting simultaneous FDA, EFSA, and BIS compliance face divergent migration testing protocols that fragment production batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Coffee Cup Market |
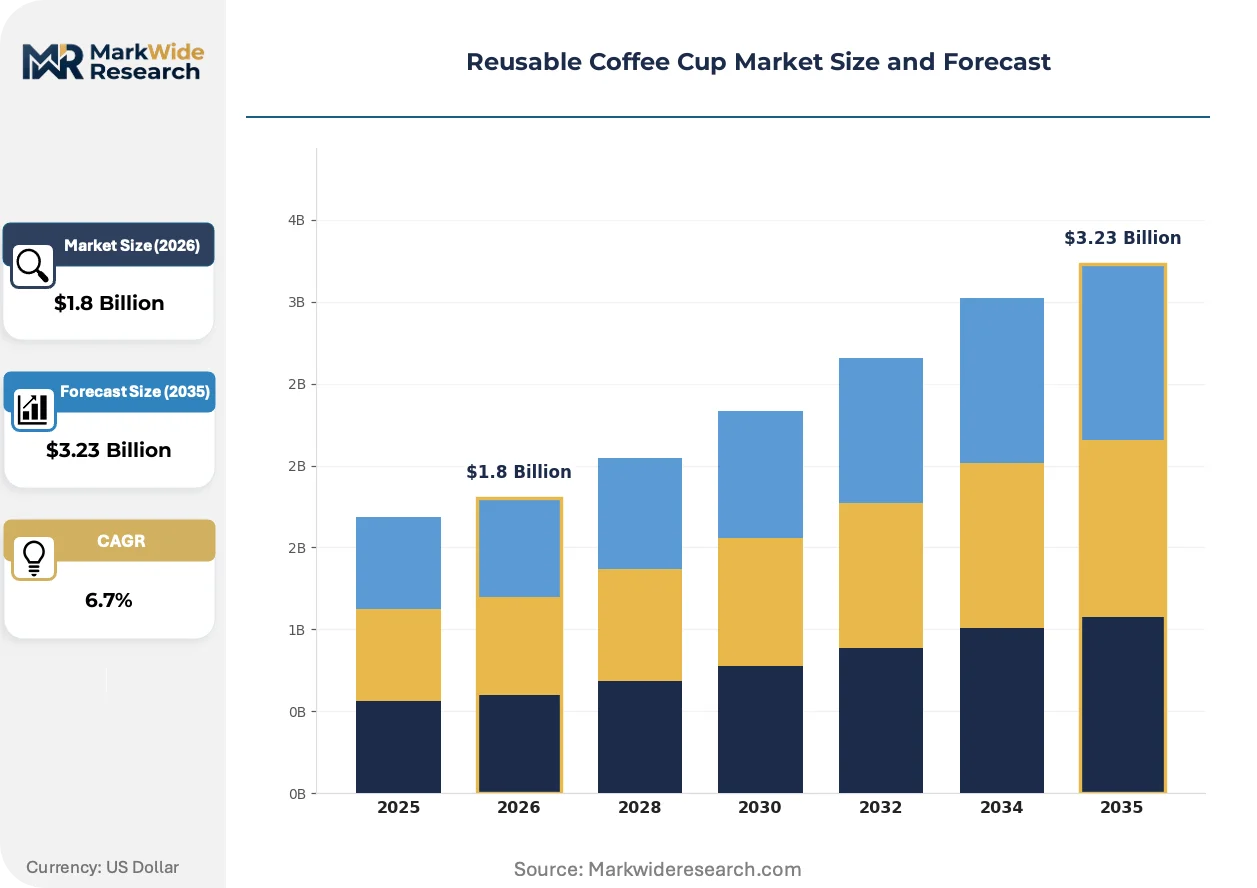
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Silicone, Glass, Stainless Steel, Plastic Capacity: 8 oz, 12 oz, 16 oz, 20 oz Usage Occasion: Office, Travel, Home, Outdoor Design Type: Insulated, Collapsible, Customizable, Standard |
| Companies Covered | KeepCup, Frank Green, Hydro Flask, Circular&Co., Klean Kanteen, YETI Holdings, Inc., Thermos LLC, Ecoffee Cup, Stanley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Coffee Cup Market Trends and Innovations
Material science convergence with embedded electronics is redefining what constitutes a coffee vessel, transforming passive containers into active service-delivery nodes.
Medical-grade silicone laminates bonded to stainless steel cores are displacing pure polymer collapsible designs in commuter segments. Urban professionals in German and Australian cities adopt these hybrid vessels for packability without thermal compromise. The displacement is compressing addressable volume for single-material silicone competitors.
REACH chemical restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick interior coatings from European-market production. Manufacturers pivot to ceramic-derived or uncoated electropolished finishes that satisfy migration limits. Stainless steel segments with premium positioning absorb compliance costs most readily.
Direct-to-employer procurement contracts are emerging as a parallel channel alongside retail and foodservice distribution. Sustainability officers at London and New York financial institutions negotiate bulk vessel programs with customized branding. This channel rotation concentrates volume with fewer buyers, altering manufacturer sales force deployment.
Reusable Coffee Cup Market Segmentation
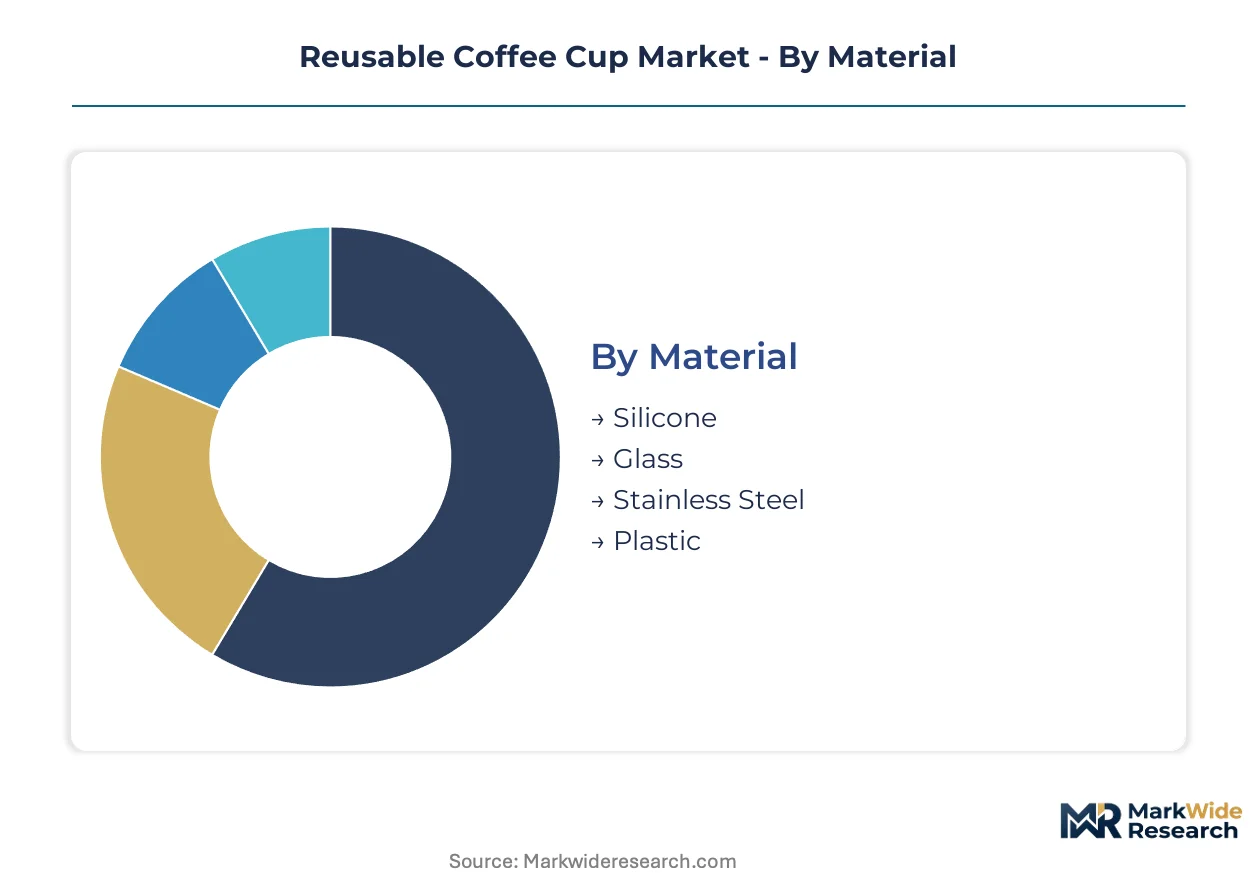
Material composition determines thermal performance, regulatory compliance pathways, and margin architecture across retail, foodservice, and corporate procurement channels. Capacity sizing and design formats further stratify addressable demand by commuter behavior patterns and café workflow compatibility.
Material:
Channel mix varies sharply by material: stainless steel dominates premium retail and corporate gifting, silicone collapsibles concentrate in travel retail and e-commerce, glass anchors office-direct sales, while plastic competes in QSR promotional programs.
- Stainless Steel:Double-wall vacuum construction with 18/8 food-grade alloy delivers 6-12 hour thermal retention. German and Australian commuter corridors drive demand for electropolished and ceramic-lined variants that satisfy ECHA migration limits under REACH.
- Silicone:Medical-grade platinum-cured elastomer enables collapsible geometries that compress to 30% of expanded volume. Backpack commuters in dense urban clusters prioritize packability over insulation duration, feeding travel retail and direct-to-consumer channels.
- Glass:Borosilicate construction offers microwave compatibility and aesthetic transparency for desk-based consumption. Office procurement channels in London and New York financial districts favor this material for visible sustainability signaling.
- Plastic:Tritan copolyester and polypropylene variants compete on unit economics for QSR loyalty program giveaways and entry-level retail placement. FDA food-contact compliance enables broad US distribution despite thermal performance trade-offs.
By volume, plastic leads through promotional scale. By growth pace, silicone collapsibles are climbing the fastest as hybrid work patterns reshape commuter needs.
Capacity:
Cost tier stratification aligns with beverage pricing psychology: smaller formats command premium per-ounce pricing in specialty coffee channels, while larger vessels compete on utility value in outdoor and travel segments.
- 12 oz:Standard espresso-based drink volume matches specialty café menu architecture. This format captures the highest margin per unit in retail channels due to universal machine compatibility and commuter daily-use frequency.
- 16 oz:North American coffeehouse standard size accommodates drip coffee and larger milk-based beverages. Foodservice procurement contracts in the United States specify this capacity for loyalty program integration.
- 8 oz:Concentrated espresso and macchiato volumes prevail in Italian and French café culture. Premium positioning in Milan and Paris specialty channels supports higher unit economics despite smaller absolute volume.
- 20 oz:Extended-duration outdoor and road-trip usage drives demand for maximum liquid capacity. Camping and adventure retail channels in Australia and the western United States concentrate this segment's volume.
By volume, 12 oz leads through café workflow standardization. By margin contribution, 8 oz specialty formats gain share fastest.
Usage Occasion:
Customer type determines purchase trigger and replacement cycle: office users buy for desk aesthetics, travelers prioritize packability, home users seek versatility, outdoor enthusiasts demand durability extremes.
- Office:Desktop permanence enables glass and ceramic constructions that sacrifice portability for microwave access and visual appeal. Corporate sustainability mandates in London and New York drive bulk procurement through facilities management channels.
- Travel:Airport and rail commuter contexts favor leakproof sealing and compact stowage. Collapsible silicone and slim-profile stainless steel designs concentrate in this segment with TSA-friendly dimensions.
- Home:Multi-beverage versatility across coffee, tea, and cold drinks supports larger capacity vessels with interchangeable lids. E-commerce discovery and subscription models capture this discretionary purchase behavior.
- Outdoor:Hiking and camping contexts demand impact resistance and extended thermal retention. Vacuum-insulated stainless steel with carabiner-compatible lids dominates specialty outdoor retail in Germany and the western United States.
By volume, office procurement leads through corporate ESG programs. By expansion trajectory, travel occasions are gaining share fastest as return-to-office patterns stabilize.
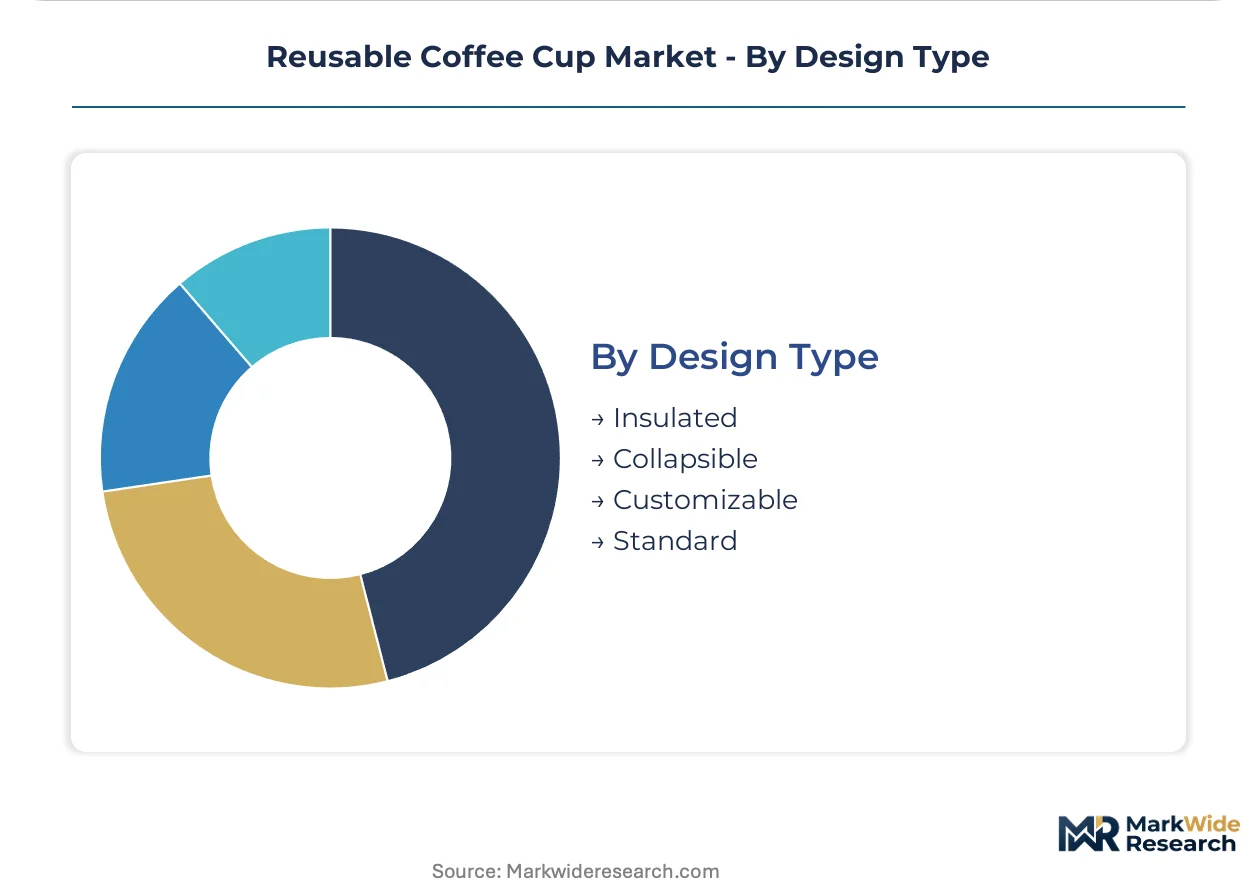
Design Type:
Maturity gradients separate established formats from emerging innovations: insulated and standard designs represent baseline market presence, while collapsible and customizable variants capture technology-driven growth.
- Insulated:Vacuum-sealed double-wall construction across stainless steel and some glass variants delivers thermal performance that rivals disposable cup temperature maintenance. This design commands premium pricing in cold-climate geographies.
- Collapsible:Silicone bellows and nesting geometries enable pocket-scale portability that expands to full capacity. Urban density in Melbourne and Berlin normalizes this format for multi-modal commuters.
- Customizable:Interchangeable sleeves, lid colors, and engraving services support corporate branding and individual expression. Direct-to-employer channels in technology and financial services specify this capability for identity programs.
- Standard:Single-wall construction without thermal enhancement competes on cost and simplicity for home and casual use. Entry retail and promotional channels sustain volume despite functional limitations.
By volume, standard designs lead through price accessibility. By growth pace, customizable formats are expanding most quickly as corporate procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers absorb 40-60% pricing premiums for REACH-compliant vessels, while Indian metro buyers prioritize sub-$10 entry points. This asymmetry fragments manufacturer margin architectures across geographies.
Germany
Urban commuters in Berlin and Hamburg drive insulated stainless steel demand through dense café networks and municipal waste reduction targets. ECHA REACH restrictions on PFAS coatings force ceramic-lined and electropolished interior finishes. Bavaria's manufacturing clusters supply precision vacuum-sealing equipment to domestic cup producers.
United States
Specialty coffee chains in Seattle and Portland normalize bring-your-own-cup discounts, while corporate ESG procurement in New York and San Francisco opens direct B2B channels. FDA food-contact material standards govern silicone and stainless steel formulations. Austin and Denver outdoor retail corridors concentrate vacuum-insulated vessel distribution for adventure segments.
United Kingdom
London's financial district sustainability mandates drive bulk corporate procurement of glass and customizable vessels for desk-based consumption. The UK's post-EU regulatory alignment with REACH maintains chemical migration testing requirements. Manchester and Birmingham café density supports 12 oz format standardization across independent roasters.
Australia
Melbourne's café culture generates design feedback loops that propagate collapsible silicone formats to European markets. Municipal waste targets in Sydney and Brisbane accelerate single-use displacement. KeepCup's origin in Victoria sustains regional design leadership and Asia-Pacific distribution anchoring.
India
Mumbai and Bangalore metro café expansion creates first-mover positioning for BIS-certified exporters targeting institutional procurement. FSSAI food-contact standards intersect with BIS certification requirements for formal market entry. Delhi-NCR corporate campuses pilot direct-to-employer vessel programs under ESG procurement mandates.
Reusable Coffee Cup Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium insulated specialists compete on vacuum-sealing performance and material science R&D, while collapsible silicone manufacturers optimize packability and unit economics. The market fragments across three strategic archetypes: design-origin lifestyle brands, outdoor-performance specialists, and corporate-procurement scale players. Dominant competitive moves include geographic expansion into BIS-regulated India and strategic partnerships with café chains for loyalty-integrated lid technology.
Among design-origin lifestyle specialists, KeepCup and Frank Green exemplify regionally anchored brand equity that propagates globally. KeepCup represents Melbourne café culture translation into European and North American markets. Frank Green occupies a position at the convergence of industrial design and embedded payment technology. Hydro Flask anchors the outdoor-performance tier through vacuum-insulation specialization. These three players illustrate how geographic origin and functional positioning stratify competitive space without consolidated market control.
| Leading Market Players |
|---|
| KeepCup |
| Frank Green |
| Hydro Flask |
| Circular&Co. |
| Klean Kanteen |
| YETI Holdings, Inc. |
| Thermos LLC |
| Ecoffee Cup |
| Stanley |
| Others |
Pricing and Supply Chain Analysis
ECHA REACH migration limits on per- and polyfluoroalkyl substances simultaneously gate European supplier qualification and stratify price tiers between ceramic-lined premium vessels and reformulation-lagged competitors. This regulatory threshold forces dual-track manufacturing that fragments scale economics and amplifies geographic price spreads.
Pricing Analysis
German consumers absorb 40-60% premiums for REACH-compliant vessels while Indian metro buyers cluster below $10 entry points. Pricing stratifies across premium, standard, and economy tiers anchored by certification grade and thermal performance specifications. Cost compression in silicone collapsible segments intensifies as petrochemical feedstock volatility feeds through East Asian chemical parks. QSR procurement teams exhibit highest price sensitivity; corporate sustainability officers show lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate stainless steel vacuum vessel assembly while strategic stockpiling of medical-grade silicone prevails among collapsible manufacturers facing catalyst supply uncertainty. Manufacturing gravity centers on China for precision metal forming, Vietnam for silicone molding, and Germany for vacuum-sealing equipment. Raw material dependencies span 18/8 stainless steel feedstock, platinum-cured silicone elastomer, and borosilicate glass tubing. Single-source vulnerability concentrates in specialized vacuum-pump componentry. Distribution runs through café chain procurement portals, outdoor retail networks, and direct-to-employer corporate channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through corporate ESG procurement mandates that aggregate demand across technology and financial services campuses, fragmenting traditional retail channel leverage.
For Market Incumbents: Fortify certification moats by accelerating BIS pathway completion ahead of Indian metro café expansion. Deepen backward integration into vacuum-sealing equipment supply through Bavarian manufacturing partnerships. Lock in barista workflow training partnerships with specialty chains to raise switching costs against emerging payment-chip lid competitors. For New Entrants and Emerging Players: BIS fast-track certification unlocks institutional procurement in Mumbai and Bangalore before incumbent compliance documentation cycles complete. White-space concentrates in India corporate campus direct-to-employer programs and hybrid-material silicone-stainless collapsible designs. Go-to-market should anchor with facilities management channel partnerships rather than retail shelf placement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across collapsible silicone manufacturing as automated platinum-curing lines displace batch processes. Long-term viability favors design-origin lifestyle brands with café culture authenticity over commodity stainless stampers. Acquisition targets should display integrated payment-chip R&D pipelines or established Melbourne café network relationships. Watch for REACH coating restriction enforcement intensity as margin compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Payment-Chip Lid Integration | NFC-enabled vessels bypass traditional loyalty infrastructure at specialty chains in Berlin and Melbourne. |
| BIS Certification Fast-Track | First-mover compliance captures institutional procurement in Mumbai and Bangalore metro corridors. |
| Corporate Campus Direct Programs | ESG mandates at London and New York financial firms aggregate demand outside retail fragmentation. |
| Ceramic Lining R&D Investment | REACH-compliant interior finishes defend European market access against reformulation-lagged competitors. |
| Barista Workflow Partnerships | Training integration with German and Australian café chains raises switching costs for new vessel entrants. |
Research Methodology
A standing panel of café chain procurement directors, sustainability officers at financial services firms, vacuum-sealing equipment engineers, and specialty coffee roasters provided ongoing calibration. Primary interviews combined with secondary validation from customs trade records, SEC filings of outdoor retail conglomerates, ECHA substance restriction updates, and café industry association reports. Bottom-up vessel shipment data triangulated against top-down consumer expenditure estimates.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation modeling incorporated material composition, capacity sizing, usage occasion, and design format dimensions. CAGRs derived from regression analysis of historical adoption curves weighted by regulatory enforcement timelines and café density indices. Forecast inputs included REACH reformulation cycle durations and BIS certification backlog estimates.
The analysis sits within stated boundaries; outcomes outside sustained EU Single-Use Plastics Directive enforcement or accelerated India metro café expansion would require recalibration. Forecasts reflect assumptions on barista workflow adaptation rates and silicone feedstock price stability. Revision becomes warranted when REACH coating restriction enforcement crosses threshold intensity or India corporate ESG procurement mandates accelerate beyond modeled adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Asia Pacific Coffee Market
Coffee
US Coffee Machine Market
Coffee
Singapore Coffee Roaster Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Adaptogen Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Ethiopia Coffee Market
Coffee
Coffee Bottle Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Raw Coffee Beans Market
Coffee
Out-Of-Home Coffee Market
Coffee
North America Specialty Coffee Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Cold Brew Coffee Market
Coffee
Coffee and Tea Capsule Market