
 Animal Feed Safety Testing Equipment Market | 2026-2036
Animal Feed Safety Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Safety Testing Equipment Market Insights
EU Regulation 2023/915 on maximum levels for certain contaminants in food and feed is consolidating compliance spending across European feed manufacturers. Thermo Fisher Scientific leverages its chromatography portfolio to anchor premium positioning in mycotoxin analysis workflows. Neogen Corporation sustains channel dominance through specialized test kits calibrated for aflatoxin B1 detection in dairy feed rations. Agilent Technologies competes on spectroscopy platforms designed for multi-residue pesticide screening in compound feeds.
Animal feed safety testing equipment comprises analytical instruments and consumable kits engineered to detect pathogens, chemical residues, mycotoxins, and nutritional deficiencies in feed matrices, with detection thresholds typically ranging from parts-per-billion for aflatoxins to colony-forming-unit counts for Salmonella species. These systems serve the primary commercial purpose of preventing contaminated feed from entering livestock production chains, thereby protecting animal health, human food safety, and export market access. Mycotoxin test kits command the largest installed base due to regulatory mandates for aflatoxin and vomitoxin screening, while PCR-based pathogen detection represents the fastest-expanding technology segment as poultry farms adopt same-day Salmonella and E. coli verification. Chromatography systems retain the deepest margin pools because method development services and consumable replenishment generate recurring revenue streams beyond initial instrument placement.
The FDA's Food Safety Modernization Act preventive controls for animal food, EFSA's guidance on feed additive safety assessment, and ISO/IEC 17025 laboratory accreditation standards collectively shape instrument specifications, validation protocols, and vendor qualification criteria across major markets. Feed manufacturers in the United States and European Union now face parallel requirements for hazard analysis, supply chain verification, and documented testing frequencies that directly determine equipment procurement cycles. Stakeholders must monitor evolving maximum residue limits for emerging mycotoxins such as T-2 toxin and diacetoxyscirpenol, as regulatory expansion into these analytes will drive replacement demand for platforms with broader compound libraries and lower detection thresholds.
Market Dynamics
Chromatography-based mycotoxin detection systems are consolidating procurement budgets as feed manufacturers absorb stricter aflatoxin surveillance mandates from the FDA and EFSA, compressing capital deployment cycles toward integrated platforms that bundle method development with consumable replenishment.
Growth Catalysts
- EU Regulation 2023/915:Maximum residue limits for aflatoxins and fumonisins in corn and soybean meal are mandating laboratory upgrades across European compound feed producers.
- PCR-based pathogen detection:Same-day Salmonella and E. coli verification is accelerating adoption in poultry farm quality control workflows.
- ISO/IEC 17025 accreditation:Documented testing frequencies and supply chain verification requirements are driving replacement demand for validated analytical platforms.
Market Restraints
- High-purity solvent costs:Chromatography-grade acetonitrile and methanol price volatility constrains operational budgets for high-throughput laboratories.
- Reference material scarcity:Certified mycotoxin standards from European suppliers face extended lead times, delaying method validation.
- Detection threshold limitations:Emerging T-2 toxin and diacetoxyscirpenol analytes exceed current immunoassay kit sensitivity ranges.
Strategic Opportunities
- Brazilian feed export sector:ANVISA alignment with Codex Alimentarius standards creates demand for multi-residue pesticide screening platforms in São Paulo and Paraná processing clusters.
- Near-infrared spectroscopy convergence:Portable NIR devices integrated with cloud-based chemometric models enable on-farm nutritional deficiency screening.
- Subscription-based consumable programs:Reagent replenishment contracts lock in recurring revenue streams beyond initial instrument placement.
Industry Challenges
- Analytical chemist shortage:Method development expertise for complex feed matrices remains concentrated among aging specialists in Germany and the Netherlands.
- Legacy LIMS integration:New chromatography data systems require costly middleware to connect with established laboratory information management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Safety Testing Equipment Market |
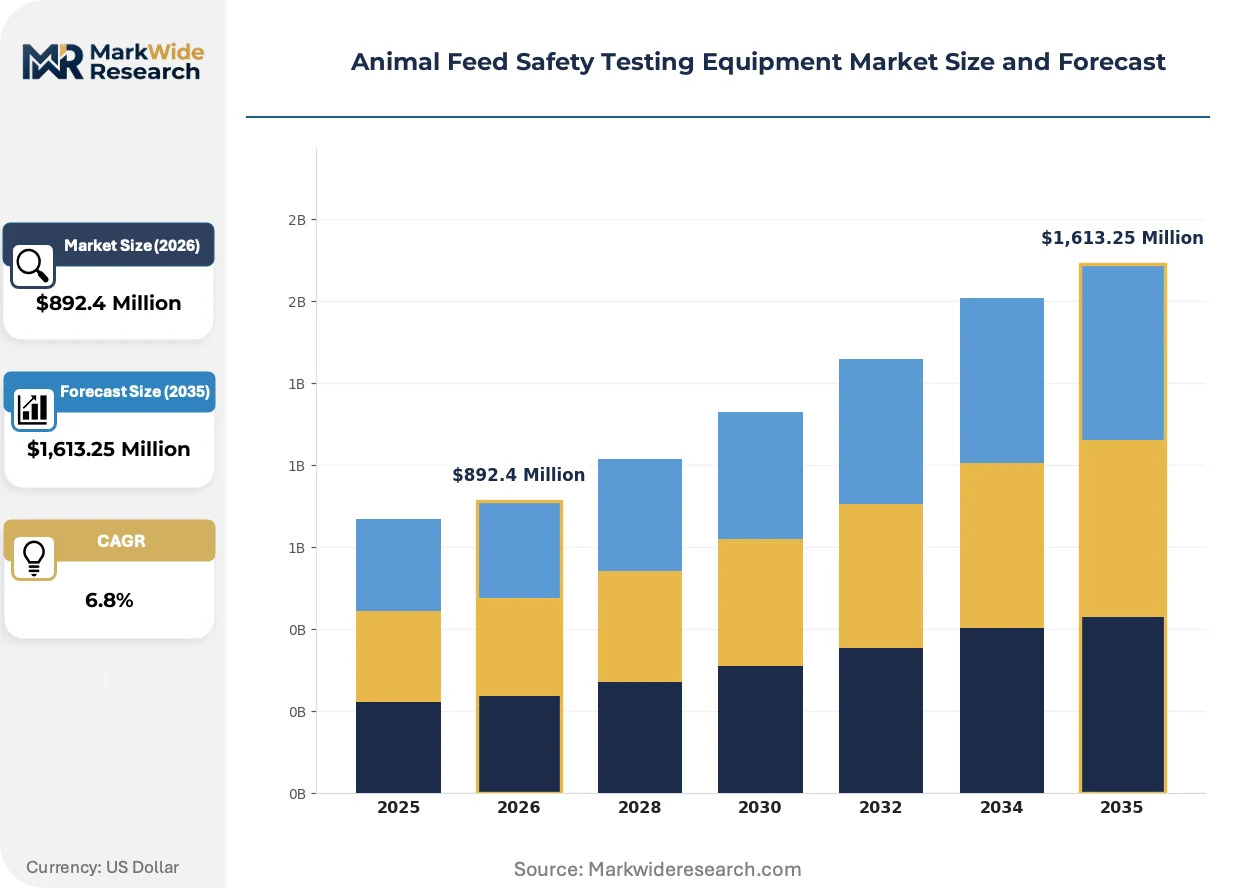
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Testing Equipment, Chemical Analyzers, Mycotoxin Test Kits, Nutritional Analyzers Technology: Chromatography, Spectroscopy, PCR, ELISA End User: Poultry Farms, Livestock Producers, Aquaculture Facilities, Feed Manufacturers Application: Quality Control, Regulatory Compliance, Product Development, Research |
| Companies Covered | Thermo Fisher Scientific, Neogen Corporation, Agilent Technologies, SGS SA, Eurofins Scientific, Bureau Veritas, Intertek Group plc, ALS Limited, Mérieux NutriSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Safety Testing Equipment Market Trends and Innovations
Portable and connected detection platforms are compressing the time between sampling and regulatory decision-making, reshaping how feed manufacturers allocate capital between centralized laboratories and distributed quality control points.
Quantum cascade laser spectroscopy is electrifying real-time mycotoxin screening at grain elevator intake points. Large integrated poultry operations in Iowa and Arkansas are deploying these systems to bypass laboratory bottlenecks during harvest surge periods. The technology is electrifying competitive positioning among instrument vendors by collapsing detection turnaround from days to minutes.
The FDA's Food Safety Modernization Act preventive controls for animal food are mandating documented hazard analysis across all registered feed facilities. Manufacturers must now validate supply chain verification procedures or face inspection citations. Small and mid-sized compound feed producers in the Midwest are consolidating testing volumes through third-party ISO-accredited laboratories to satisfy documentation burdens.
Service unbundling is fragmenting traditional instrument vendor relationships. Feed manufacturers now separate hardware procurement from method development support and consumable supply, pitting specialized chromatography service firms against original equipment providers. This pattern is most visible among dairy feed ration blenders in Wisconsin and California seeking cost transparency in multi-year operating agreements.
Animal Feed Safety Testing Equipment Market Segmentation
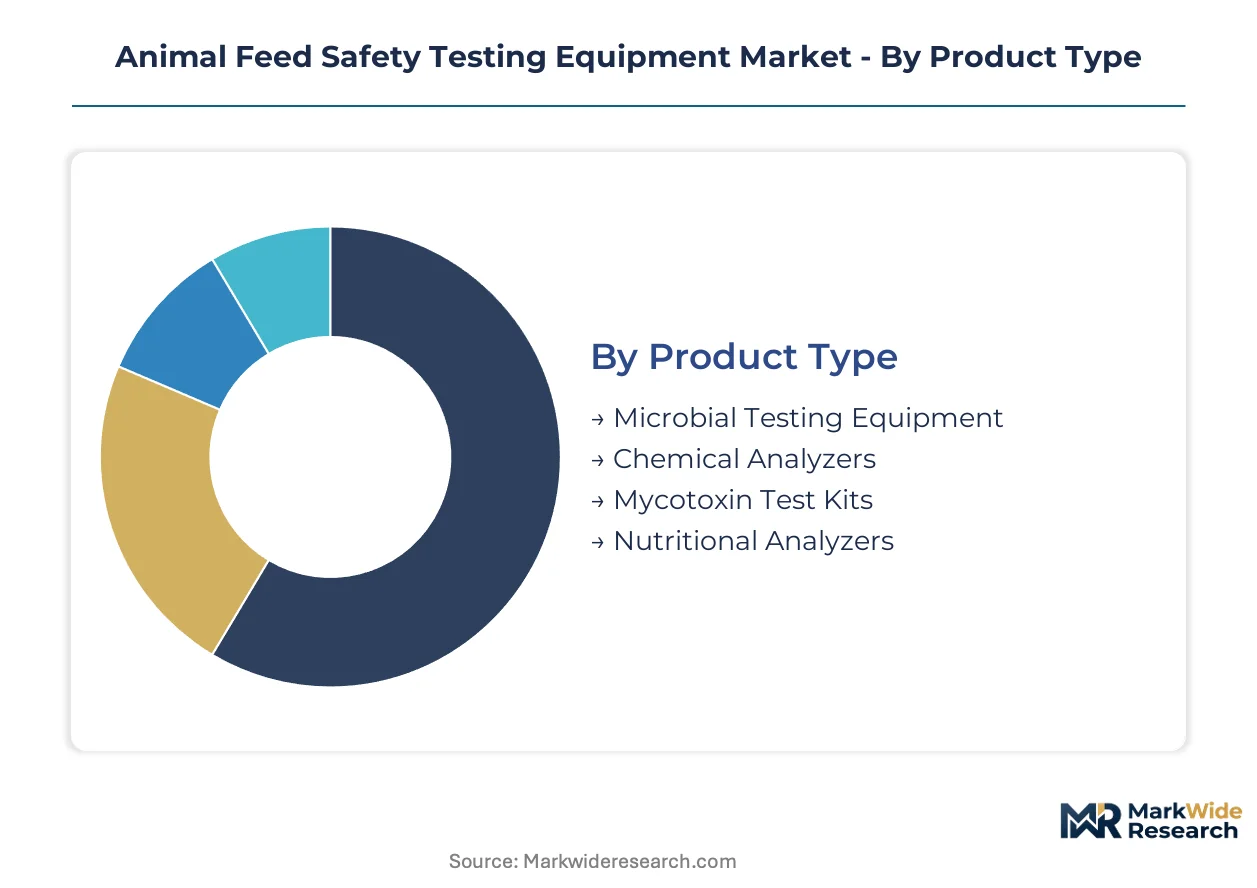
Feed safety testing equipment segments reflect divergent capital deployment patterns across centralized laboratories and distributed farm-level quality control points. Procurement decisions hinge on detection sensitivity requirements, regulatory documentation burdens, and operational throughput demands specific to each buyer category.
Product Type:
Capital intensity and consumable replenishment frequency separate buyers in this category, with high-throughput laboratories favoring instrument-heavy platforms while on-farm operations prioritize rapid test kits.
- Mycotoxin Test Kits:Immunoassay-based detection systems calibrated for aflatoxin B1 and vomitoxin screening dominate installed base due to FDA and EFSA surveillance mandates. Corn and soybean meal processors in Iowa and Illinois concentrate procurement volumes here, driven by harvest-season surge testing requirements and documented verification protocols under preventive controls regulations.
- Chromatography Systems:High-performance liquid chromatography and mass spectrometry platforms deliver parts-per-billion detection thresholds for multi-residue mycotoxin panels. European compound feed manufacturers in Germany and the Netherlands absorb premium pricing for integrated systems bundling method development services, generating recurring revenue through solvent and column replenishment contracts.
- Microbial Testing Equipment:Automated colony counters and pathogen identification systems serve Salmonella and E. coli verification workflows.
- Chemical Analyzers:Spectroscopy-based platforms detect pesticide residues and heavy metal contamination in imported feed ingredients.
- Nutritional Analyzers:Near-infrared devices enable proximate analysis of protein, fat, and moisture content in finished feed rations.
Volume sits with Mycotoxin Test Kits; growth tilts toward Chromatography Systems.
Technology:
Detection speed and capital expenditure thresholds differentiate technology selection, with same-day result requirements pushing adoption toward rapid molecular methods while reference laboratories maintain chromatography for definitive quantification.
- Chromatography:Liquid and gas chromatography platforms retain deepest margin pools through consumable lock-in and method development service contracts. Large integrated poultry operations in Arkansas and Texas deploy these systems for aflatoxin and fumonisin quantification at parts-per-billion thresholds required for export certification to EU markets.
- PCR:Polymerase chain reaction systems deliver same-day Salmonella and E. coli verification, expanding fastest among poultry farm quality control workflows. Brazilian processors in São Paulo and Paraná adopt PCR platforms to satisfy ANVISA alignment with Codex Alimentarius pathogen standards for export-bound soybean meal.
- Spectroscopy:UV-visible and atomic absorption instruments support heavy metal screening in mineral premixes.
- ELISA:Enzyme-linked immunosorbent assay kits provide cost-effective mycotoxin screening for mid-sized feed mills.
Revenue concentrates in Chromatography; PCR is expanding most quickly.
End User:
Regulatory proximity and documentation burden shape procurement patterns, with export-facing manufacturers investing in accredited laboratories while domestic-oriented farms prioritize rapid on-site screening.
- Feed Manufacturers:Compound feed producers face consolidated compliance spending under FDA preventive controls and EFSA contaminant regulations. Facilities in Wisconsin and California absorb capital costs for ISO/IEC 17025 accredited platforms to satisfy documented testing frequencies and supply chain verification requirements.
- Poultry Farms:Vertically integrated operations in Iowa and Georgia deploy portable detection systems at intake points to bypass laboratory bottlenecks during harvest surge periods. Quantum cascade laser spectroscopy is gaining traction here for real-time mycotoxin screening without sample preparation delays.
- Livestock Producers:Dairy and beef operations concentrate testing budgets on nutritional analyzers for ration optimization.
- Aquaculture Facilities:Shrimp and salmon producers prioritize pathogen detection for Vibrio and Aeromonas species in formulated feeds.
Procurement volume clusters with Feed Manufacturers; Poultry Farms are gaining share fastest.
Application:
Operational purpose determines equipment specification, with compliance-driven buyers prioritizing validation documentation and traceability while research-oriented users emphasize method flexibility and detection breadth.
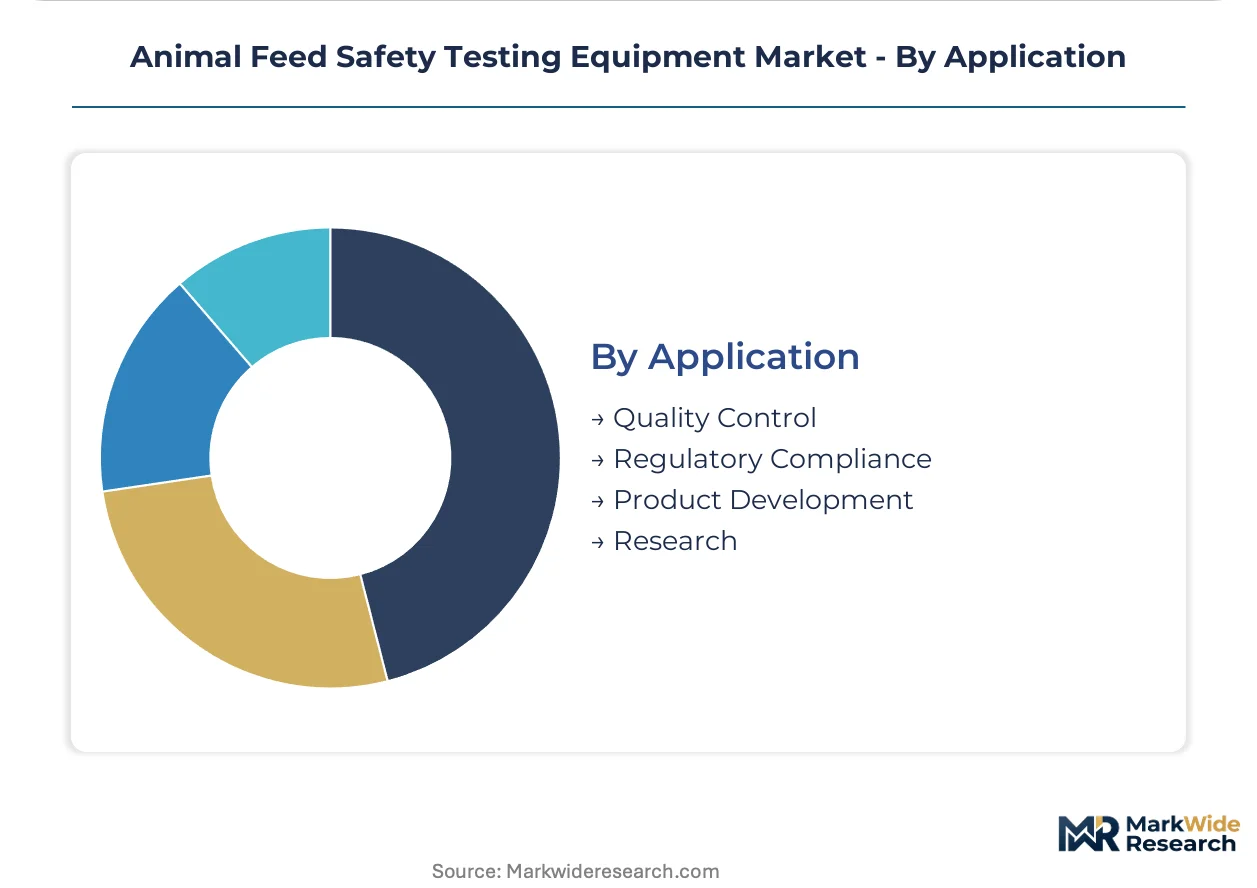
- Regulatory Compliance:Documented hazard analysis and supply chain verification requirements under FDA Food Safety Modernization Act and EU Regulation 2023/915 drive replacement demand for validated analytical platforms. Third-party ISO-accredited laboratories in the Midwest consolidate testing volumes from small and mid-sized compound feed producers seeking cost transparency in multi-year operating agreements.
- Quality Control:Same-day verification workflows at grain elevators and feed mills prioritize detection speed over analytical breadth. Near-infrared spectroscopy convergence enables on-farm nutritional deficiency screening through portable devices integrated with cloud-based chemometric models.
- Product Development:Feed additive manufacturers invest in broad-spectrum screening for novel ingredient safety assessment.
- Research:University and government laboratories pursue method development for emerging mycotoxins including T-2 toxin and diacetoxyscirpenol.
Spending concentrates in Regulatory Compliance; Quality Control is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States feed manufacturers absorb the largest procurement volumes for mycotoxin detection systems as FDA preventive controls tighten documentation requirements for aflatoxin surveillance in corn and soybean meal processing.
United States
Poultry integrators in Iowa and Arkansas drive quantum cascade laser spectroscopy adoption for real-time grain intake screening. FDA Food Safety Modernization Act preventive controls mandate documented hazard analysis across all registered feed facilities. Large compound feed producers in the Midwest consolidate testing volumes through third-party ISO/IEC 17025 laboratories to satisfy regulatory documentation burdens.
Germany
European compound feed manufacturers prioritize chromatography platforms bundling method development with consumable replenishment contracts. EU Regulation 2023/915 on maximum contaminant levels mandates laboratory upgrades for aflatoxin and fumonisin detection. Industrial clusters in Lower Saxony and Bavaria concentrate premium instrument procurement as exporters face stricter residue limits for EU market access.
Brazil
Soybean meal processors in São Paulo and Paraná expand PCR-based pathogen detection to satisfy ANVISA alignment with Codex Alimentarius export standards. The country's national agricultural regulator enforces microbiological criteria for feed ingredients bound for European and Asian markets. Integrated poultry operations in the southeastern processing belt absorb capital costs for same-day Salmonella verification workflows.
China
Domestic feed safety equipment demand concentrates in Shandong and Jiangsu provinces as livestock producers face stricter mycotoxin surveillance under national food safety standards. The State Administration for Market Regulation mandates contaminant testing frequencies for corn and wheat imports. Large agribusiness groups in the Yangtze River Delta region deploy multi-residue screening platforms to protect export market access.
Netherlands
Specialized feed additive manufacturers in the Randstad region invest in broad-spectrum analytical platforms for novel ingredient safety assessment. EFSA guidance on feed additive safety assessment shapes instrument validation protocols and vendor qualification criteria. Third-party testing laboratories near Rotterdam consolidate European compound feed compliance spending under consolidated ISO/IEC 17025 accreditation frameworks.
Animal Feed Safety Testing Equipment Market Competitive Landscape
United States-based conglomerates anchor one tier; European specialists hold differentiated positions in method development services and consumable replenishment. The market structure tilts toward consolidation as integrated technology providers bundle hardware with recurring revenue streams. Three archetypes dominate: chromatography platform vendors, rapid test kit specialists, and third-party testing service consolidators. Competitive dynamics center on vertical integration into consumable supply chains and geographic expansion through distribution partnerships.
Within the integrated technology tier, Thermo Fisher Scientific exemplifies the chromatography-platform archetype through its analytical instrument portfolio. Neogen Corporation occupies a position among rapid detection specialists with calibrated immunoassay systems. Agilent Technologies represents the spectroscopy-oriented segment competing on multi-residue screening capabilities. These three anchors illustrate how vendor positioning stratifies across detection speed, sensitivity thresholds, and service bundling models.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Neogen Corporation |
| Agilent Technologies |
| SGS SA |
| Eurofins Scientific |
| Bureau Veritas |
| Intertek Group plc |
| ALS Limited |
| Mérieux NutriSciences Corporation |
| Others |
Pricing and Supply Chain Analysis
Large compound feed producers in the Midwest and Germany absorb the majority of chromatography system procurement volumes, anchoring contract-based pricing with bundled method development and consumable replenishment clauses.
Pricing Analysis
Short lead-time premiums for certified mycotoxin reference materials from European suppliers compress operational budgets at ISO/IEC 17025 laboratories facing FDA and EFSA validation deadlines. Pricing stratifies across premium, standard, and economy tiers based on detection sensitivity thresholds and after-sales service bundling. Cost compression in solvent supply chains intensifies as chromatography-grade acetonitrile price volatility feeds through to high-throughput facilities. Small and mid-sized feed mills in Wisconsin and California exhibit the highest price sensitivity, while export-facing compound feed manufacturers in the Netherlands absorb premium instrument costs to secure EU market access.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch specialty chemical suppliers for certified aflatoxin and fumonisin reference standards. Manufacturing concentration in the United States, Germany, and China feeds the global installed base of HPLC and mass spectrometry platforms. Critical dependencies include high-purity solvents, chromatography columns, and immunoassay reagents. Tariff exposure on Chinese-sourced optical components for spectroscopy systems threatens margin stability at instrument vendors. Distribution runs through authorized dealer networks and direct sales forces serving accredited third-party laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory documentation burdens under FDA preventive controls and EU Regulation 2023/915 are consolidating procurement volumes toward integrated platform vendors, squeezing standalone test kit specialists without recurring revenue streams.
For Market Incumbents: Hedge against portable detection platform displacement by acquiring cloud-connected spectroscopy capabilities or licensing quantum cascade laser technology from agricultural instrumentation startups. Lock in backward integration into consumable supply chains through captive solvent purification facilities in the United States or Germany. Defensive consolidation around ISO/IEC 17025-accredited service laboratories protects against third-party testing volume attrition. For New Entrants and Emerging Players: Near-infrared spectroscopy convergence with smartphone-based chemometric applications offers the most penetrable wedge for on-farm nutritional screening in Brazil and China. Target poultry farm quality control workflows in Iowa and Arkansas with subscription-based reagent replenishment models that bypass capital-intensive chromatography procurement. Partner with regional feed additive distributors for channel access without direct sales force buildout. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized chromatography service firms in the Netherlands and Germany with aging specialist workforces and established EFSA method validation libraries. Long-term viability hinges on consumable lock-in rates and regulatory expansion into emerging mycotoxin analytes. Monitor ANVISA alignment with Codex Alimentarius standards as the inflection signal for Brazilian export sector equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Consumable Replenishment Contracts | Recurring revenue streams from solvent and column supply lock in customer retention at ISO-accredited laboratories. |
| Portable Spectroscopy Integration | Quantum cascade laser deployment at grain elevators collapses detection turnaround from laboratory days to minutes. |
| Third-Party Laboratory Consolidation | Midwest testing volume aggregation satisfies FDA documentation burdens for small compound feed producers. |
| Method Development Service Expansion | EFSA-guided validation protocols for T-2 toxin detection differentiate European chromatography vendors. |
| Cloud-Based Chemometric Platforms | Remote model updates enable real-time nutritional deficiency screening without on-site specialist presence. |
Research Methodology
Independent corroboration across primary interviews with feed quality control directors, chromatography service laboratory managers, regulatory affairs specialists at compound feed manufacturers, and poultry farm operations executives underwrites the qualitative findings. Secondary validation draws from FDA Food Safety Modernization Act guidance documents, EFSA contaminant regulation filings, ISO/IEC 17025 accreditation databases, and customs records for analytical instrument imports. Bottom-up procurement volume estimates triangulate against top-down market sizing derived from vendor revenue disclosures and installed base modeling.
Rate-of-change decomposition across technology segments, product types, end-user categories, and geographic regulatory clusters structures the analytical framework. Segmentation dimensions include detection platform type, throughput capacity tier, and accreditation status. CAGRs derive from regression analysis of historical procurement cycles correlated with regulatory mandate implementation timelines. Feed additive safety assessment requirements and emerging mycotoxin surveillance expansion inform industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including hypothetical regulatory rollback of FDA preventive controls, breakthrough displacement of chromatography by biosensor platforms, and sustained commodity price collapse in corn and soybean markets. Deviation in EFSA maximum residue limit expansion timelines or ANVISA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Traceability Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Allergen Testing Market
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
Vitamin Test Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Food Tester Market