
 North America Specialty Coffee Market | 2026-2036
North America Specialty Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
North America Specialty Coffee Market Insights
A wide capital-intensity divergence between small-batch roasters and scaled operations is rotating competitive dynamics across the North America specialty coffee landscape. Stumptown Coffee Roasters leverages its Portland roots and direct-trade sourcing to sustain premium positioning in wholesale channels. Blue Bottle Coffee anchors its growth through meticulous in-house roasting protocols and tightly controlled retail footprints in coastal metros. Intelligentsia Coffee Roasters differentiates via its Black Cat Espresso program and barista training academies that reinforce brand authority.
Specialty coffee comprises arabica-dominant beans scoring eighty points or above on the Specialty Coffee Association cupping protocol, processed through washed, natural, or honey methods to preserve terroir-specific acidity and aromatics. The primary commercial purpose centers on delivering traceable, high-sensory experiences that command price premiums over commodity-grade alternatives. Whole bean and light roast segments lead margin pools as consumers invest in home grinding equipment and prefer brighter, origin-distinct profiles. Pods and instant formats compete on convenience but occupy lower per-gram value tiers despite faster volume growth in office and travel contexts.
The FDA oversees food safety and labeling standards for roasted coffee products across the United States, while the USDA administers organic certification pathways that shape premium positioning and consumer trust. California's Proposition 65 warnings on acrylamide exposure have compelled roasters to refine dark roast protocols and strengthen supply-chain documentation. Stakeholders must monitor how state-level climate disclosure rules and evolving organic integrity enforcement reshape sourcing economics and roasting investment decisions.
Market Dynamics
Single-origin traceability requirements and cold brew processing patents are concentrating capital among roasters capable of vertical quality control, compressing margins for commodity-dependent intermediaries.
Growth Catalysts
- California Proposition 65 compliance:Roasters investing in acrylamide mitigation protocols gain shelf-access advantages in the largest US state market, forcing competitors to upgrade roasting infrastructure.
- Pacific Northwest roasting clusters:Density of third-wave cafés in Portland and Seattle creates knowledge spillovers that accelerate barista training standardization and equipment innovation cycles.
- Nitrogen-infusion equipment:Draft-system manufacturers are retrofitting café infrastructure to support on-tap cold brew, expanding format accessibility beyond bottled alternatives.
Market Restraints
- Arabica price volatility:Weather shocks in Colombian and Brazilian highlands transmit directly to North American roasting cost structures, squeezing light-roast specialists with limited hedging capacity.
- Organic certification backlog:USDA-accredited body processing delays extend farm-to-shelf timelines by 8-14 months, constraining product launches for seasonal micro-lots.
- Substitute beverage encroachment:Functional energy drinks and adaptogenic teas capture trial occasions among 18-34 demographics, compressing specialty coffee's share of caffeine occasions.
Strategic Opportunities
- Texas metropolitan expansion:Underpenetrated Austin and Dallas-Fort Worth markets offer whitespace for roasting facilities serving 7+ million consumers with limited third-wave density.
- Office channel nitro systems:Corporate foodservice distributors are piloting keg-exchange programs that bypass traditional café retail entirely.
- USDA organic integrity enforcement:Strengthened supply-chain documentation requirements favor roasters with existing direct-trade relationships, creating regulatory moats against late entrants.
Industry Challenges
- Q-grading talent scarcity:Certified cuppers command premium wages in Portland and San Francisco, forcing regional roasters to outsource quality control or accept inconsistent scoring.
- Legacy roasting equipment integration:Probat and Diedrich system retrofits for emission compliance require six-figure capital commitments that strain mid-tier operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Specialty Coffee Market |
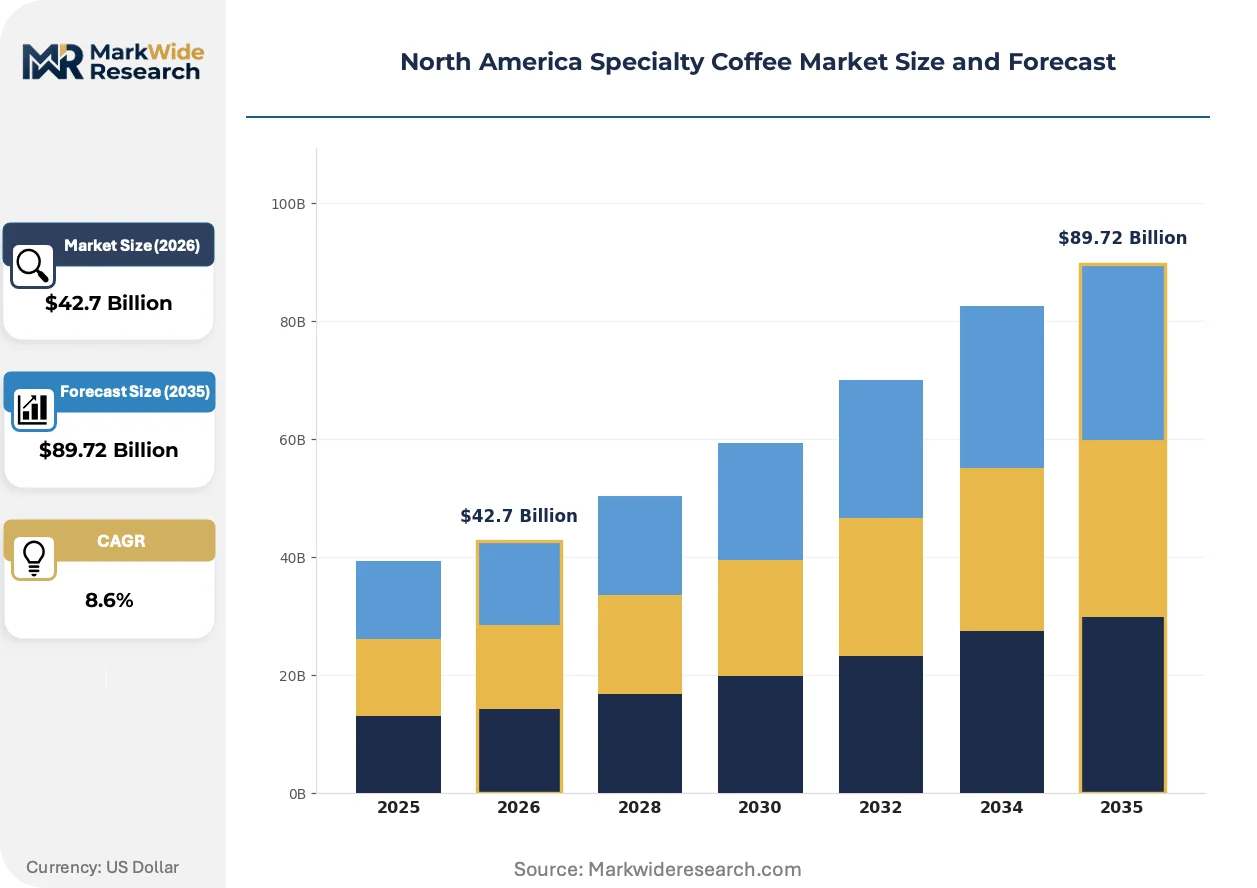
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Bean, Ground, Instant, Pods End User: Households, Cafés, Restaurants, Offices Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Roast Level: Light, Medium, Dark, Flavored |
| Companies Covered | Counter Culture Coffee, Onyx Coffee Lab, Blue Bottle Coffee, Mostra Coffee Roasters, Sey Coffee, Stumptown Coffee Roasters, Verve Coffee Roasters, Bird Rock Coffee Roasters, Intelligentsia Coffee Roasters, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Specialty Coffee Market Trends and Innovations
Cold extraction methods and precision fermentation are fragmenting traditional roast-centric value chains, enabling new entrants to bypass conventional roasting infrastructure entirely.
Precision fermentation of coffee-derived flavor compounds is decomposing the traditional farm-to-roaster supply chain. Biotech startups in California are synthesizing arabica-specific acids and aromatics for use in ready-to-drink formulations. Large beverage manufacturers are adopting these inputs to reduce agricultural procurement exposure while maintaining sensory claims.
FDA enforcement of updated Food Safety Modernization Act traceability rules is compelling roasters to deploy blockchain-enabled lot tracking. Medium-sized wholesale operations face disproportionate compliance costs relative to scaled competitors with existing ERP integration. Canadian import facilities are accelerating adoption ahead of US deadlines to secure cross-border shipping advantages.
Home grinding equipment penetration has shifted bulk purchasing patterns toward whole-bean formats. Specialty retailers are responding with subscription models that displace traditional grocery velocity. This rotation is most pronounced in Pacific Northwest urban markets where equipment ownership exceeds national averages by substantial margins.
North America Specialty Coffee Market Segmentation
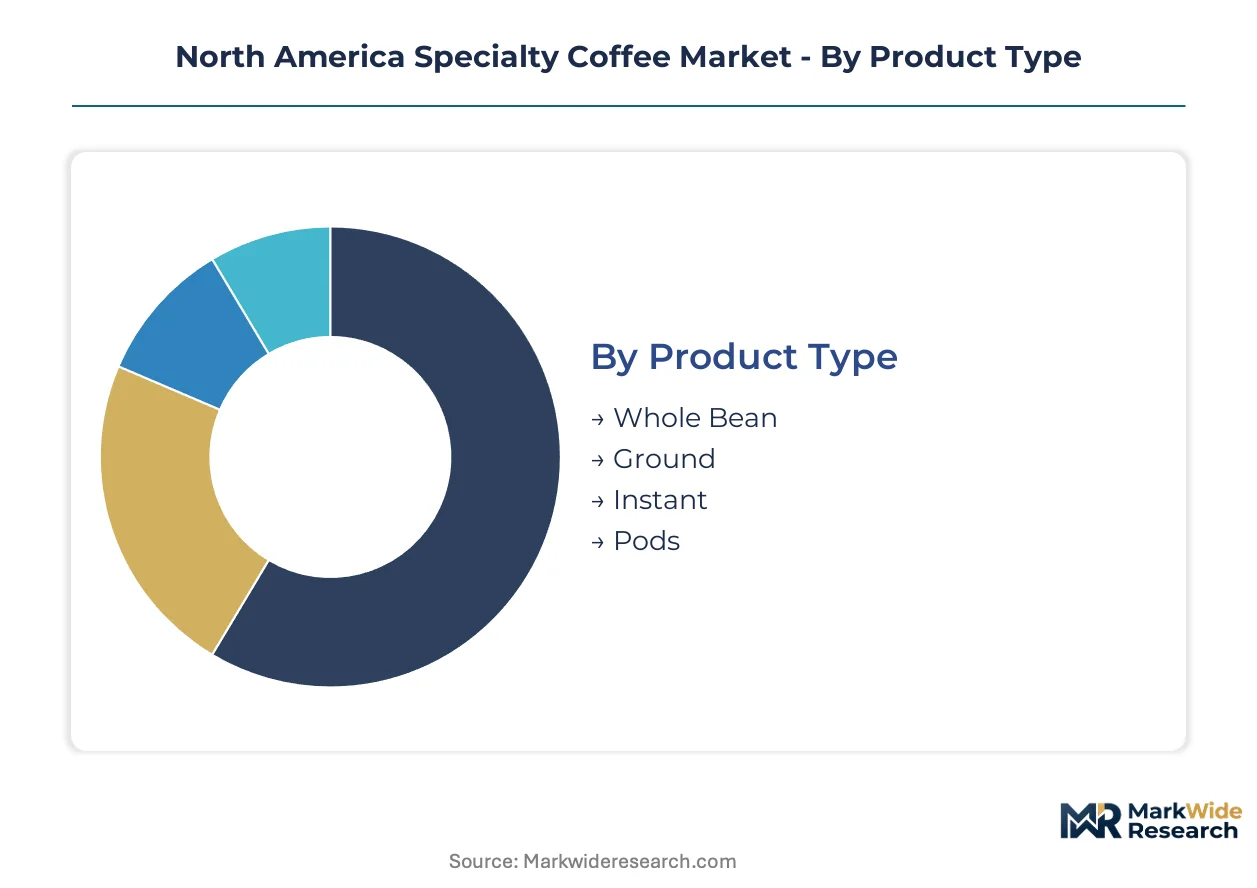
Specialty coffee segmentation reflects divergent margin structures across preparation formats and procurement channels. Roasters calibrate SKU portfolios across these dimensions to capture price premiums while managing FDA labeling compliance and state-level acrylamide disclosure requirements.
Product Type:
FDA nutritional labeling exemptions for whole bean products create regulatory differentiation that shapes competitive positioning across formats.
- Whole Bean:Unprocessed arabica requiring home grinding equipment, commanding highest per-gram margins. California and Pacific Northwest households with burr grinder penetration above national averages drive sustained volume concentration despite equipment cost barriers.
- Ground:Pre-milled specialty coffee optimized for drip and pour-over preparation methods. Convenience-focused households in Texas metropolitan areas represent expanding demand as roasting facilities establish Dallas-Austin distribution corridors.
- Instant:Soluble arabica extracts processed through freeze-drying or spray-drying methods. Travel and office contexts in under-café'd secondary cities sustain niche positioning.
- Pods:Single-serve aluminum or compostable capsules compatible with proprietary brewing systems. Corporate foodservice channels in Austin and Dallas-Fort Worth pilot keg-exchange bypass programs that threaten traditional pod velocity.
Established volume favors Whole Bean; emerging adoption favors Pods.
End User:
Customer procurement scale determines roasting contract structures and quality protocol stringency.
- Households:Individual consumers purchasing through retail or subscription channels. Home grinding equipment ownership in Pacific Northwest urban markets exceeds national benchmarks, rotating bulk purchasing toward whole-bean formats and displacing traditional grocery velocity.
- Cafés:Third-wave coffee shops emphasizing single-origin traceability and barista-crafted preparation. Portland and Seattle density creates knowledge spillovers accelerating equipment innovation and training standardization cycles.
- Restaurants:Full-service and fast-casual dining operations integrating specialty coffee into beverage programs. Post-pandemic labor constraints compress on-premise grinding capacity, favoring pre-ground or nitro-keg solutions.
- Offices:Corporate campuses and coworking facilities provisioning employee caffeine occasions. Nitrogen-infusion draft systems are retrofitting breakroom infrastructure, expanding format accessibility beyond bottled alternatives.
Direct-trade relationships anchor Cafés; standardization pressures concentrate in Offices.
Distribution Channel:
Channel selection dictates cold chain requirements and traceability documentation burdens.
- Online Retail:Direct-to-consumer subscription platforms and marketplace storefronts. Whole-bean subscription models displace traditional grocery velocity most pronouncedly in Pacific Northwest urban markets.
- Supermarkets:Mass-market grocery and club store shelf placement requiring Proposition 65 compliance documentation. California shelf-access advantages accrue to roasters with acrylamide mitigation protocols.
- Specialty Stores:Dedicated coffee retailers and equipment showrooms emphasizing origin storytelling and brewing education. Barista training academies reinforce brand authority and justify price premiums.
- Wholesale:Business-to-business supply to cafés, restaurants, and institutional foodservice. Stumptown leverages Portland roots and direct-trade sourcing to sustain premium positioning in this channel.
Margin concentration sits with Specialty Stores; volume scale concentrates in Wholesale.
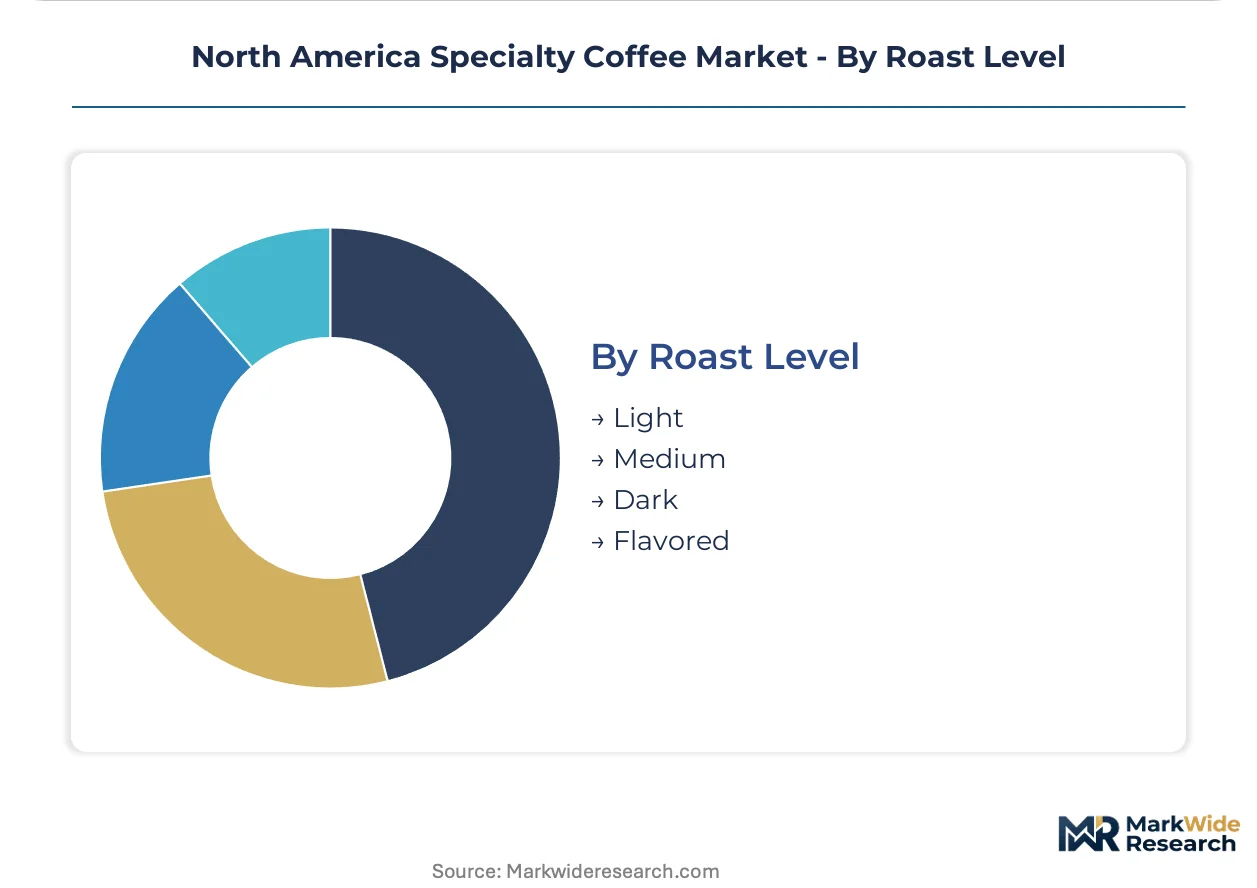
Roast Level:
Degree of thermal processing determines acrylamide formation thresholds and organic certification integrity risks.
- Light:Minimal roasting preserving terroir-specific acidity and origin aromatics. USDA organic certification backlogs constrain seasonal micro-lot launches for specialists with limited hedging capacity against arabica price volatility.
- Medium:Balanced development targeting broader palate accessibility while retaining traceability claims. Texas metropolitan expansion offers whitespace for roasting facilities serving consumers with limited third-wave density.
- Dark:Extended roasting reducing acidity and emphasizing body through Maillard reaction products. California Proposition 65 warnings compelled infrastructure upgrades that strain mid-tier operations with legacy Probat and Diedrich systems.
- Flavored:Post-roast infusion of natural or synthetic flavor compounds. FDA food safety modernization traceability rules compel blockchain-enabled lot tracking with disproportionate compliance costs for medium-sized operations.
Light roasts command price premiums; Dark roasts face regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest roasting clusters command price premiums through direct-trade sourcing density, while Texas metropolitan markets absorb volume growth from underpenetrated third-wave café expansion.
United States
California households with burr grinder penetration above national averages sustain whole-bean demand concentration. FDA food safety modernization traceability rules compel blockchain-enabled lot tracking with disproportionate compliance costs for medium-sized wholesale operations. Los Angeles and San Francisco roasting clusters anchor premium positioning through barista training academies and origin storytelling infrastructure.
Canada
Toronto and Vancouver cafés drive single-origin traceability requirements through consumer education investments. Health Canada import facility standards accelerate adoption of lot-tracking systems ahead of US deadlines to secure cross-border shipping advantages. Montreal roasting operations leverage Quebec's specialty retail density to test nitrogen-infusion draft systems for office channel expansion.
Mexico
Mexico City metropolitan cafés absorb micro-lot volumes from Chiapas and Oaxaca highland cooperatives. The country's national food safety regulator enforces labeling standards that shape organic certification integrity for cross-border specialty exports. Guadalajara roasting facilities serve central Mexico's emerging third-wave density with medium-roast protocols calibrated to broader palate accessibility.
Pacific Northwest
Portland and Seattle knowledge spillovers accelerate equipment innovation cycles and barista training standardization. Oregon and Washington state climate disclosure rules reshape sourcing economics for roasters with direct-trade relationships. Seattle roasting clusters concentrate Q-grading talent, forcing regional competitors to outsource quality control or accept inconsistent cupping scores.
Texas
Austin and Dallas-Fort Worth whitespace offers roasting facility expansion serving seven million consumers with limited third-wave density. Texas metropolitan labor markets absorb cold brew processing talent from coastal migration. Houston distribution corridors connect to Gulf Coast import infrastructure, reducing farm-to-roaster timelines for Brazilian and Colombian arabica shipments.
North America Specialty Coffee Market Competitive Landscape
Concentration sits with scaled roasters possessing direct-trade sourcing infrastructure and proprietary cold brew processing patents. Mid-tier operations face margin compression from arabica price volatility and legacy equipment retrofit costs for emission compliance. Two strategic archetypes dominate: Portland-rooted wholesale specialists leveraging Pacific Northwest roasting cluster density, and California-based retail operators controlling tightly curated metropolitan footprints. Competitive moves center on M&A consolidation of regional roasting facilities and strategic partnerships with nitrogen-infusion equipment manufacturers for office channel bypass programs.
Within the wholesale-specialist tier, Stumptown Coffee Roasters and Intelligentsia Coffee Roasters exemplify archetypes built on direct-trade sourcing and barista training academies. Blue Bottle Coffee occupies a position representing California-based retail density through meticulously controlled coastal metropolitan footprints. Counter Culture Coffee and Onyx Coffee Lab sit within the regional roasting cluster model, leveraging geographic origin to sustain premium positioning in underpenetrated Texas and Southeast markets.
| Leading Market Players |
|---|
| Counter Culture Coffee |
| Onyx Coffee Lab |
| Blue Bottle Coffee |
| Mostra Coffee Roasters |
| Sey Coffee |
| Stumptown Coffee Roasters |
| Verve Coffee Roasters |
| Bird Rock Coffee Roasters |
| Intelligentsia Coffee Roasters |
| Others |
Pricing and Supply Chain Analysis
USDA organic certification pathways gate both supply qualification and price differentiation simultaneously, forcing roasters to absorb 8-14 month farm-to-shelf timelines or forfeit premium positioning in California and Pacific Northwest retail channels. This regulatory chokepoint compresses margins for operators lacking direct-trade relationships while amplifying price premiums for certified micro-lot offerings.
Pricing Analysis
The customization-premium spread between direct-trade single-origin lots and standard wholesale blends exceeds threefold at the roasting tier. Subscription models and micro-lot auctions anchor the premium structure, while commodity-indexed contracts dominate foodservice procurement. Price differentiation hinges on cupping scores above 85 points and organic certification integrity. Cost compression in dark-roast segments is intensifying because Proposition 65 compliance upgrades strain legacy equipment operators. Office channel buyers exhibit highest price sensitivity; third-wave cafés demonstrate lowest sensitivity due to origin storytelling requirements.
Supply Chain Analysis
Inventory-strategy preferences bifurcate between Pacific Northwest just-in-time roasting clusters and Texas strategic stockpiling for metropolitan expansion. Raw arabica draws from Colombia, Brazil, and Guatemala highland cooperatives. Green coffee sourcing rests on Q-grading talent scarcity in Portland and San Francisco. Single-source vulnerability concentrates in Colombian weather-exposed harvests. Distribution runs through direct-trade relationships for premium tiers and commodity intermediaries for standard blends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arabica price cyclicality is driving recovery dynamics as Brazilian and Colombian harvest shocks transmit through roasting cost structures. Inventory restocking and certification backlogs create temporary margin windows for prepared operators.
For Market Incumbents: Consolidate regional roasting facilities in underpenetrated Texas corridors to capture Austin and Dallas-Fort Worth whitespace. Acquire nitrogen-infusion equipment manufacturers to lock office channel bypass programs before corporate foodservice distributors scale keg-exchange pilots. Functional energy drink encroachment threatens caffeine occasion share; vertical integration into cold brew processing patents defends premium positioning. For New Entrants and Emerging Players: Barista training standardization gaps in secondary Texas cities offer service-layer entry points where coastal incumbents under-invest. Target medium-roast protocols calibrated to broader palate accessibility in Houston distribution corridors. Launch direct-to-office subscription models bypassing traditional café retail infrastructure entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across emission-compliant roasting equipment as Proposition 65 and FDA traceability rules compound compliance burdens. Five-to-ten year viability favors scaled operators with existing ERP integration and direct-trade sourcing infrastructure. Acquire mid-tier roasting facilities with USDA organic certification pipelines and Portland or Seattle geographic anchoring. Watch Q-grading wage inflation as inflection indicator for quality control outsourcing trends.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Trade Sourcing Consolidation | Locks micro-lot supply chains against USDA certification backlogs in Colombian and Brazilian highlands. |
| Nitrogen-Infusion Equipment Partnership | Retrofits café and office infrastructure for on-tap cold brew beyond bottled format constraints. |
| Acrylamide Mitigation Protocol Investment | Secures California shelf-access advantages under Proposition 65 disclosure requirements. |
| Texas Roasting Facility Expansion | Serves seven million consumers in Austin and Dallas-Fort Worth with limited third-wave density. |
| Blockchain-Enabled Lot Tracking Deployment | Preempts FDA Food Safety Modernization Act traceability enforcement with disproportionate compliance costs for mid-tier competitors. |
Research Methodology
Operator-level perspectives from roasting facility managers, Q-graders, café owners, and corporate foodservice procurement directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA labeling guidance documents, USDA organic certification databases, and California Office of Environmental Health Hazard Assessment Proposition 65 determinations. Bottom-up volume triangulation across product format segments reconciled with top-down market sizing from trade flow data and roasting capacity disclosures.
Sensitivity analysis tested arabica price volatility scenarios and certification timeline delays across the projection horizon. Segmentation dimensions modeled include preparation format, end-user procurement scale, distribution channel cold chain requirements, and roast-level acrylamide formation thresholds. CAGRs derived from historical volume trajectories and elasticity-adjusted price assumptions. Forecast inputs incorporated Pacific Northwest equipment penetration rates and Texas metropolitan population migration patterns.
Forecasts assume regulatory continuity in FDA food safety modernization and USDA organic integrity enforcement; material policy shifts would require re-modeling. Arabica futures volatility and Q-grading labor market tightness represent primary revision triggers. Revision becomes warranted when Colombian or Brazilian harvest shocks exceed historical variance bands or when organic certification processing delays extend beyond current 8-14 month baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Grinder Market
Coffee
Sparkling Coffee Market
Coffee
Espresso Powder Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Global Nespresso Capsules Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Smart Coffee Maker Market
Coffee
Coffee Capsules Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Reusable Coffee Cup Market
Coffee
Green Coffee Bean Extract Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Coffee Pods and Capsules Market
Coffee
South America Coffee Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Ready to Drink (RTD) Coffee Market