
 Office Coffee Service (OCS) Market | 2026-2036
Office Coffee Service (OCS) Market Size, Share, and Industry Trends Forecast 2026-2036
Office Coffee Service (OCS) Market Analytics
ISO 22000 food safety management certification is rotating vendor eligibility across the Office Coffee Service landscape, filtering out smaller operators lacking documented hazard controls. Lavazza leverages its integrated roasting network to secure supply consistency for high-volume contracts. Sodexo anchors its competitive stance through facility-wide beverage management programs that bundle coffee with pantry services. Farmer Bros. Co. specializes in regional roasting proximity, shortening delivery windows for freshness-sensitive accounts.
Office Coffee Service encompasses the provision of brewed coffee, related equipment, and replenishment logistics to commercial workplaces, typically involving machines rated for 50 to 500+ daily servings with water-line or reservoir-fed brewing systems. The primary commercial purpose centers on sustaining employee productivity and satisfaction while externalizing beverage procurement overhead to specialized operators. Pod-based systems currently occupy the largest product type share due to portion control and minimal cleaning requirements, though traditional whole-bean equipment is gaining traction among employers prioritizing sustainability credentials. Subscription service models now dominate service type revenue streams, locking in predictable recurring income for providers and simplifying budget forecasting for facilities managers.
FDA food facility registration requirements govern imported coffee and flavoring additives entering the US market, while EU REACH regulations constrain chemical migration limits from plastic pod materials into hot beverages. The EU Green Deal extends producer responsibility mandates toward packaging recyclability, pressuring manufacturers toward aluminum or compostable pod alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to absorb compliance costs or pass them through contract renegotiations.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are forcing rapid equipment and packaging reconfiguration across workplace beverage supply chains, compressing refresh cycles and rewiring procurement evaluation criteria.
Growth Catalysts
- REACH chemical migration limits:Aluminum pod alternatives gain traction as ECHA thresholds tighten on plastic hot-contact materials, accelerating equipment replacement demand.
- Bean-to-cup automation:Corporate facilities prioritize whole-brew systems with integrated grinders to eliminate single-use packaging waste entirely.
- Germany workplace culture:Equipment refresh cycles concentrate in German metropolitan clusters where employer-funded coffee remains a standard benefit.
Market Restraints
- Arabica price volatility:Weather-driven harvest fluctuations in Brazilian and Colombian highlands compress operator margins during contract lock-in periods.
- Roasting capacity concentration:Regional supply dependence on a limited network of mid-scale roasting facilities creates fulfillment vulnerability for freshness-guaranteed contracts.
- Water infrastructure heterogeneity:Variable building plumbing standards across aged European office stock limit universal machine deployment without costly retrofit.
Strategic Opportunities
- Compostable pod certification:Early alignment with evolving EU packaging recyclability standards creates first-mover positioning ahead of mandated phase-outs.
- Pantry service bundling:Coffee-plus-snack consolidated procurement contracts reduce vendor management overhead for multi-site facility operators.
- IoT-enabled predictive maintenance:Sensor-integrated brewing equipment allows remote diagnostics and automated replenishment triggering.
Industry Challenges
- ISO 22000 documentation burden:Smaller regional operators lack resources to maintain hazard analysis critical control point systems required for large-account eligibility.
- Legacy equipment interoperability:Retrofitting connected monitoring systems onto reservoir-fed machines installed pre-2020 demands hardware modification expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Office Coffee Service (OCS) Market |
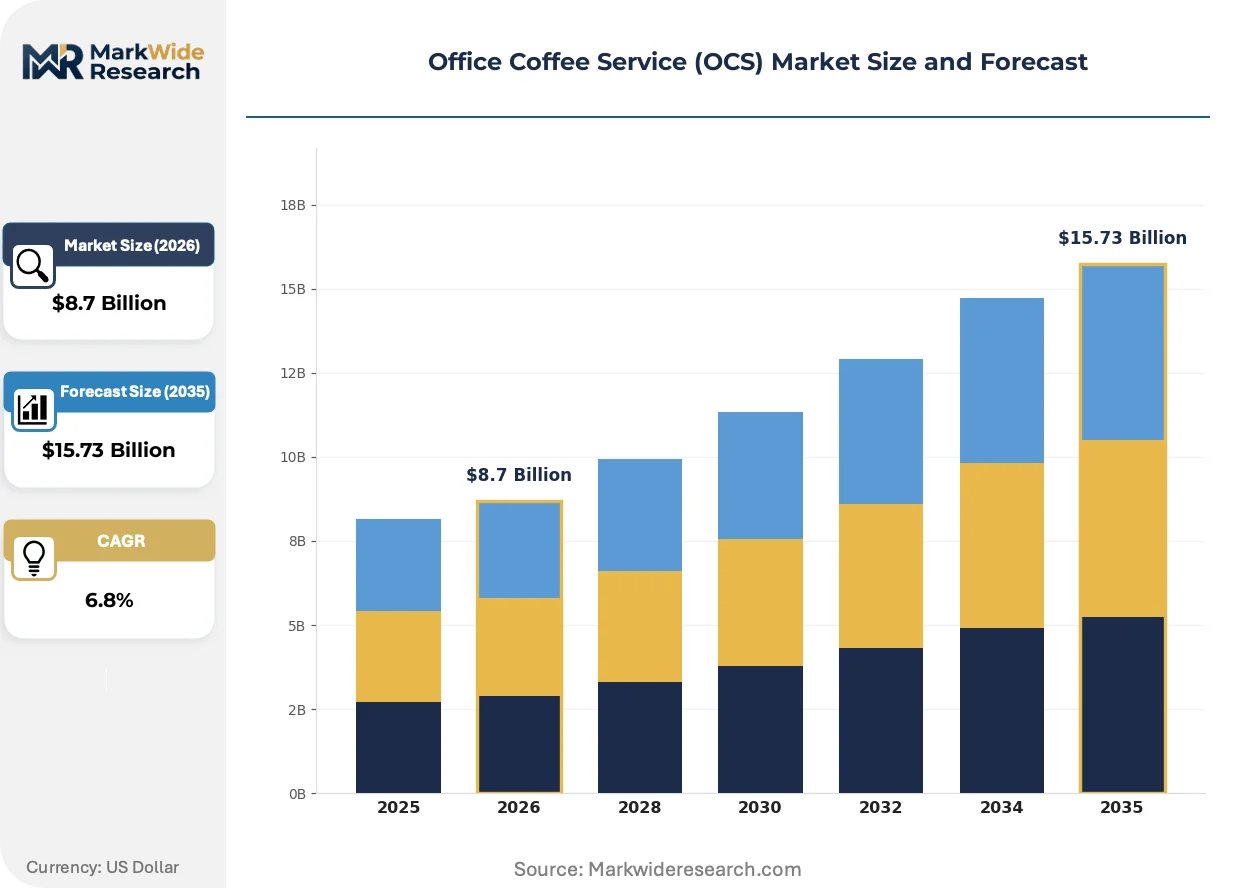
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee Machines, Pods, Traditional Coffee, Instant Coffee Distribution Channel: Direct Sales, Online Retail, Wholesale, Franchising Service Type: Subscription Service, On-Demand Supply, Maintenance Service, Equipment Rental End User: Corporate Offices, Hospitality Industry, Educational Institutions, Healthcare Facilities |
| Companies Covered | Lavazza, Aramark, Nestlé, Sodexo, Compass Group, Starbucks, Farmer Bros. Co., Bunn-O-Matic Corporation, Keurig Dr Pepper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Office Coffee Service (OCS) Market Evolving Landscape
Connected brewing infrastructure and sustainable packaging alternatives are actively rewiring competitive positioning, while procurement evaluation criteria pivot from unit economics toward lifecycle compliance and employee experience metrics.
Modular bean-to-cup systems with swappable flavor cartridges is fragmenting the traditional split between pod convenience and whole-bean quality. Mid-size corporate campuses in the Netherlands and Scandinavia are piloting these hybrid configurations during 2025 equipment refresh windows. The technology is fragmenting vendor specialization boundaries, forcing traditional roasters and equipment OEMs into direct service competition.
EU Green Deal packaging recyclability mandates are accelerating aluminum and industrially-compostable pod material transitions ahead of statutory deadlines. Roasting operators face capital allocation decisions between retrofitting existing filling lines or outsourcing to certified third-party packagers. German and French facility managers report contract renegotiation leverage as they demand verified end-of-life processing documentation.
Subscription-based replenishment with usage-based billing is displacing traditional purchase-order procurement in multi-location corporate accounts. Facilities management platforms are consolidating coffee spend with other consumables under single-source vendor arrangements. This consolidation pattern is most visible in UK and Irish professional services firms with distributed office networks.
Office Coffee Service (OCS) Market Segmentation
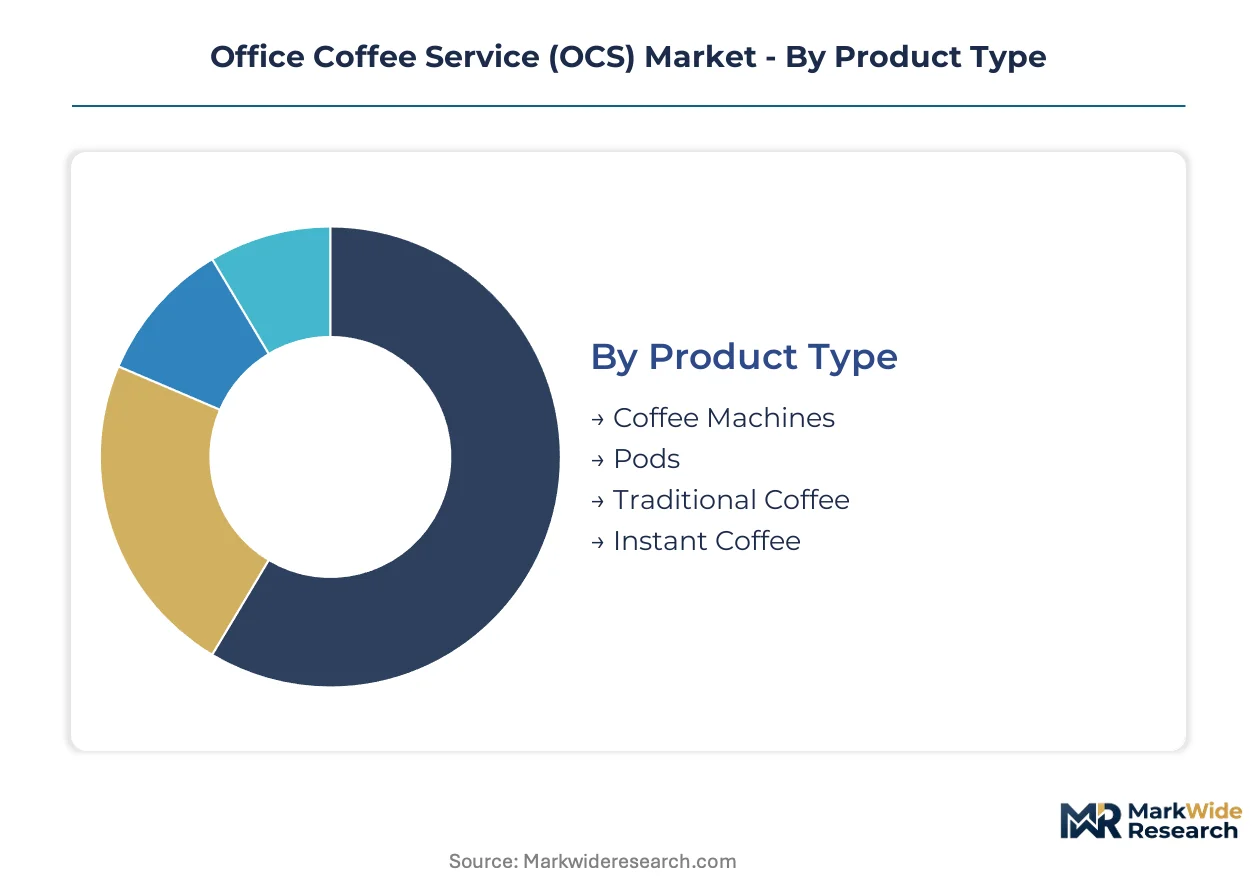
Office Coffee Service segmentation reveals divergent margin profiles across equipment ownership models and procurement channels. Understanding these structural differences enables targeted resource allocation for vendors navigating the shift from transactional sales toward recurring service relationships.
Product Type:
Pods command the widest gross margins through proprietary format lock-in, while bean-to-cup systems generate superior lifetime value via consumable attachment rates.
- Pods:Single-serve aluminum or plastic capsules designed for proprietary brewing systems with portion-controlled dosing. German corporate campuses and UK professional services firms drive replacement demand as ECHA migration limits accelerate format transitions away from legacy plastics.
- Coffee Machines:Water-line or reservoir-fed brewing equipment rated for 50 to 500+ daily servings, encompassing automatic, semi-automatic, and manual configurations. Bean-to-cup configurations with integrated grinders are expanding most quickly in Dutch and Scandinavian office clusters seeking packaging waste elimination.
- Traditional Coffee:Whole-bean or pre-ground bulk coffee prepared through batch brewing systems without single-use containment.
- Instant Coffee:Soluble coffee granules requiring only hot water dispensing infrastructure for preparation.
The dominant share belongs to Pods, while Coffee Machines are closing the gap fastest.
Distribution Channel:
Channel economics vary sharply by customer scale, with direct sales capturing enterprise accounts and online retail penetrating sub-50-employee installations.
- Direct Sales:Field-based account executives managing multi-year contracts with integrated equipment and replenishment provisioning. Corporate headquarters in Frankfurt, London, and Paris concentrate procurement authority for pan-European facility networks.
- Wholesale:Third-party distribution through foodservice intermediaries supplying independent roasters and regional equipment dealers.
- Online Retail:E-commerce platforms enabling self-service procurement for smaller offices with standardized equipment requirements.
- Franchising:Licensed operator networks delivering localized service coverage under national brand standards.
Direct Sales retains the largest revenue concentration, though Online Retail is gaining share fastest among sub-100-employee segments.
Service Type:
Revenue predictability distinguishes subscription models from transactional alternatives, reshaping vendor cash flow profiles and customer switching costs.
- Subscription Service:Fixed-fee recurring contracts covering equipment, consumables, and preventive maintenance with predictable monthly billing. UK and Irish distributed office networks favor consolidated single-source arrangements bundling coffee with pantry services.
- Maintenance Service:Reactive and scheduled technical support contracts for equipment owned or leased by end users.
- Equipment Rental:Operating lease structures transferring capital burden from facilities to service providers.
- On-Demand Supply:Purchase-order-based replenishment without contractual volume commitments.
Subscription Service holds the leading position, while Maintenance Service is expanding most quickly as installed bases of connected equipment mature.
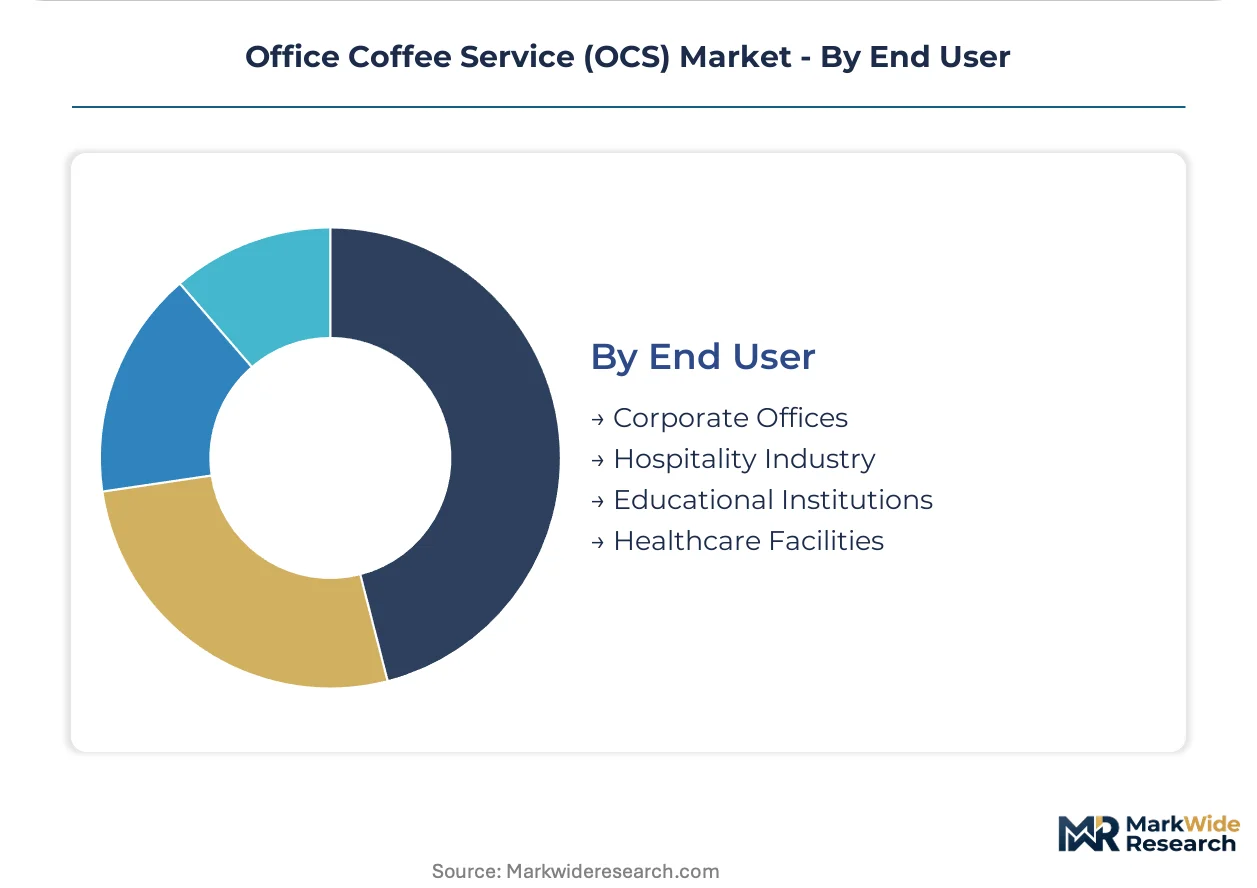
End User:
Per-employee consumption intensity and contract sophistication vary dramatically across workplace environments, from high-volume corporate settings to regulated healthcare applications.
- Corporate Offices:Employer-funded beverage programs sustaining productivity in professional workplace environments. German metropolitan clusters exhibit the shortest equipment refresh cycles where coffee provision remains a standard employment benefit.
- Hospitality Industry:Hotels and conference centers requiring front-of-house quality presentation with back-of-house operational efficiency.
- Healthcare Facilities:Hospitals and clinics with stringent hygiene protocols and 24-hour operational requirements.
- Educational Institutions:Universities and research campuses with seasonal demand fluctuation and decentralized procurement authority.
Corporate Offices command the dominant share, while Healthcare Facilities are climbing the fastest as patient experience investments extend to waiting area amenities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers in Germany, the United Kingdom, and the Netherlands drive the shortest equipment refresh cycles as employer-funded coffee programs remain standard workplace benefits. Procurement authority concentrates in metropolitan clusters where sustainability mandates and productivity investments intersect.
Germany
Frankfurt and Munich corporate campuses prioritize bean-to-cup systems to eliminate single-use packaging waste. The EU Green Deal's extended producer responsibility mandates force rapid transitions toward aluminum and compostable pod alternatives. Equipment refresh cycles in Berlin-Brandenburg accelerate as facilities managers demand verified end-of-life processing documentation.
United Kingdom
London professional services firms consolidate coffee procurement with pantry services under single-source subscription contracts. UK REACH regulations align with ECHA chemical migration thresholds, pressuring plastic pod phase-outs. Distributed office networks in Manchester and Birmingham favor usage-based billing models that simplify multi-location budget forecasting.
Netherlands
Amsterdam and Rotterdam mid-size campuses pilot modular brewing systems with swappable flavor cartridges. Dutch environmental regulations enforce strict packaging recyclability standards ahead of EU-wide deadlines. Randstad region facility operators report contract renegotiation leverage as they mandate compostable pod certification from service providers.
France
Paris headquarters concentrate pan-European procurement authority for corporate facility networks. ANSM oversight of food contact materials complements EU-level chemical migration limits. Île-de-France employers expand whole-bean equipment deployment to satisfy employee experience metrics alongside sustainability credentials.
United States
New York and Chicago corporate offices anchor North American demand for premium bean-to-cup automation. FDA food facility registration requirements govern imported coffee and flavoring additives entering the supply chain. Pacific Northwest technology employers drive connected brewing infrastructure adoption with IoT-enabled predictive maintenance requirements.
Office Coffee Service (OCS) Market Competitive Landscape
Player mix skews toward integrated foodservice operators and specialized roasting networks with regional proximity advantages. Market structure exhibits moderate consolidation around facility-wide beverage management providers. Two strategic archetypes dominate: multinational contract caterers bundling coffee with pantry services, and regional roasters competing on freshness guarantees through shortened delivery windows. Competitive moves center on strategic partnerships for compostable pod certification and portfolio diversification into connected equipment platforms.
Within the integrated foodservice tier, Sodexo and Compass Group exemplify facility-wide beverage management archetypes that consolidate procurement overhead for multi-site operators. Lavazza anchors the roasting-specialist position through supply consistency secured via integrated production networks. Farmer Bros. Co. occupies a regional proximity niche, representing operators who compete on delivery window compression for freshness-sensitive accounts.
| Leading Market Players |
|---|
| Lavazza |
| Aramark |
| Nestlé |
| Sodexo |
| Compass Group |
| Starbucks |
| Farmer Bros. Co. |
| Bunn-O-Matic Corporation |
| Keurig Dr Pepper |
| Others |
Value Network & Pricing Analysis
Subscription contracts with take-or-pay volume commitments lock in multi-year supply access for roasting operators while anchoring price visibility against arabica futures volatility. German facility managers leverage these structures to secure equipment refresh budgets against EU Green Deal compliance cost uncertainty.
Pricing Analysis
Cost-plus contracts indexed to Intercontinental Exchange arabica futures dominate large-account procurement, with adjustments for ISO 22000 certification tier and regional delivery radius. Three-tier pricing structure across premium, standard, and economy levels separates bean-to-cup installations from pod-based systems and instant coffee provisioning. Pricing pressure stems from roasting capacity concentration in Brazil and Colombia compressing operator margins during contract lock-in periods. Sub-100-employee offices exhibit highest price sensitivity, while corporate headquarters in Frankfurt and London prioritize sustainability credentials over unit cost.
Supply Chain Analysis
Container availability constraints on Santos-Hamburg and Santos-Rotterdam trade lanes intermittently extend green coffee delivery windows for European roasters. Supply concentrates in Brazil, Colombia, and Vietnam for arabica and robusta sourcing, with mid-scale roasting facilities in Germany, Italy, and the Netherlands processing for regional distribution. The chain draws from water filtration components, brewing equipment assemblies, and compostable pod materials as critical inputs. Single-source vulnerability sits with Brazilian harvest weather exposure. Distribution runs through direct sales forces for enterprise accounts, supplemented by foodservice intermediaries for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Office Coffee Service market builds defensive moats through regulatory entrenchment, where ISO 22000 certification requirements and EU Green Deal compliance create switching costs that cement incumbent positions.
For Market Incumbents: Shield market share by accelerating compostable pod certification ahead of mandated EU phase-outs, locking in contract renewal preference among sustainability-focused facility managers. Deepen backward integration into regional roasting capacity to compress delivery windows for freshness-guaranteed accounts. Prioritize IoT-enabled equipment platforms to raise replacement costs for customers evaluating vendor switches.
For New Entrants and Emerging Players: Anchor in the UK and Irish distributed office networks where subscription service consolidation creates white-space for specialized pantry bundling. Target sub-100-employee segments through online retail channels with standardized bean-to-cup configurations. Lead with usage-based billing models that simplify budget forecasting for multi-location professional services firms.
For Investors and Strategic Acquirers: Regional roasting specialists with integrated quality control systems represent the most compelling acquisition archetype, offering freshness proximity advantages that multinational caterers cannot replicate internally. Long-term viability hinges on positioning ahead of aluminum and compostable pod format transitions. Monitor ECHA chemical migration threshold announcements as inflection indicators for equipment replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Pod Certification | Early alignment with EU Green Deal mandates secures first-mover positioning ahead of statutory phase-outs. |
| IoT Equipment Platform Integration | Sensor-enabled predictive maintenance raises customer switching costs and enables usage-based billing models. |
| Pantry Service Bundling | Consolidated procurement contracts reduce vendor management overhead for multi-site facility operators. |
| Regional Roasting Capacity Expansion | Proximity roasting shortens delivery windows for freshness-sensitive accounts in metropolitan clusters. |
| Direct Sales Channel Investment | Field-based account executives capture multi-year enterprise contracts with integrated equipment provisioning. |
Research Methodology
Desk research of trade association filings, customs records, and regulatory databases preceded structured interviews with facilities management directors, roasting operation heads, equipment OEM product managers, and foodservice procurement leads. Primary fieldwork captured contract structuring practices and refresh cycle timing across German, UK, and Dutch corporate campuses. Secondary validation drew from EU Green Deal implementation guidance, ECHA technical dossiers, and ISO 22000 certification registries. Bottom-up account sizing triangulated against top-down market value estimates.
Variance decomposition across product type, distribution channel, service type, and end-use segments shaped the analytical framework over the projection horizon. Modeled dimensions encompassed equipment ownership models, procurement channel economics, and regional regulatory clusters. CAGRs derived from segment-level volume trajectories weighted by pricing tier mix. Forecast inputs incorporated arabica futures curve assumptions and EU packaging recyclability mandate implementation schedules.
Material uncertainties — weather-driven harvest fluctuations, ECHA threshold revisions, and logistics disruption recurrence — sit outside the modeled envelope. Forecasts reflect assumptions about contract renewal rates and equipment replacement timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Latin America Coffee Market
Coffee
Mushroom Coffee Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Australia Coffee Market
Coffee
Global Professional Coffee Machine Market
Coffee
Coffee Extracts Market
Coffee
Instant Coffee Market
Coffee
Oceania Coffee Market
Coffee
Coffee Decoction Maker Market
Coffee
Cold Brew Coffee Pots Market
Coffee
Adaptogen Coffee Market
Coffee
Coffee Roaster Machine Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
United States Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market