
 Cold Brew Coffee Market | 2026-2036
Cold Brew Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Brew Coffee Market Analysis
The gap between premium single-origin cold brew and mass-market commodity offerings is recalibrating how manufacturers allocate roasting and extraction capacity. Starbucks Corporation leverages its retail footprint to push ready-to-drink formats through grocery and cafe channels simultaneously. Nestlé S.A. anchors its position through concentrated production platforms that supply both branded and private-label customers. Califia Farms differentiates via plant-based formulation expertise that commands shelf-space premiums in specialty retail.
Cold brew coffee denotes coffee extracted with room-temperature or chilled water over 12–24 hours, yielding lower acidity and higher caffeine concentration per ounce than hot-brewed equivalents. The process requires coarse grinding, filtered water systems, and refrigerated storage to preserve flavor stability and microbial safety. Ready-to-drink cans dominate value capture due to convenience positioning and extended shelf-life engineering, while concentrate formats serve food-service accounts seeking customizable beverage programs. Pods remain a nascent structural segment where margin pools are shallow because equipment compatibility and consumer education costs remain elevated.
The US FDA governs cold brew as a low-acid canned food subject to Hazard Analysis Critical Control Point protocols, while USDA organic certification shapes premium pricing tiers. The EU Food Information to Consumers Regulation mandates precise caffeine labeling that influences formulation decisions for export-bound producers. Stakeholders must monitor evolving extended-shelf-life processing technologies and shifting deposit-return legislation on single-use cans across multiple jurisdictions.
Market Dynamics
The shift from seasonal to year-round menu permanence is restructuring cold brew production economics, forcing manufacturers to invest in ambient-stable processing lines and extended-shelf-life packaging formats previously reserved for dairy and juice categories.
Growth Catalysts
- USDA Organic Certification:Premium tier pricing power in United States grocery channels rewards roasters who achieve certified supply chains, compressing the margin gap between specialty and mass-market tiers.
- Food Service Permanence:Quick-service chains and independent cafes now list cold brew as core menu infrastructure rather than limited-time offers, stabilizing concentrate offtake volumes.
- High-Pressure Processing:HPP technology extends refrigerated shelf life without thermal degradation, enabling regional brands to access national distribution.
Market Restraints
- Arabica Price Volatility:Input cost swings from Brazilian and Colombian harvest cycles compress blender margins during contract renegotiations.
- FDA HACCP Compliance Burden:Low-acid canned food classification imposes pathogen monitoring costs that disadvantage small-batch producers lacking in-house microbiology labs.
- Refrigerated Distribution Concentration:Cold chain dependency limits route-to-market options in regions with sparse temperature-controlled logistics infrastructure.
Strategic Opportunities
- Plant-Based Formulation Convergence:Oat and almond milk integration commands shelf-space premiums in United States specialty retail channels.
- Concentrate Food-Service Expansion:Customizable beverage programs in European hospitality sectors remain underpenetrated versus ready-to-drink dominance.
- Deposit-Return Legislation Tailwind:EU single-use packaging directives incentivize aluminum can circularity investments ahead of compliance deadlines.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise bridging roast profile stability with extended shelf life commands premium compensation.
- Co-Packer Capacity Bottlenecks:Aseptic filling line availability constrains brand expansion during seasonal demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Brew Coffee Market |
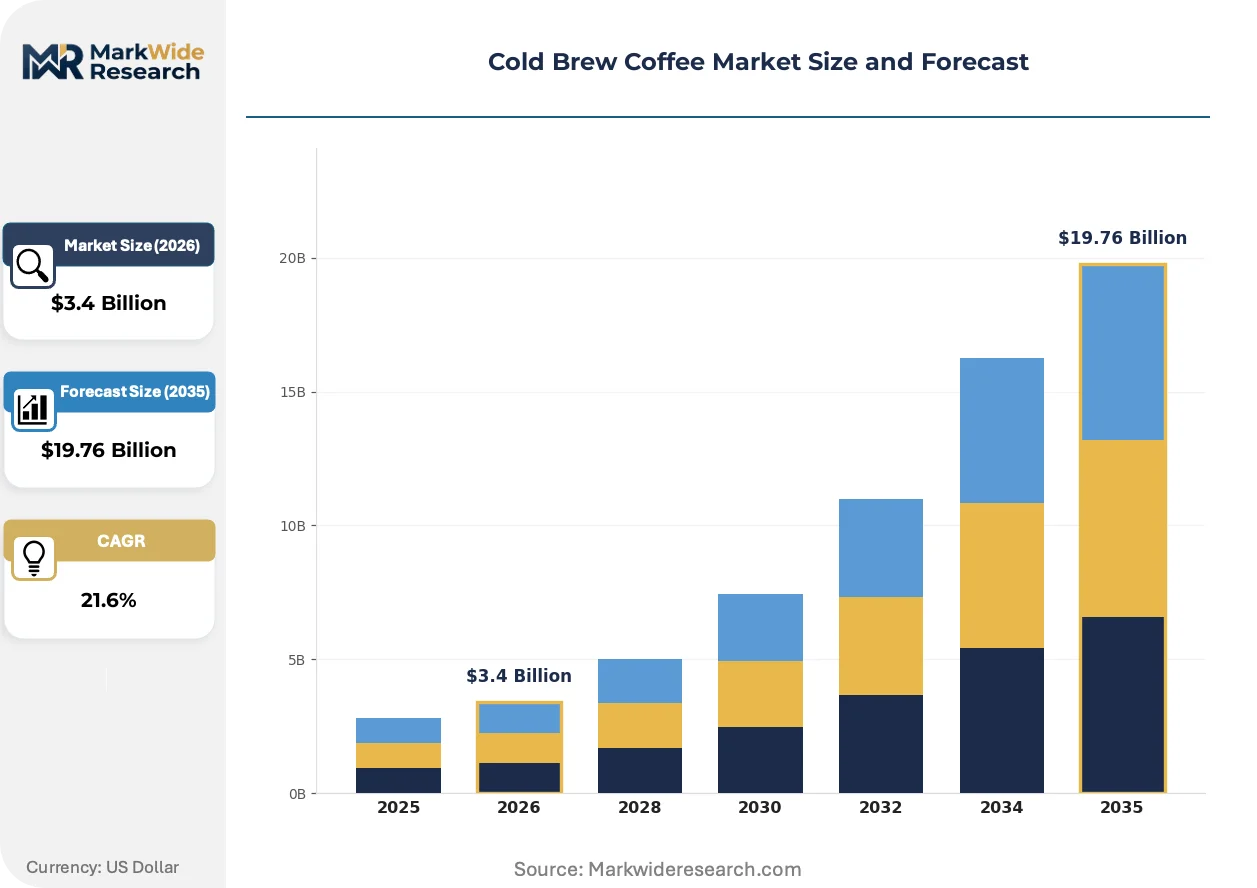
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $19.76 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Concentrate, Grounds, Pods Packaging Type: Cans, Bottles, Pouches, Jars Distribution Channel: Supermarkets, Online Stores, Specialty Shops, Cafes Customer Type: Retail Consumers, Food Service, Enterprises, Wholesalers |
| Companies Covered | Starbucks Corporation, Nestlé S.A., JAB Holding Company, Califia Farms, La Colombe Coffee Roasters, Stumptown Coffee Roasters, Chameleon Cold-Brew, High Brew Coffee, RISE Brewing Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Brew Coffee Market Emerging Trajectories
Processing technology convergence and regulatory labeling precision are redefining competitive advantage in cold brew manufacturing, with shelf-life engineering and caffeine transparency emerging as primary differentiation vectors.
Nitrogen infusion technology is unifying draft-system dispensing with retail can formats, allowing roasters to replicate cafe-quality texture in ambient distribution. Specialty chains and stadium concessions are adopting inline nitrogen generators at accelerating rates. This capability compression is collapsing the experience gap between on-premise and packaged consumption.
The EU Food Information to Consumers Regulation mandates milligram-precision caffeine disclosure on ready-to-drink labels, forcing reformulation of high-caffeine concentrates bound for European export. Manufacturers are adjusting extraction protocols and dilution ratios to standardize declared content across batches. German and Dutch importers now require third-party caffeine assay documentation as standard procurement terms.
Direct-to-subscription purchasing is displacing conventional grocery replenishment among United States millennials and Gen Z consumers, with roasters building recurring revenue through customizable roast and flavor rotation programs. This channel bypasses slotting fee structures that favor multinational beverage conglomerates. California and Pacific Northwest urban clusters show highest subscription penetration, with fulfillment infrastructure now replicating in Texas and Florida metros.
Cold Brew Coffee Market Segmentation
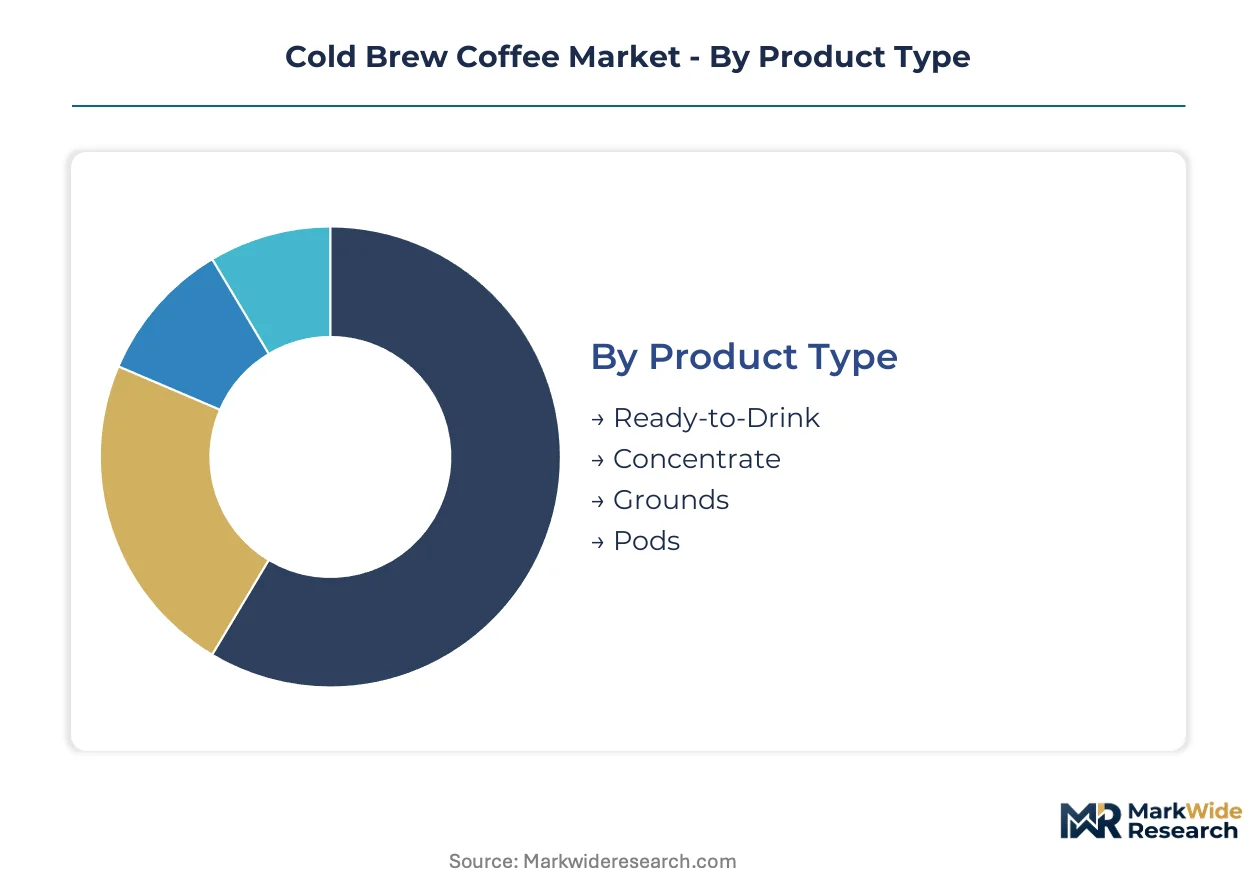
Cold brew manufacturers configure production assets around format-specific shelf-life requirements and channel economics. Segmentation discipline separates ambient-stable mass-market plays from refrigerated premium positioning.
Product Type:
Upgrade cycles from homemade preparation to commercial formats are compressing as convenience premiums narrow.
- Ready-to-Drink:Pre-diluted formulations in shelf-stable packaging dominate grocery velocity. United States convenience store chains and airport concessions drive placement density for single-serve cans with nitrogen widget integration.
- Concentrate:Dilutable extracts with 4:1 to 10:1 reconstitution ratios serve food-service accounts seeking customizable beverage programs. European hospitality procurement in Germany and Netherlands favors concentrate tote systems for draft dispense.
- Grounds:Coarse-grind retail packs target home brewers with equipment investments. Specialty roasters in Pacific Northwest urban clusters bundle grounds with filtration apparatus.
- Pods:Single-serve capsules remain format-constrained by equipment compatibility limitations and consumer education costs. Keurig and Nespresso system licensing restricts independent roaster participation.
Volume placements concentrate in Ready-to-Drink; the faster expansion belongs to Concentrate.
Packaging Type:
Cost tier stratification separates premium nitrogen-charged formats from commodity multi-serve containers.
- Cans:Aluminum formats with internal nitrogen widgets replicate draft texture. Deposit-return legislation in Germany and pending EU single-use directives are accelerating circularity investments.
- Bottles:Glass and PET containers serve multi-serve refrigerated segments. Japanese convenience chains favor slender PET profiles for grab-and-go velocity.
- Pouches:Flexible formats reduce shipping cube and material cost. Australian camping and outdoor retail channels show niche adoption for concentrate pouches.
- Jars:Multi-serve glass containers concentrate in direct-to-subscription channels. Roasters in California and Texas metros use jar formats for customizable flavor rotation programs.
Can placements lead current volume; pouch formats are climbing the fastest in specialty outdoor and subscription channels.
Distribution Channel:
Customer acquisition economics vary sharply between slotting-fee grocery and direct subscription models.
- Supermarkets:Mass-market velocity depends on refrigerated case placement and seasonal promotional calendars. United States conventional and natural grocery chains command placement fees that disadvantage regional roasters.
- Online Stores:Direct-to-consumer fulfillment bypasses retail margin stacking. Texas and Florida metro replication of California subscription infrastructure is expanding geographic reach.
- Specialty Shops:Curated assortment and staff education support premium pricing. Independent retailers in Portland and Brooklyn function as brand incubators for emerging roasters.
- Cafes:On-premise draft systems and retail grab-and-go cases serve dual purposes. Quick-service chain adoption in United States is stabilizing concentrate offtake.
Supermarket placements anchor volume; online channels are gaining share fastest among millennial and Gen Z cohorts.
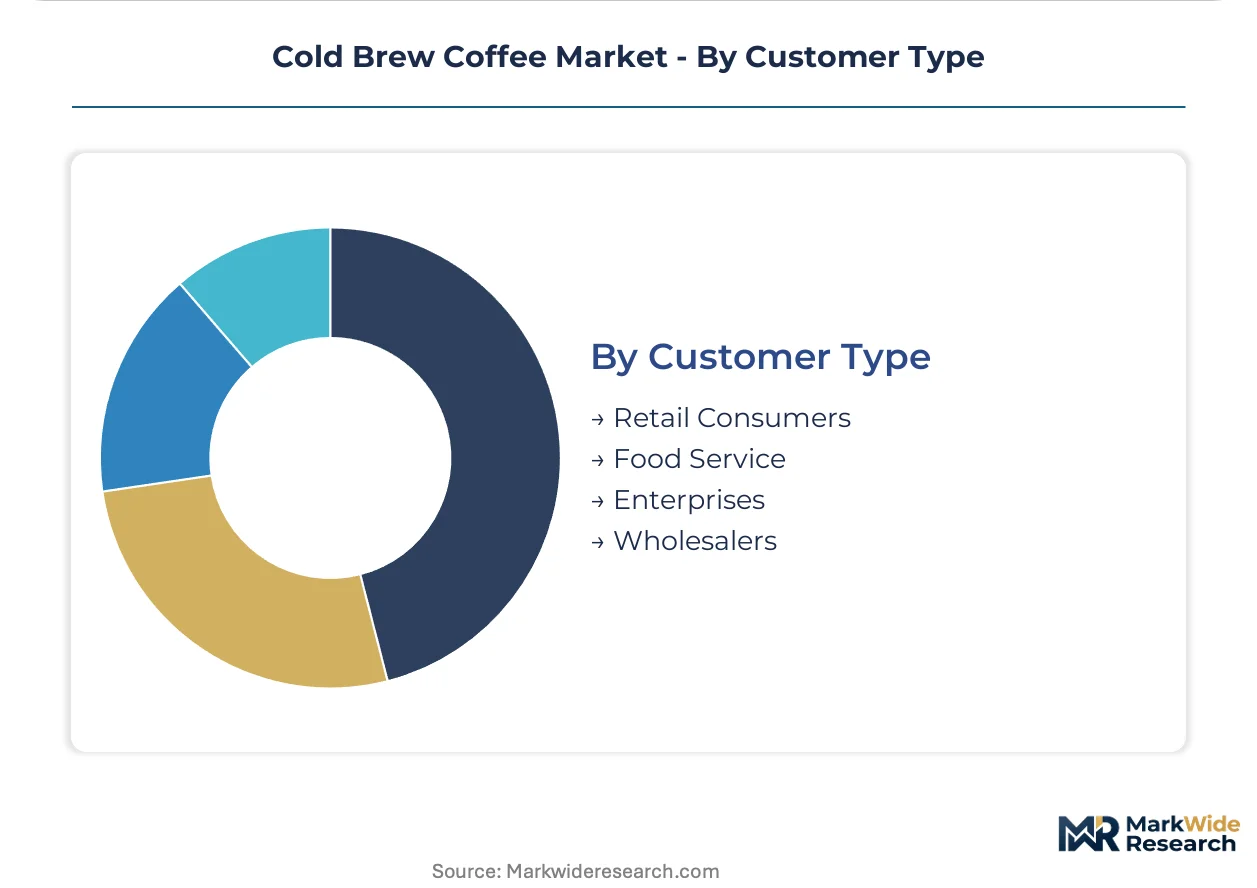
Customer Type:
Margin structure diverges between price-sensitive wholesale commodity and premium direct retail.
- Retail Consumers:Individual purchasers drive flavor innovation velocity through subscription feedback loops. Customizable roast rotation programs concentrate in California and Pacific Northwest urban clusters.
- Food Service:Cafe and restaurant accounts require consistent concentrate supply for menu stability. Year-round permanence in United States quick-service chains is restructuring production economics.
- Enterprises:Corporate pantry and hospitality procurement favors ambient-stable formats with extended shelf life. Office coffee service distributors bundle cold brew with equipment leasing.
- Wholesalers:Route-to-market intermediaries aggregate regional roaster output for broadline distribution. Cold chain capacity constraints limit wholesaler coverage in temperature-logistics-sparse regions.
Food service captures current volume concentration; enterprise procurement shows steepest expansion trajectory as workplace beverage programs upgrade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors North American cold brew innovation, hosting roasting clusters that supply specialty chains and direct-to-subscription channels across the continent.
United States
Specialty coffee chains and grocery channels drive volume concentration, with California and Texas metros replicating Pacific Northwest subscription infrastructure. The FDA imposes Hazard Analysis Critical Control Point protocols on low-acid canned cold brew. Portland and Brooklyn independent retailers function as brand incubators for emerging roasters testing novel extraction protocols.
Germany
European hospitality procurement favors concentrate tote systems for draft dispense in cafes and restaurants. The EU Food Information to Consumers Regulation mandates milligram-precision caffeine disclosure, forcing reformulation of export-bound concentrates. Berlin and Hamburg roasting clusters are investing in nitrogen widget canning lines to replicate cafe-quality texture for retail distribution.
Japan
Convenience store chains favor slender PET bottle profiles for grab-and-go velocity in dense urban corridors. METI guidelines on food labeling shape premium positioning strategies for imported and domestic brands. Tokyo and Osaka metropolitan areas concentrate specialty roasting capacity, with direct-to-consumer subscription models penetrating secondary cities.
Australia
Outdoor and camping retail channels show niche adoption for flexible concentrate pouches reducing shipping cube. The country's national food safety regulator enforces strict microbiological standards on extended-shelf-life beverages. Melbourne and Sydney roasting clusters are piloting deposit-return circularity investments ahead of anticipated packaging legislation.
Netherlands
German and Dutch importers require third-party caffeine assay documentation as standard procurement terms for concentrate shipments. EU single-use packaging directives accelerate aluminum can circularity investments among Dutch co-packers. Amsterdam and Rotterdam logistics hubs enable refrigerated distribution across Northern European hospitality markets.
Cold Brew Coffee Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as multinational beverage conglomerates operate captive canning lines while specialty roasters outsource aseptic filling to third-party packers. The market exhibits tiered concentration, with scale players commanding grocery slotting fees and regional craft brands capturing subscription loyalty. Three archetypes dominate: vertically integrated roasting-to-retail operators, plant-based formulation specialists, and co-packer-dependent craft labels. Competitive moves center on M&A to secure roasting capacity and strategic partnerships to access nitrogen infusion technology.
Within the multinational beverage tier, Starbucks Corporation and Nestlé S.A. occupy positions defined by retail footprint scale and concentrated production platforms respectively. Among plant-based formulation specialists, Califia Farms exemplifies the archetype commanding shelf-space premiums through oat and almond milk integration expertise.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Nestlé S.A. |
| JAB Holding Company |
| Califia Farms |
| La Colombe Coffee Roasters |
| Stumptown Coffee Roasters |
| Chameleon Cold-Brew |
| High Brew Coffee |
| RISE Brewing Co. |
| Others |
Supply Flow & Price Mechanics
United States quick-service chains and grocery buyers concentrate procurement volume, anchoring contract-based concentrate pricing that rewards scale with slotting-fee relief and refrigerated case placement guarantees. This buyer concentration compresses margin capture for regional roasters lacking national distribution infrastructure.
Pricing Analysis
USDA Organic certification anchors value-based pricing premiums in United States grocery channels, separating certified specialty tiers from conventional mass-market offerings. Price differentiation rests on extraction protocol sophistication and nitrogen-infusion capability rather than commodity bean sourcing alone. Cost compression in mass-market ready-to-drink tiers intensifies as Brazilian arabica volatility feeds through contract renegotiations. Food-service accounts exhibit lowest price sensitivity due to menu-margin absorption, while direct-to-subscription retail consumers demand flavor-rotation value to justify recurring commitments.
Supply Chain Analysis
Dual-sourcing requirements from major United States grocery chains and European hospitality distributors mandate multi-supplier qualification for concentrate and ready-to-drink formats. Green coffee sourcing concentrates in Brazil, Colombia, and Ethiopia, with roasting capacity clustering in Seattle, Portland, and Berlin metropolitan areas. Aseptic filling line availability constrains brand expansion during demand spikes, creating co-packer capacity bottlenecks. Distribution runs through temperature-controlled logistics networks that limit route-to-market options in cold-chain-sparse regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold brew market sits in a processing-technology transition, with high-pressure processing and nitrogen-infusion systems displacing legacy thermal pasteurization and draft-only dispensing. This capability compression reshapes competitive advantage toward shelf-life engineering and texture replication.
For Market Incumbents: Acquire captive aseptic filling capacity in Texas and Florida metros to secure production autonomy ahead of co-packer bottlenecks. Deepen backward integration into certified organic supply chains to defend margin position against arabica price volatility and compress the specialty-mass gap.
For New Entrants and Emerging Players: Enter via direct-to-subscription channels in secondary United States metros replicating California fulfillment infrastructure, bypassing grocery slotting-fee barriers. Target European hospitality concentrate procurement in Germany and Netherlands, where draft-dispense customization remains underpenetrated versus ready-to-drink dominance.
For Investors and Strategic Acquirers: The window for entry favors plant-based formulation specialists with oat and almond milk integration expertise ahead of mainstream dairy convergence. Watch nitrogen widget canning line investments as the inflection signal separating scalable premium positioning from draft-constrained regional players.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | HPP technology extends refrigerated shelf life without thermal degradation, enabling national distribution for regional brands. |
| Nitrogen Widget Canning Investment | Inline nitrogen generators replicate cafe-quality texture in ambient retail formats, collapsing the on-premise experience gap. |
| Organic Certification Investment | USDA certification unlocks premium tier pricing power in United States grocery channels previously reserved for multinational conglomerates. |
| Direct-to-Subscription Infrastructure | Customizable flavor rotation programs bypass slotting-fee structures and build recurring revenue among millennial and Gen Z cohorts. |
| European Hospitality Concentrate Expansion | Draft-dispense tote systems in Germany and Netherlands address underpenetrated food-service customization demand. |
Methodological Framework
Independent corroboration across roasting operations executives, food-service procurement directors, grocery category buyers, and co-packer facility managers underwrites the qualitative findings. Secondary validation draws from FDA low-acid canned food filings, USDA organic certification databases, EU Food Information to Consumers regulatory texts, and refrigerated logistics trade association data. Bottom-up volume triangulation from concentrate tote shipments and ready-to-drink can production runs converges with top-down grocery velocity audits and subscription platform disclosures.
Comparable historical periods spanning seasonal demand cycles and regulatory implementation phases anchor the projection framework across the analysis window. Segmentation dimensions model product format, packaging type, distribution channel, and customer archetype alongside extraction protocol sophistication tiers. CAGRs derive from slope-intercept fitting of normalized volume trajectories, with inputs weighted toward high-pressure processing adoption curves and nitrogen-infusion equipment deployment rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under arabica commodity spikes and deposit-return legislation acceleration. Deviation in FDA HACCP enforcement intensity or EU single-use packaging compliance deadlines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Decoction Maker Market
Coffee
South America Coffee Market
Coffee
Reusable Coffee Cup Market
Coffee
UK Coffee Roaster Market
Coffee
Cold Brew Coffee Pots Market
Coffee
Coffee Pods and Capsules Market
Coffee
Butter Coffee Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Tea and Coffee Bags Market
Coffee
North America Coffee Market
Coffee
RTD Coffee Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Freeze Dried Coffee Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Instant Coffee Market