
 Europe Coffee Pods and Capsules Market | 2026-2036
Europe Coffee Pods and Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coffee Pods and Capsules Market Foresight
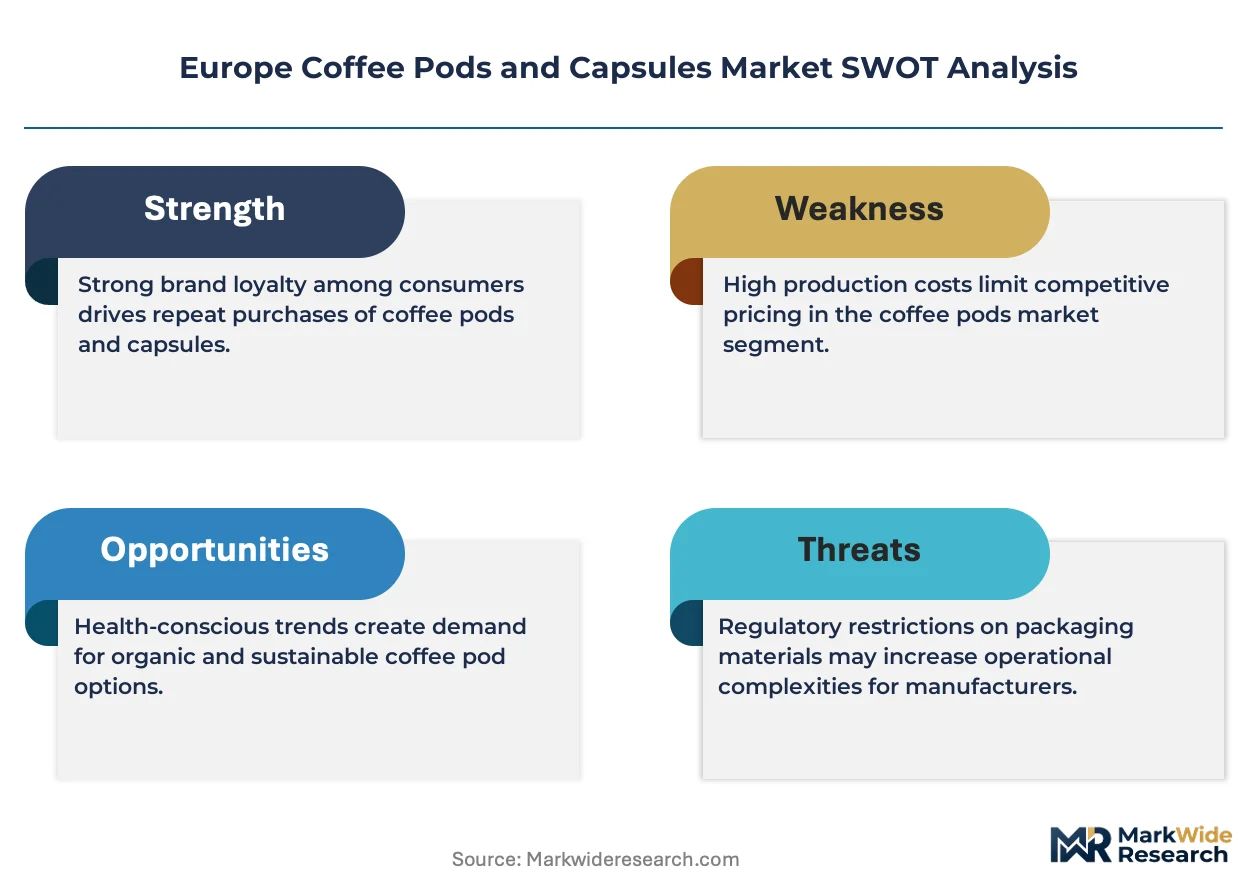
Premium roast-tier certification is rotating through European retail channels as consumers trade up from standard commodity offerings. Nestlé Nespresso SA leverages its proprietary aluminum capsule ecosystem to sustain premium positioning across French and Swiss markets. JDE Peet's N.V. anchors volume distribution through broad retail partnerships spanning German and Benelux supermarkets. Luigi Lavazza S.p.A. differentiates via heritage espresso credentials and direct relationships with Italian hospitality operators.
Europe coffee pods and capsules comprise pre-portioned ground coffee sealed in single-use containers, typically manufactured from aluminum, plastic, or compostable biopolymers, designed for extraction under bar-pressure systems producing standardized beverage outputs. The primary commercial purpose centers on eliminating grinding variability while reducing preparation time for foodservice and residential end-users. Single-Serve Pods dominate volume flows through supermarket and e-commerce channels, while Aluminum capsules capture disproportionate margin pools due to recyclability premiums and Nespresso-compatible licensing structures. Biodegradable materials represent the fastest-evolving Material Type segment as ECHA-aligned sustainability mandates reshape supplier R&D allocation across Italian and German manufacturing bases.
EU REACH frameworks govern chemical migration limits from plastic capsules into beverage contact surfaces, while the EU Green Deal's packaging waste reduction targets are forcing material transitions before national implementation deadlines. EFSA guidelines on food contact materials further constrain novel biopolymer introductions, creating compliance layering that favors incumbents with established testing protocols. Stakeholders must monitor pending revisions to the Packaging and Packaging Waste Regulation to calibrate material roadmaps and recycling infrastructure investments.
Market Dynamics
The EU Single-Use Plastics Directive is forcing material transitions across European manufacturing bases before national implementation deadlines reshape competitive positioning.
Growth Catalysts
- Biodegradable biopolymers:ECHA-aligned sustainability mandates in Germany and Italy are redirecting supplier R&D allocation toward compostable alternatives.
- Urban hospitality operators:Premium single-serve formats are gaining traction among foodservice chains in French and German metropolitan clusters.
- Aluminum recyclability premiums:Nespresso-compatible licensing structures capture disproportionate margin pools through closed-loop collection systems.
Market Restraints
- Aluminum price volatility:Input cost fluctuations compress margins for producers dependent on virgin metal sourcing.
- EFSA compliance layering:Novel biopolymer introductions face extended testing protocols that favor incumbents with established validation frameworks.
- Plastic substitution pressure:Consumer backlash against petroleum-based capsules accelerates demand for alternatives before supply scales.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian residential markets show nascent single-serve adoption with limited local production capacity.
- EU Green Deal packaging targets:Extended producer responsibility schemes create first-mover advantages for circular infrastructure investors.
- Smart brewing convergence:IoT-enabled machines and subscription replenishment models integrate hardware with consumable supply.
Industry Challenges
- Biopolymer certification timelines:EFSA food contact material approvals delay product launches by 18-24 months.
- Recycling infrastructure fragmentation:National collection scheme heterogeneity complicates pan-European aluminum recovery programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coffee Pods and Capsules Market |
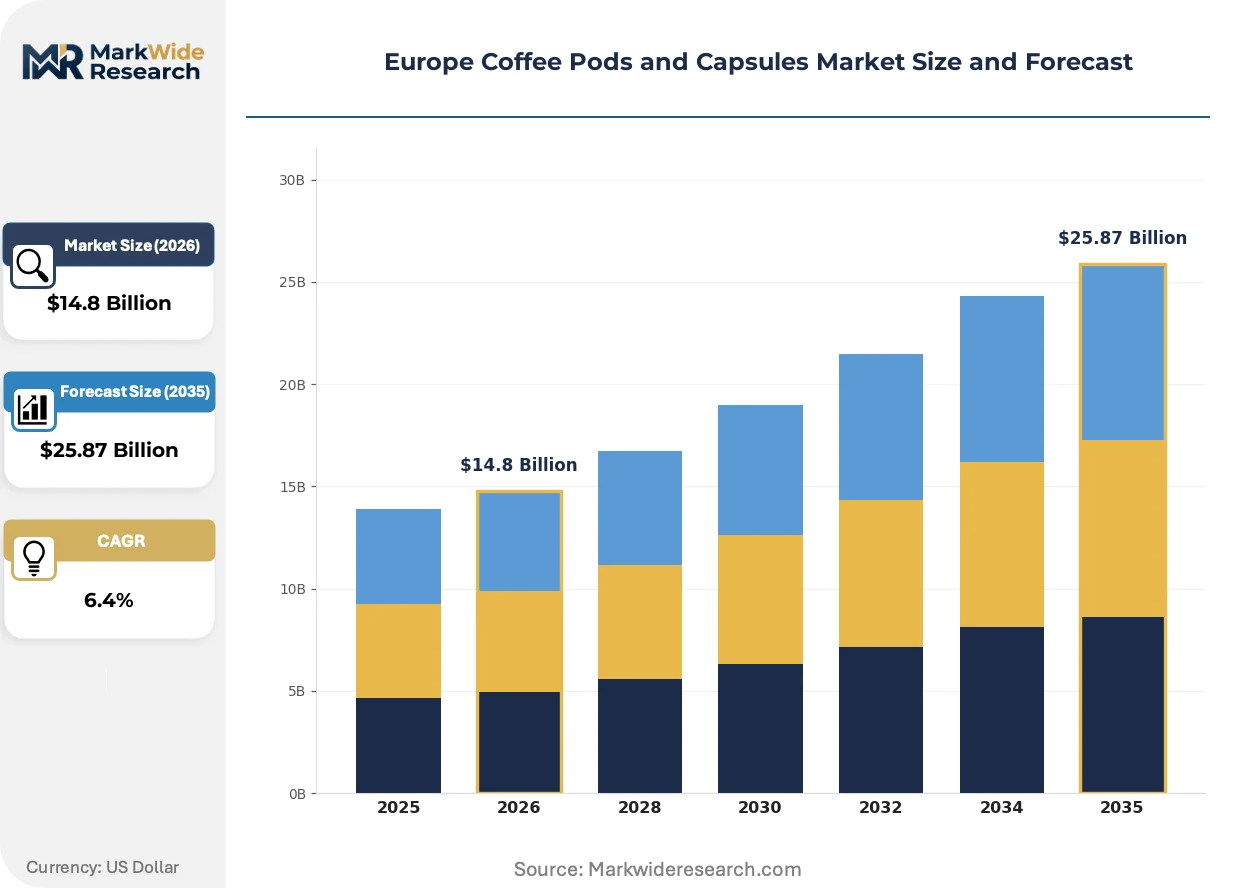
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Serve Pods, Capsules, Ground Coffee, Instant Coffee Brewing Method: Espresso Machines, Drip Coffee Makers, Pod Machines, French Press Material Type: Plastic, Aluminum, Biodegradable, Paper Flavors: Espresso, Medium Roast, Dark Roast, Decaf |
| Companies Covered | JDE Peet's N.V., The Kraft Heinz Company, Nestlé Nespresso SA, Segafredo Zanetti, Tassimo, Luigi Lavazza S.p.A., Starbucks Corporation, Ethical Coffee Company, Illycaffè S.p.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coffee Pods and Capsules Market Shifts & Advancements
Material science advances and regulatory compression are simultaneously enabling premium positioning and threatening incumbent plastic-based supply chains across European markets.
Compostable biopolymer formulations are bifurcating the material landscape between performance-grade aluminum and emerging plant-based alternatives. Italian manufacturers lead pilot deployments with polylactic acid blends targeting hospitality operators seeking sustainability credentials. The technology is bifurcating procurement standards as buyers split between premium recyclability and novel biodegradability claims.
EU REACH chemical migration limits are tightening enforcement across plastic capsule categories. ECHA scrutiny of bisphenol analogues and phthalate alternatives forces reformulation investments before 2025 compliance deadlines. German and French regulators coordinate inspection protocols that disproportionately affect mid-tier private-label suppliers lacking dedicated toxicology teams.
Subscription-based replenishment models are displacing supermarket bulk purchasing among urban professionals. Direct-to-consumer channels capture recurring revenue from Swiss and Benelux households while eroding traditional retail velocity. Paris and Milan demonstrate the sharpest channel rotation as convenience-oriented consumption consolidates around automated delivery scheduling.
Europe Coffee Pods and Capsules Market Segmentation
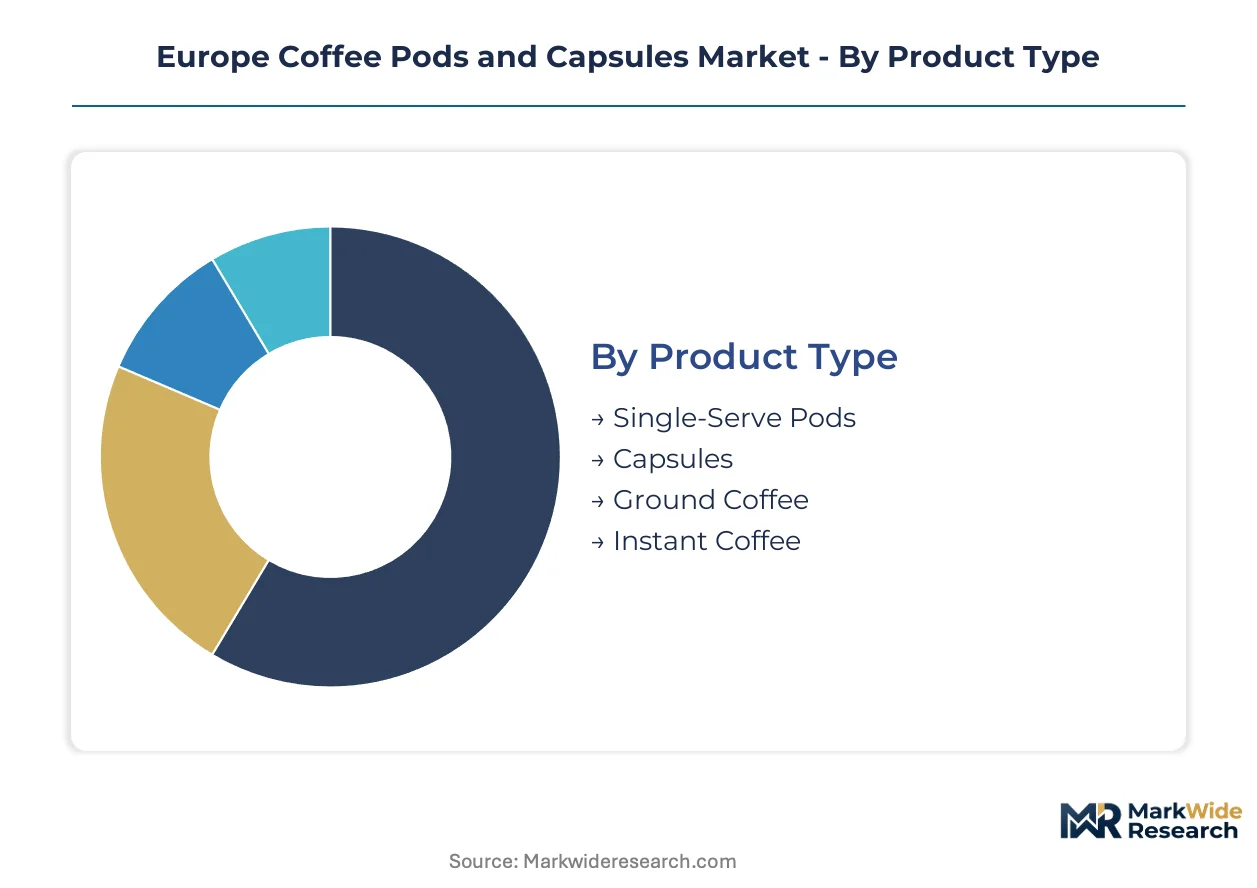
Segmentation in the Europe coffee pods and capsules market reveals distinct channel affinities and margin structures. Material composition and brewing compatibility determine pricing power, while flavor profiles and format types dictate household penetration rates across metropolitan clusters.
Product Type:
Supermarket chains and e-commerce platforms channel different formats based on price elasticity and replenishment frequency.
- Single-Serve Pods:Soft, porous paper or mesh containers holding pre-ground coffee for pressure-based extraction systems. French and German households drive volume through hypermarket bulk purchasing and automated subscription replenishment.
- Capsules:Rigid aluminum or plastic shells engineered for bar-pressure machines with sealed aroma barriers. Swiss and Italian markets concentrate demand here, with hospitality operators in Paris and Milan paying recyclability premiums for aluminum variants.
- Ground Coffee:Bulk loose-format coffee requiring manual dosing and tamping, primarily retailed through traditional grocery.
- Instant Coffee:Spray-dried or freeze-dried soluble granules dissolving without extraction equipment, dominant in price-sensitive Eastern European markets.
Single-Serve Pods dominate installed base. Capsules is where expansion concentrates.
Brewing Method:
Equipment ownership patterns in German and French metropolitan areas determine consumable format demand.
- Pod Machines:Proprietary and open-system pressure brewers using sealed single-serve formats. Urban professionals in Benelux cities and Swiss cantons anchor replacement demand through subscription-linked hardware.
- Espresso Machines:Manual and semi-automatic systems requiring tamped ground coffee or compatible capsules. Italian hospitality operators sustain this segment via heritage preparation rituals and direct supplier relationships.
- Drip Coffee Makers:Gravity-fed filtration systems using paper pods or loose grounds, common in Northern European residential settings.
- French Press:Immersion brewing with coarse grounds, retaining niche share among sustainability-conscious consumers avoiding single-use packaging.
Pod Machines command the largest installed base. Espresso Machines is climbing the fastest among premium hospitality upgrades.
Material Type:
EU regulatory timelines and ECHA sustainability mandates are redirecting procurement specifications across manufacturing bases.
- Biodegradable:Polylactic acid and compostable biopolymer formulations decomposing under industrial composting conditions. German and Italian suppliers pilot these for hospitality operators seeking ESG-compliant supply chains ahead of EU Single-Use Plastics Directive deadlines.
- Aluminum:Virgin and recycled metal shells with oxygen barrier properties enabling extended shelf stability. Nespresso-compatible licensing structures in France and Switzerland capture margin premiums through closed-loop collection infrastructure.
- Plastic:Polypropylene and polystyrene capsules facing substitution pressure from petroleum-based material restrictions.
- Paper:Fiber-based pods for soft-format brewing, limited by moisture barrier performance in high-pressure systems.
Aluminum dominates installed base. Biodegradable is gaining share fastest as EFSA approval pathways mature.
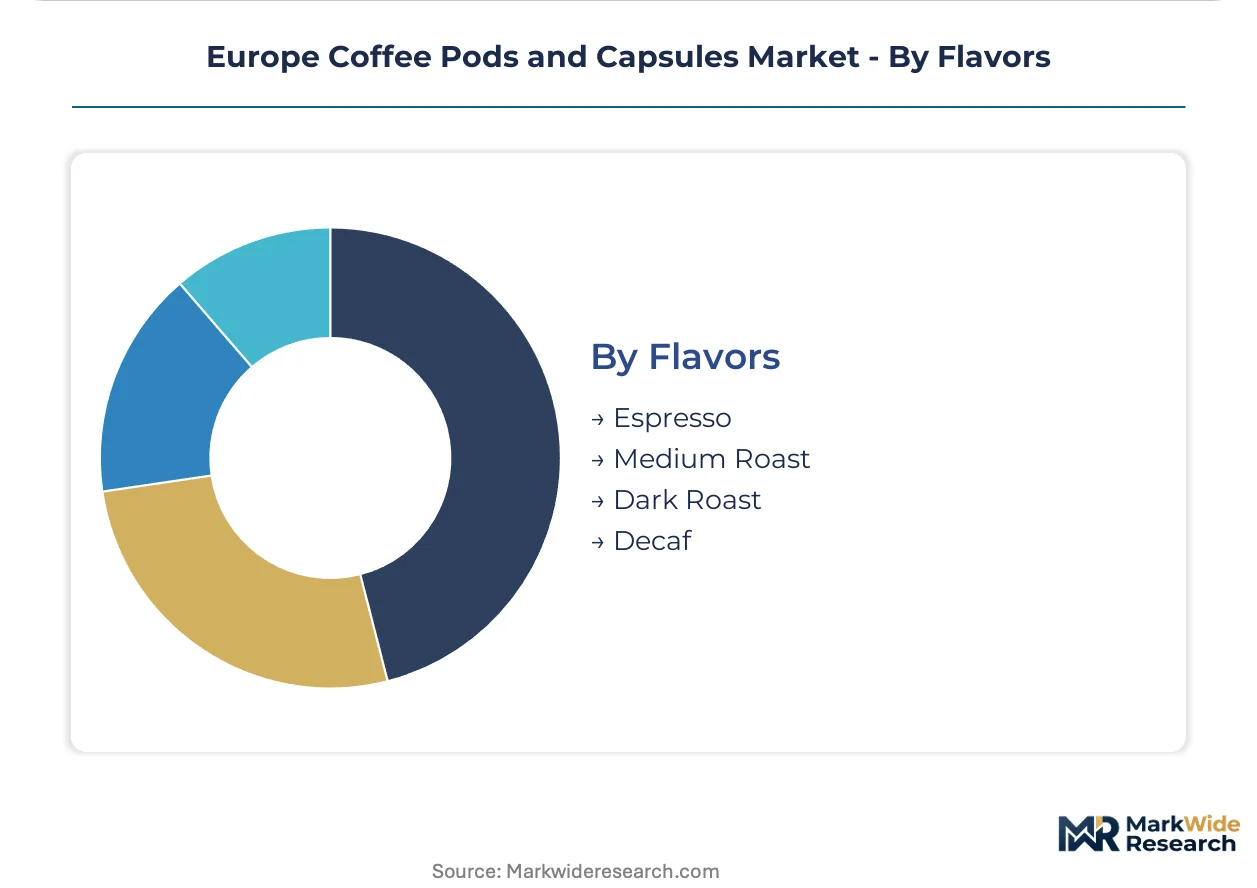
Flavors:
Roast certification tiers stratify pricing across retail and foodservice channels in Western European markets.
- Espresso:Dark-roast blends optimized for short extraction volumes and crema formation. Italian and French hospitality operators specify these for traditional preparation standards.
- Dark Roast:Extended roasting profiles reducing acidity and emphasizing body. German supermarket chains move volume through private-label offerings.
- Medium Roast:Balanced acidity and body profiles targeting broad household palatability.
- Decaf:Solvent or water-processed caffeine removal for evening consumption and medical dietary restrictions.
Espresso dominates installed base. Dark Roast is where volume expansion concentrates through retail private-label growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian manufacturers export compostable biopolymer capsules to German and French hospitality operators seeking ESG-compliant supply chains ahead of EU Single-Use Plastics Directive deadlines. Swiss aluminum capsule producers supply premium recyclability formats to Paris and Milan metropolitan clusters.
Germany
Urban hospitality chains in Berlin and Munich drive premium single-serve adoption through automated subscription replenishment models. ECHA-aligned sustainability mandates redirect supplier R&D toward polylactic acid biopolymers. The Rhine-Ruhr manufacturing corridor hosts pilot compostable capsule production for foodservice operators.
France
Parisian metropolitan professionals displace supermarket bulk purchasing through direct-to-consumer subscription channels. EU REACH chemical migration limits tighten enforcement across plastic capsule categories ahead of 2025 compliance deadlines. Lyon hospitality operators specify aluminum variants with closed-loop collection infrastructure.
Italy
Heritage espresso preparation rituals sustain demand among Milan and Rome foodservice operators through direct supplier relationships. EFSA food contact material approvals constrain novel biopolymer introductions with 18-24 month validation timelines. Turin manufacturing bases lead pilot deployments of compostable alternatives for ESG-conscious buyers.
Switzerland
Swiss canton households anchor replacement demand through subscription-linked proprietary hardware ecosystems. Nespresso-compatible licensing structures capture recyclability premiums via established collection programs. Zurich and Geneva retail channels concentrate premium roast-tier certification distribution.
Poland
Nascent single-serve adoption in Warsaw and Krakow residential markets outpaces local production capacity. EU Green Deal packaging waste reduction targets accelerate material transitions before national implementation deadlines. Limited domestic manufacturing creates import dependency for biodegradable and aluminum alternatives.
Europe Coffee Pods and Capsules Market Competitive Landscape
Listed leaders compete with private specialists across material science and distribution reach dimensions. The vendor base stratifies into three tiers: multinational FMCG conglomerates with proprietary aluminum ecosystems, mid-cap European heritage roasters with hospitality relationships, and emerging biopolymer specialists targeting sustainability premiums. Consolidation pressure intensifies as EFSA compliance layering favors incumbents with established toxicology validation frameworks. Dominant competitive moves include backward integration into compostable material supply and exclusive retail partnership anchoring in German and Benelux supermarket chains.
Within the heritage-roaster archetype, Luigi Lavazza S.p.A. and Illycaffè S.p.A. exemplify Italian-origin S.p.A. structures leveraging direct foodservice relationships. Nestlé Nespresso SA occupies a position representing the multinational proprietary-ecosystem tier through its Swiss SA entity structure. Among Netherlands-based N.V. conglomerates, JDE Peet's N.V. anchors the broad-distribution archetype spanning German and Benelux retail channels.
| Leading Market Players |
|---|
| JDE Peet's N.V. |
| The Kraft Heinz Company |
| Nestlé Nespresso SA |
| Segafredo Zanetti |
| Tassimo |
| Luigi Lavazza S.p.A. |
| Starbucks Corporation |
| Ethical Coffee Company |
| Illycaffè S.p.A. |
| Others |
Supply & Pricing Matrix
Take-or-pay contracts between German hospitality chains and Italian biopolymer suppliers lock in multi-year supply access while fixing input cost visibility against aluminum price volatility. These arrangements concentrate procurement power among operators with sufficient volume scale to justify dedicated production runs.
Pricing Analysis
Material-generation pricing gaps separate virgin aluminum capsules from recycled-content variants and emerging compostable alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by recyclability certification and brewing system compatibility. Cost compression in plastic-based tiers is intensifying because EU REACH compliance investments compound with petroleum-based material stigma. Private-label supermarket buyers in Germany exhibit highest price sensitivity, while Swiss subscription-channel households accept sustained premiums for closed-loop aluminum recovery programs.
Supply Chain Analysis
Just-in-time inventory strategies dominate aluminum capsule production in Switzerland and France, whereas German biopolymer manufacturers maintain strategic stockpiles of polylactic acid feedstock against EFSA approval delays. Supply concentrates in Italy, Germany, and Switzerland for finished capsule manufacturing, with raw material sourcing drawing from Belgian aluminum smelters and Thai biopolymer resin producers. Single-source vulnerability runs through Nespresso-compatible licensing structures that control compatible machine installed bases. Distribution runs through Benelux supermarket consolidation and direct-to-consumer subscription platforms anchored in Paris and Zurich metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as post-pandemic hospitality normalization in Paris, Berlin, and Milan restarts premium single-serve procurement cycles deferred during travel restrictions.
For Market Incumbents: Fortify aluminum capsule margin pools by deepening backward integration into closed-loop collection infrastructure before EU Green Deal extended producer responsibility schemes harden. EFSA compliance layering favors incumbents with established toxicology validation frameworks against mid-tier private-label threats. Prioritize capacity addition in the Rhine-Ruhr corridor to anchor German foodservice supply relationships. For New Entrants and Emerging Players: Hospitality-operator sustainability reporting gaps present white-space where incumbents under-serve ESG documentation needs for scope-three emissions tracking. Polish and Romanian residential markets offer the most penetrable geography given nascent single-serve adoption and limited local production capacity. Pursue white-label biopolymer supply partnerships with Italian manufacturers lacking direct distribution reach. For Investors and Strategic Acquirers: Capital is best deployed toward heritage-roaster S.p.A. structures with captive Italian hospitality relationships and underexploited compostable material pipelines. Five-to-ten year viability hinges on successful EFSA approval pathway navigation for novel biopolymers. Watch biopolymer certification timeline compression as the inflection signal indicating regulatory clarity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Material Scale-Up | Italian manufacturers pilot polylactic acid blends ahead of EU Single-Use Plastics Directive deadlines. |
| Closed-Loop Collection Infrastructure | Swiss aluminum producers capture recyclability premiums through Nespresso-compatible licensing structures. |
| Direct-to-Consumer Channel Expansion | Paris and Milan subscription platforms displace supermarket bulk purchasing among urban professionals. |
| EFSA Compliance Investment | German suppliers accelerate toxicology validation to maintain market access under tightening food contact material rules. |
| Eastern European Distribution Partnership | Benelux consolidators anchor Polish and Romanian retail presence before local production capacity develops. |
Research Methodology
Initial hypotheses were tested against primary input from hospitality procurement directors, coffee roaster R&D leads, supermarket category buyers, and EFSA regulatory consultants and refined through secondary validation. Primary fieldwork combined structured interviews with foodservice chain operators in Berlin, Paris, and Milan alongside supply chain mapping with Italian and German manufacturers. Secondary sources included EU REACH regulatory filings, EFSA food contact material opinions, customs trade data for aluminum and biopolymer inputs, and Nielsen retail audit data for Benelux and German supermarket channels. Bottom-up volume estimates triangulated against top-down market sizing across material type and brewing method segments.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects and regulatory scenario impacts. Segmentation modeling incorporated material type transitions, brewing system installed base evolution, and regional hospitality recovery patterns. CAGRs were derived from normalized historical trajectory analysis adjusted for regulatory inflection timing. Forecast inputs included EFSA approval pipeline status for novel biopolymers and EU Green Deal implementation schedules across member state jurisdictions.
Forecasts assume regulatory continuity in EU REACH, EFSA food contact material frameworks, and national packaging waste reduction regimes; material policy shifts would require re-modeling of material transition timelines and competitive positioning. Aluminum price volatility, biopolymer certification delays, and hospitality demand cyclicality constitute specific revision triggers. Revision becomes warranted when EFSA approval timeline compression or extension crosses thresholds that alter first-mover advantage calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Caffeine Market
Coffee
Coffee Roaster Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Coffee Decoction Maker Market
Coffee
Coffee Brewers Market
Coffee
GCC Instant Coffee Market
Coffee
Vietnam Coffee Market
Coffee
Espresso Powder Market
Coffee
Coffee Fruit Extract Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Raw Coffee Beans Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Europe Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Instant Coffee Market
Coffee
India Ready-To-Drink (RTD) Coffee Market