
 Coffee Fruit Extract Market | 2026-2036
Coffee Fruit Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Fruit Extract Market Analytics
Upcycled extraction technology is rewriting how coffee cherry waste converts into standardized nutraceutical inputs. Tate & Lyle leverages its flavor systems infrastructure to integrate coffee fruit extract into mainstream beverage applications. NatureWise anchors its direct-to-consumer channel with single-origin coffee fruit supplements targeting antioxidant seekers. Givaudan differentiates through botanical extraction expertise that preserves chlorogenic acid stability across formulation types.
Coffee fruit extract comprises bioactive compounds derived from the whole coffee cherry, including pulp and cascara, typically standardized to polyphenol and chlorogenic acid concentrations between 40% and 70% for commercial nutraceutical use. The ingredient serves primarily as an antioxidant fortifier in functional foods and dietary supplements seeking clean-label positioning. Powder formats lead volume throughput due to shelf stability and blending flexibility in manufacturing environments. Dietary supplements capture premium margin pools as consumers prioritize cognitive health and metabolic support claims. Skincare products represent the fastest-growing application as cosmetic chemists incorporate coffee fruit polyphenols into anti-aging formulations.
FDA GRAS self-affirmation pathways and EFSA novel food consultation requirements shape how suppliers validate safety dossiers for coffee fruit extract entry into US and European channels. ISO 22000 and HACCP frameworks govern extraction facility certification, directly influencing buyer qualification criteria for contract manufacturing partnerships. Stakeholders must monitor evolving substantiation standards for antioxidant health claims across multiple jurisdictions to sustain commercial traction.
Market Dynamics
Upcycled extraction infrastructure is concentrating supply capability among facilities capable of meeting EU Green Deal traceability mandates while standardizing chlorogenic acid yields for nutraceutical buyers.
Growth Catalysts
- EU Green Deal circular economy mandates:The regulation accelerates ingredient traceability requirements, forcing functional beverage manufacturers to source certified upcycled inputs with verified chain-of-custody documentation.
- Specialty coffee culture convergence:United States wellness product innovation channels now absorb cascara-derived extracts for antioxidant positioning, creating pull-through from premium roast-to-retail networks.
- Supercritical CO2 extraction:This solvent-free processing technology preserves polyphenol integrity while meeting clean-label manufacturing standards demanded by dietary supplement formulators.
Market Restraints
- Raw material geographic concentration:Coffee cherry waste availability clusters in Brazil, Colombia, and Ethiopia, exposing processors to harvest volatility and single-origin supply disruptions.
- EFSA novel food consultation timelines:European market entry requires 18-24 month safety dossier reviews, compressing first-mover advantage windows for new extract suppliers.
- Green tea extract substitution:Established catechin-based antioxidants compete on price and clinical substantiation, forcing coffee fruit extract to differentiate on sustainability credentials alone.
Strategic Opportunities
- South Korean functional beauty channel:MFDS cosmetic ingredient registrations enable entry into K-beauty anti-aging formulations where polyphenol sourcing stories command premium positioning.
- Direct-to-consumer subscription models:Single-origin coffee fruit supplements bypass traditional retail slotting fees, capturing full margin from antioxidant-seeking wellness consumers.
- ISO 22000 certification arbitrage:Facilities achieving this food safety management standard unlock contract manufacturing partnerships with multinational functional food brands seeking qualified suppliers.
Industry Challenges
- Botanical extraction talent scarcity:Specialized workforce capable of stabilizing chlorogenic acid across formulation types remains concentrated in Swiss and French flavor houses.
- HACCP facility capex requirements:Hazard analysis infrastructure for coffee fruit processing demands seven-figure equipment investments that exclude smaller agricultural cooperatives.
- Antioxidant claim substantiation fragmentation:Divergent FDA GRAS self-affirmation and EFSA health claim evaluation standards force parallel safety dossier development for transatlantic market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Fruit Extract Market |
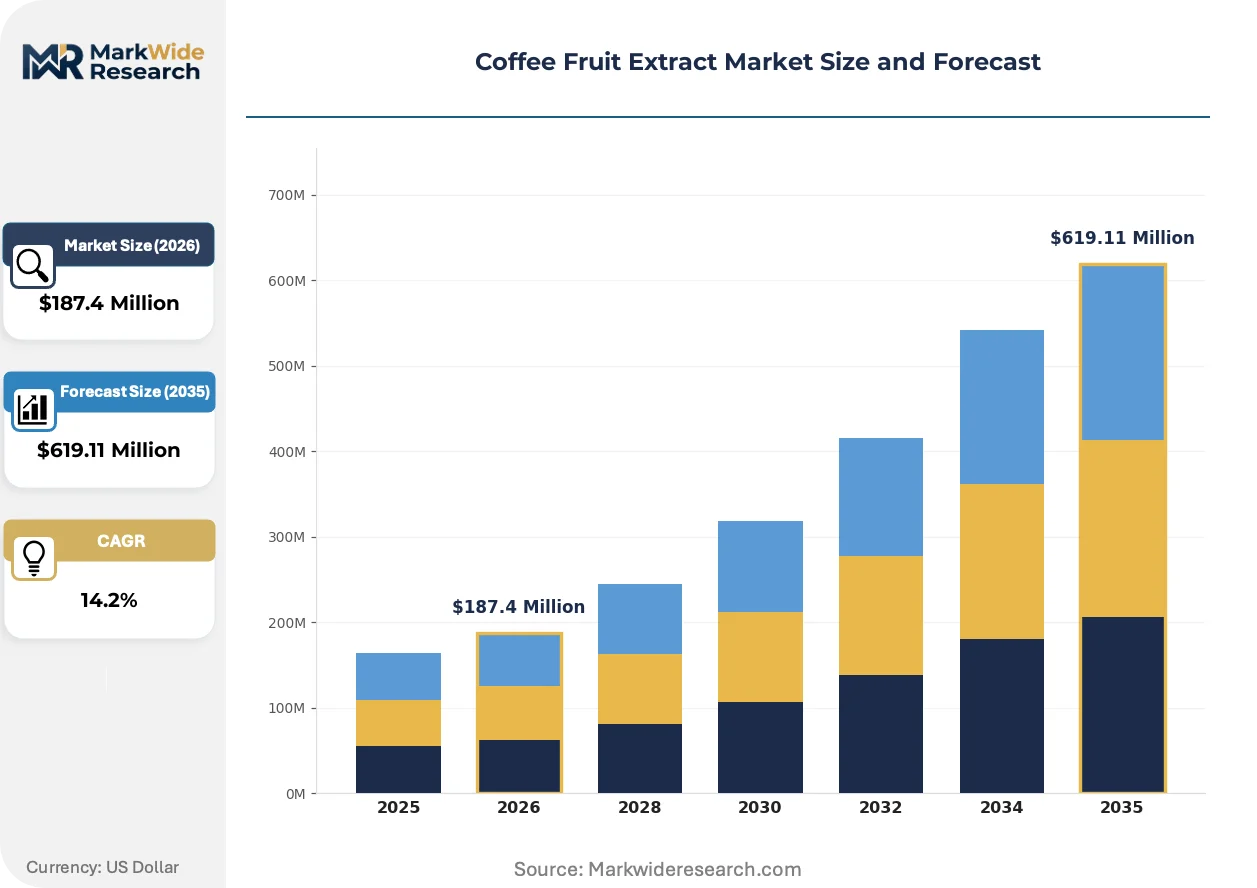
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pulp, Seed, Green Coffee Bean, Powder End User: Food & Beverage, Pharmaceuticals, Nutraceuticals, Cosmetics Application: Dietary Supplements, Functional Foods, Skincare Products, Beverages Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores |
| Companies Covered | Tate & Lyle, Synergy Flavors, Givaudan, NatureWise, Pure Svetol, Firmenich, Olam International, Sports Research, Naturex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Fruit Extract Market Evolving Landscape
Extraction technology convergence with sustainability verification systems is compressing development cycles for standardized nutraceutical inputs while reshaping buyer qualification criteria.
Supercritical fluid extraction is hybridizing with membrane filtration to produce coffee fruit extracts with tighter polyphenol standardization. Dietary supplement contract manufacturers in Germany and Switzerland adopt these integrated systems to reduce batch-to-batch variability. The technology is hybridizing quality assurance and production throughput, enabling just-in-time supply agreements with multinational functional food brands.
EFSA novel food consultation requirements are tightening substantiation standards for antioxidant health claims across European channels. This regulatory pressure forces extract suppliers to commission clinical trials on cognitive and metabolic endpoints before market entry. Dietary supplement applications face the steepest compliance burden, with several suppliers redirecting initial launch volumes toward less regulated cosmetic ingredient channels.
Clean-label procurement criteria now prioritize upcycled ingredient certifications over conventional organic claims. Functional beverage formulators in California and Pacific Northwest markets substitute coffee fruit extract for synthetic antioxidants, driven by retail buyer sustainability scorecards. This preference shift concentrates contract volumes with suppliers possessing third-party waste-stream verification from coffee processing cooperatives.
Coffee Fruit Extract Market Segmentation
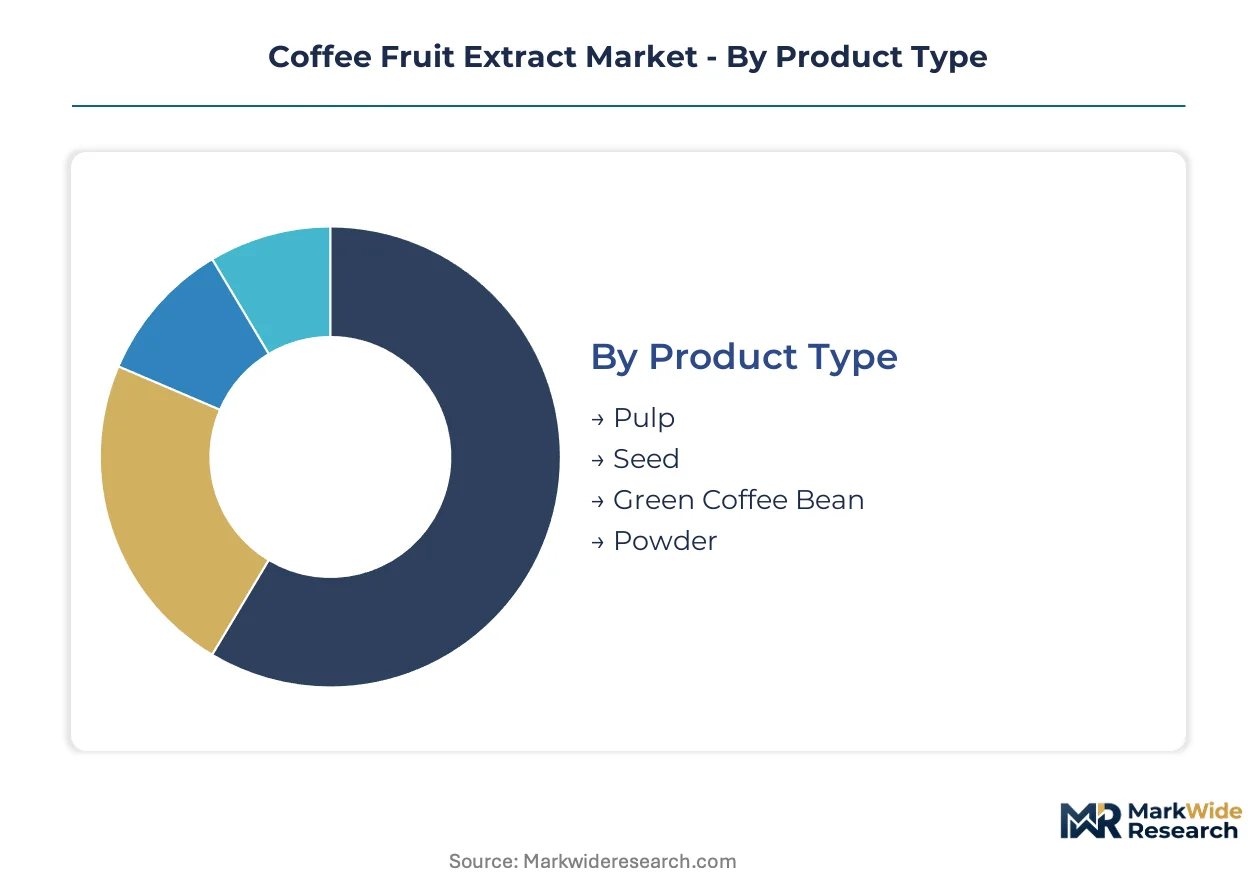
Segmentation in coffee fruit extract markets reveals how extraction technology maturity and end-use regulatory thresholds partition commercial opportunity. Buyers qualify suppliers through product format specifications and channel access credentials that vary sharply across pharmaceutical versus cosmetic applications.
Product Type:
Mature formats dominate commercial volumes while emerging extraction targets reshape supplier R&D allocation.
- Pulp:Cascara-derived concentrates standardized to 40-70% polyphenol content anchor upcycled supply chains. Brazilian and Colombian wet-mill cooperatives now certify pulp streams for EU Green Deal traceability compliance, though harvest seasonality compresses contract pricing windows.
- Powder:Spray-dried and freeze-dried formats deliver shelf stability exceeding 24 months for dietary supplement manufacturers. German contract manufacturers prioritize powder inputs for blending flexibility in high-speed encapsulation lines.
- Seed:Coffee cherry seed fractions contain distinct lipid profiles separate from roasted coffee bean chemistry. Specialty oil extractors in Ethiopia pilot cold-press seed oils for K-beauty facial serum applications.
- Green Coffee Bean:Unroasted bean extracts retain higher chlorogenic acid stability than thermally processed alternatives. Swiss flavor houses integrate these fractions into functional beverage prototypes requiring clean-label antioxidant positioning.
Powder handles the majority of throughput; pulp is the fastest mover on share.
End User:
Regulatory burden intensity separates premium-margin channels from commodity-adjacent applications.
- Food & Beverage:Functional beverage formulators in California and Pacific Northwest markets substitute coffee fruit extract for synthetic antioxidants. Retail buyer sustainability scorecards now mandate third-party waste-stream verification for upcycled ingredient procurement.
- Cosmetics:Anti-aging formulations incorporate coffee fruit polyphenols for oxidative stress protection claims. South Korean MFDS cosmetic ingredient registrations enable premium positioning in K-beauty channels where sourcing narratives command price premiums.
- Nutraceuticals:Dietary supplement applications face steep EFSA novel food consultation timelines, forcing parallel dossier development for transatlantic market access.
- Pharmaceuticals:Clinical-grade extract specifications require GMP-compliant facilities with ISO 22000 certification. The compliance threshold excludes smaller agricultural cooperatives from contract manufacturing partnerships.
Food & Beverage absorbs the largest volume base; Cosmetics is climbing the fastest on margin contribution.
Application:
Claim substantiation requirements fragment addressable market entry by regulatory jurisdiction.
- Dietary Supplements:Cognitive health and metabolic support positioning drives antioxidant-seeking wellness consumer demand. Direct-to-consumer subscription models bypass traditional retail slotting fees for single-origin coffee fruit supplements.
- Skincare Products:Cosmetic chemists formulate polyphenol-rich serums targeting photoaging and barrier function repair. The segment is expanding most quickly as suppliers redirect initial launch volumes from heavily regulated supplement channels.
- Functional Foods:Clean-label fortification in snack and bakery applications leverages coffee fruit extract's upcycled sustainability credentials for ESG-aligned procurement.
- Beverages:Ready-to-drink antioxidant waters and functional coffee hybrids integrate cascara-derived extracts for dual-origin storytelling.
Dietary Supplements commands premium pricing; Skincare Products is gaining share fastest on regulatory arbitrage.
Distribution Channel:
Channel control determines margin capture and consumer education depth for novel ingredient categories.
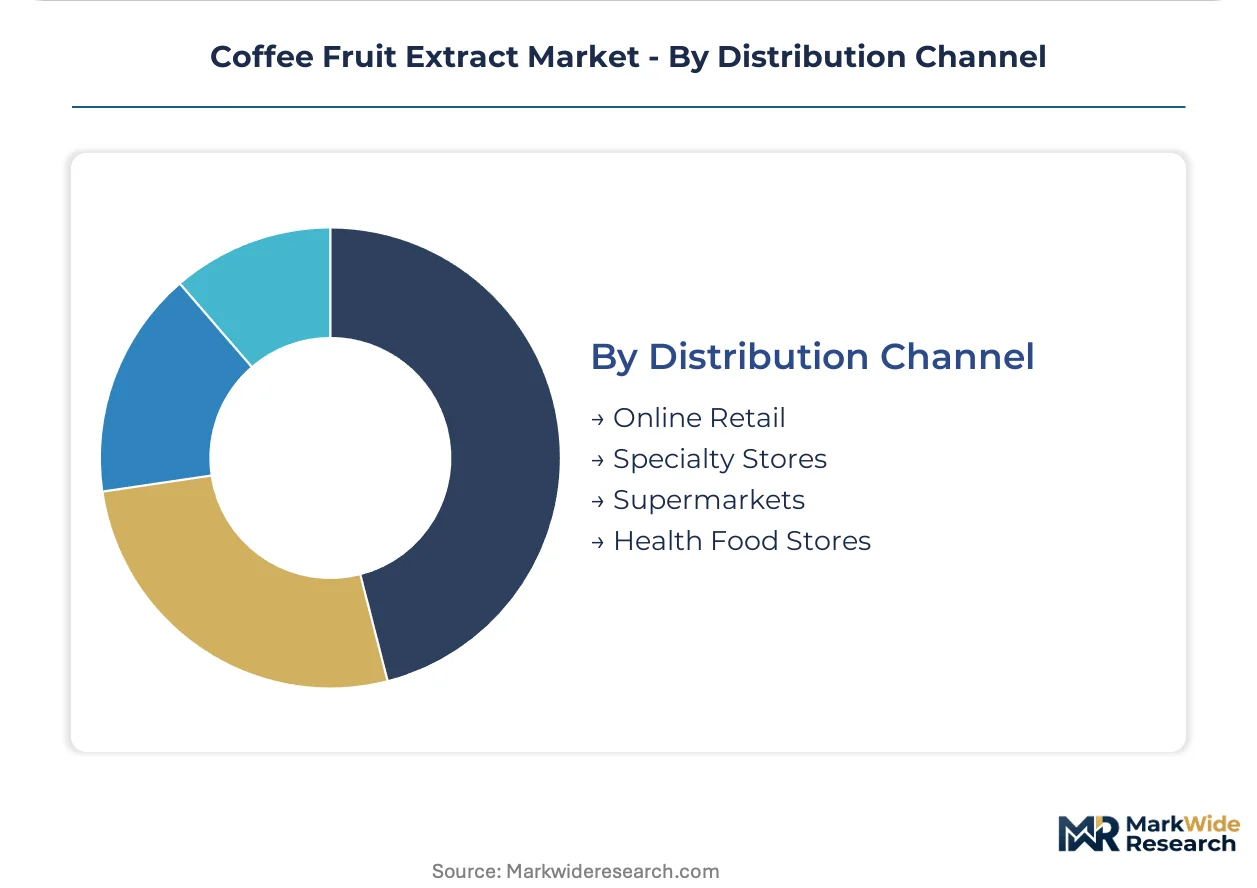
- Online Retail:Direct-to-consumer platforms enable full margin retention and subscription-based replenishment for antioxidant-seeking wellness segments. NatureWise and comparable brands anchor customer acquisition through single-origin provenance storytelling.
- Health Food Stores:Staff-assisted consultation supports complex ingredient education for polyphenol-standardized products. The channel qualifies premium pricing through third-party certification verification.
- Specialty Stores:Premium roast-to-retail networks in United States specialty coffee culture channels absorb cascara-derived extracts for crossover wellness positioning.
- Supermarkets:Mass retail slotting fees and sustainability scorecard compliance compress margins for smaller extract suppliers lacking scale economies.
Online Retail captures the highest growth trajectory; Health Food Stores maintains the deepest margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian wet-mill cooperatives export cascara-derived pulp concentrates to German contract manufacturers and US functional beverage formulators, establishing the dominant trade-flow corridor for upcycled coffee fruit extract.
United States
Specialty coffee culture in California and the Pacific Northwest drives antioxidant-seeking wellness demand. FDA GRAS self-affirmation pathways govern dietary supplement entry. Seattle and Portland roasting networks now certify cascara waste streams for third-party sustainability verification.
Germany
Contract manufacturers in Bavaria and Baden-Württemberg absorb spray-dried powder inputs for high-speed encapsulation lines. EFSA novel food consultation requirements compress first-mover advantage windows. Swiss-border extraction facilities near Basel concentrate supercritical CO2 processing capability.
Brazil
Wet-mill cooperatives in Minas Gerais and São Paulo anchor global pulp supply with EU Green Deal traceability certification. Harvest seasonality exposes processors to raw material volatility. Campinas-based agricultural clusters pilot membrane filtration integration for tighter polyphenol standardization.
South Korea
K-beauty anti-aging formulations command premium positioning for polyphenol sourcing narratives. MFDS cosmetic ingredient registrations enable market entry with lower regulatory burden than nutraceutical channels. Seoul-based formulators integrate coffee fruit extracts into facial serum applications.
Switzerland
Flavor houses in Geneva and Zurich preserve chlorogenic acid stability across beverage formulation types. ISO 22000 certification unlocks multinational brand partnerships. Basel-region extraction talent concentrates botanical stabilization expertise for standardized nutraceutical inputs.
Coffee Fruit Extract Market Competitive Landscape
On the supply side, the industry is consolidating around extraction facilities capable of meeting EU Green Deal traceability mandates while maintaining chlorogenic acid yields. Three archetypes dominate: flavor houses with botanical infrastructure, direct-to-consumer supplement brands, and agricultural traders with wet-mill network control. Competitive moves concentrate on ISO 22000 certification arbitrage and supercritical CO2 capacity expansion.
Within the flavor-system tier, Tate & Lyle and Givaudan exemplify botanical extraction specialists leveraging existing infrastructure for coffee fruit integration. NatureWise occupies a position in the direct-to-consumer archetype, anchoring subscription-based channels with single-origin provenance storytelling. These three represent distinct competitive vectors: B2B ingredient supply, B2C brand building, and formulation technology licensing.
| Leading Market Players |
|---|
| Tate & Lyle |
| Synergy Flavors |
| Givaudan |
| NatureWise |
| Pure Svetol |
| Firmenich |
| Olam International |
| Sports Research |
| Naturex |
| Others |
Value Network & Pricing Analysis
Brazilian wet-mill cooperative concentration in Minas Gerais and São Paulo anchors raw material availability, pushing margin pools downstream toward extraction facilities with EU Green Deal traceability certification and ISO 22000 credentials.
Pricing Analysis
Prior-generation spray-dried powder formats trade at commodity-adjacent levels while supercritical CO2 extracts command formulation-grade premiums. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified pharmaceutical inputs from cosmetic-grade polyphenols and beverage-grade cascara concentrates. Cost compression in standard-tier pulp supplies is intensifying because harvest seasonality compresses contract windows. Dietary supplement manufacturers exhibit highest price sensitivity due to EFSA novel food consultation cost burdens, while K-beauty formulators absorb premium positioning for MFDS-registered cosmetic ingredients.
Supply Chain Analysis
Single-source vulnerability between Brazilian wet-mill cooperatives and German contract manufacturers dominates supply chain risk architecture. Raw material availability clusters in Brazil, Colombia, and Ethiopia, drawing from coffee cherry waste streams, chlorogenic acid standardization equipment, and third-party sustainability verification systems. Distribution runs through Swiss flavor houses for formulation technology licensing and direct-to-consumer platforms for margin retention. Tariff exposure on processed extract shipments to European channels compounds geographic concentration risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment models for single-origin coffee fruit supplements expand faster than commodity pulp trading, creating service-attach opportunities that recapture margin from traditional agricultural trading margins.
For Market Incumbents: Build traceability moats through backward integration into wet-mill cooperative networks. Secure EU Green Deal chain-of-custody certification ahead of 2025 compliance deadlines. Expand supercritical CO2 capacity in Basel-region facilities to defend against green tea extract substitution threats.
For New Entrants and Emerging Players: South Korean MFDS cosmetic ingredient registrations represent the most penetrable entry point given lower regulatory burden than EFSA novel food pathways. Direct-to-consumer subscription models for antioxidant-seeking wellness consumers bypass retail slotting fees. Anchor customer acquisition through single-origin provenance storytelling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flavor houses seeking botanical extraction diversification. Five-to-ten year viability hinges on clinical trial substantiation for cognitive health claims. Watch EFSA health claim evaluation standards as the inflection signal for nutraceutical channel reopening.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Development | Clinical trials on metabolic endpoints unlock European nutraceutical channel access. |
| ISO 22000 Certification Investment | Food safety credentials qualify suppliers for multinational functional brand partnerships. |
| Supercritical CO2 Capacity Expansion | Solvent-free processing preserves chlorogenic acid integrity for clean-label positioning. |
| Direct-to-Consumer Platform Launch | Subscription models capture full margin from antioxidant-seeking wellness segments. |
| Wet-Mill Cooperative Integration | Upstream control over cascara waste streams secures EU Green Deal traceability compliance. |
Research Methodology
Operator-level perspectives from extraction facility managers, dietary supplement formulators, cosmetic chemists, and wet-mill cooperative directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA GRAS notification databases, EFSA novel food consultation registers, and ISO 22000 certification records. Bottom-up volume triangulation across pulp, powder, seed, and green coffee bean formats converged with top-down value estimates derived from trade flow analysis between Brazilian agricultural clusters and European contract manufacturers.
Scenario-bracketing framed the analytical approach across the analysis window, modeling product type, end-user regulatory burden, application claim substantiation requirements, and distribution channel control dimensions. CAGRs derived from segment-level growth differentials applied to base-year volume estimates. Forecast inputs incorporated EU Green Deal implementation timelines and MFDS cosmetic registration pathway acceleration.
Macroeconomic conditions sit as an overlay; deviation in coffee commodity price volatility and transatlantic shipping cost structures would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory consultation timelines and clinical trial completion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Pods Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Europe Coffee Market
Coffee
Latin America Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Espresso Powder Market
Coffee
Australia Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Brewers Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Out-Of-Home Coffee Market
Coffee
China Coffee Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Coffee Roaster Machine Market
Coffee
Portable Espresso Machines Market