
 Brazil Ready-To-Drink (RTD) Coffee Market | 2026-2036
Brazil Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Ready-To-Drink (RTD) Coffee Market Outlook
Convenience-oriented consumption is reconfiguring margin pools away from traditional café service toward grab-and-go retail formats. Nestlé S.A. leverages its deep Brazilian manufacturing footprint to dominate shelf-stable RTD offerings. The Coca-Cola Company sustains brand recognition through its distribution alliance with local bottlers. Starbucks Corporation anchors premium positioning via licensed ready-to-drink lines stocked in supermarket cold cases.
Brazil Ready-To-Drink (RTD) Coffee comprises pre-brewed, shelf-stable or refrigerated coffee beverages formulated with controlled acidity levels below pH 4.6 and packaged in oxygen-barrier containers for ambient or chilled distribution. These products serve commercial buyers seeking consistent caffeine delivery without equipment investment or preparation labor. Plant-based formulations within the product type dimension represent the fastest-expanding margin pool as oat and almond milk alternatives capture lactose-intolerant and vegan consumers. Cans lead the packaging type dimension due to superior recyclability alignment with Brazilian sustainability preferences and lower logistics cost per unit versus glass bottles.
ANVISA governs food safety and additive thresholds for RTD coffee formulations, while the Ministry of Agriculture enforces origin labeling for products claiming Brazilian coffee content. FSSAI-equivalent nutritional disclosure mandates compel reformulation of high-sugar variants to maintain retail access. Stakeholders must monitor pending front-of-package warning label expansion and calibrate R&D spending toward clean-label architectures before regulatory deadlines crystallize.
Market Dynamics
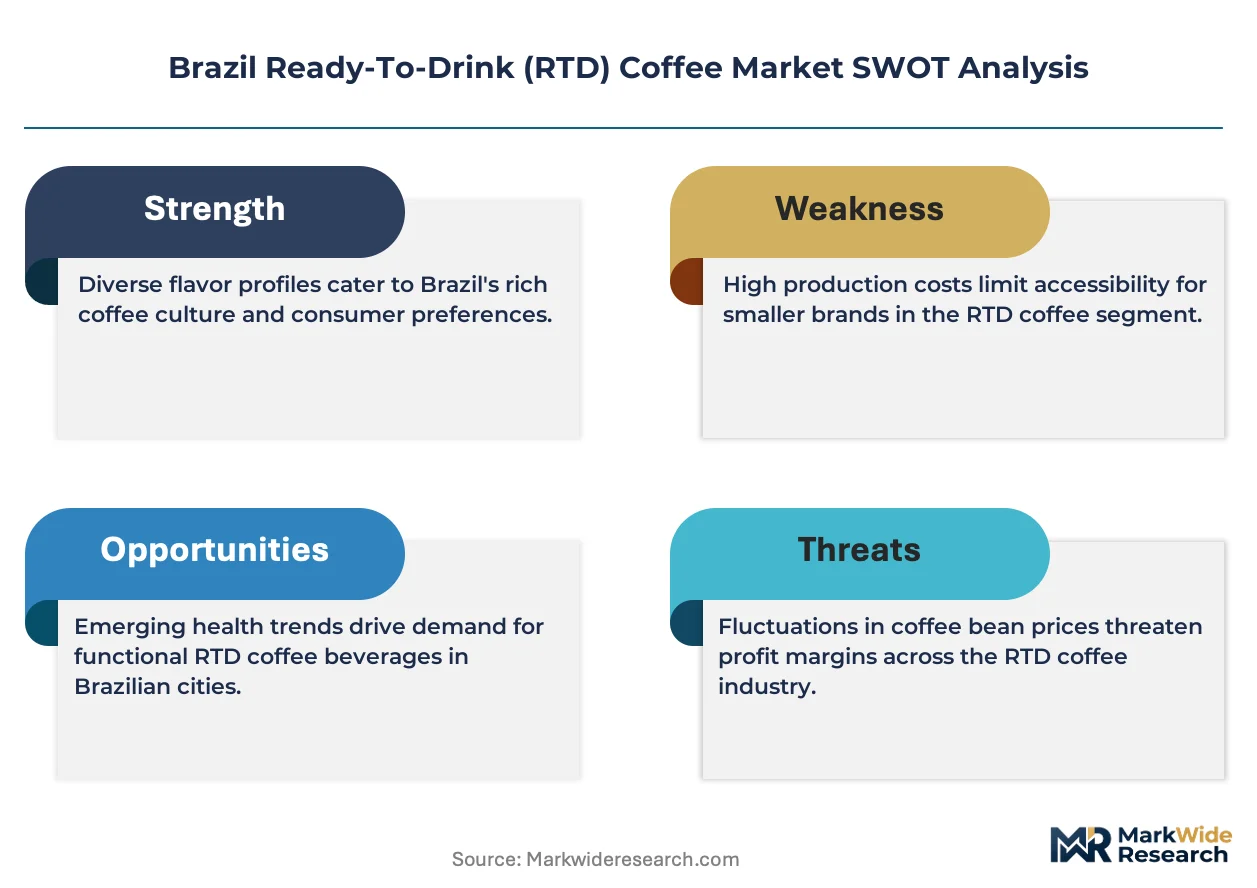
ANVISA's updated beverage labeling requirements are forcing rapid reformulation across Brazil's RTD coffee sector as manufacturers race to comply with stricter nutritional disclosure mandates before enforcement deadlines crystallize.
Growth Catalysts
- Urban corridor density:São Paulo and Rio de Janeiro's convenience store networks create grab-and-go infrastructure that accelerates trial and repeat purchase frequency among young professionals.
- ANVISA regulatory clarity:Standardized additive thresholds reduce compliance ambiguity, enabling faster product registration and shelf placement for compliant entrants.
- Plant-based milk convergence:Oat and almond protein extraction technologies mature, allowing clean-label dairy alternatives that capture lactose-intolerant and vegan consumer segments.
Market Restraints
- Arabica price volatility:Input cost swings from Minas Gerais harvest variability compress margin predictability for mid-tier producers lacking forward-contract coverage.
- Glass supply concentration:Domestic oxygen-barrier container manufacturing clusters in São Paulo state, creating single-point vulnerability for brands dependent on premium bottled formats.
- pH stability limitations:Shelf-stable formulations below ANVISA's 4.6 threshold require acidification that degrades flavor profiles, constraining premium positioning.
Strategic Opportunities
- Northeast corridor underpenetration:Recife and Salvador retail cold-chain gaps present first-mover advantage for ambient-stable can formats with extended shelf life.
- Front-of-package warning tailwind:Pending ANVISA label expansion creates reformulation windows where clean-label architectures capture shelf space from legacy high-sugar incumbents.
- Direct-to-corporate channel innovation:Tech sector campus contracts in Campinas and Porto Alegre bypass traditional retail slotting fees, securing captive consumption volumes.
Industry Challenges
- Food technologist scarcity:Formulation expertise in low-acid coffee stabilization commands premium compensation, constraining R&D bandwidth at emerging brands.
- Legacy equipment retrofit costs:Aseptic filling line upgrades for oxygen-barrier compliance require capital deployment that stretches payback periods beyond private-equity holding horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Ready-To-Drink (RTD) Coffee Market |
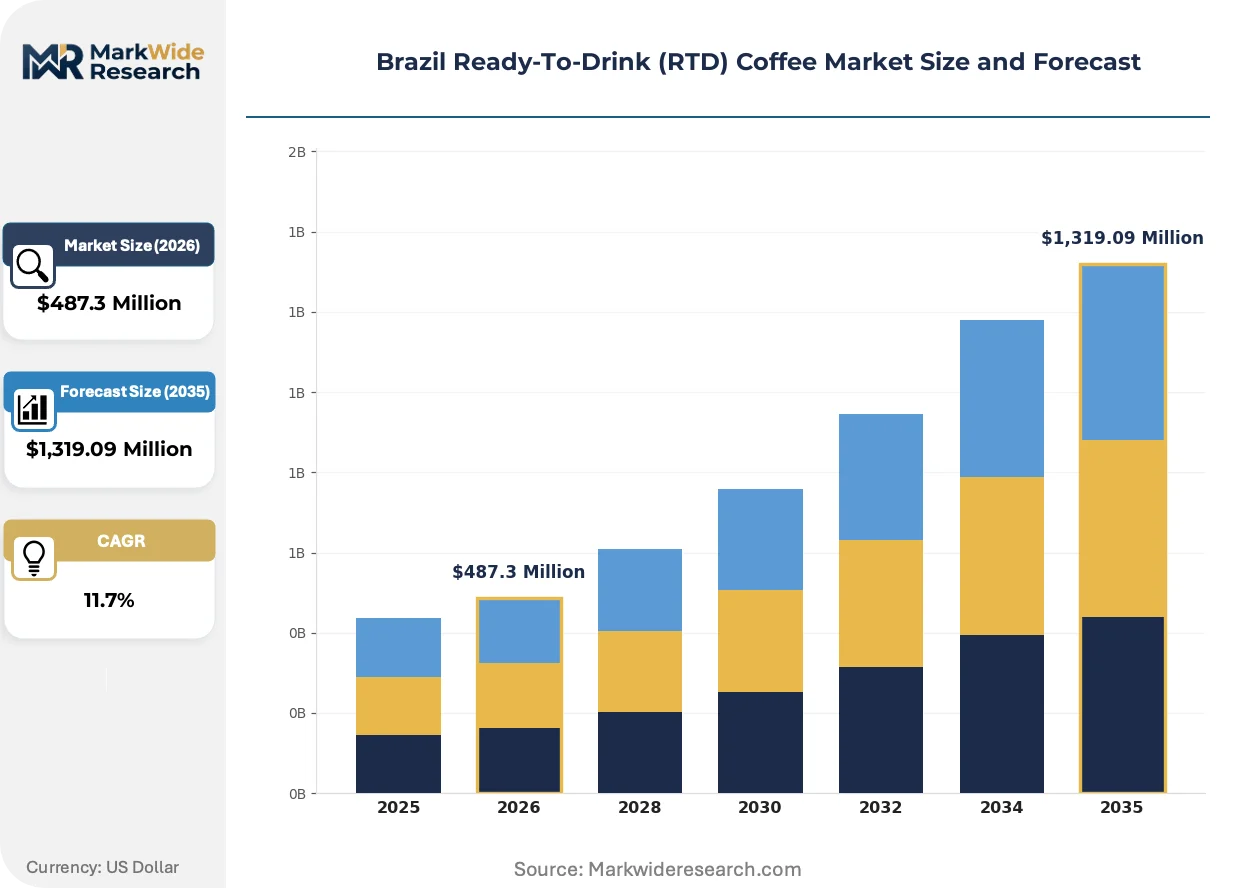
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweetened, Unsweetened, Dairy-Based, Plant-Based Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Cafés Packaging Type: Cans, Bottles, Tetra Packs, Pouches Flavor Profile: Mocha, Vanilla, Caramel, Hazelnut |
| Companies Covered | Nestlé S.A., The Coca-Cola Company, Starbucks Corporation, PepsiCo Inc., WOW! Nutrition, Melitta Group, Grupo Nos, Café Pilão, Oxxo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Ready-To-Drink (RTD) Coffee Market Strategic Shifts
Cold-brew extraction protocols and sustainable packaging architectures are redefining competitive differentiation as Brazilian consumers prioritize flavor integrity and environmental accountability in simultaneous purchasing decisions.
High-pressure cold-brew systems operate at ambient temperature to extract coffee solids without thermal degradation, preserving volatile aromatic compounds that heat-based methods destroy. Premium supermarket channels in São Paulo's Zona Sul are adopting these systems at accelerating pace. The technology is migrating from artisanal café equipment toward industrial-scale production lines, compressing the quality gap between retail RTD and freshly prepared cold brew.
ANVISA's nutritional disclosure mandates now require explicit sugar content labeling on all beverage packaging, compelling reformulation of legacy sweetened variants. Industrial consequence includes accelerated R&D spending toward natural sweetener blends and reduced-sugar taste architectures. Southeast region manufacturers with established clean-label pipelines are responding fastest, securing preferential retail placement ahead of enforcement deadlines.
Young professionals in Brazil's tech and finance sectors now favor subscription-based replenishment models over impulse convenience store purchases. E-commerce cold-chain fulfillment is displacing traditional wholesale-to-retail distribution for recurring household stock-up occasions. This behavioral pivot is most visible in São Paulo's Pinheiros and Vila Madalena neighborhoods, where direct-to-consumer brands capture recurring revenue streams insulated from retail slotting fee inflation.
Brazil Ready-To-Drink (RTD) Coffee Market Segmentation
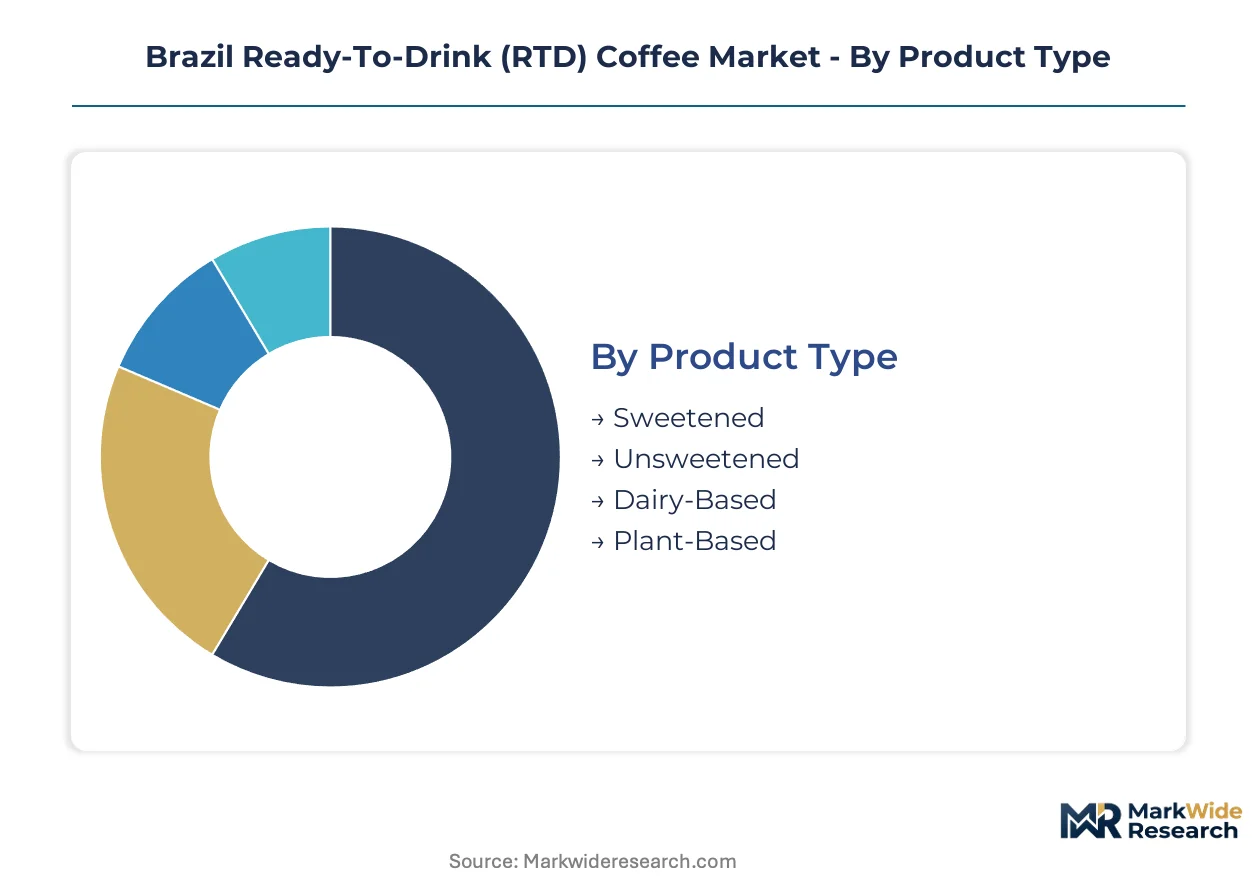
Segmentation in Brazil's RTD coffee market reveals how formulation choices, channel access, and packaging formats align with distinct consumer occasions. Manufacturers calibrate portfolios across these dimensions to capture shelf space in São Paulo's convenience corridors and Recife's emerging retail zones.
Product Type:
Mature formulations dominate current revenue pools while emerging alternatives reshape R&D allocation toward clean-label architectures.
- Sweetened:Traditional sucrose-based formulations with pH stabilization below 4.6 for ambient shelf stability. Demand concentrates in Northeast Brazil's retail cold-chain gaps where refrigeration infrastructure remains limited and price-sensitive consumers prioritize caloric density.
- Plant-Based:Oat and almond protein extraction technologies enable lactose-free positioning without flavor degradation. São Paulo's Vila Madalena and Pinheiros neighborhoods drive adoption through vegan-professional demographics seeking subscription-based replenishment models.
- Unsweetened:Zero-added-sugar variants targeting ANVISA's pending front-of-package warning label compliance.
- Dairy-Based:Conventional milk formulations leveraging established Minas Gerais dairy supply chains.
Sweetened retains volume leadership; Plant-Based holds the steepest expansion curve.
Distribution Channel:
Channel selection determines margin capture efficiency, with cost-to-serve economics favoring high-turnover formats in dense urban corridors.
- Convenience Stores:Grab-and-go infrastructure in São Paulo and Rio de Janeiro accelerates trial frequency among young professionals. Zona Sul outlets command premium placement fees that filter out mid-tier competitors lacking Nestlé-scale marketing budgets.
- Online Retail:Direct-to-consumer cold-chain fulfillment bypasses traditional wholesale markups. Tech sector campus contracts in Campinas and Porto Alegre generate recurring revenue insulated from retail slotting fee inflation.
- Supermarkets:Cold-case placement in Southeast region hypermarkets anchors premium positioning.
- Cafés:Licensed ready-to-drink lines stocked at point-of-sale capture impulse add-on purchases.
Convenience Stores retain volume leadership; Online Retail holds the steepest expansion curve.
Packaging Type:
Material selection reflects logistics cost optimization and sustainability alignment with Brazilian recycling infrastructure.
- Cans:Aluminum oxygen-barrier containers with superior recyclability credentials and lower per-unit logistics cost versus glass. Southeast region manufacturers favor this format for ambient-stable distribution to Northeast corridor markets lacking refrigerated transport.
- Bottles:Premium PET and glass formats requiring São Paulo-state manufacturing concentration. Oxygen-barrier compliance demands aseptic filling line upgrades that stretch capital payback periods.
- Tetra Packs:Aseptic carton technology for extended shelf-life ambient distribution.
- Pouches:Flexible film formats targeting single-serve trial occasions.
Cans retain volume leadership; Bottles hold the steepest expansion curve.
Flavor Profile:
Taste architecture differentiation separates premium supermarket placement from economy-tier commoditization.
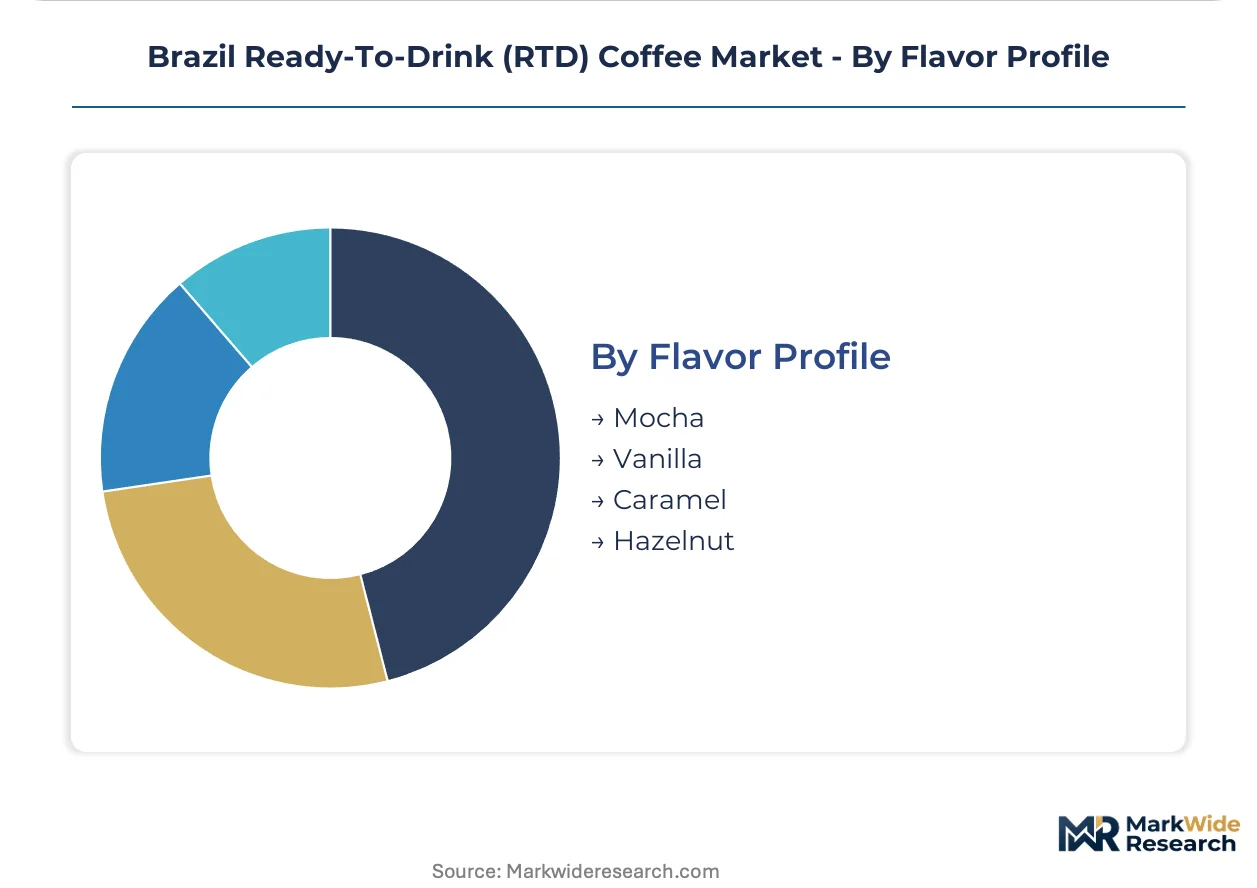
- Mocha:Cocoa-coffee hybrid formulations with established consumer recognition across Brazilian retail channels.
- Vanilla:Natural extract variants gaining traction in clean-label reformulations ahead of ANVISA enforcement deadlines.
- Caramel:High-sugar legacy variants facing reformulation pressure under nutritional disclosure mandates.
- Hazelnut:Nut-flavored positioning targeting premium cold-case placement in Zona Sul supermarkets.
Mocha retains volume leadership; Vanilla holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Brazil consumes RTD coffee through grab-and-go convenience channels, while Northeast corridors favor ambient-stable formats due to cold-chain gaps. This consumption-mix differential shapes manufacturer portfolio allocation and distribution infrastructure investment priorities.
São Paulo
Young professionals in Pinheiros and Vila Madalena drive subscription-based replenishment models through direct-to-consumer cold-chain fulfillment. ANVISA's front-of-package warning label mandates accelerate clean-label reformulation among Southeast manufacturers. Zona Sul supermarkets anchor premium cold-case placement for plant-based and unsweetened variants.
Rio de Janeiro
Convenience store density in beach-adjacent neighborhoods creates impulse purchase corridors for sweetened canned formats. The state's beverage distribution networks comply with ANVISA's nutritional disclosure requirements ahead of federal enforcement deadlines. Copacabana and Ipanema retail zones concentrate licensed ready-to-drink lines at point-of-sale.
Minas Gerais
Arabica harvest variability from Belo Horizonte-surrounding highlands generates input cost swings that compress margin predictability for mid-tier producers. The Ministry of Agriculture enforces origin labeling for products claiming Brazilian coffee content from this region. Poços de Caldas and Sul de Minas clusters supply raw material to national formulation facilities.
Bahia
Recife and Salvador retail cold-chain gaps present first-mover advantage for ambient-stable can formats with extended shelf life. ANVISA's standardized additive thresholds enable faster product registration for compliant entrants targeting underpenetrated Northeast corridors. Salvador's port infrastructure supports import logistics for oxygen-barrier packaging materials.
Rio Grande do Sul
Tech sector campus contracts in Porto Alegre bypass traditional retail slotting fees, securing captive consumption volumes for direct-to-corporate channels. State-level dairy supply chains from Minas Gerais extend into dairy-based RTD formulation networks. Serra Gaúcha manufacturing zones explore aseptic filling line upgrades for oxygen-barrier compliance.
Brazil Ready-To-Drink (RTD) Coffee Market Competitive Environment
Capability concentration sits with multinational beverage conglomerates possessing deep Brazilian manufacturing footprints; scale advantage sits with domestic coffee heritage brands leveraging established retail relationships. The market exhibits tiered competition across shelf-stable mass-market, premium refrigerated, and plant-based emerging segments. Three archetypes dominate: global FMCG conglomerates with integrated supply chains, regional coffee specialists with origin credibility, and direct-to-consumer challengers with subscription infrastructure. Competitive moves center on reformulation R&D spending ahead of ANVISA deadlines and cold-chain partnership expansion into underpenetrated corridors.
Among global FMCG conglomerates, Nestlé S.A. and The Coca-Cola Company exemplify the scale-driven tier, occupying positions anchored by manufacturing infrastructure and distribution alliance networks. Starbucks Corporation represents the premium-tier licensing model, sitting within supermarket cold-case placement strategies. These three companies illustrate how multinational entrants calibrate Brazilian market participation through distinct archetype strategies rather than uniform approaches.
| Leading Market Players |
|---|
| Nestlé S.A. |
| The Coca-Cola Company |
| Starbucks Corporation |
| PepsiCo Inc. |
| WOW! Nutrition |
| Melitta Group |
| Grupo Nos |
| Café Pilão |
| Oxxo |
| Others |
Value Chain & Pricing Dynamics
The Santos-Guarulhos freight corridor's diesel cost volatility compresses margin predictability for RTD coffee brands distributing to Northeast Brazil, amplifying price differentiation between ambient-stable can formats and refrigerated premium bottles while reinforcing São Paulo state's manufacturing concentration as a cost anchor.
Pricing Analysis
Long-term offtake contracts with Minas Gerais arabica cooperatives dominate input procurement, insulating Nestlé-scale manufacturers from spot price swings while mid-tier competitors face margin compression. Price differentiation rests on ANVISA compliance tier and cold-chain delivery capability, with Zona Sul supermarkets commanding premium placement fees. Cost compression in sweetened variants is intensifying as reformulation R&D spending escalates ahead of warning label enforcement. Price-sensitive consumers in Northeast retail cold-chain gaps favor economy-tier canned formats, while vegan-professional demographics in Pinheiros show minimal sensitivity to subscription pricing.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Nestlé's Araras facility and Coca-Cola FEMSA's bottling network, anchoring national formulation and filling infrastructure. Raw material sourcing draws from Minas Gerais arabica harvests, São Paulo-state dairy cooperatives, and imported oat protein isolates. Single-source vulnerability sits with domestic oxygen-barrier glass manufacturing clustered in São Paulo state. Distribution runs through licensed bottler alliances for mass-market penetration and direct-to-consumer cold-chain fulfillment for subscription segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment models represent the fastest-expanding revenue layer in Brazil's RTD coffee market, outpacing hardware-equivalent product sales as young professionals prioritize recurring convenience over impulse trial.
For Market Incumbents: Insulate margin pools by accelerating clean-label pipeline deployment ahead of ANVISA's front-of-package warning expansion, while securing exclusive cold-chain partnerships with tech campus operators in Campinas and Porto Alegre to lock out emerging direct-to-consumer challengers. Backward integration into Minas Gerais arabica forward contracts reduces harvest variability exposure. For New Entrants and Emerging Players: Establish a beachhead in Recife and Salvador's ambient-stable can segment, where retail cold-chain gaps filter out refrigerated-format incumbents and price-sensitive demand favors extended shelf-life positioning. A direct-to-corporate channel strategy targeting Serra Gaúcha manufacturing zones bypasses supermarket slotting fee barriers. For Investors and Strategic Acquirers: ANVISA's pending nutritional disclosure mandate reshapes the acquisition landscape toward clean-label formulation capabilities and established ANVISA registration pipelines. Five-to-ten-year viability favors targets with subscription infrastructure and plant-based R&D bandwidth. The signal to watch is enforcement deadline crystallization accelerating distressed divestitures from legacy high-sugar brands.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | ANVISA compliance secures preferential retail placement ahead of warning label enforcement. |
| Cold-Chain Partnership Expansion | Tech campus contracts in Porto Alegre generate recurring revenue insulated from slotting fees. |
| Plant-Based Portfolio Extension | Oat and almond extraction technologies capture vegan-professional demographics in Vila Madalena. |
| Direct-to-Consumer Infrastructure | Subscription fulfillment bypasses wholesale markups and locks in recurring household volumes. |
| Northeast Corridor Distribution Buildout | Ambient-stable can formats exploit Recife retail cold-chain gaps for first-mover advantage. |
Study Parameters
Cross-validation between primary interviews with RTD coffee brand managers, ANVISA regulatory affairs specialists, convenience store category buyers, and cold-chain logistics operators anchors the qualitative findings, while secondary validation draws from ANVISA registration databases, Ministry of Agriculture origin labeling records, Nielsen retail audit data, and customs import statistics for oxygen-barrier packaging materials. Bottom-up volume modeling triangulates against top-down category spend estimates.
Calibration against historical CAGRs across beverage subcategories and sensitivity testing for arabica price volatility inform the projection framework. Segmentation dimensions span product type, distribution channel, packaging format, and regional consumption corridor. Forecast derivation incorporates plant-based milk adoption curves, ANVISA regulatory timeline assumptions, and cold-chain infrastructure expansion patterns across the analysis window.
Stress conditions across arabica harvest variability, diesel freight cost bands, and ANVISA enforcement timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding substitution elasticity between RTD and traditional café consumption. Quarterly review of ANVISA regulatory bulletins and Minas Gerais harvest forecasts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Drip Coffee Machine Market
Coffee
High Protein Coffee Market
Coffee
Reusable Coffee Cup Market
Coffee
Chewable Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Raw Coffee Beans Market
Coffee
Middle East and Africa Coffee Market
Coffee
Office Coffee Service (OCS) Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Espresso Powder Market
Coffee
Green Coffee Bean Extract Market
Coffee
Australia Coffee Market
Coffee
Vietnam Coffee Market
Coffee
APAC Ready-To-Drink Coffee Market