
 Brewing Boiler Market | 2026-2036
Brewing Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Brewing Boiler Market Outlook
China is fragmenting as regional equipment makers expand stainless-steel fabrication capacity for mid-sized brewing systems. Anheuser-Busch InBev SA/NV leverages vertical integration across its megabreweries to standardize boiler specifications globally. Heineken N.V. anchors European demand through energy-efficiency mandates at its Netherlands and Ireland production sites. Sierra Nevada Brewing Co. differentiates through on-site renewable thermal integration at its California and North Carolina facilities.
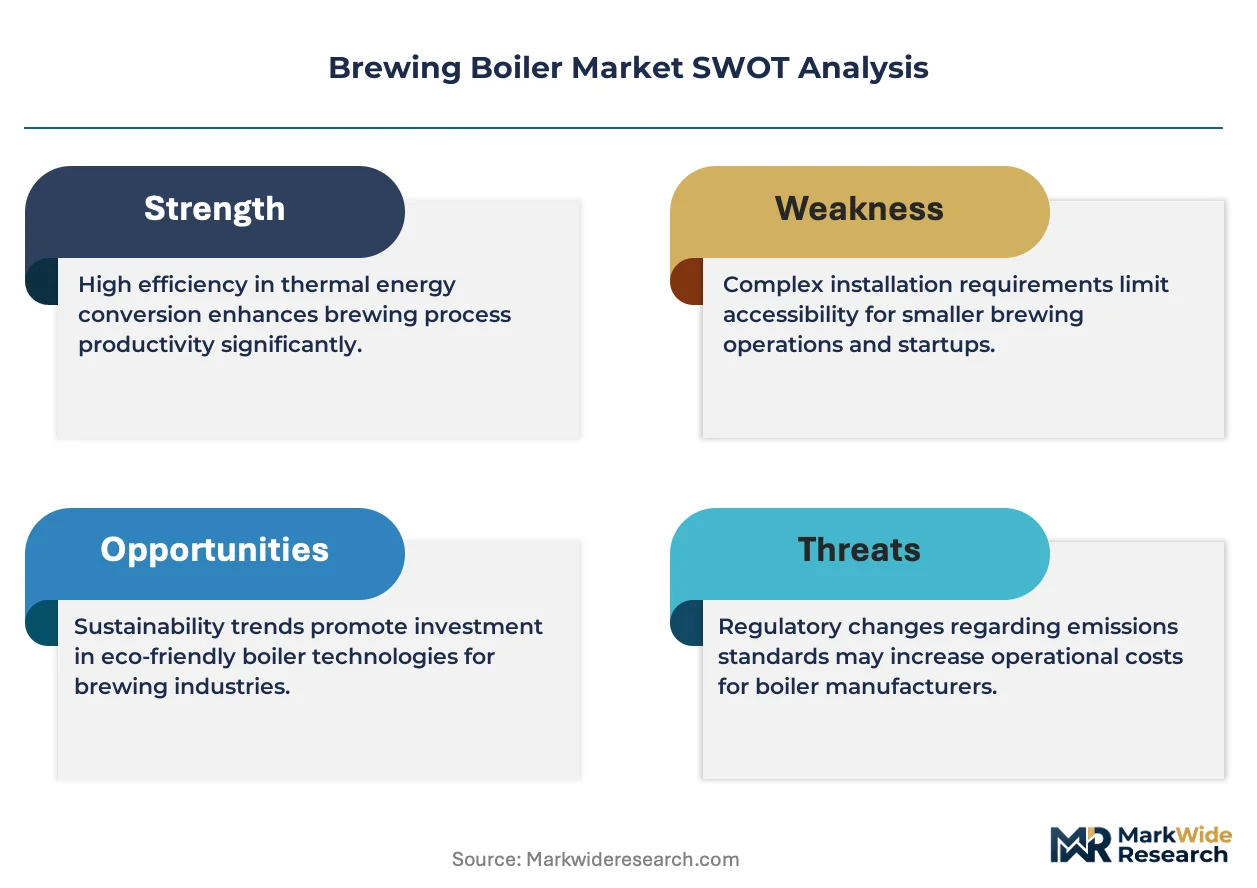
A brewing boiler is a pressure vessel engineered to generate steam or hot water at controlled temperatures and pressures for mashing, lautering, boiling, and cleaning operations in beer production, typically constructed from food-grade stainless steel with ASME-certified welding and operating at pressures between 15 and 150 psi. Gas boilers retain the largest installed base across large-scale breweries due to lower fuel costs and existing infrastructure, though electric systems are gaining share among craft operators seeking carbon footprint reduction and installation flexibility. Steam technology dominates throughput-intensive applications where wort boiling demands rapid heat transfer, while condensing designs command premium positioning through recovered latent heat and reduced stack losses.
EPA emissions regulations under the National Emission Standards for Hazardous Air Pollutants constrain oil-fired boiler deployments and accelerate natural gas and electric conversions across US brewing facilities. EU F-Gas Regulation and national efficiency codes in Germany and Belgium shape equipment specifications for Heineken and Carlsberg Group production networks. Stakeholders must monitor evolving carbon border adjustments and building energy codes that will redefine total cost of ownership calculations for boiler investments across major brewing regions.
Market Dynamics
EPA emissions standards under the National Emission Standards for Hazardous Air Pollutants are forcing fuel-switching investments across US brewing facilities, compressing oil-fired boiler deployments and accelerating natural gas and electric conversions among craft and industrial operators alike.
Growth Catalysts
- Natural gas infrastructure expansion:Pipeline network extensions in the US Midwest and Germany lower connection barriers for mid-sized breweries upgrading from oil-fired systems.
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases drive heat pump and electric boiler adoption across Belgian and Dutch production sites.
- Stainless-steel fabrication capacity:Regional equipment makers in China's Shandong and Guangdong provinces expand mid-sized brewing system output for export markets.
Market Restraints
- Nickel alloy price volatility:Food-grade 316L stainless steel input costs fluctuate with mining supply constraints, pressuring margins for ASME-certified fabricators.
- Specialized welder scarcity:ASME Section IX certified welders concentrate in Germany and the US Upper Midwest, creating installation bottlenecks for custom boiler projects.
- Condensing boiler technical limits:Corrosion susceptibility in low-return-temperature applications restricts deployment in facilities with intermittent steam demand patterns.
Strategic Opportunities
- India craft brewery emergence:FSSAI licensing simplification and state-level excise reforms open equipment markets in Maharashtra and Karnataka.
- Renewable thermal integration:Solar thermal and biogas cogeneration convergence enables carbon-neutral steam generation at California and North Carolina production campuses.
- Service contract unbundling:Predictive maintenance subscriptions separate from equipment sales, creating recurring revenue streams for controls-integrated boiler OEMs.
Industry Challenges
- ASME certification timelines:Third-party inspection backlogs extend project delivery schedules by four to eight weeks for pressure vessel approvals.
- Legacy control system integration:Brewery SCADA platforms from disparate vintages complicate IoT sensor retrofitting for remote monitoring deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewing Boiler Market |
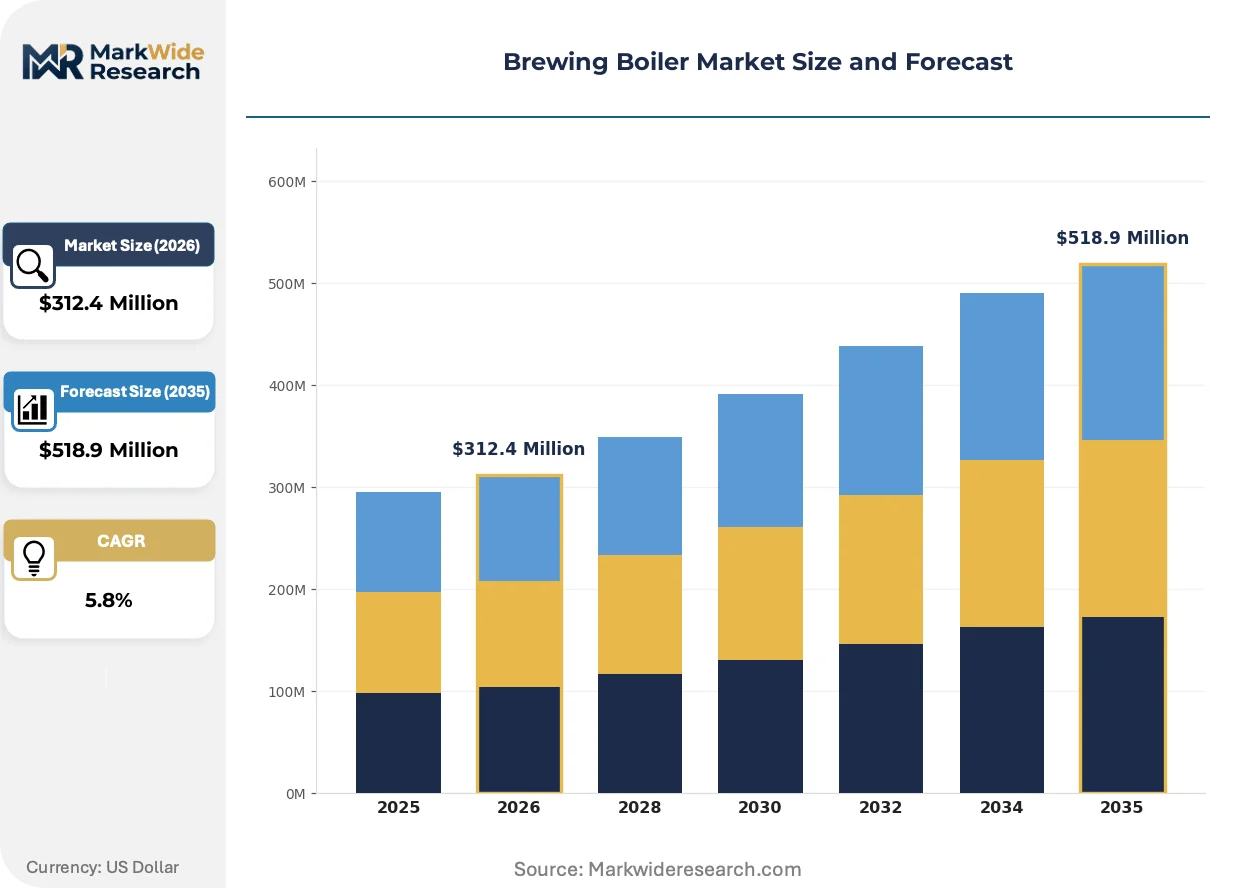
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Boilers, Gas Boilers, Oil Boilers, Biomass Boilers End User: Microbreweries, Craft Breweries, Large-scale Breweries, Brewpubs Technology: Hot Water, Steam, Condensing, Non-Condensing Installation: Indoor, Outdoor, Mobile, Fixed |
| Companies Covered | Anheuser-Busch InBev SA/NV, Heineken N.V., Carlsberg Group, Molson Coors Beverage Company, Constellation Brands Inc., Diageo PLC, Boston Beer Company Inc., Sierra Nevada Brewing Co., D.G. Yuengling and Son Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewing Boiler Market Strategic Shifts
Digital twin technology is virtualizing boiler performance optimization across brewing operations, compressing commissioning cycles and enabling predictive maintenance before physical installation completes.
Condensing economizer systems with polymer heat exchangers are recovering latent heat from stack gases at sub-dewpoint temperatures. Craft breweries in Oregon and Colorado deploy these packages to meet corporate carbon reduction commitments without boiler replacement. The technology is virtualizing traditional energy audit workflows, allowing real-time efficiency modeling that displaces annual manual assessments.
EPA enforcement of Maximum Achievable Control Technology standards tightens particulate matter limits for biomass-fired units. Industrial breweries in Wisconsin and Pennsylvania retrofit existing grate systems with electrostatic precipitators or switch to natural gas. Small-scale operators respond by clustering for shared steam infrastructure, consolidating emissions permitting burdens.
Equipment-as-a-service contracts now bundle boiler, maintenance, and energy management into per-hectoliter fees. Mid-sized German breweries favor this model to preserve capital for taproom expansion rather than production infrastructure. Bavaria and Baden-Württemberg host the densest adoption, where Reinheitsgebot compliance requirements elevate service provider specialization premiums.
Brewing Boiler Market Segmentation
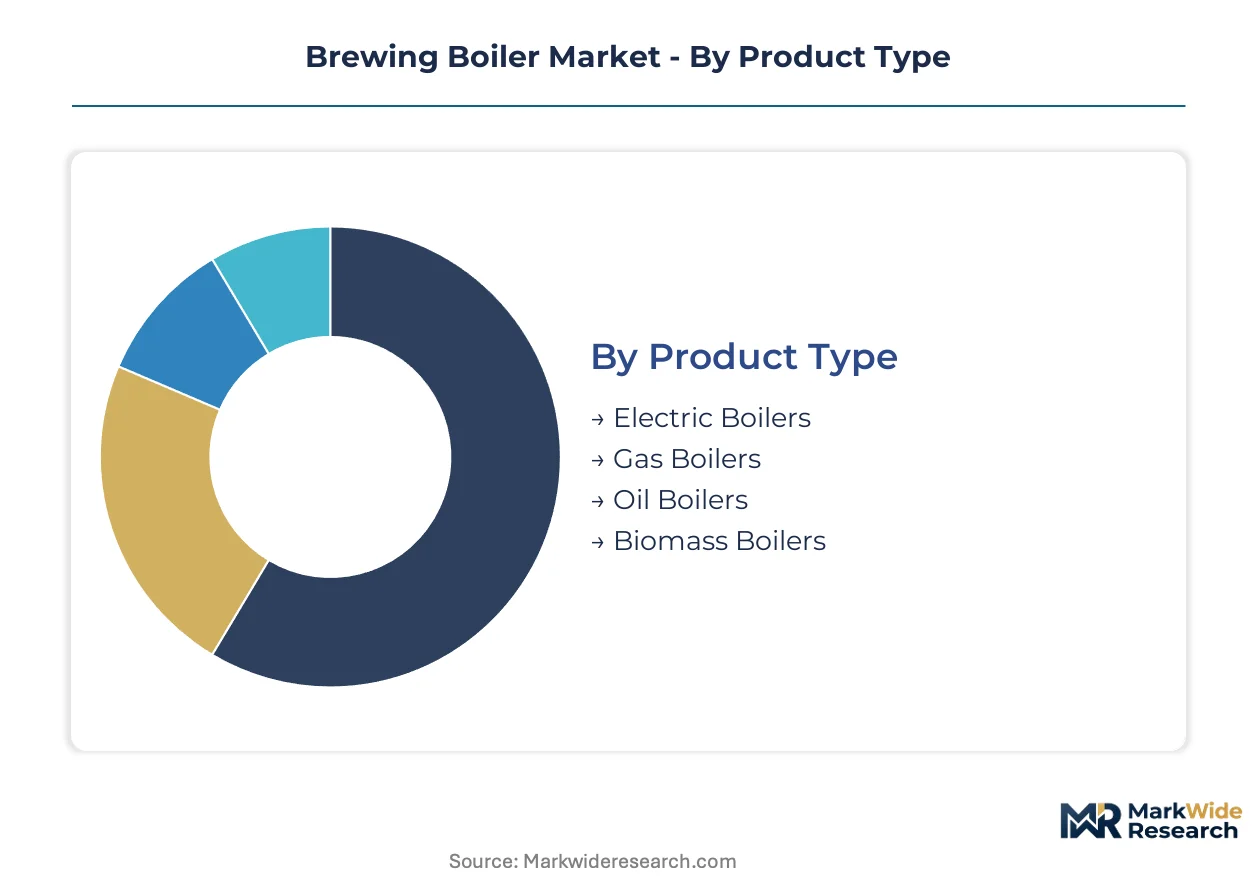
Brewing boiler procurement cycles vary dramatically across equipment categories, with replacement intervals ranging from 15 years for fixed gas installations to under 5 years for mobile electric units serving seasonal operations. Understanding these velocity differences helps suppliers align inventory, service contracts, and financing products to actual customer decision rhythms.
Product Type:
Gas boilers turn over slowest due to infrastructure lock-in, while electric systems cycle fastest as craft operators experiment with carbon reduction strategies and relocate frequently.
- Electric Boilers:Resistance or electrode systems generating steam through direct electrical conversion, eliminating combustion emissions at the point of use. Demand concentrates in California and Oregon craft clusters where municipal renewable electricity contracts enable zero-carbon brewing claims, though kilowatt-hour rates in Germany and Belgium constrain adoption despite EU Green Deal alignment.
- Gas Boilers:Natural gas-fired pressure vessels with forced-draft or atmospheric burners, dominating throughput-intensive applications. Large-scale breweries in the US Midwest and Bavaria anchor installed base expansion, leveraging existing pipeline infrastructure and lower per-thermal-unit costs versus electrification.
- Oil Boilers:Liquid fuel combustion systems, primarily residual fuel oil or distillate, facing accelerated retirement under EPA National Emission Standards for Hazardous Air Pollutants.
- Biomass Boilers:Grate or fluidized-bed systems burning spent grain, wood chips, or agricultural residues, concentrated in Wisconsin and Pennsylvania where feedstock integration with malting operations creates circular thermal economies.
Gas boilers anchor the volume base while electric systems gain share at the steepest rate.
End User:
Customer scale determines specification complexity, with microbreweries prioritizing plug-and-play installation speed against large-scale facilities engineering for 25-year operational lifespans.
- Microbreweries:Sub-1,000 hectoliter annual output operations, typically owner-operated with limited technical staff. Equipment decisions in Maharashtra and Karnataka favor containerized electric skids with FSSAI-compliant stainless construction, compressing commissioning timelines amid licensing urgency.
- Craft Breweries:Mid-sized regional producers between 1,000 and 100,000 hectoliters, driving specification innovation through sustainability differentiation. North Carolina and Colorado facilities integrate solar thermal preheat and condensing economizers to meet corporate carbon commitments without sacrificing wort boiling intensity.
- Large-scale Breweries:Industrial megabreweries exceeding 100,000 hectoliters, standardizing on ASME-certified gas steam systems with 150 psi operating pressure.
- Brewpubs:On-premise production with direct retail service, prioritizing aesthetic integration and noise attenuation over thermal efficiency metrics.
Large-scale breweries concentrate procurement value while craft breweries expand the addressable market most aggressively.
Technology:
Heat transfer modality and efficiency architecture separate applications by temperature precision requirements and capital recovery horizons.
- Hot Water:Low-pressure closed-loop systems operating below 250°F, deployed for mashing and CIP circuits where temperature uniformity outweighs rapid heat flux. German Reinheitsgebot-compliant mid-sized breweries specify these for lautering operations, pairing with separate steam boilers for wort boiling to satisfy tradition-driven process separation.
- Steam:Saturated or superheated vapor systems delivering rapid, uniform heat transfer for wort boiling and sterilization. Throughput-intensive applications in Ireland and Netherlands Heineken facilities mandate steam technology, with energy-efficiency mandates driving condensing economizer retrofits on existing installations.
- Condensing:Latent heat recovery designs extracting additional thermal energy from stack gases, commanding premium positioning in carbon-constrained markets.
- Non-Condensing:Traditional high-temperature return designs, retaining share in intermittent-duty applications where corrosion risk from condensate limits condensing deployment.
Steam technology dominates installed capacity while condensing designs climb the fastest among replacement investments.
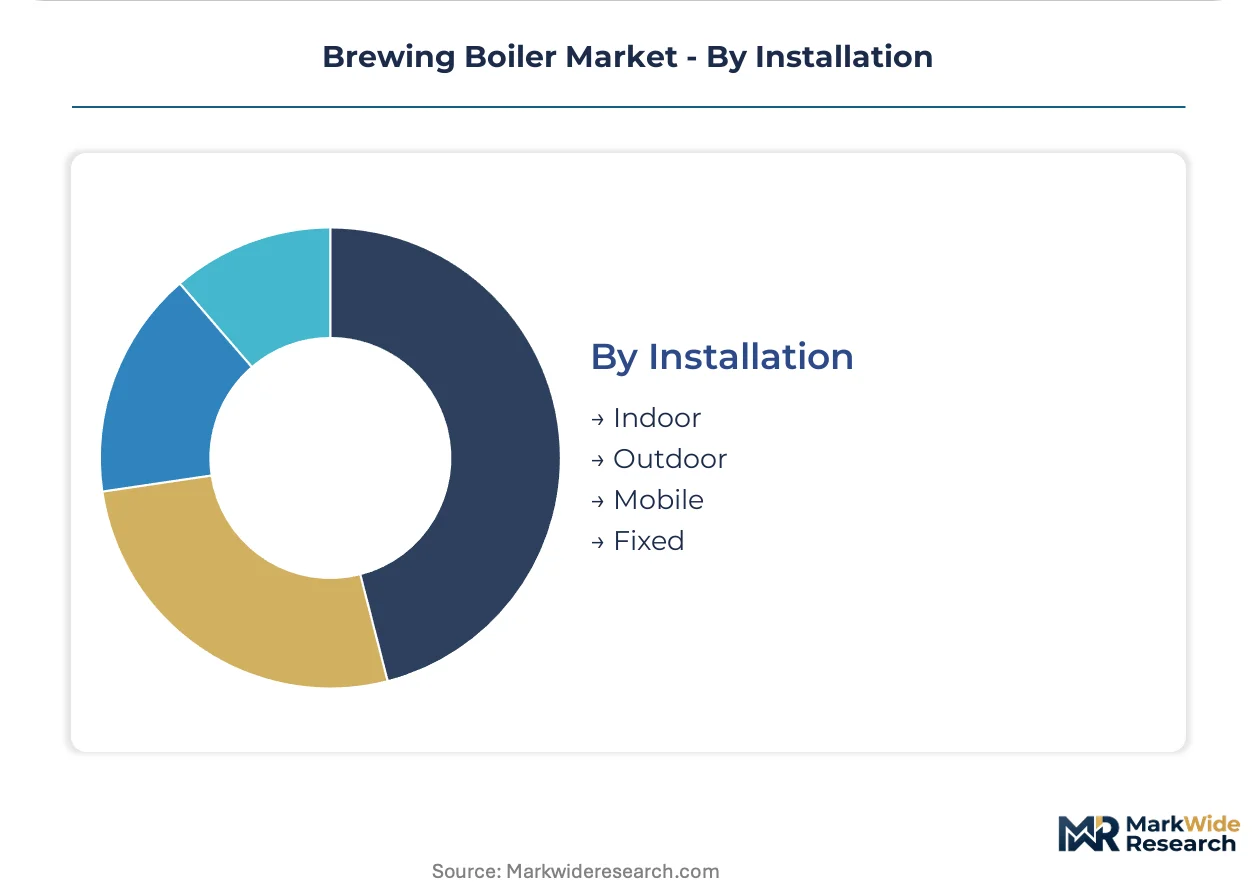
Installation:
Physical deployment configuration shapes permitting complexity, weatherproofing requirements, and operational flexibility for seasonal or experimental production.
- Indoor:Climate-controlled equipment rooms with integrated ventilation and fuel delivery, standard for permanent production facilities. Bavaria and Baden-Württemberg breweries favor indoor gas installations to satisfy TÜV inspection protocols and Reinheitsgebot-adjacent process hygiene expectations.
- Outdoor:Weatherized enclosures with freeze protection and vandal resistance, common in North American craft operations with limited building footprint. Oregon and Colorado seasonal producers specify outdoor electric skids to bypass indoor air quality permitting and accelerate taproom construction timelines.
- Mobile:Trailer-mounted or containerized systems for festival production, pilot brewing, and disaster recovery.
- Fixed:Permanent foundation-mounted installations with dedicated utility interconnections, amortized over 15-20 year depreciation schedules.
Fixed installations anchor capital deployment while mobile configurations expand the fastest among emerging market entrants testing production viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards under the National Emission Standards for Hazardous Air Pollutants anchor US regulatory pressure, while EU F-Gas Regulation and Germany's Reinheitsgebot tradition shape parallel demand centers across the Atlantic.
United States
Midwest craft breweries expand capacity while converting oil-fired systems to natural gas under EPA enforcement. The National Emission Standards for Hazardous Air Pollutants compress residual fuel oil deployments. Wisconsin and Pennsylvania industrial operators cluster for shared steam infrastructure to consolidate emissions permitting.
Germany
Reinheitsgebot compliance sustains dense demand from small and mid-sized breweries requiring specialized steam equipment. EU F-Gas Regulation phase-down schedules accelerate heat pump and electric boiler adoption. Bavaria and Baden-Württemberg host concentrated equipment-as-a-service adoption where breweries preserve capital for taproom expansion.
China
Regional equipment makers in Shandong and Guangdong provinces expand stainless-steel fabrication capacity for mid-sized brewing systems targeting export markets. National dual carbon goals pressure fuel-switching investments. Yangtze River Delta and Pearl River Delta clusters drive domestic craft brewery emergence with simplified licensing frameworks.
India
FSSAI licensing simplification and state-level excise reforms open equipment markets in Maharashtra and Karnataka. Microbreweries favor containerized electric skids with FSSAI-compliant stainless construction. Mumbai and Bangalore urban clusters compress commissioning timelines amid licensing urgency for sub-1,000 hectoliter operators.
Netherlands
Heineken N.V. production sites anchor European energy-efficiency mandates through condensing economizer retrofits. EU F-Gas Regulation shapes heat pump adoption timelines. Rotterdam and Amsterdam industrial corridors concentrate throughput-intensive steam technology deployments with recovered latent heat systems.
Brewing Boiler Market Competitive Environment
Capability concentration sits with ASME-certified fabrication specialists; scale advantage sits with vertically integrated beverage conglomerates. The vendor base separates into three tiers: stainless-steel pressure vessel fabricators serving custom specifications, regional equipment assemblers targeting mid-sized craft operators, and captive engineering divisions within multinational brewers. Dominant competitive moves include strategic partnerships between boiler OEMs and controls integrators for predictive maintenance subscriptions, plus geographic expansion by Chinese fabricators into Southeast Asian craft markets.
Among North American beverage conglomerates, Anheuser-Busch InBev SA/NV and Molson Coors Beverage Company exemplify scale-driven standardization across megabrewery networks. Sierra Nevada Brewing Co. occupies a differentiated position through renewable thermal integration at production campuses. These three entities represent contrasting archetypes: captive vertical integration, portfolio diversification across price tiers, and sustainability-forward craft differentiation.
| Leading Market Players |
|---|
| Anheuser-Busch InBev SA/NV |
| Heineken N.V. |
| Carlsberg Group |
| Molson Coors Beverage Company |
| Constellation Brands Inc. |
| Diageo PLC |
| Boston Beer Company Inc. |
| Sierra Nevada Brewing Co. |
| D.G. Yuengling and Son Inc. |
| Others |
Value Chain & Pricing Dynamics
Shandong and Guangdong provinces anchor stainless-steel fabrication capacity expansion, compressing equipment margins for European and North American fabricators while elevating pricing power for buyers with scale to consolidate procurement. This geographic shift in supply concentration forces ASME-certified specialists to differentiate through service bundling rather than hardware premiums alone.
Pricing Analysis
Equipment pricing spreads widest between German TÜV-certified fabricators and Chinese regional assemblers, with the premium-mid-economy pricing differentiation driven by certification tier and after-sales service depth. ASME Section IX welding certification commands substantial premiums in North American markets where certified welder scarcity constrains installation capacity. Pricing pressure stems from nickel alloy cost volatility pressuring margins across all tiers, with microbreweries exhibiting highest price sensitivity due to capital constraints while large-scale breweries prioritize total cost of ownership over upfront equipment spend.
Supply Chain Analysis
Supplier financing facilities with extended payment terms have proliferated among Chinese equipment makers seeking to displace European incumbents in Southeast Asian craft markets. Manufacturing concentration rests on China, Germany, and the United States, with food-grade 316L stainless steel and ASME-certified pressure vessel components drawing from mining and specialized fabrication networks. Single-source vulnerability concentrates in nickel alloy supply chains subject to mining disruption, while distribution runs through regional equipment distributors with brewery engineering expertise and direct OEM sales teams for megabrewery accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against modular electric skids displacing traditional gas-fired systems in carbon-constrained jurisdictions. Electrification mandates and renewable thermal integration threaten incumbent gas boiler installed bases.
For Market Incumbents: Insulate core gas boiler revenue through predictive maintenance subscriptions that embed controls expertise and create switching costs. Deepen backward integration into heat exchanger manufacturing to capture margin from nickel alloy price volatility. Prioritize certification investment in EU F-Gas Regulation-compliant heat pump systems to defend position against electric entrants in Netherlands and Belgium production corridors.
For New Entrants and Emerging Players: Maharashtra and Karnataka present underpenetrated craft brewery equipment demand where FSSAI licensing urgency compresses procurement cycles and favors containerized electric skid providers. Target microbrewery segments with plug-and-play commissioning capabilities and localized service partnerships. Pursue equipment-as-a-service contract structures to bypass capital expenditure barriers among emerging market operators.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ASME certification scarcity and specialized welder bottlenecks create durable moats for fabrication specialists with established quality systems. Target mid-sized regional boiler OEMs with controls integration capabilities and established brewery customer relationships. Monitor EPA enforcement intensity and EU carbon border adjustment implementation as inflection signals for fuel-switching investment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Controls Integration Partnership | Predictive maintenance subscriptions create recurring revenue streams tied to Heineken energy-efficiency mandates. |
| Regional Fabrication Expansion | Shandong and Guangdong capacity buildout targets Southeast Asian craft brewery export demand with cost-competitive stainless systems. |
| Certification Investment | ASME Section IX welding program expansion addresses installer bottlenecks constraining North American project delivery. |
| Renewable Thermal Convergence | Solar thermal and biogas integration enables carbon-neutral steam claims at Sierra Nevada California and North Carolina campuses. |
| Service Contract Unbundling | Per-hectoliter fee structures preserve brewery capital for taproom expansion in Bavaria and Baden-Württemberg markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA enforcement records, EU F-Gas Regulation implementation documents, and ASME certification databases. Primary interviews engaged boiler OEM engineering directors, brewery maintenance managers at craft and industrial facilities, and regional equipment distributor technical sales leads. Secondary validation incorporated customs trade data for stainless-steel pressure vessel imports, SEC filings from publicly traded beverage conglomerates, and TÜV inspection protocol documentation. Bottom-up equipment shipment analysis triangulates against top-down brewery production capacity estimates across the analysis window.
Forecast inputs incorporate fuel-switching investment cycles, regulatory compliance deadlines, and brewery capacity expansion pipelines without year-specific anchoring. Segmentation dimensions model product type, end-user scale tier, technology heat transfer modality, and installation configuration across the projection horizon. CAGRs derive from equipment replacement interval analysis, regulatory-driven conversion velocity, and emerging market penetration curves. Industry-specific inputs include nickel alloy price trajectory assumptions and certified welder supply elasticity in key manufacturing regions.
Practitioners should monitor EPA Maximum Achievable Control Technology enforcement intensity, EU carbon border adjustment implementation timing, and Chinese dual carbon goal acceleration for early signals of demand inflection. Forecasts embed assumptions regarding regulatory continuity and commodity price stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Crossflow Wine Filters Market
Food Processing Equipment
Pet Food Processing Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Milk Sterilizer Machine Market