
 Raw Coffee Beans Market | 2026-2036
Raw Coffee Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Raw Coffee Beans Market Analytics
The capital-intensity divergence between integrated traders and boutique origin buyers is rotating competitive advantage toward firms with direct farm relationships and in-country processing assets. Neumann Kaffee Gruppe leverages its vertical milling networks across origin countries to sustain cost-advantaged throughput. Olam International anchors its position through digital traceability platforms that compete on compliance readiness for European buyers. Sucafina SA differentiates via specialty-grade sourcing teams that dominate auction circuits in East Africa and Central America.
Raw coffee beans constitute unroasted seeds of Coffea arabica and Coffea canephora species, typically traded at 9-13% moisture content with defect thresholds set by the Specialty Coffee Association for cupping scores above 80 points. These beans serve as the foundational input for roasting operations, instant coffee extraction, and cold brew concentrate manufacturing across commercial and specialty channels. Arabica and Robusta product types split the value pool, with washed processing methods commanding premiums in specialty segments while natural-processed lots capture share in commercial blends. Grade stratification concentrates margin capture in specialty and premium tiers, where origin transparency and organic certification unlock price premiums over standard commercial grades.
Brazil's MAPA, Colombia's FNC, and the EU's EUDR framework collectively shape market access through phytosanitary protocols, geographic indication enforcement, and deforestation due-diligence mandates. The EU Deforestation Regulation specifically demands geolocation verification for all coffee shipments entering European ports, forcing traders to restructure origin documentation systems. Stakeholders must monitor how EUDR implementation timelines interact with ICE exchange certification standards and origin-country export licensing reforms.
Market Dynamics
The EU Deforestation Regulation is forcing a complete overhaul of traceability infrastructure, compelling traders to deploy geolocation verification systems and restructure documentation workflows for every lot entering European ports.
Growth Catalysts
- EUDR Compliance Mandate:European buyers now require farm-level geolocation data, creating urgent demand for digital traceability platforms that verify chain-of-custody from harvest to port.
- Specialty Roaster Expansion:Boutique roasting operations in Germany and the Netherlands are sourcing single-origin lots with cupping scores above 85 points, pulling premium-grade Arabica through direct trade channels.
- Climate-Adaptive Varieties:Brazil's agricultural research agency EMBRAPA has released drought-tolerant cultivars that maintain cup quality under water stress, stabilizing supply from Minas Gerais during irregular rainfall cycles.
Market Restraints
- Input Cost Volatility:Fertilizer prices tied to natural gas markets in Russia and Belarus swing Arabica production economics in Colombia's Nariño department, where smallholder farms lack hedging instruments.
- Supply Concentration Risk:Brazil's Minas Gerais region accounts for a dominant share of global Arabica export volume, exposing price discovery mechanisms to localized frost events and currency fluctuations.
- Technical Limitation:Moisture content calibration at origin mills lacks standardization, creating disputes when 9-13% thresholds are interpreted differently by ICE exchange certifiers and private buyers.
Strategic Opportunities
- Underpenetrated Geography:Rwanda's Western Province holds untapped potential for specialty-grade Bourbon varieties, with washing station infrastructure expanding but cupping expertise still scarce among local cooperatives.
- Regulatory Tailwind:The EU Green Deal's carbon border adjustment mechanism will eventually price embodied emissions in coffee transport, rewarding ocean-freight consolidation and penalizing air-freighted micro-lots.
- Distribution Innovation:Blockchain-enabled forward contracts now allow roasters to lock in harvest-specific lots six months pre-shipment, bypassing traditional spot-market intermediaries in Antwerp and Hamburg.
Industry Challenges
- Capex Intensity:Building in-country dry milling capacity requires capital deployment for hulling equipment and color-sorting machinery, straining balance sheets of mid-sized trading houses.
- Certification Timeline Compression:Organic certification cycles now lag behind EUDR implementation deadlines, forcing exporters to pursue parallel verification tracks for the same farm lots.
- Integration Complexity:Legacy ERP systems at established traders cannot ingest satellite-derived deforestation alerts, creating manual reconciliation bottlenecks at origin documentation centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Raw Coffee Beans Market |
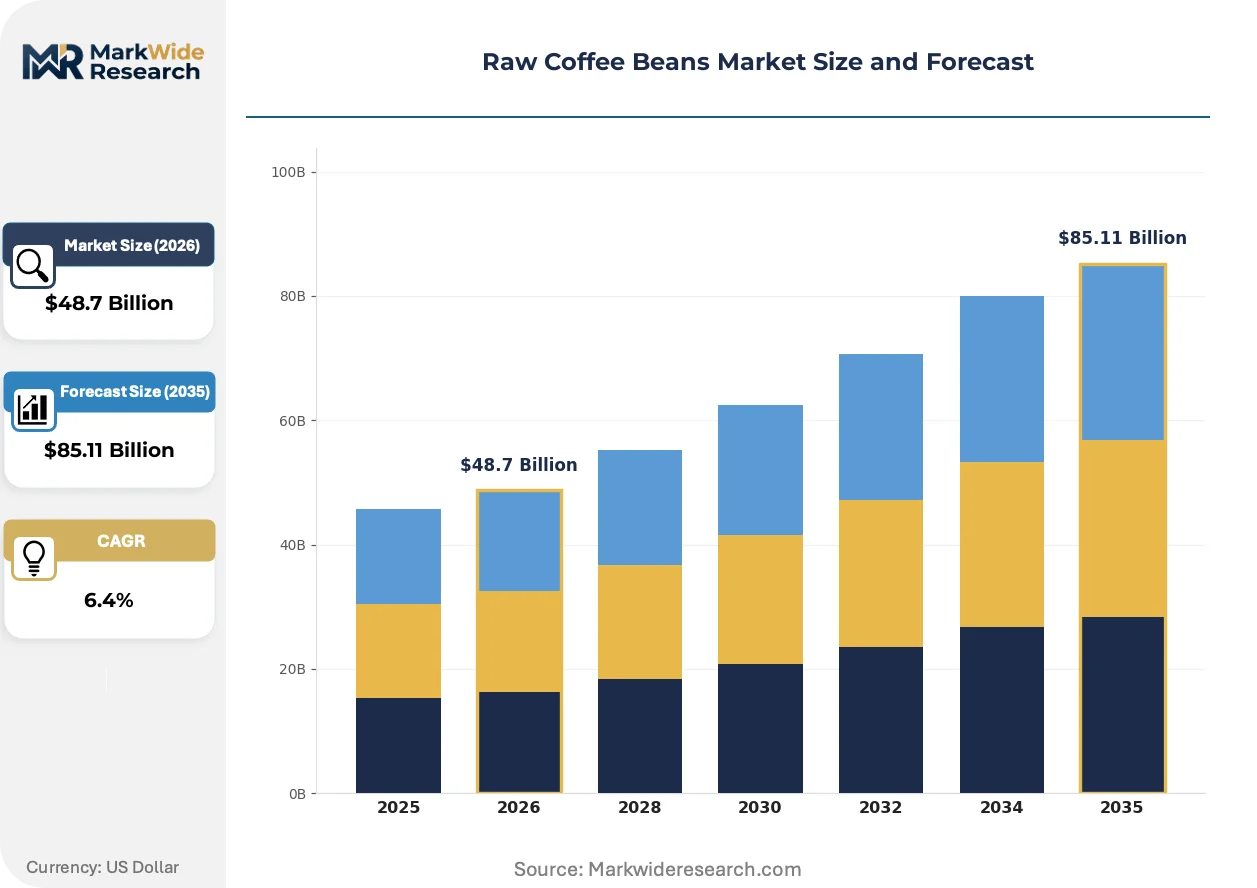
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Liberica, Excelsa Processing Method: Washed, Natural, Honey, Semi-Washed Grade: Specialty, Premium, Standard, Commercial Origin: Single Origin, Blends, Sustainable, Organic |
| Companies Covered | Neumann Kaffee Gruppe, Louis Dreyfus Company, Olam International, Sucafina SA, ECOM Agroindustrial, Volcafe Ltd., Belco SA, LUIGI LAVAZZA SpA, Illycaffe Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Raw Coffee Beans Market Evolving Landscape
Digital traceability infrastructure is displacing paper-based chain-of-custody systems, while regulatory pressure from Brussels accelerates compliance technology adoption across the value chain.
Blockchain-based provenance tracking is fragmenting the traditional role of origin exporters as trusted intermediaries. Specialty roasters in Copenhagen and Melbourne now query immutable ledger records to verify farm gate prices paid to Colombian cooperatives. This disintermediation compresses margin capture for conventional traders while rewarding technology-enabled direct-sourcing platforms.
The EU Deforestation Regulation mandates geolocation coordinates for every production plot exceeding four hectares, with due diligence documentation required at entry points in Rotterdam and Hamburg. Traders are deploying satellite imagery verification services to pre-validate compliance before vessel loading. Smallholder-dominated supply chains in Ethiopia and Kenya face acute adaptation pressure given fragmented farm geometries below the threshold.
Buyer concentration among certified B-Corp roasting chains is rotating procurement criteria toward living wage verification and carbon footprint disclosure. Direct trade relationships now specify agronomic technical assistance as a contract term, with agronomists from consuming countries embedding at origin during harvest periods. This pattern is most visible in Nordic markets where consumer-facing transparency requirements outpace regulatory minimums.
Raw Coffee Beans Market Segmentation
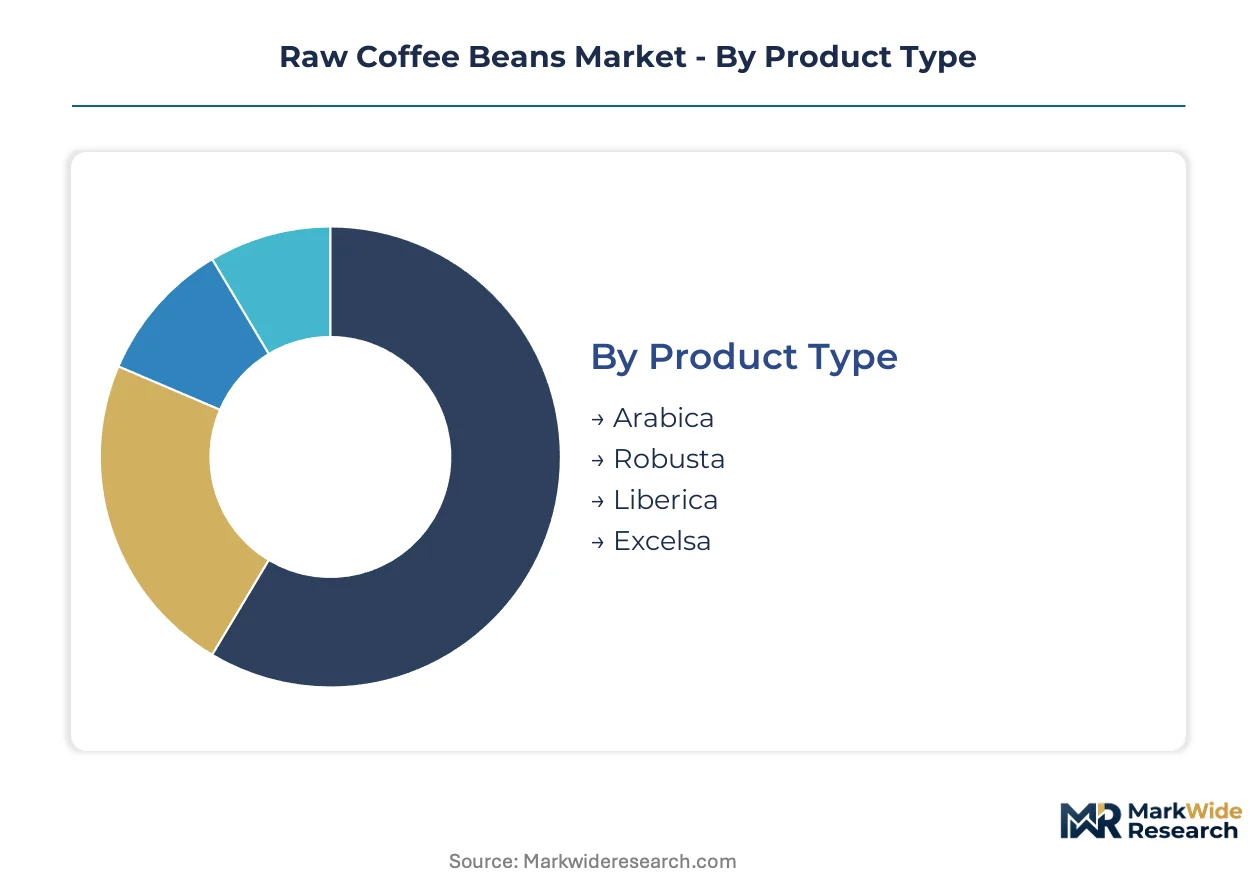
Segmentation in raw coffee beans determines pricing power, regulatory exposure, and supply chain configuration. Roasters configure procurement strategies around cup profile requirements, processing consistency, and origin verification mandates.
Product Type:
Domestic consumption patterns in producing countries favor Robusta for soluble extraction, while export-led demand concentrates on Arabica for specialty roasting channels in Germany, the Netherlands, and Nordic markets.
- Arabica:Higher acidity and complex aromatic profiles define this species, with moisture content standards at 9-13% for specialty grades. Demand concentrates in Copenhagen and Melbourne roasting clusters where cupping scores above 85 points command contract premiums.
- Robusta:Elevated caffeine content and fuller body suit espresso blending and instant coffee manufacturing. Vietnamese Dak Lak province and Indonesian Sumatra supply export volumes to Italian and Spanish commercial roasters seeking cost-stable inputs.
- Liberica:Distinctive woody and floral notes characterize this low-volume species, with Philippine Batangas province maintaining heirloom cultivation for domestic heritage markets.
- Excelsa:Tart fruit-forward cup profiles distinguish this species, cultivated primarily in Philippine Mindanao for regional specialty consumption with minimal export infrastructure.
Arabica commands the established base. The steepest expansion runs through Robusta as climate-adaptive cultivars improve cup acceptability in premium blends.
Processing Method:
Cost tier differentiation separates labor-intensive washed methods from capital-efficient natural processing, with honey methods occupying a narrowing mid-tier position.
- Washed:Fermentation tanks and extensive water usage produce clean, consistent cup profiles with pronounced acidity. Colombian Nariño department and Kenyan Nyeri county dominate export supply to European buyers requiring EUDR-compliant documentation.
- Natural:Sun-dried cherries on raised beds concentrate sugars and fruit notes, with Ethiopia's Sidama zone supplying distinctive lots to Japanese and Australian specialty markets.
- Honey:Partial mucilage retention creates balanced sweetness and body, with Costa Rica's Tarrazú region pioneering this method for US West Coast direct trade relationships.
- Semi-Washed:Abbreviated fermentation reduces water consumption while moderating wild fermentation notes, prevalent in Brazilian Cerrado for commercial grade export.
Washed methods anchor specialty procurement. Natural processing is gaining share fastest as water-scarce origins expand raised bed infrastructure.
Grade:
Margin capture stratifies sharply across tiers, with certification requirements and origin transparency separating premium segments from commodity price exposure.
- Specialty:SCA cupping scores above 80 points with zero primary defects, requiring farm-level traceability and harvest-date documentation. German and Dutch B-Corp roasting chains specify living wage verification and carbon disclosure for these lots.
- Premium:Strict screen size uniformity and limited defect thresholds position this tier for branded retail and foodservice accounts in France and Switzerland.
- Standard:Exchange-grade specifications from ICE certified warehouses serve volume roasting operations with less stringent origin requirements.
- Commercial:Blending-grade lots with higher defect tolerance supply instant coffee extraction and private-label roasting in price-sensitive markets.
Specialty grade concentrates margin expansion. Premium tier volume is climbing the fastest as mid-market roasting chains upgrade input specifications.
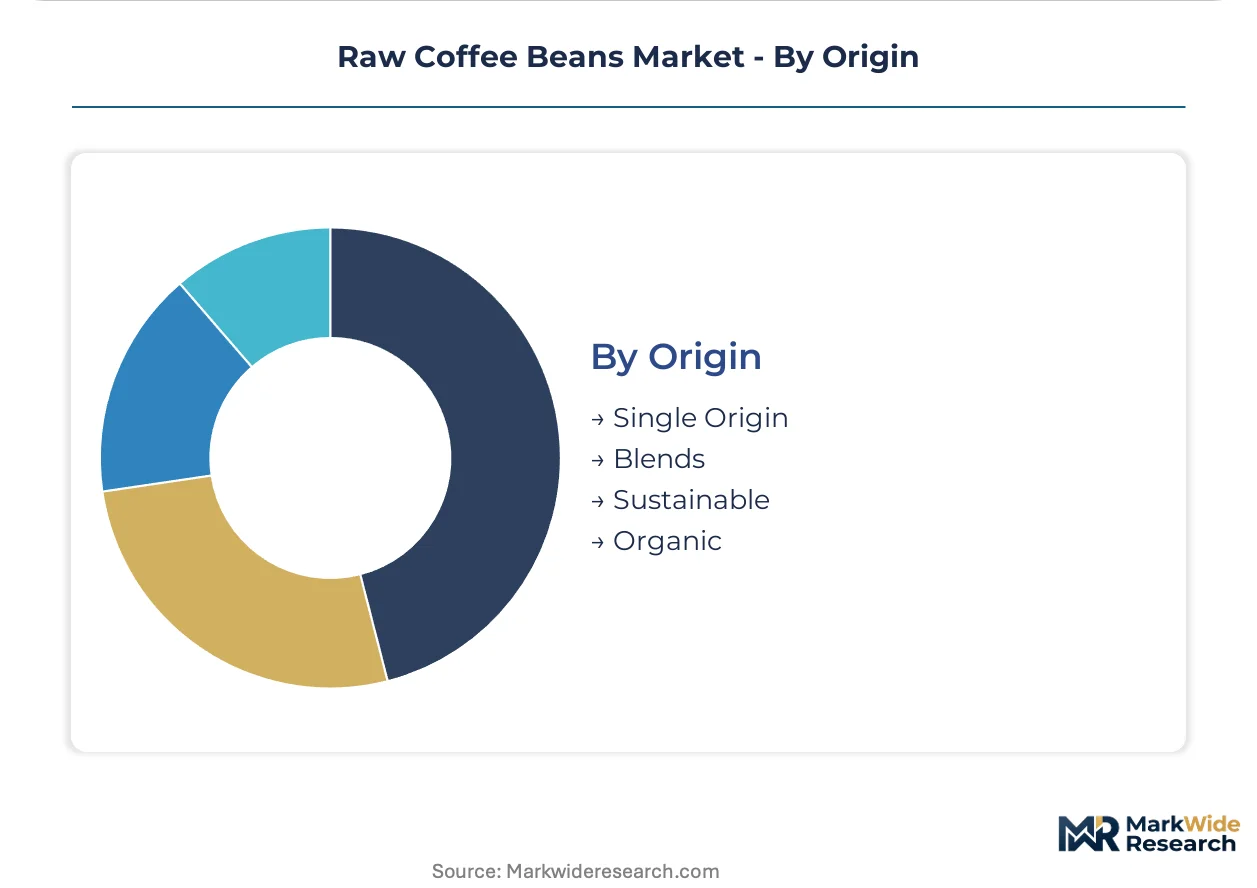
Origin:
Supply concentration and regulatory readiness determine which origin categories can access European ports under EUDR geolocation mandates.
- Single Origin:Farm or cooperative-specific lots with harvest-lot isolation enable cup profile differentiation and price transparency. Rwanda's Western Province washing stations and Colombia's Huila department micro-lots exemplify this category's expansion trajectory.
- Blends:Multi-origin composition optimizes cost stability and flavor consistency for commercial roasting at scale, with Brazilian Minas Gerais and Vietnamese Central Highlands providing base volumes.
- Sustainable:Rainforest Alliance or 4C verification addresses deforestation and labor standards without full organic certification, bridging compliance gaps for EUDR readiness.
- Organic:Certified absence of synthetic inputs requires three-year conversion periods, with Peruvian Cajamarca and Mexican Chiapas smallholders capturing price premiums despite yield penalties.
Blends maintain volume dominance. Single origin is expanding most quickly as blockchain-enabled forward contracts reduce spot market friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German roasting operations import traceable Arabica for specialty extraction, while Vietnamese manufacturers process Robusta into soluble powder for domestic consumption. Brazil's export infrastructure ships both species through Santos port to diverging end-markets.
Brazil
Minas Gerais washing stations supply cup-scored lots to Copenhagen and Melbourne roasting clusters. MAPA enforces phytosanitary protocols for export certification. São Paulo-based trading houses coordinate container consolidation from Cerrado dry mills.
Germany
Hamburg and Bremen ports handle EUDR-compliant documentation for incoming East African lots. The EU Deforestation Regulation mandates geolocation verification at entry points. Cologne and Düsseldorf roasting facilities specialize in single-origin espresso profiles.
Colombia
Nariño department micro-lots command direct-trade premiums from Dutch B-Corp chains. FNC manages geographic indication enforcement for Huila and Cauca origins. Bogotá export offices coordinate harvest-lot isolation for European specialty buyers.
Vietnam
Dak Lak province Robusta supplies Italian and Spanish commercial blending operations. The Ministry of Agriculture and Rural Development oversees export licensing reforms. Ho Chi Minh City traders consolidate container loads for instant coffee manufacturers.
Ethiopia
Sidama zone natural-processed lots reach Japanese and Australian specialty markets. Smallholder fragmentation complicates EUDR geolocation compliance for sub-four-hectare plots. Addis Ababa exporters deploy satellite verification services for European-bound shipments.
Raw Coffee Beans Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in firms controlling origin milling networks. The trading layer fragments across boutique sourcing teams and commodity volume handlers. Strategic archetypes include vertically integrated origin processors, digital traceability platforms, and specialty-grade auction specialists. Competitive moves center on backward integration into hulling capacity and compliance technology licensing for EUDR readiness.
Within the integrated processing tier, Neumann Kaffee Gruppe and Sucafina SA exemplify contrasting scale strategies. Neumann's GmbH structure reflects German capital deployment across multi-origin milling assets. Sucafina SA occupies a position bridging Swiss trading heritage with East African and Central American specialty auction presence. Olam International represents the digital infrastructure archetype, with its Singapore-based agribusiness model anchoring traceability platform development for European regulatory compliance.
| Leading Market Players |
|---|
| Neumann Kaffee Gruppe |
| Louis Dreyfus Company |
| Olam International |
| Sucafina SA |
| ECOM Agroindustrial |
| Volcafe Ltd. |
| Belco SA |
| LUIGI LAVAZZA SpA |
| Illycaffe Spa |
| Others |
Value Network & Pricing Analysis
Climate-adaptive Robusta cultivars from Vietnam's Central Highlands are displacing Arabica in mid-market espresso blends, simultaneously shifting procurement geography toward Southeast Asia and compressing price premiums for washed-process Brazilian lots. This substitution dynamic redraws margin capture across the value chain as roasters reformulate cost-stable blends.
Pricing Analysis
After-sales revenue from agronomic technical assistance and harvest-lot isolation services now drives lifetime value beyond the initial bean transaction. Pricing stratifies across specialty, premium, and commercial tiers, with SCA cupping scores above 85 points and EUDR-compliant geolocation documentation commanding substantial contract premiums from German B-Corp roasting chains. Cost compression in commercial-grade lots is intensifying because Vietnamese Dak Lak province has expanded drought-tolerant Robusta acreage. Mid-market roasting operations show highest price sensitivity, while Nordic specialty buyers prioritize origin transparency over per-kilogram cost.
Supply Chain Analysis
Brazil and Vietnam anchor global export volume, with Minas Gerais washing stations and Dak Lak dry mills feeding divergent end-markets. The supply chain draws from fertilizer inputs tied to natural gas markets, ocean freight consolidation services, and satellite-derived deforestation verification platforms. Single-source vulnerability concentrates in Brazil's Arabica belt, where localized frost events disrupt price discovery mechanisms. Distribution runs through Antwerp and Hamburg port complexes for European specialty channels, while Ho Chi Minh City traders consolidate container loads for instant coffee manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital traceability platform licensing represents a service-attach opportunity expanding faster than physical bean trading, as EUDR compliance mandates force roasters to subscribe to geolocation verification systems for every harvest lot.
For Market Incumbents: Secure backward integration into hulling and color-sorting capacity across Colombia's Nariño department to defend margin position against boutique origin buyers with direct farm relationships. Prioritize certification investment in organic and Rainforest Alliance tracks to preempt compliance gaps as EU Green Deal carbon border adjustments mature. Channel control through captive milling assets in Minas Gerais protects throughput against climate-driven supply volatility. For New Entrants and Emerging Players: EUDR fast-track certification services for Ethiopian smallholder cooperatives with sub-four-hectare plots represent immediate white-space capture, as fragmented farm geometries create acute documentation bottlenecks for established traders. Rwanda's Western Province washing stations offer the most penetrable geography, with Bourbon varieties and scarce local cupping expertise enabling direct-trade relationships with Copenhagen roasting clusters. Deploy blockchain-enabled forward contracting as the go-to-market angle, bypassing traditional spot-market intermediaries. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated origin processors with in-country milling networks and digital traceability infrastructure already deployed. The five-to-ten-year viability window favors firms controlling both physical processing assets and compliance technology licensing revenue streams. Watch satellite verification service penetration rates among East African exporters as the inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dry Milling | Captive hulling capacity in Brazil's Cerrado insulates margin from spot price volatility. |
| Digital Traceability Platform Licensing | EUDR-compliant geolocation systems generate recurring revenue from European roasters. |
| Climate-Adaptive Cultivar Development | EMBRAPA drought-tolerant releases stabilize supply from Minas Gerais during irregular rainfall. |
| Direct Trade Relationship Expansion | Farm gate price transparency unlocks premium positioning with Nordic B-Corp roasting chains. |
| Sustainable Certification Fast-Track | Parallel organic and EUDR verification tracks accelerate market access for Peruvian smallholders. |
Research Methodology
Cross-validation between primary interviews with coffee trading executives and secondary validation through customs export data anchors the qualitative findings. The research program combined discussions with origin export office managers, European roasting procurement directors, dry mill operations heads, and satellite verification platform developers, alongside trade statistics from Santos and Hamburg port authorities, ICE exchange certification records, and FNC geographic indication filings. Bottom-up harvest-lot aggregation and top-down export volume reconciliation provided triangulation across the analysis window.
Sensitivity analysis tested demand elasticity across specialty, premium, and commercial grade tiers, with segmentation dimensions spanning product type, processing method, grade stratification, and origin verification category. CAGRs were derived from production volume trajectories, consumption pattern shifts, and regulatory implementation timelines. Forecast inputs incorporated EUDR compliance cost pass-through assumptions and climate-adaptive cultivar adoption curves from EMBRAPA field trials.
Decision-makers should treat outputs as directional under sustained EUDR implementation and stable ocean freight rate assumptions; material deviation in regulatory enforcement intensity or fertilizer cost volatility would warrant model refresh. Forecasts reflect these base conditions alongside supply concentration risk in Brazil's Minas Gerais region. Recalibration cycles align with material shifts in EU Green Deal carbon border adjustment mechanisms and origin-country export licensing reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Instant Coffee Market
Coffee
India Coffee Roaster Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Coffee Roaster Market
Coffee
Cafix Market
Coffee
RTD Coffee Market
Coffee
Coffee Bottle Market
Coffee
North America Specialty Coffee Market
Coffee
UK Coffee Roaster Market
Coffee
Coffee Fruit Extract Market
Coffee
North America Coffee Market
Coffee
Green Coffee Market
Coffee
Canned Coffee Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Office Coffee Service (OCS) Market