
 US Coffee Machine Market | 2026-2036
US Coffee Machine Market Size, Share, and Industry Trends Forecast 2026-2036
US Coffee Machine Market Insights
China is narrowing its role as a contract manufacturing hub for US-bound coffee equipment, though Vietnam and Mexico are expanding assembly capacity for North American brands. BUNN-O-Matic Corporation anchors its position through commercial-grade distribution to foodservice operators, while Keurig Green Mountain Inc. dominates pod-based system placements in offices and hotels. De'Longhi Group differentiates through European-designed espresso platforms adapted for US voltage standards and countertop dimensions.
A coffee machine is an electromechanical appliance that heats water to specific extraction temperatures, typically between 195°F and 205°F, and delivers pressurized or gravity-fed brewing for ground coffee or sealed pods. Single-serve machines lead volume sales through Keurig and Nespresso-compatible pod ecosystems, while espresso machines capture the highest margin pools among enthusiast households. Fully automatic technology is expanding fastest as touchscreen interfaces and integrated grinders reduce operational complexity for café-style output at home.
FCC certification governs wireless-enabled smart coffee machines, while NHTSA and DOT standards indirectly shape commercial fleet installations for mobile foodservice. California's CEC regulations under Title 20 enforce stringent standby power limits that manufacturers must meet for market access. Stakeholders should monitor how EPA Energy Star revisions and emerging state-level right-to-repair legislation affect modular design requirements and aftermarket service economics.
Market Dynamics
California's Title 20 standby power regulations are compressing design cycles for thermoblock heating systems, forcing manufacturers to abandon traditional boiler architectures before 2027 compliance deadlines.
Growth Catalysts
- CEC Title 20 Efficiency Mandates:California's appliance standards are accelerating thermoblock adoption across the Pacific Northwest and Southwest corridors, creating pull-through demand for compliant equipment in adjacent states.
- Hybrid Work Stabilization:Corporate offices in Seattle, Portland, and San Francisco are expanding single-serve pod placements as attendance policies crystallize, sustaining above-replacement purchase cycles.
- Specialty Roasting Cluster Density:Portland's third-wave café ecosystem and Seattle's roasting heritage maintain household espresso machine penetration rates substantially above national averages.
Market Restraints
- Aluminum and Copper Input Volatility:Thermoblock manufacturing depends on precision-extruded aluminum and copper heating elements subject to commodity price swings that compress margin pools on economy-tier units.
- Contract Manufacturing Concentration Risk:Assembly capacity for US-bound equipment concentrates in Vietnam and Mexico border zones, exposing brands to single-point logistics disruptions and tariff exposure.
- Pod Ecosystem Lock-In:Keurig and Nespresso-compatible systems create switching costs that deter brand migration, limiting competitive entry for alternative pod formats.
Strategic Opportunities
- Right-to-Repair Legislative Tailwinds:Emerging state-level repair mandates in New York and Minnesota are creating modular design premiums for field-serviceable brewing systems with standardized component interfaces.
- Smart Machine Convergence:Integration of Wi-Fi connectivity with EPA Energy Star monitoring is enabling utility demand-response programs that subsidize connected appliance purchases.
- Mobile Foodservice Fleet Expansion:NHTSA-compliant commercial installations for food trucks and catering vehicles represent underpenetrated volume for 12V and inverter-compatible brewing systems.
Industry Challenges
- FCC Certification Timelines:Wireless-enabled smart coffee machines face 14-18 week approval cycles for RF emissions testing, compressing product launch windows against seasonal retail calendars.
- Legacy Voltage Adaptation:European-designed espresso platforms require substantial re-engineering for 120V US standards, extending R&D cycles and complicating global platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Coffee Machine Market |
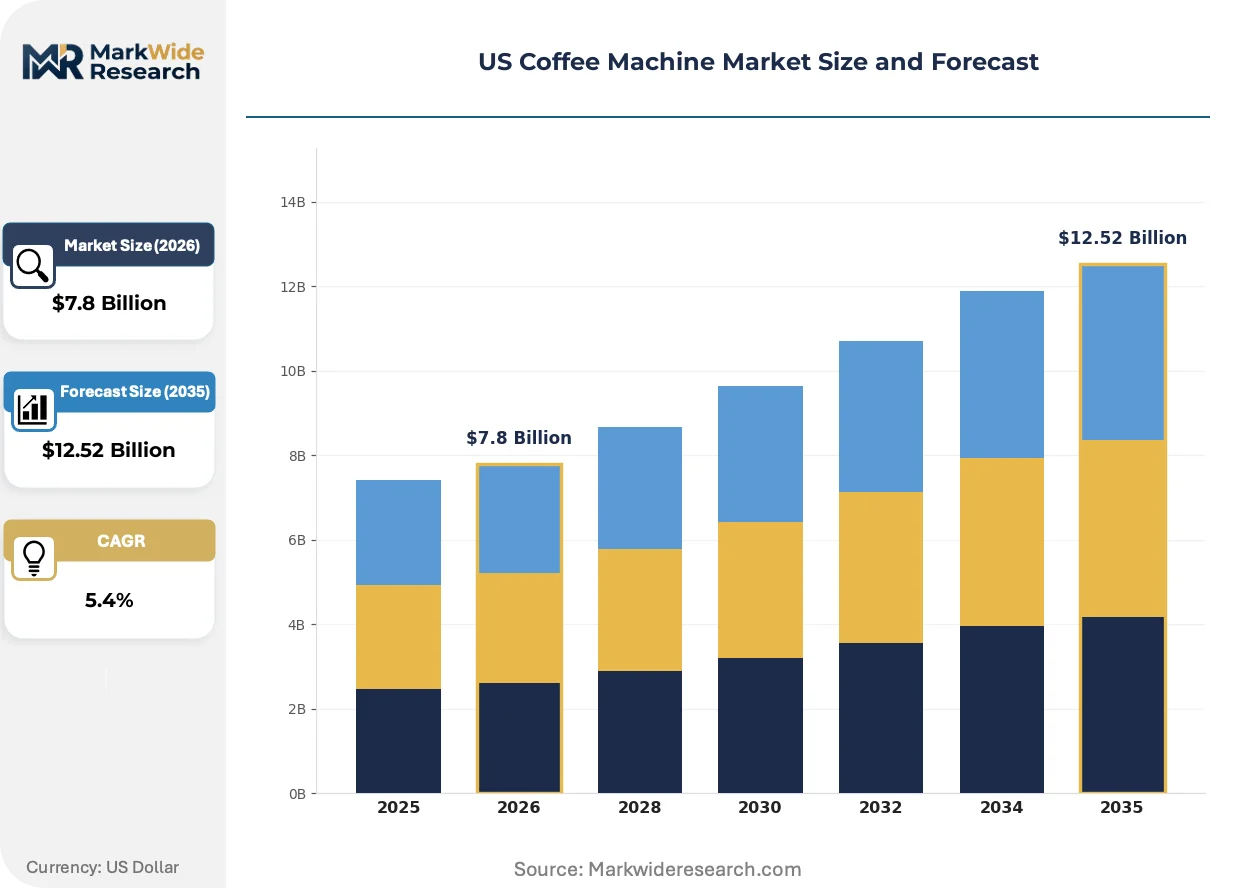
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Espresso Machines, Drip Coffee Makers, Single-Serve Machines, French Press End User: Households, Offices, Cafés, Restaurants Technology: Manual, Semi-Automatic, Fully Automatic, Pod-Based Distribution Channel: Online Stores, Supermarkets, Specialty Retailers, Direct Sales |
| Companies Covered | BUNN-O-Matic Corporation, Breville, Keurig Green Mountain Inc., SharkNinja Operating LLC, Koninklijke Philips N.V., De'Longhi Group, Hamilton Beach Brands Inc., Spectrum Brands, Inc., Nestlé SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Coffee Machine Market Trends and Innovations
Thermoblock heating architectures are virtualizing traditional boiler-based thermal management, while regulatory pressure on standby power and shifting procurement patterns reshape competitive positioning across price tiers.
Thermoblock rapid-heating technology is virtualizing the thermal mass requirements of conventional boiler systems by replacing stored-water reservoirs with flash-heating aluminum blocks. Office and hospitality buyers in Seattle and Portland are specifying these systems for reduced energy draw during idle periods. This shift is compressing the installed base of reservoir-style machines ahead of California's 2027 efficiency enforcement window.
EPA Energy Star 8.0 revisions for commercial foodservice equipment are tightening active-mode and standby power budgets that manufacturers must document through third-party certification. The industrial consequence is accelerated phase-out of resistive heating elements in favor of induction-compatible thermoblock designs. Foodservice operators in California, Washington, and Oregon face the most immediate compliance pressure and are pre-emptively specifying certified equipment in renovation cycles.
Corporate procurement departments are consolidating coffee equipment purchasing under facilities management rather than decentralized office administration, centralizing vendor negotiations and service contracting. This concentration is displacing fragmented local dealer relationships with direct manufacturer or national distributor agreements. The shift is most visible in Fortune 500 headquarters clusters across the San Francisco Bay Area and Puget Sound metro corridors.
US Coffee Machine Market Segmentation
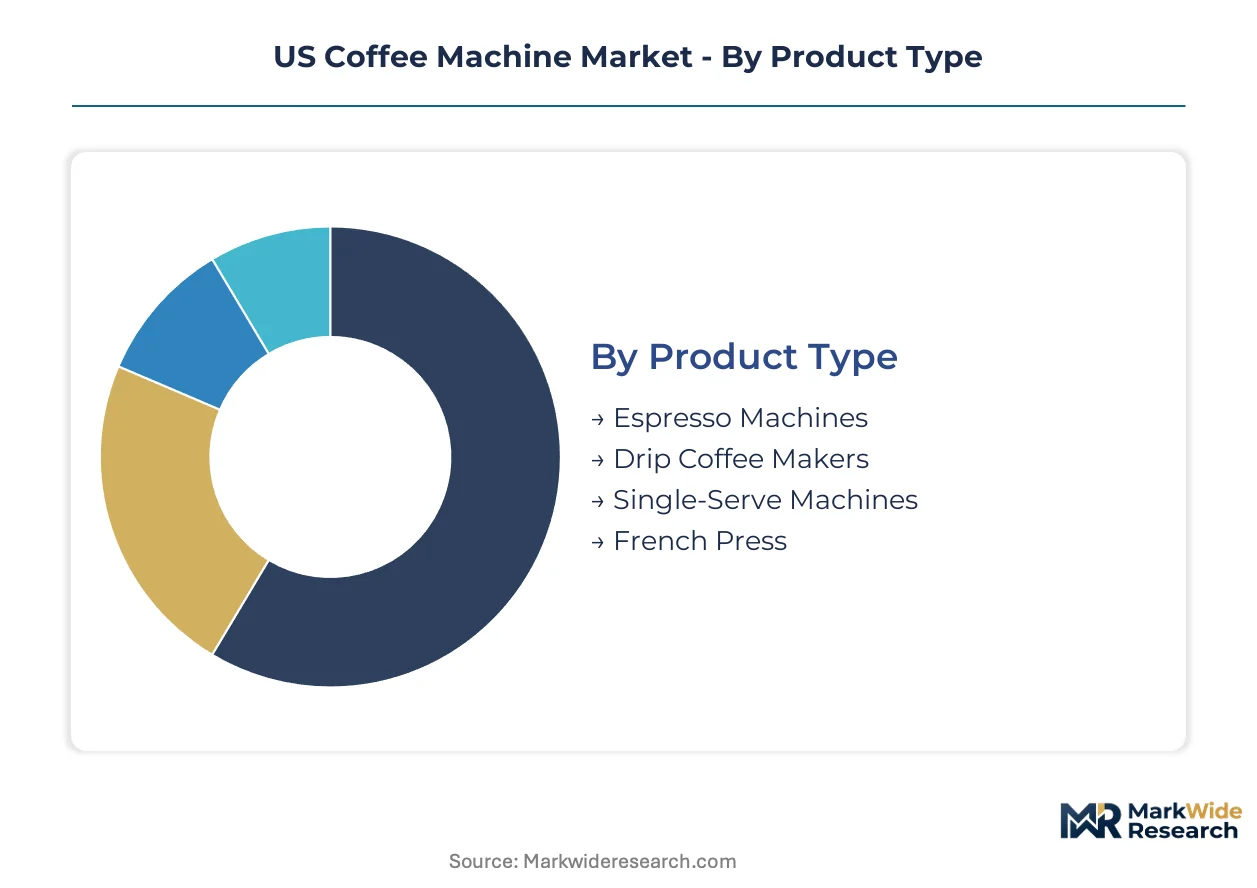
Segmentation in the US coffee machine market reveals distinct replacement cycles and margin profiles across product architectures. Understanding where demand concentrates by technology, end-use, and channel exposes where manufacturers must prioritize R&D and inventory positioning.
Product Type:
Espresso machines turn over slowest due to durability expectations and enthusiast attachment, while single-serve systems cycle fastest through planned obsolescence and pod ecosystem upgrades.
- Espresso Machines:Pump-driven or lever-operated systems achieving 9-bar extraction pressure with portafilter interfaces. Seattle and Portland households sustain penetration rates well above national averages due to third-wave café culture density and home roasting adoption. These units command the highest average selling prices and longest replacement intervals in residential channels.
- Single-Serve Machines:Pod-compatible electromechanical brewers using puncture-and-pressure delivery at 195°F nominal. Corporate offices across the San Francisco Bay Area and Puget Sound corridors are expanding placements as hybrid attendance policies stabilize, driving above-replacement purchase cycles in commercial segments.
- Drip Coffee Makers:Gravity-fed reservoir systems with warming plate or thermal carafe configurations. Midwest and Southern households favor these for volume brewing and lower acquisition cost.
- French Press:Immersion-style manual brewers using coarser grinds and 4-minute steep protocols. Specialty roasting enthusiasts in urban clusters favor these for flavor clarity and zero electrical dependency.
Drip coffee makers dominate installed base across suburban and rural geographies. Single-serve machines are where expansion concentrates in commercial and premium residential segments.
End User:
Cost tier alignment separates commodity procurement in mass-market channels from specification-driven purchasing in foodservice and corporate facilities.
- Households:Disaggregated demand spanning apartment, single-family, and vacation property contexts. Pacific Northwest metros exhibit espresso machine penetration substantially above national benchmarks due to roasting heritage and café culture saturation.
- Offices:Centralized procurement under facilities management rather than decentralized administration. Fortune 500 headquarters clusters in California, Washington, and Oregon are consolidating vendor negotiations and service contracting around national distributor relationships.
- Cafés:Commercial-grade equipment requiring NSF certification and high-duty-cycle components. Independent operators in Portland's third-wave ecosystem specify dual-boiler or heat-exchange systems for milk texturing throughput.
- Restaurants:Back-of-house installations prioritizing speed and volume over extraction nuance. Breakfast-focused chains favor pour-over batch systems or high-capacity drip platforms for throughput consistency.
Households anchor volume demand through replacement cycles. Offices are climbing the fastest as hybrid work stabilization triggers equipment refresh programs.
Technology:
Maturity gradients separate legacy manual methods from converging automation and pod-based convenience architectures.
- Fully Automatic:Integrated grinder-to-cup systems with touchscreen interfaces and programmable extraction parameters. Enthusiast households in Seattle and San Francisco metro areas specify these for café-style output without operational complexity, driving the steepest expansion trajectory in premium residential tiers.
- Pod-Based:Proprietary or compatible sealed-cartridge systems with puncture brewing mechanics. Keurig and Nespresso ecosystems dominate office and hospitality placements through convenience and portion control.
- Semi-Automatic:Pump-driven espresso with user-controlled grind, dose, and extraction timing. Home barista communities favor these for ritual engagement and flavor adjustability.
- Manual:Lever or direct-lever systems requiring full operator control over pressure profiling. Collector and professional barista segments sustain niche demand for these heritage architectures.
Pod-based systems dominate installed base in commercial and convenience-oriented residential contexts. Fully automatic technology is where expansion concentrates as touchscreen integration and grinder convergence reduce skill barriers.
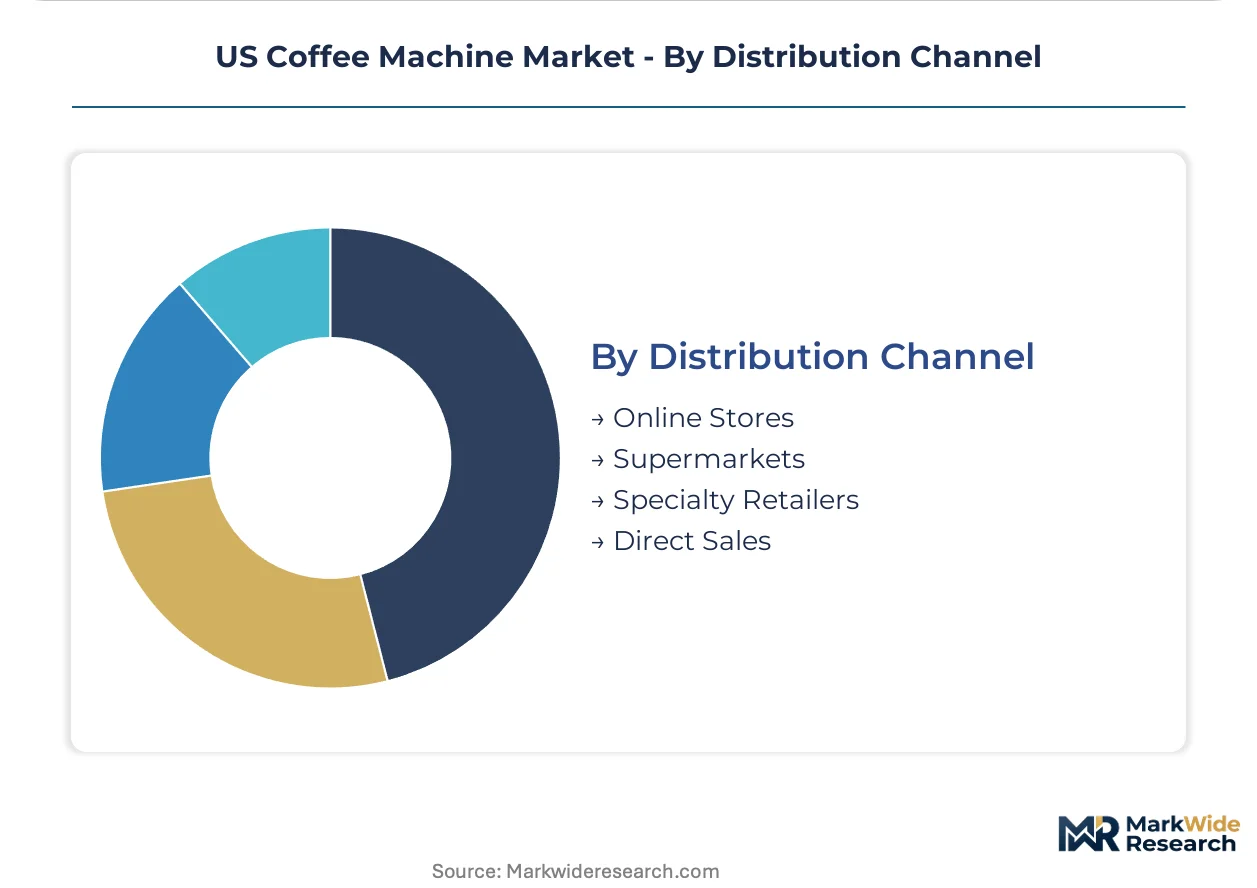
Distribution Channel:
Volume concentration versus margin capture splits between mass retail and specialized service-oriented channels.
- Specialty Retailers:Curated assortments with demonstration capacity and repair service integration. Portland and Seattle independent dealers sustain relationships with roasting operations and enthusiast communities through technical support and equipment education.
- Online Stores:Direct-to-consumer and marketplace platforms with review aggregation and comparison tools. Replacement part availability and warranty fulfillment are becoming decisive conversion factors.
- Supermarkets:Mass-market pod systems and economy drip brewers with high-impulse placement. These channels compress margin pools through promotional intensity and private-label competition.
- Direct Sales:Manufacturer-controlled relationships with foodservice operators and corporate procurement departments. National accounts in California and Washington are consolidating under this channel for service bundling and volume pricing.
Online stores dominate transaction volume growth. Specialty retailers anchor margin capture through service attachment and technical consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest households deploy espresso systems at substantially higher rates than national benchmarks, while corporate procurement in California and Texas favors pod-based convenience for hybrid office configurations.
Pacific Northwest
Seattle's roasting heritage and Portland's third-wave café density sustain household espresso machine penetration well above US averages. Washington and Oregon adopt California's CEC Title 20 standby power standards through regional energy efficiency compacts. Corporate facilities in the Puget Sound corridor are consolidating coffee equipment procurement under centralized vendor contracts.
California
Bay Area technology campuses and Los Angeles entertainment headquarters drive premium single-serve placements as attendance policies stabilize. The California Energy Commission enforces Title 20 appliance efficiency regulations that eliminate non-compliant reservoir-style machines from retail channels. San Diego and Orange County foodservice operators pre-emptively specify thermoblock systems ahead of 2027 compliance deadlines.
Texas
Dallas-Fort Worth and Austin corporate campuses are expanding pod-based installations for distributed workforce models. The Texas Commission on Environmental Quality coordinates with federal EPA Energy Star certification pathways for commercial foodservice equipment. Houston's energy sector headquarters anchor demand for high-capacity brewing systems in executive floor installations.
Northeast Corridor
New York and Boston financial services firms are refreshing office coffee infrastructure around national distributor relationships rather than local dealer networks. New York's right-to-repair legislation creates modular design premiums for field-serviceable equipment with standardized component interfaces. Philadelphia and Washington DC government contractors specify NSF-certified commercial systems for federal facility installations.
Southeast
Atlanta and Miami hospitality operators favor pour-over batch systems for breakfast service throughput in limited-service hotels. Florida's building energy code adopts standby power limits that mirror California's Title 20 thresholds for commercial foodservice equipment. Charlotte's banking sector headquarters are consolidating procurement under facilities management departments for volume pricing leverage.
US Coffee Machine Market Competitive Landscape
Capability concentration sits with European-designed espresso specialists; scale advantage sits with North American pod-system incumbents. The vendor base stratifies across three tiers: heritage European manufacturers with voltage-adapted platforms, domestic brands with commercial foodservice distribution, and Asian contract assemblers with thermoblock manufacturing expertise. Dominant competitive moves include direct procurement consolidation by Fortune 500 facilities departments and thermoblock technology licensing for California compliance.
Among heritage European manufacturers, De'Longhi Group and Koninklijke Philips N.V. exemplify the voltage-adaptation archetype required for 120V US market entry. BUNN-O-Matic Corporation anchors the commercial-grade distribution tier with foodservice operator relationships. These three entities represent distinct strategic positions: European design adaptation, commercial channel depth, and contract manufacturing scale respectively.
| Leading Market Players |
|---|
| BUNN-O-Matic Corporation |
| Breville |
| Keurig Green Mountain Inc. |
| SharkNinja Operating LLC |
| Koninklijke Philips N.V. |
| De'Longhi Group |
| Hamilton Beach Brands Inc. |
| Spectrum Brands, Inc. |
| Nestlé SA |
| Others |
Pricing and Supply Chain Analysis
Vietnam and Mexico border zones concentrate thermoblock assembly capacity for US-bound equipment, anchoring margin capture with brands that maintain direct procurement relationships with Fortune 500 facilities departments rather than fragmented dealer networks.
Pricing Analysis
Long-term offtake agreements between national distributors and corporate procurement departments dominate commercial segments, while spot purchasing persists in residential channels. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified commercial systems from residential pod-based units and entry-level drip brewers. Cost compression in economy-tier thermoblock manufacturing is intensifying because aluminum and copper commodity volatility erodes fixed-margin contracts. Foodservice operators exhibit the lowest price sensitivity due to compliance-driven replacement cycles, whereas mass-market households prioritize acquisition cost over lifecycle efficiency.
Supply Chain Analysis
Precision-extruded aluminum for thermoblock heating elements draws from Vietnam, Mexico, and Chinese component suppliers before final assembly in North American border zones. Copper heating elements and electronic control modules feed from established Asian manufacturing clusters. Single-source vulnerability concentrates in thermoblock die-casting capacity, where limited qualified suppliers create qualification bottlenecks for new entrants. Distribution runs through national distributor relationships with facilities management departments, displacing legacy local dealer networks in corporate and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including preventive maintenance contracts and pod subscription programs are expanding faster than hardware sales, creating recurring-revenue premiums for manufacturers with field-service infrastructure.
For Market Incumbents: Insulate core corporate accounts by embedding thermoblock compliance expertise into facilities management contracts ahead of California's enforcement window. Secure backward integration into aluminum die-casting capacity to buffer commodity volatility. Defend against modular repair specialists by proprietary component interfaces that complicate third-party servicing. For New Entrants and Emerging Players: Establish a beachhead in mobile foodservice fleet installations, where NHTSA-compliant 12V and inverter-compatible systems remain underpenetrated. Target food truck operators and catering vehicle builders with compact thermoblock architectures. Pursue direct sales channel entry rather than competing for supermarket shelf space against entrenched pod-system incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturers with thermoblock engineering capabilities and existing California Energy Commission certification pathways. Long-term viability favors assemblers with geographic diversification across Vietnam and Mexico production footprints. Monitor right-to-repair legislative progression in New York and Minnesota as an inflection signal for modular design premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoblock Technology Licensing | Accelerates California Title 20 compliance for legacy boiler-dependent product lines. |
| Direct Procurement Consolidation | Fortune 500 facilities departments are displacing fragmented local dealer relationships. |
| Smart Machine Connectivity Integration | Wi-Fi-enabled Energy Star monitoring unlocks utility demand-response subsidy programs. |
| Modular Design Standardization | Field-serviceable component interfaces capture premiums from emerging repair mandates. |
| Mobile Foodservice Certification | NHTSA-compliant 12V systems address underpenetrated food truck and catering vehicle demand. |
Research Methodology
Operator-level perspectives from facilities management directors, foodservice equipment procurement leads, specialty retail buyers, and aftermarket service technicians anchored the qualitative base. Primary interview data combined with secondary validation from EPA Energy Star certification databases, California Energy Commission appliance listings, SEC 10-K filings of publicly traded manufacturers, and customs import records for thermoblock components. Bottom-up shipment estimates triangulated against top-down market sizing across product type, end-use, and regional segments.
Scenario-bracketing around regulatory compliance timelines and commodity price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user category, distribution channel, and technology tier. CAGRs derived from replacement cycle analysis, penetration rate trajectories, and price elasticity assumptions. Forecast inputs incorporated thermoblock adoption curves tied to California Title 20 enforcement and corporate hybrid work stabilization patterns.
Macroeconomic conditions sit as an overlay; deviation in aluminum and copper commodity indices, tariff schedules, or freight rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timing and replacement cycle elasticity. Material shifts in right-to-repair legislative progression or EPA Energy Star revision scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Capsules Market
Coffee
Coffee Cherry Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Adaptogen Coffee Market
Coffee
Middle East Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
Green Coffee Bean Extract Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Global Coffee Market
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
China Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
Coffee Roaster Machine Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
APAC Ready-To-Drink Coffee Market