
 Global Nespresso Capsules Market | 2026-2036
Global Nespresso Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nespresso Capsules Market Outlook
Remote workers and boutique hoteliers are reorganizing demand toward single-serve precision brewing. Nestlé sustains proprietary pod architecture across European and Asian licensing agreements. Lavazza specializes in third-party compatible aluminum capsules that bypass patent restrictions. JDE Peet's anchors the office coffee channel through institutional vending partnerships.
Nespresso capsules are hermetically sealed aluminum or compostable polymer pods containing 5–7 grams of roasted, ground coffee, designed for extraction at 19-bar pressure in proprietary brewing systems. Espresso and Lungo capsule types dominate volume, while flavored variants command wider per-unit margins in retail sleeves. The hospitality end-user segment concentrates procurement through bulk packaging contracts, whereas home users drive sleeve-format turnover through subscription platforms.
EU REACH and F-Gas Regulation shape aluminum sourcing and recycling mandates for pod manufacturers. FDA food-contact standards govern US import compliance for polymer-lined capsules. Stakeholders must monitor extended producer responsibility expansions in France and Italy alongside compostable certification timelines from TÜV Austria and OK Compost.
Market Dynamics
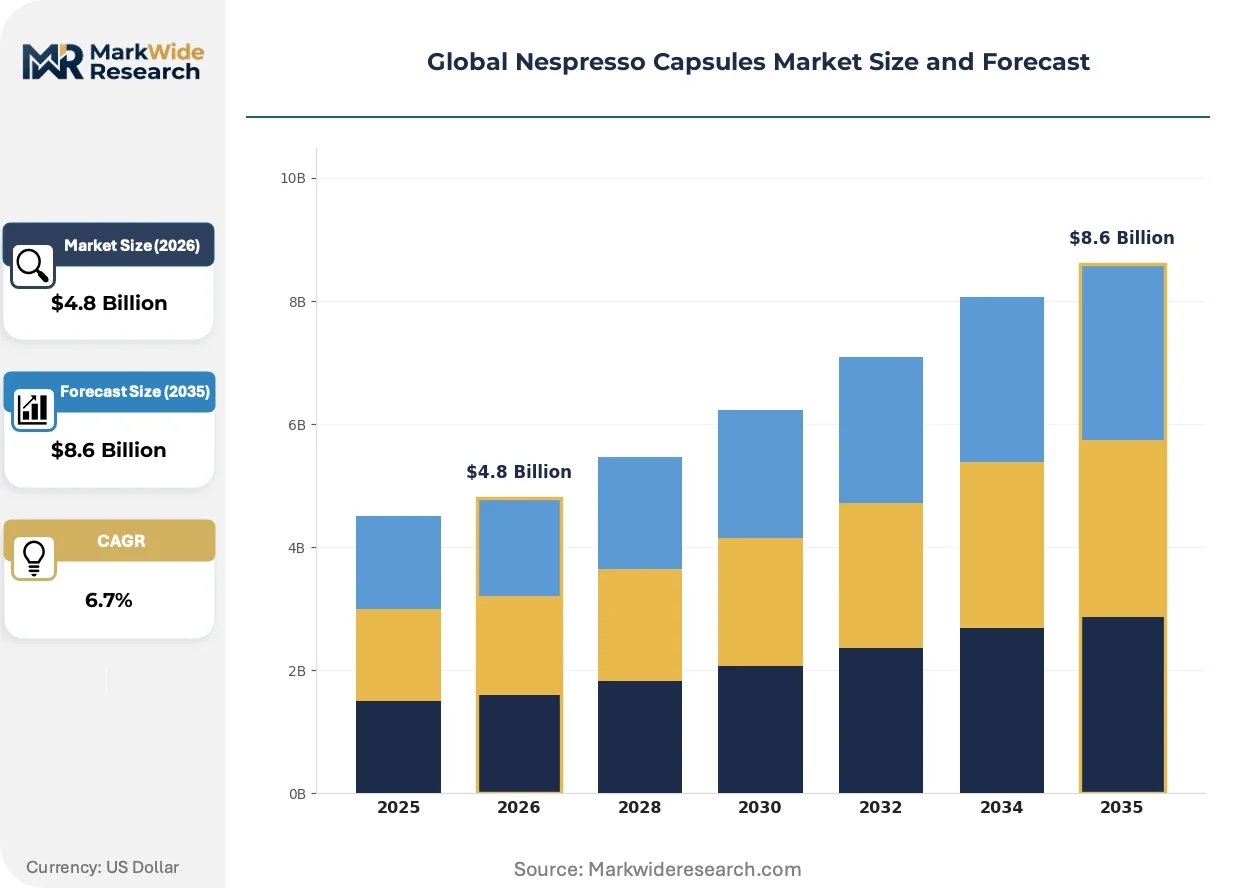
EU packaging waste directives and REACH chemical restrictions are forcing aluminum sourcing reconfigurations across pod manufacturers, while café-at-home consumption patterns concentrate demand in Germany, France, and Italy.
Growth Catalysts
- Extended Producer Responsibility mandates:France and Italy enforce pod-recycling infrastructure investments that normalize circular economy participation. Premium hospitality channels respond with aluminum-compatible procurement contracts.
- Remote work normalization:Boutique hoteliers and home office setups reorganize demand toward single-serve precision brewing systems. Subscription platforms capture recurring revenue from sleeve-format turnover.
- 19-bar extraction technology:Proprietary brewing systems lock in hermetic seal requirements that sustain capsule architecture demand. Espresso and Lungo variants dominate volume throughput.
Market Restraints
- Aluminum price volatility:Primary metal input costs fluctuate with energy-intensive smelting economics. LME price swings compress margin predictability for manufacturers.
- Patent architecture concentration:Nestlé's proprietary pod designs restrict third-party compatibility without licensing agreements. Jurisdictional enforcement varies across European and Asian markets.
- Compostable polymer performance gaps:TÜV Austria certification timelines lag commercial deployment needs. OK Compost standards create formulation uncertainty for polymer-lined alternatives.
Strategic Opportunities
- Underpenetrated Asian licensing markets:Japanese and South Korean café-at-home cultures remain below European per-capita capsule consumption. METI energy efficiency standards favor precision brewing adoption.
- Flavored variant margin expansion:Retail sleeve formats command wider per-unit margins than standard espresso lines. Premium positioning enables ingredient sourcing differentiation.
- Office channel vending integration:Institutional partnerships bypass retail shelf competition. JDE Peet's anchors this channel through bulk packaging contracts.
Industry Challenges
- Dual certification complexity:EU REACH compliance for aluminum sourcing runs parallel to FDA food-contact standards for US polymer-lined imports. Timeline misalignment delays product launches.
- F-Gas Regulation refrigeration dependencies:Cold chain logistics for compostable capsules face refrigerant phase-down requirements. ECHA restrictions complicate temperature-controlled distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nespresso Capsules Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Capsule Type: Espresso, Lungo, Flavored, Decaffeinated Flavor Profile: Intense, Smooth, Fruity, Nutty Packaging Type: Box, Sleeve, Bulk, Single Serve End User: Home, Office, Hospitality, Retail |
| Companies Covered | Illycaffè, Bestpresso, Nestlé, Starbucks, Gourmesso, JDE Peet's, Keurig Dr Pepper, Maxwell House, Lavazza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nespresso Capsules Market Strategic Shifts
Material science advances and regulatory chemistry mandates are actively restructuring pod composition strategies, with aluminum recyclability and polymer biodegradability competing for technical investment priority.
Compostable polymer formulations are decomposing the traditional aluminum monopoly in pod architecture. German and Italian retail channels accelerate adoption of TÜV Austria-certified alternatives. This material transition is compressing the premium pricing power historically held by hermetic metal seals.
EU F-Gas Regulation and REACH chemical restrictions tighten aluminum sourcing and recycling mandates for pod manufacturers. ECHA enforcement requires supply chain documentation for primary metal inputs. Hospitality procurement teams in France and Italy now prioritize suppliers with closed-loop recycling partnerships.
Subscription platforms displace retail sleeve purchases among remote workers and boutique hoteliers. Nestlé's direct-to-consumer infrastructure captures recurring revenue that wholesale channels cannot match. This channel rotation concentrates most visibly in Germany's urban centers.
Global Nespresso Capsules Market Segmentation
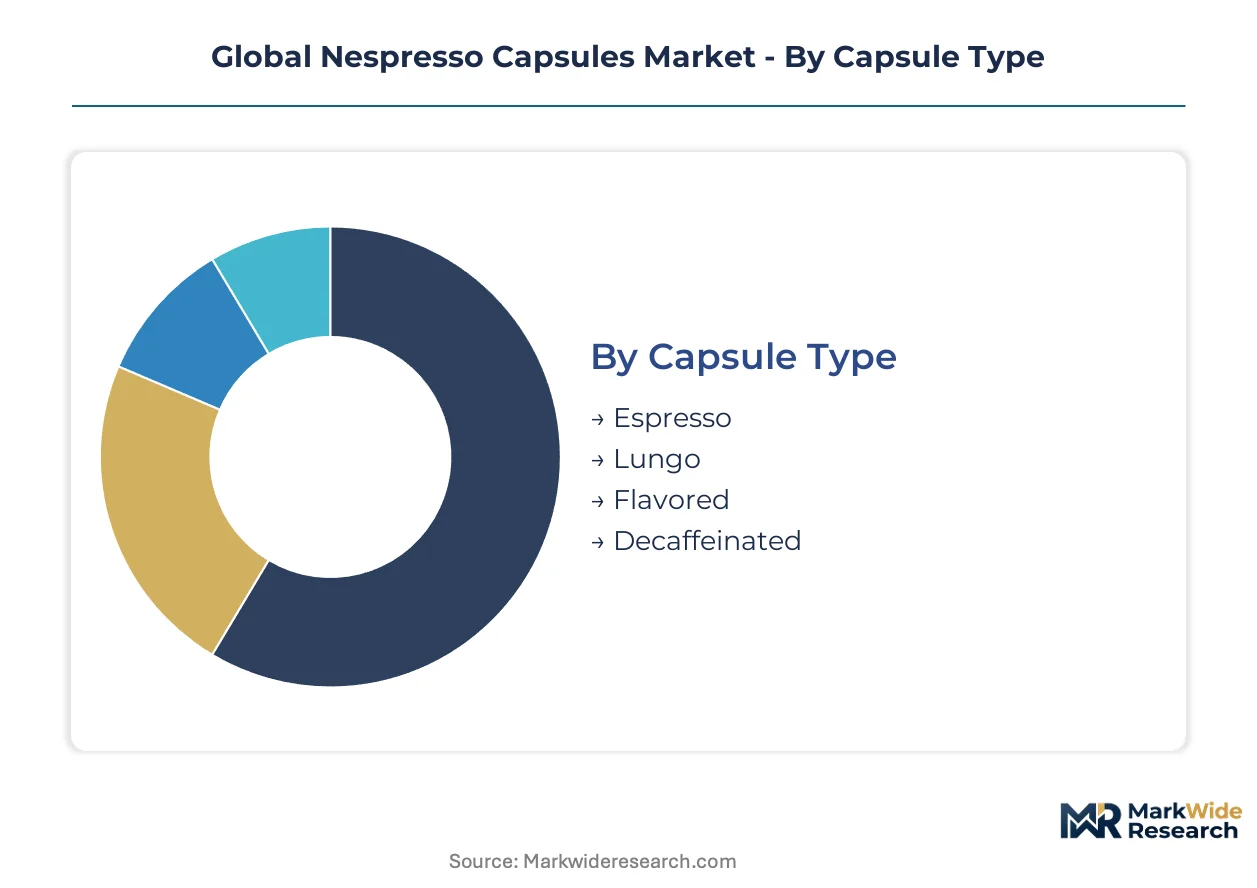
Capsule architecture and consumption context determine margin capture across the Nespresso ecosystem. Material composition, brewing parameters, and procurement channel each create distinct value pools that manufacturers navigate through differentiated positioning.
Capsule Type:
Margin concentration tracks toward variants with ingredient complexity and brewing versatility rather than baseline formulations.
- Espresso:Hermetically sealed aluminum pods containing 5–7 grams of finely ground arabica-robusta blends, engineered for 25–40ml extraction at 19-bar pressure. German and Italian home users drive volume through subscription platforms, with café-at-home culture normalizing daily consumption rituals.
- Flavored:Vanilla, caramel, and cocoa-infused grinds layered between protective foil barriers to prevent aroma migration. Boutique hoteliers in France prioritize these for in-room amenities, where per-unit premiums offset higher ingredient costs.
- Lungo:Extended 110ml extraction format with coarser grind calibration and reinforced seal integrity for longer water contact. Office channel procurement in the Netherlands favors this format for meeting-room brewing stations.
- Decaffeinated:CO2 or water-processed beans maintaining volatile aromatic compounds through pressurized decaffeination. Health-conscious urban consumers in Spain and Switzerland sustain niche demand through pharmacy and specialty retail.
The dominant share belongs to Espresso, while Flavored is closing the gap fastest.
Flavor Profile:
Intensity calibration and roast depth create tiered pricing architecture that separates commodity from specialty positioning.
- Intense:Dark-roasted robusta-dominant blends with cupping scores emphasizing bitterness and body. Southern European markets concentrate demand, with Italian consumers treating these as default breakfast preparations.
- Smooth:Medium-roast arabica formulations with malic acidity suppression through extended Maillard reaction control. French retail channels allocate prime shelf positioning to these balanced profiles.
- Fruity:Light-roast single-origin or regional blends preserving terroir-specific ester and aldehyde compounds. Scandinavian specialty coffee shops drive adoption through origin storytelling.
- Nutty:Brazilian and Colombian base coffees with pyrazine compound emphasis through specific roasting curves. German supermarket private-label programs source these for price-accessible premium positioning.
Intense formulations command the largest volume position, though Fruity profiles are expanding most quickly through third-wave coffee channel penetration.
Packaging Type:
Channel economics and consumption velocity determine format selection, with bulk and subscription models compressing per-unit margins against retail premiums.
- Sleeve:Ten-capsule sealed cardboard units with nitrogen-flushed internal pouches, designed for retail impulse and subscription replenishment. Direct-to-consumer platforms in Germany and the UK capture recurring revenue through automated reorder algorithms.
- Bulk:Fifty-to-one-hundred capsule cases with minimal outer packaging for hospitality and institutional procurement. French hotel chains negotiate annual contracts with closed-loop recycling requirements written into supply agreements.
- Box:Twenty-to-thirty capsule gift-oriented presentations with premium finishing and seasonal artwork. Japanese department stores treat these as omiyage culture accessories during holiday periods.
- Single Serve:Individual capsule vending and trial formats, often promotional or hospitality amenity applications. Airport lounges in Switzerland and the UAE deploy these for traveler sampling.
Sleeve formats dominate revenue contribution, while Bulk packaging is gaining share fastest through hospitality channel consolidation.
End User:
Procurement sophistication and consumption frequency separate stable recurring demand from discretionary purchase patterns.
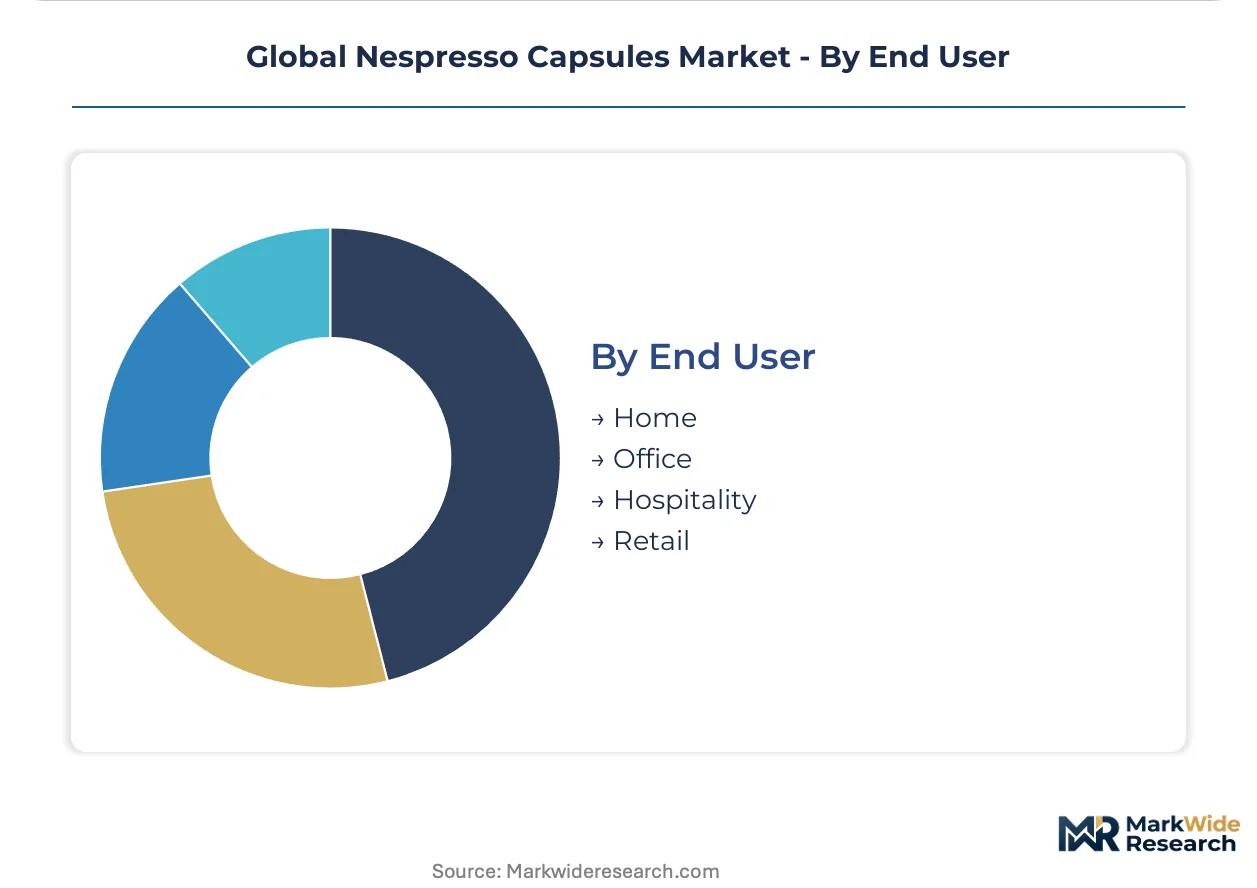
- Home:Individual consumers purchasing through retail, e-commerce, or subscription for daily personal consumption. Remote work normalization in urban Germany and France has elevated machine penetration and capsule throughput.
- Hospitality:Boutique hotels, serviced apartments, and premium B&Bs sourcing through B2B contracts with sustainability compliance requirements. EU packaging waste directives drive aluminum-compatible system selection.
- Office:Corporate facilities and coworking spaces deploying institutional brewing equipment with volume-based supply agreements. JDE Peet's anchors this channel through vending partnership networks.
- Retail:Supermarkets, specialty coffee shops, and convenience stores acting as distribution intermediaries rather than final consumers. Italian retail channels accelerate compostable capsule shelf space allocation.
Home consumption retains the largest demand base, though Hospitality is climbing the fastest as premium accommodation channels reorganize procurement post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss capsule exports flow primarily into German, French, and Italian retail channels, with secondary demand emerging from Japanese hospitality procurement. Aluminum-compatible systems dominate cross-border trade corridors as EU packaging directives tighten material compliance requirements.
Germany
Subscription platforms and café-at-home culture drive capsule throughput in Berlin and Munich metropolitan clusters. ECHA enforcement of REACH chemical documentation mandates closed-loop aluminum sourcing for all pod manufacturers. Bavaria's precision engineering corridor hosts machine-tool suppliers that retrofit brewing equipment for hermetic seal compatibility.
France
Boutique hoteliers in Paris and Lyon reorganize procurement toward aluminum-compatible systems for in-room amenities. Extended Producer Responsibility mandates require pod-recycling infrastructure investments from all hospitality suppliers. The Île-de-France region concentrates demand through premium accommodation channels with annual bulk contracting.
Italy
Daily espresso rituals sustain the highest per-capita capsule consumption in Milan and Rome urban centers. ANSM packaging compliance rules align with EU waste directives to accelerate compostable certification timelines. Piedmont's coffee roasting heritage clusters specialty producers developing TÜV Austria-certified polymer alternatives.
Japan
METI energy efficiency standards favor precision brewing adoption in Tokyo and Osaka household markets. Department store omiyage culture drives seasonal gift-format demand through department store channels. The Kanto region leads machine penetration as remote work normalizes home consumption.
United States
Office channel vending partnerships and remote work setups sustain dual demand streams in New York and California metro areas. FDA food-contact standards govern polymer-lined capsule imports from European suppliers. Pacific Northwest specialty coffee culture creates niche demand for single-origin compatible pods.
Global Nespresso Capsules Market Competitive Environment
Listed leaders compete with private specialists across proprietary technology and third-party compatibility dimensions. Nestlé's vertically integrated structure dominates through direct-to-consumer infrastructure, while Lavazza and JDE Peet's anchor alternative positioning. Three archetypes define competitive positioning: patent-holding system integrators, licensed compatibility manufacturers, and private-label commodity suppliers. M&A activity concentrates on recycling infrastructure assets, while capacity expansion targets Asian licensing markets.
Among European-origin market anchors, Nestlé and Lavazza exemplify divergent strategic postures. Nestlé occupies the proprietary-system tier through hermetic seal technology and subscription platform control. Lavazza represents the licensed-compatibility archetype, specializing in aluminum capsules that bypass patent restrictions through third-party agreements. JDE Peet's anchors the institutional-vending channel through bulk packaging contracts with office and hospitality procurement teams.
| Leading Market Players |
|---|
| Illycaffè |
| Bestpresso |
| Nestlé |
| Starbucks |
| Gourmesso |
| JDE Peet's |
| Keurig Dr Pepper |
| Maxwell House |
| Lavazza |
| Others |
Value Chain & Pricing Dynamics
Sixty-day aluminum inventory cycles in European pod manufacturing compress margin buffers when LME price volatility spikes, concentrating pricing power with vertically integrated suppliers who control primary metal sourcing through closed-loop recycling partnerships.
Pricing Analysis
Next-generation compostable polymer capsules trade at 15-20% premiums over incumbent aluminum architectures, while legacy polymer-lined formats face price erosion from REACH compliance cost absorption. Pricing stratifies across premium hermetic seals, standard aluminum compatibility, and economy-grade third-party pods based on certification tier and brewing system exclusivity. Cost compression in standard-tier capsules intensifies because Lavazza and compatibles flood retail channels with patent-bypass alternatives. Boutique hoteliers show least price sensitivity, prioritizing closed-loop recycling credentials in procurement contracts.
Supply Chain Analysis
Switzerland and Germany anchor precision aluminum forming and hermetic seal manufacturing, while Italy concentrates coffee roasting and flavor formulation capabilities. Raw material flows draw from Guatemalan and Colombian arabica suppliers, Norwegian aluminum smelters, and Austrian polymer compounders. Single-source vulnerability concentrates in Nestlé's proprietary brewing system licensing, which controls capsule geometry specifications. Distribution runs through direct-to-consumer subscription platforms, hospitality B2B contracts, and retail sleeve replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from compostable polymer alternatives and third-party compatible capsules that erode proprietary system lock-in.
For Market Incumbents: Compound subscription platform retention through exclusive flavor variant releases that third-party manufacturers cannot replicate. Deepen backward integration into aluminum recycling infrastructure to neutralize ECHA sourcing documentation requirements and defend margin position against Lavazza-compatible price competition. For New Entrants and Emerging Players: Differentiate on TÜV Austria-certified compostable formulations that bypass Nestlé patent architecture entirely. Target Japanese and South Korean licensing markets where METI energy efficiency standards favor precision brewing adoption but per-capita consumption remains below European benchmarks. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because EU Extended Producer Responsibility mandates transform recycling asset ownership into competitive moats. Acquisition targets should cluster around closed-loop aluminum recovery operators and compostable certification laboratories. The signal to watch is ANSM enforcement timelines for Italian packaging compliance rules.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Partnership | ECHA documentation requirements now mandate traceable aluminum sourcing from European smelters. |
| Compostable Certification Investment | TÜV Austria and OK Compost standards unlock retail shelf space in German and Italian channels. |
| Direct-to-Consumer Platform Expansion | Subscription algorithms capture recurring revenue that wholesale hospitality contracts cannot match. |
| Asian Licensing Market Entry | METI standards in Japan and South Korea favor precision brewing with low per-capita penetration. |
| Flavored Variant Pipeline Development | Vanilla and caramel infusions command wider margins than baseline espresso in boutique hotel procurement. |
Study Parameters
A spread of perspectives from Nespresso system engineers, hospitality procurement managers, aluminum smelter sustainability officers, and specialty coffee roasters converged on the working assumptions. Primary fieldwork combined structured interviews with channel partners and machine-tool suppliers alongside secondary validation through EU packaging directive filings, ECHA REACH registration databases, and customs trade flow records. Bottom-up capsule volume estimates triangulated against top-down market value reconstructions.
Segmentation dimensions modeled include capsule architecture type, flavor intensity calibration, packaging format velocity, and end-user procurement sophistication across the projection horizon. CAGRs derived from historical consumption elasticities and machine penetration curves, incorporating aluminum price volatility bands and compostable certification adoption timelines as scenario inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated compostable performance breakthroughs would require recalibration. Forecasts reflect documented assumptions about hospitality channel recovery velocity and remote work normalization persistence. Recalibration cycles align with material shifts in ECHA enforcement priorities and TÜV Austria certification standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Cold Brew Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
High Protein Coffee Market
Coffee
Middle East Coffee Market
Coffee
Espresso Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
North America Coffee Market
Coffee
Canned Coffee Market
Coffee
RTD Coffee Market
Coffee
Global Coffee Market
Coffee
China Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Bags Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
Coffee Pods and Capsules Market