
 US Coffee Roaster Market | 2026-2036
US Coffee Roaster Market Size, Share, and Industry Trends Forecast 2026-2036
US Coffee Roaster Market Insights
Multi-source green bean procurement is hardening as roasters diversify away from single-origin dependency. Starbucks Coffee Company leverages its vertically integrated supply chain to secure long-term contracts with Latin American cooperatives. Intelligentsia Coffee Roasters differentiates through direct trade relationships that bypass conventional commodity markets. Onyx Coffee Lab anchors its competitive position in Northwest Arkansas through precision-profile roasting technology and limited-batch releases.
A coffee roaster is a thermal processing machine that applies controlled heat to green coffee beans at temperatures between 370°F and 540°F, inducing Maillard reactions and pyrolysis to develop flavor compounds, aroma oils, and bean structure for commercial brewing or retail sale. Batch roasters dominate the specialty segment where profile repeatability and small-lot flexibility command premium pricing, while continuous roasters serve high-volume commercial operators with throughput demands exceeding 1,000 pounds per hour. Electric roasters are gaining share in urban markets where municipal emissions ordinances restrict gas-fired equipment, though gas roasters retain cost advantages in regions with lower natural gas tariffs.
The FDA enforces Current Good Manufacturing Practice requirements for food equipment surfaces and allergen controls, while the USDA administers organic certification standards that constrain permissible cleaning agents and lubricants in certified roasting operations. The Occupational Safety and Health Administration monitors combustible dust hazards from roasted coffee particulate, driving demand for upgraded ventilation and fire suppression systems. Stakeholders must monitor evolving municipal electrification mandates and carbon disclosure rules that will reshape capital expenditure priorities for roasting equipment replacement cycles.
Market Dynamics
Municipal electrification mandates in Portland, Seattle, and San Francisco are forcing roasting operations to retire gas-fired equipment ahead of depreciation schedules, compressing capital replacement cycles and reshaping vendor competition.
Growth Catalysts
- FDA Food Safety Modernization Act:The Act's preventive controls rule elevates equipment traceability requirements, driving replacement demand for roasters with integrated data-logging capabilities.
- Specialty café chain expansion:National café operators are installing in-house roasting programs to differentiate on freshness and origin storytelling, creating pull for mid-capacity batch systems.
- USDA organic certification growth:Expanding organic coffee sales constrain permissible cleaning agents and lubricants, favoring roaster designs engineered for certified operation from installation.
Market Restraints
- Green bean price volatility:Arabica futures on the Intercontinental Exchange swing with Brazilian frost and Colombian rainfall patterns, squeezing roasting margins and deferring equipment purchases.
- Combustible dust regulation:OSHA's National Emphasis Program on combustible dust mandates upgraded ventilation and fire suppression, adding fifteen to twenty-five percent to facility retrofit costs.
- Natural gas tariff differentials:Regions with elevated utility rates lose cost advantages for thermal roasting, disadvantaging operators in the Northeast against Pacific Northwest competitors.
Strategic Opportunities
- Electric roasting technology:Municipal emissions ordinances in California and Pacific Northwest cities create first-mover advantage for vendors with mature electric product lines.
- Direct trade procurement models:Roasters bypassing commodity exchanges for farmer relationships need profile-repeatability equipment that documents batch provenance for retail storytelling.
- Carbon disclosure rules:Emerging SEC climate disclosure requirements and state-level mandates in California will favor roasting operations with verifiable emissions data, advantaging connected equipment platforms.
Industry Challenges
- Roastmaster talent scarcity:The specialized skill of profile development across origin varietals concentrates in Portland and Seattle, constraining expansion in secondary markets.
- Legacy equipment integration:Retrofitting existing facilities with emission-compliant ventilation while maintaining production continuity demands phased capital deployment that smaller operators struggle to sequence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Coffee Roaster Market |
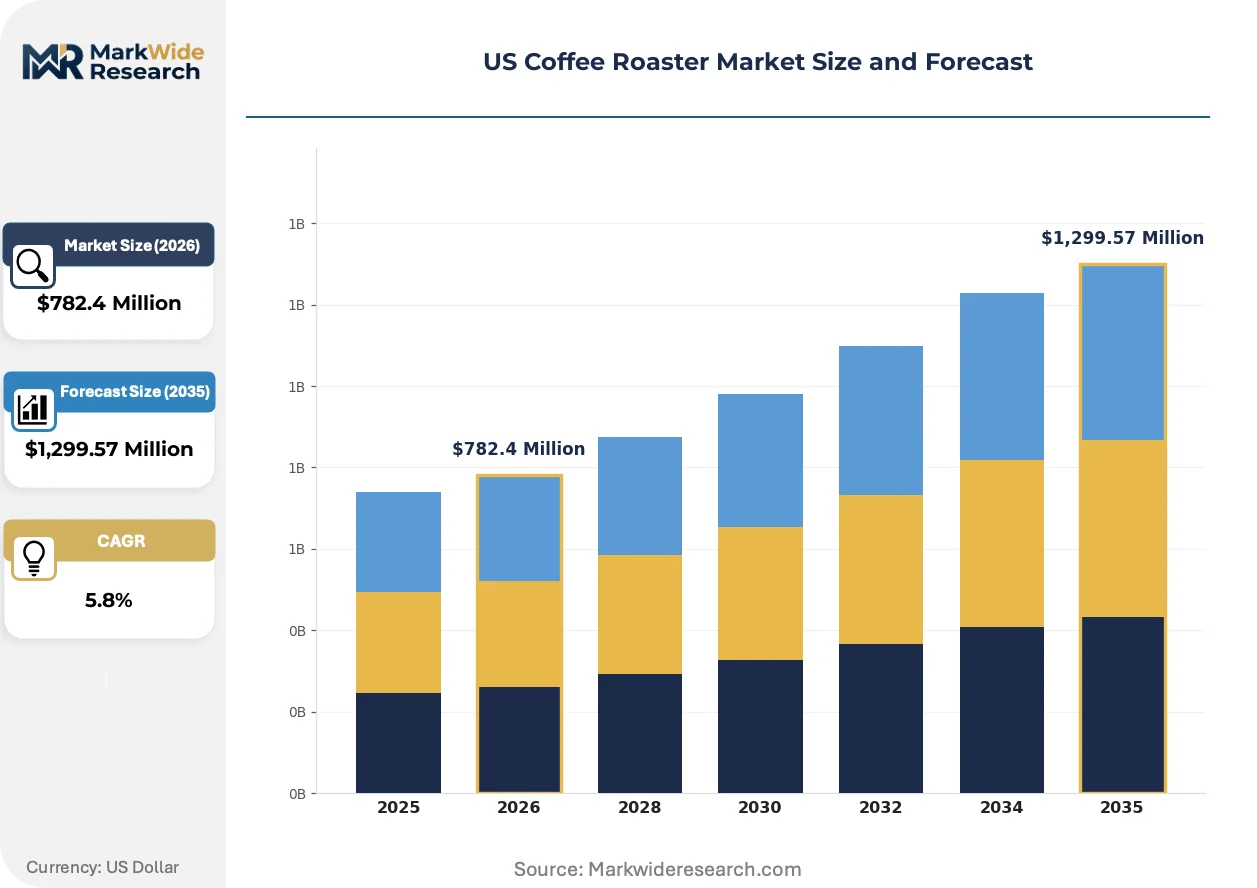
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,299.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Roasters, Continuous Roasters, Specialty Roasters, Commercial Roasters End User: Restaurants, Cafés, Gourmet Shops, Retail Outlets Distribution Channel: Direct Sales, Online Sales, Wholesalers, Distributors Technology: Electric Roasters, Gas Roasters, Hybrid Roasters, Manual Roasters |
| Companies Covered | Starbucks Coffee Company, Keurig Green Mountain, Dunkin' Donuts, Intelligentsia Coffee Roasters, Blue Bottle Coffee Roasters, Onyx Coffee Lab, Heart Coffee Roasters, Sey Coffee, Verve Coffee Roasters, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Coffee Roaster Market Trends and Innovations
Roasting technology is converging with data analytics and emission controls, compressing the traditional gap between craft precision and commercial throughput while regulatory pressure accelerates equipment refresh cycles.
Precision-profile roasting software is consolidating control over batch repeatability and energy consumption. Mid-sized specialty roasters in Denver and Austin are adopting these platforms fastest, seeking to replicate Seattle-level quality consistency without comparable talent depth. The technology is consolidating vendor market share toward integrated hardware-software providers and squeezing standalone equipment manufacturers.
The EPA's evolving standards for commercial kitchen emissions intersect with municipal electrification timelines in California and Oregon. Industrial consequence includes accelerated depreciation of gas-fired assets and preference for electric roasting systems in new facility planning. Pacific Northwest operators face the most compressed compliance windows and are piloting heat-recapture electric designs.
Direct trade procurement is displacing commodity exchange purchasing among specialty roasters above fifty-thousand-pound annual volume. This bypasses C-contract pricing and demands roasting equipment with origin-specific profile libraries and batch documentation for retail transparency. The shift is most visible in Portland, where café-roaster hybrids market single-farm provenance as core differentiation.
US Coffee Roaster Market Segmentation
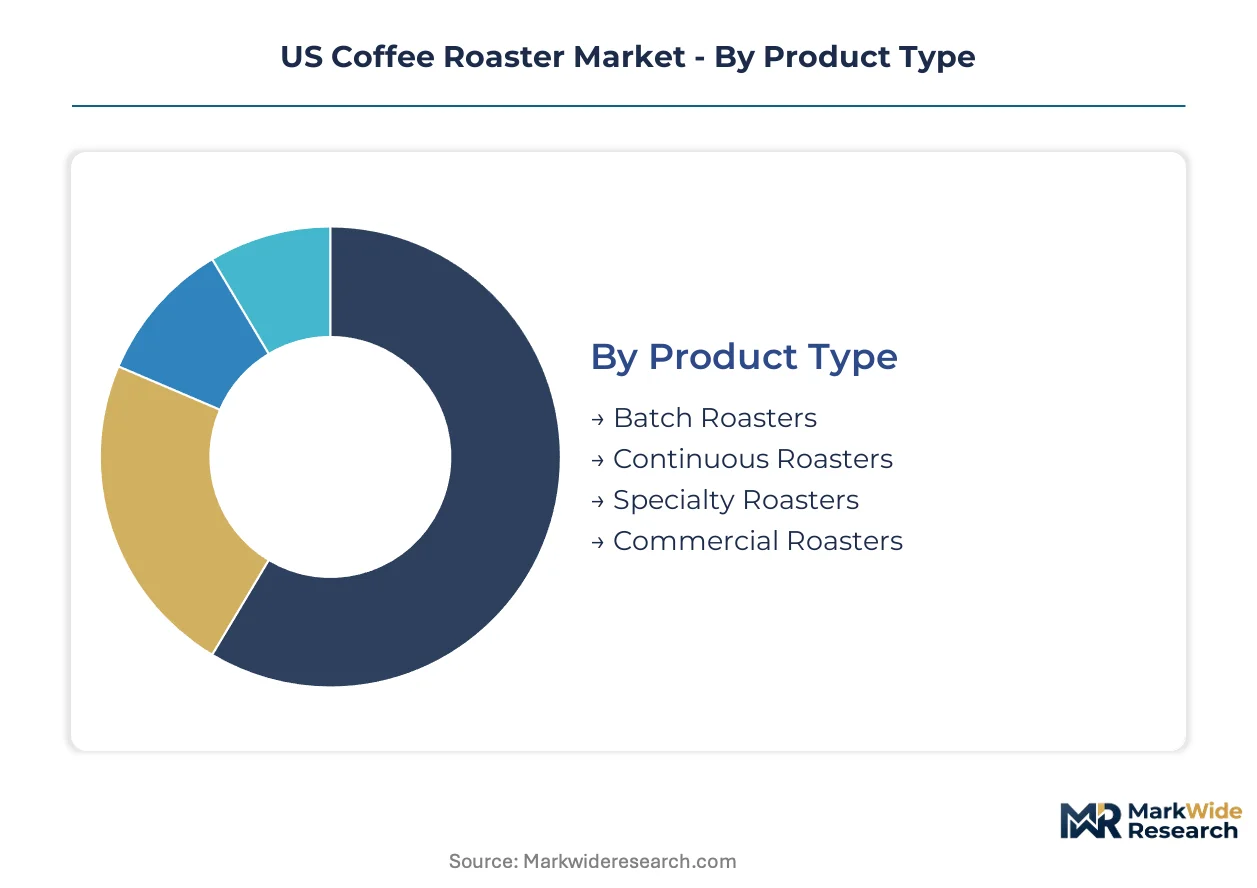
Equipment replacement cycles in the US coffee roaster market compress as municipal electrification mandates force premature retirement of gas-fired assets. Segment boundaries blur when roasters configure hybrid systems to bridge compliance windows. Procurement patterns concentrate around vendors offering modular upgrade paths rather than full-system replacement.
Product Type:
Upgrade trajectories diverge sharply between facilities facing compressed compliance deadlines and those with longer depreciation runways.
- Batch Roasters:These machines process discrete loads of 5 to 70 pounds per cycle with programmable temperature curves and airflow modulation. Specialty café chains in Portland and Seattle deploy mid-capacity batch systems to support origin-specific profile libraries and retail storytelling around single-farm provenance.
- Continuous Roasters:Drum or fluid-bed designs move green beans through heated zones on conveyor systems, sustaining throughput above 1,000 pounds per hour. High-volume commercial operators in the Midwest rely on these systems where municipal emissions ordinances remain less restrictive than Pacific Northwest mandates.
- Specialty Roasters:Compact footprint machines with precision data-logging and repeatability software dominate urban roasting labs.
- Commercial Roasters:Standardized thermal systems serve foodservice distributors and private-label producers with volume consistency priorities.
Batch Roasters sits at the top of the volume ranking, with Specialty Roasters climbing the fastest.
End User:
Application-specific thermal requirements and origin-marketing ambitions reshape equipment specifications across buyer categories.
- Restaurants:Fine-dining operators in New York and Chicago install compact electric roasters as front-of-house theater, roasting 10 to 25 pounds weekly for menu integration and guest engagement. The FDA's preventive controls rule drives demand for integrated data-logging that documents batch provenance for health inspectors.
- Cafés:Multi-location operators build in-house roasting programs to differentiate on freshness windows and direct-trade narratives. Stumptown Coffee Roasters and Blue Bottle Coffee anchor this segment with flagship roasting facilities that supply regional store networks.
- Gourmet Shops:Specialty retailers curate rotating single-origin offerings with small-lot flexibility.
- Retail Outlets:Grocery chains and mass merchants source private-label coffee through contract roasting relationships.
Cafés command the largest installed base, though Restaurants are expanding most quickly as experiential dining formats proliferate.
Distribution Channel:
Channel economics shift as vendor consolidation and direct procurement platforms displace traditional intermediary structures.
- Direct Sales:Manufacturers maintain field engineering teams for installation, commissioning, and preventive maintenance contracts. Probat and Diedrich Roasting Systems dominate this channel with factory-direct service networks covering major metropolitan roasting clusters.
- Online Sales:Entry-level electric roasters and replacement components move through manufacturer portals and industrial equipment marketplaces. Municipal electrification mandates accelerate online specification research as operators compare emission-compliant models.
- Wholesalers:Regional equipment distributors stock mid-capacity systems for faster delivery timelines.
- Distributors:Multi-brand aggregators serve secondary markets with limited manufacturer presence.
Direct Sales retains the dominant revenue share, while Online Sales gains traction fastest among independent operators.
Technology:
Thermal system selection now hinges on utility tariff structures, ventilation constraints, and municipal compliance windows rather than pure capital cost.
- Electric Roasters:Resistance-element or infrared heating systems eliminate on-site combustion and simplify ventilation requirements. San Francisco and Portland operators pilot heat-recapture electric designs as compressed compliance deadlines force gas-to-electric conversions ahead of depreciation schedules.
- Gas Roasters:Direct-fire or indirect-fired burners retain thermal efficiency advantages where natural gas tariffs remain below national averages. Texas and Louisiana roasting facilities continue specifying gas systems where municipal ordinances permit.
- Hybrid Roasters:Dual-fuel configurations allow operators to switch thermal sources as regulations or utility economics shift.
- Manual Roasters:Artisan-scale drum roasters serve training programs and micro-lot experimentation.
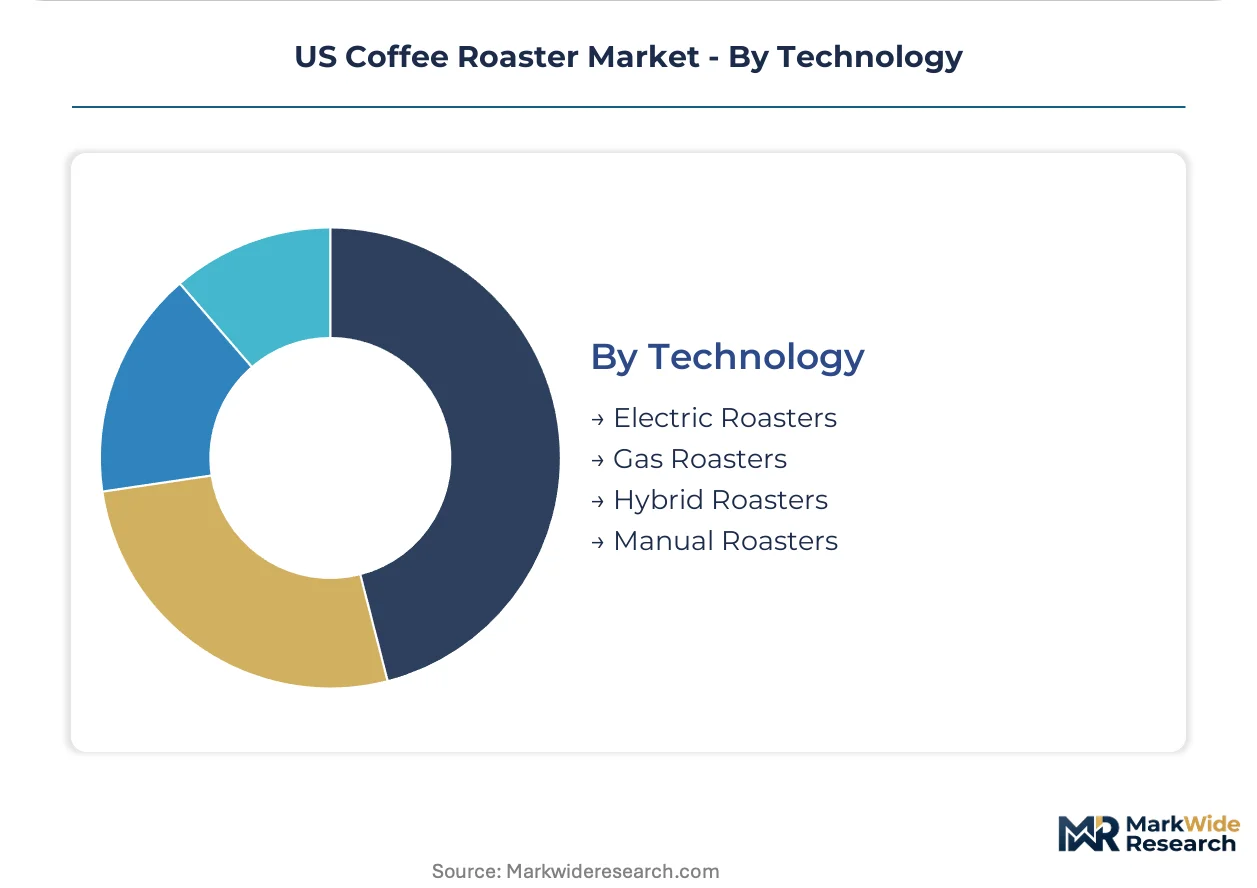
Gas Roasters still leads in cumulative installations, though Electric Roasters is expanding most quickly as coastal electrification mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest urban clusters anchor US coffee roaster demand through Portland and Seattle's craft roasting density, the nation's highest. State-level electrification mandates and municipal emissions ordinances compress equipment replacement cycles unevenly across metropolitan markets.
Pacific Northwest
Portland and Seattle roasting operations face the nation's most compressed compliance windows for gas-to-electric conversion. Oregon DEQ and Washington Ecology administer state-level carbon pricing mechanisms that accelerate depreciation schedules for combustion equipment. Seattle roasting labs pilot heat-recapture electric designs while Portland café-roaster hybrids market single-farm provenance through precision-profile systems.
California
Bay Area and Los Angeles roasting facilities confront municipal electrification mandates in San Francisco and emerging state-level rules. CARB administers cap-and-trade compliance obligations that elevate operating costs for gas-fired thermal systems. San Francisco operators pilot zero-emission roasting configurations ahead of statewide appliance efficiency standards.
Northeast Corridor
New York and Boston metropolitan roasting operations absorb elevated natural gas tariffs that erode thermal cost advantages against Pacific Northwest competitors. EPA Region 2 enforces commercial kitchen emissions standards that intersect with state-level clean energy mandates. Brooklyn and Queens roasting facilities concentrate around converted industrial warehouse districts with ventilation retrofit challenges.
Southwest
Texas roasting operations in Austin and Dallas retain gas-fired cost advantages where municipal ordinances remain permissive. TCEQ administers air quality permits with less restrictive timelines than coastal jurisdictions. Austin specialty roasters adopt precision-profile software fastest among secondary markets, seeking quality consistency without comparable roastmaster talent depth.
Mountain West
Denver roasting operations balance growth ambitions against thinner roastmaster labor pools and moderate regulatory pressure. Colorado Department of Public Health oversees emissions permitting with compliance windows less compressed than Pacific Northwest mandates. Denver specialty roasters consolidate mid-capacity batch system procurement as the region's fastest-growing roasting cluster outside coastal markets.
US Coffee Roaster Market Competitive Landscape
Global majors compete with regional champions across equipment supply and café-roaster hybrid operations, producing a tiered structure with consolidated vendor bases and fragmented retail roasting. Probat and Diedrich Roasting Systems anchor factory-direct service networks against emerging electric-specialist entrants. Three archetypes dominate: vertically integrated café chains, independent precision-profile specialists, and contract roasting operators serving private-label demand. Competitive moves concentrate on modular electric product line expansion and direct trade procurement platform development.
Within the vertically integrated café chain tier, Starbucks Coffee Company and Blue Bottle Coffee Roasters exemplify operators capturing margin through in-house roasting program control. Among independent precision-profile specialists, Intelligentsia Coffee Roasters and Onyx Coffee Lab occupy positions defined by direct trade relationships and batch documentation capabilities for retail transparency. These named entities anchor archetype descriptions without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Starbucks Coffee Company |
| Keurig Green Mountain |
| Dunkin' Donuts |
| Intelligentsia Coffee Roasters |
| Blue Bottle Coffee Roasters |
| Onyx Coffee Lab |
| Heart Coffee Roasters |
| Sey Coffee |
| Verve Coffee Roasters |
| Others |
Pricing and Supply Chain Analysis
Municipal electrification mandates in Portland, Seattle, and San Francisco gate qualified supply access and premium-tier pricing power, as emission-compliant electric roasting systems command tiered premiums over gas-fired alternatives while operators in unrestricted markets retain cost advantages through conventional thermal equipment.
Pricing Analysis
Input-cost pass-through from green bean procurement dominates pricing dynamics, with Arabica futures volatility on the Intercontinental Exchange compressing roasting margins and intensifying cost pressure across mid-capacity operators. Three-tier pricing structure across premium, standard, and economy levels separates precision-profile electric systems with integrated data-logging from basic batch configurations and entry-level manual equipment. Price differentiation centers on certification grade—USDA organic and FDA preventive controls compliance—and after-sales service bundling including preventive maintenance contracts. Cost compression in the standard tier is intensifying because green bean price volatility squeezes operators deferring equipment purchases, while gourmet shops and fine-dining restaurants demonstrate lowest price sensitivity due to experiential positioning and menu integration requirements.
Supply Chain Analysis
Green coffee bean supply rests on Brazilian, Colombian, and Ethiopian agricultural output, with roasting equipment manufacturing anchored in German, Italian, and US production clusters. Raw material dependencies include specialty steel alloys for roasting drums, precision temperature sensors, and emission-control ventilation components. Single-source vulnerability concentrates in high-grade green bean varietals from specific Latin American cooperatives, exposing roasters to frost and rainfall pattern disruptions. Distribution runs through factory-direct service networks for commercial-scale systems, while entry-level electric roasters move through manufacturer portals and industrial equipment marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US coffee roaster market functions as a stable compounder, with regulatory-driven equipment refresh cycles generating predictable replacement demand across municipal compliance windows.
For Market Incumbents: Anticipate compressed capital replacement cycles in Pacific Northwest urban clusters by accelerating modular electric product line development and securing factory-direct service contracts ahead of municipal ordinance enforcement. Defensive positioning requires backward integration into precision-profile software capabilities to counter emerging electric-specialist entrants, while certification investment in USDA organic-compliant designs captures premium-tier procurement from direct trade roasters. For New Entrants and Emerging Players: Heat-recapture electric roasting technology offers a technology-first wedge into San Francisco and Portland markets facing the most compressed gas-to-electric compliance deadlines. White-space targets include mid-capacity batch systems for Denver and Austin specialty roasters seeking Seattle-level quality consistency without comparable roastmaster talent depth, and compact electric units for New York and Chicago fine-dining operators pursuing front-of-house theater applications. A subscription-based preventive maintenance go-to-market angle differentiates against legacy vendors reliant on transactional equipment sales. For Investors and Strategic Acquirers: Roll-up economics work for regional precision-profile specialists because fragmented independent roasting operations lack capital sequencing capability for phased facility retrofit compliance. Long-term viability framing centers on five-to-ten year municipal electrification mandate proliferation across coastal states, with acquisition targets clustering around electric-specialist equipment vendors and direct trade procurement platforms. The signal to watch is EPA commercial kitchen emissions standard tightening intersecting with state-level carbon pricing mechanism adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Electric Product Line Expansion | Probat and Diedrich factory-direct networks capture premature replacement demand from Portland and Seattle operators. |
| Precision-Profile Software Integration | Denver and Austin mid-capacity roasters adopt data-logging platforms to replicate coastal quality consistency. |
| Direct Trade Procurement Platform Development | Intelligentsia and Onyx bypass commodity exchanges through farmer relationship documentation for retail transparency. |
| Certified Organic Equipment Design | USDA organic compliance constraints on cleaning agents favor roasters engineered for certified operation from installation. |
| Preventive Maintenance Contract Scaling | Integrated service bundling locks in multi-year revenue streams from café chain in-house roasting program expansions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with roasting equipment manufacturers, café chain procurement directors, specialty roaster operations managers, and municipal environmental compliance officers with secondary validation from FDA preventive controls guidance documents, USDA organic certification standards, EPA commercial kitchen emissions databases, and OSHA combustible dust enforcement records. Bottom-up equipment shipment data triangulated against top-down café chain capital expenditure disclosures and regional utility electrification mandate timelines.
Segment-weighting approaches modeled product type, end user category, distribution channel, and thermal technology dimensions across the analysis window, with CAGRs derived from equipment replacement cycle compression rates and municipal compliance deadline clustering. Forecast inputs incorporated green bean futures volatility patterns, natural gas tariff differentials by utility territory, and roastmaster labor pool concentration indices for secondary market expansion feasibility.
The model holds under stable regulatory enforcement timelines and continuous green bean supply availability; deviation in Brazilian frost severity or accelerated EPA emissions standard tightening would shift equipment procurement trajectories. A small set of named triggers—municipal electrification mandate proliferation pace, Arabica futures volatility spikes, and OSHA combustible dust enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Oceania Coffee Market
Coffee
Instant Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Global Coffee Shop Market
Coffee
North America Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Global Portable Coffee Makers Market
Coffee
Coffee Pods and Capsules Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Out-Of-Home Coffee Market
Coffee
Coffee Premixes Market
Coffee
Coffee Grinder Market
Coffee
Cold Brew Coffee Makers Market