
 Specialty Coffee Market | 2026-2036
Specialty Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Coffee Market Intelligence
Specialty café and food service procurement is restructuring around experiential consumption and origin transparency. Starbucks leverages its direct trade network across Latin American estates to sustain premium bean access. illycaffè anchors its competitive position through rigorous Arabica blending protocols and single-origin reserves. JDE Peet's competes on scale, controlling roasting infrastructure across European and Asian distribution hubs.
Specialty coffee comprises arabica-dominant beans scoring 80+ on the Specialty Coffee Association cupping scale, processed through washed, natural, or honey methods to preserve terroir-specific acidity and aromatic complexity. Its primary commercial purpose is to command price premiums through provenance storytelling and sensory differentiation in out-of-home consumption. Single Origin offerings lead margin pools due to traceability premiums, while Cold Brew segments capture fastest-growing demand through ready-to-drink convenience expansion. Food Service channels dominate volume throughput, though Online Consumers represent the most rapidly expanding customer type through subscription and direct-to-origin platforms.
FDA food safety standards and USDA organic certification govern import and labeling protocols for US-bound specialty coffee, while EU Green Deal deforestation regulations and EUDR traceability mandates reshape European sourcing requirements. REACH chemical compliance affects processing equipment and packaging materials across both jurisdictions. Stakeholders must monitor evolving origin certification schemes and carbon accounting rules to secure long-term supply access and consumer trust.
Market Dynamics
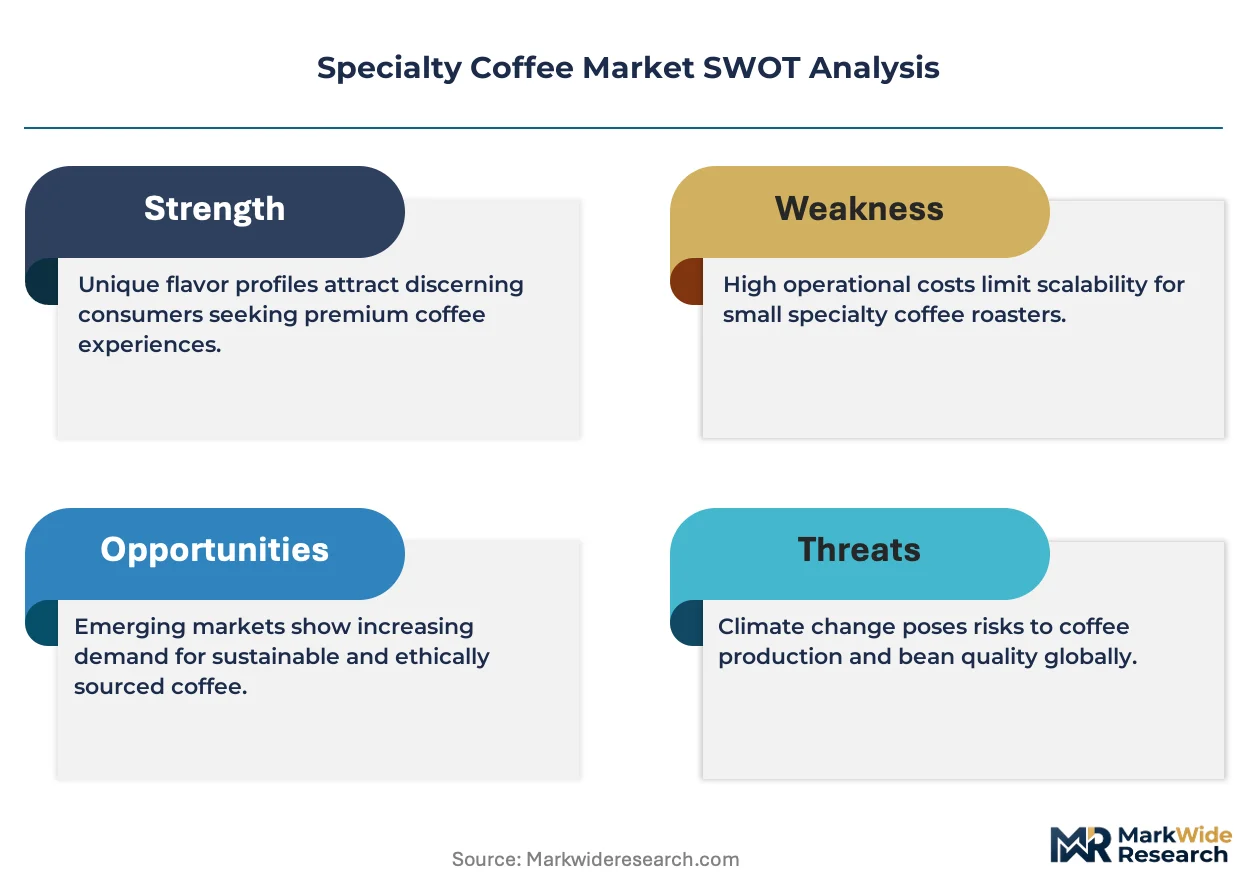
The Specialty Coffee Market is being fundamentally restructured by EU Green Deal deforestation regulations, which mandate granular traceability from farm to cup and are forcing wholesale supply chain reconfiguration ahead of enforcement deadlines.
Growth Catalysts
- EUDR Traceability Mandates:Roasters investing in blockchain-verified chain-of-custody systems capture preferential shelf placement in European retail, accelerating certification adoption across Latin American cooperatives.
- Ready-to-Drink Cold Brew Expansion:Convenience-seeking urban consumers in South Korea and Japan drive double-digit volume growth in nitrogen-infused and flash-brewed formats through automated retail channels.
- Experiential Café Formats:Third-wave coffee shops in São Paulo, Melbourne, and Copenhagen integrate on-site roasting theaters and origin storytelling to command sustained price premiums over commodity alternatives.
Market Restraints
- Arabica Price Volatility:Frost damage in Brazilian Cerrado and Minas Gerais regions creates input cost instability that compresses roaster margins during deficit cycles.
- Origin Concentration Risk:Overreliance on washed Arabica from Colombia's Nariño and Huila departments exposes buyers to climate-induced yield variability and quality inconsistency.
- REACH Chemical Compliance:European packaging and processing equipment manufacturers face reformulation costs for inks, adhesives, and machinery lubricants that restrict supplier pool flexibility.
Strategic Opportunities
- Underpenetrated Indonesian Archipelago:Toraja and Gayo highland estates offer untapped single-origin potential as EU buyers diversify beyond established Colombian and Ethiopian sources.
- Carbon-Neutral Certification Tailwinds:Science Based Targets initiative alignment and EU Carbon Border Adjustment Mechanism preparation create first-mover advantage for roasters with verified Scope 3 accounting.
- Direct-to-Consumer Subscription Platforms:Curated micro-lot releases and roast-to-order fulfillment bypass traditional foodservice intermediaries, capturing lifetime value through recurring revenue models.
Industry Challenges
- Q-Grader Talent Scarcity:Certified cupping professionals capable of consistent 80-plus-point scoring remain concentrated in Portland, Melbourne, and Oslo, constraining quality control scale-up in emerging origins.
- Multi-Certification Audit Burden:Simultaneous pursuit of Rainforest Alliance, Fairtrade, and organic credentials creates documentation complexity and timeline extension for smallholder cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Coffee Market |
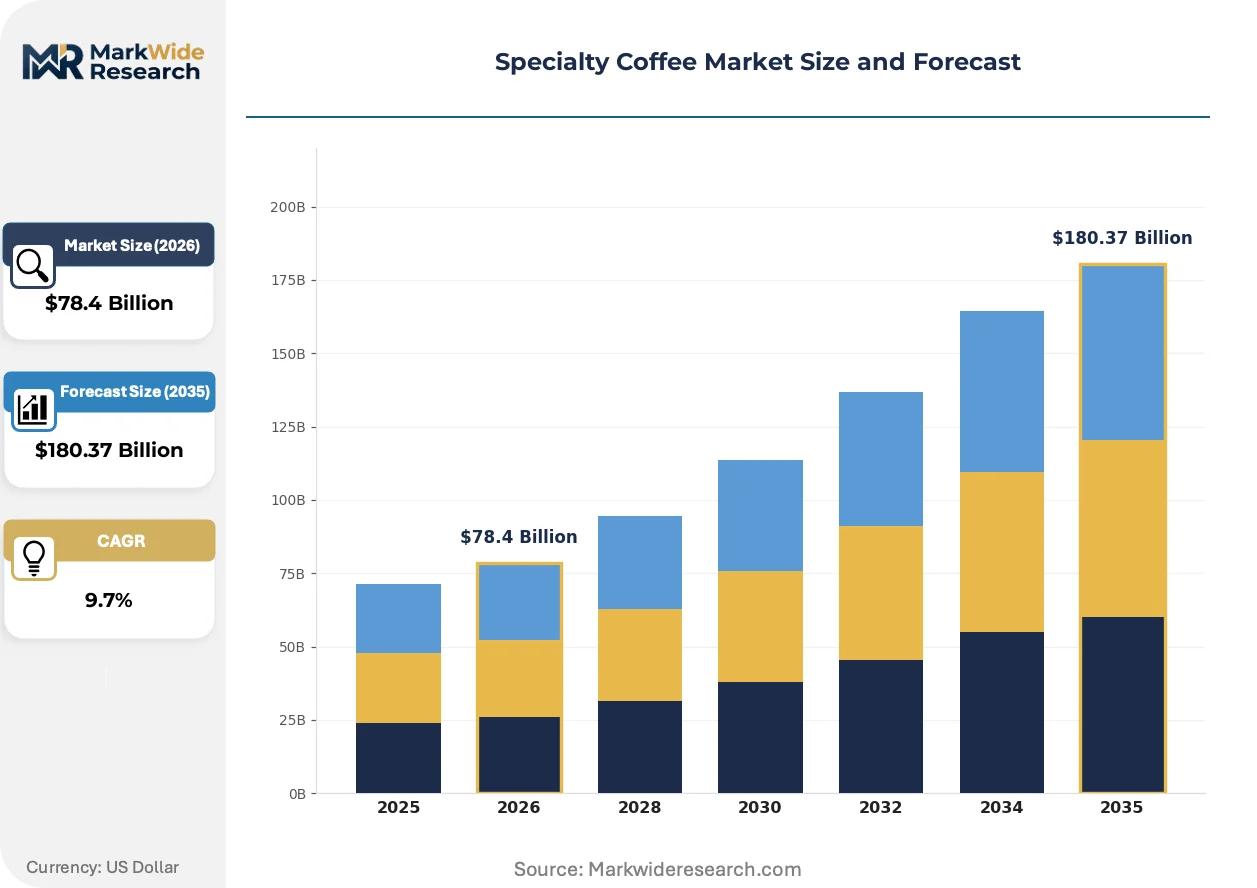
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $180.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Origin, Blends, Cold Brew, Nitro Brewing Method: Espresso, Pour Over, French Press, AeroPress Flavor Profile: Citrus, Berry, Chocolate, Nutty Customer Type: Cafés, Retailers, Online Consumers, Food Service |
| Companies Covered | Luckin Coffee, illycaffè, Starbucks, Dunkin', Tim Hortons, Nestlé, Lavazza, Olam Food Ingredients, JDE Peet's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Coffee Market Strategic Shifts & Innovations
Sensor-integrated roasting automation and regenerative agriculture verification are compressing quality variance while expanding provenance transparency. These developments are redrawing competitive boundaries between artisanal micro-roasters and scaled specialty operators.
AI-driven roast profiling systems are unifying gas-fired drum and electric fluid-bed technologies under predictive algorithms that adjust heat application in real time. Medium-scale roasters in Portland and Berlin adopt these platforms to replicate competition-winning profiles across multiple production sites. The technology is unifying previously fragmented quality control standards, enabling regional chains to compete with flagship single-location operations on sensory consistency.
EU Green Deal deforestation regulations now require geolocation coordinates for every hectare supplying European-bound coffee, effective across all member states. Roasters must demonstrate farm-level polygon mapping and risk assessment documentation or face import prohibition. Small importers in Hamburg and Rotterdam accelerate compliance hiring, while larger traders absorb satellite monitoring costs through existing sustainability departments.
Subscription-based procurement is displacing spot-market purchasing among North American and Australian micro-roasters, locking in six-month forward commitments with specific estates. This model transfers price risk to roasters while guaranteeing origin partners harvest financing and volume certainty. Kenyan and Rwandan washing stations report strongest contract uptake, replacing traditional auction dependency with direct trade relationships.
Specialty Coffee Market Segmentation
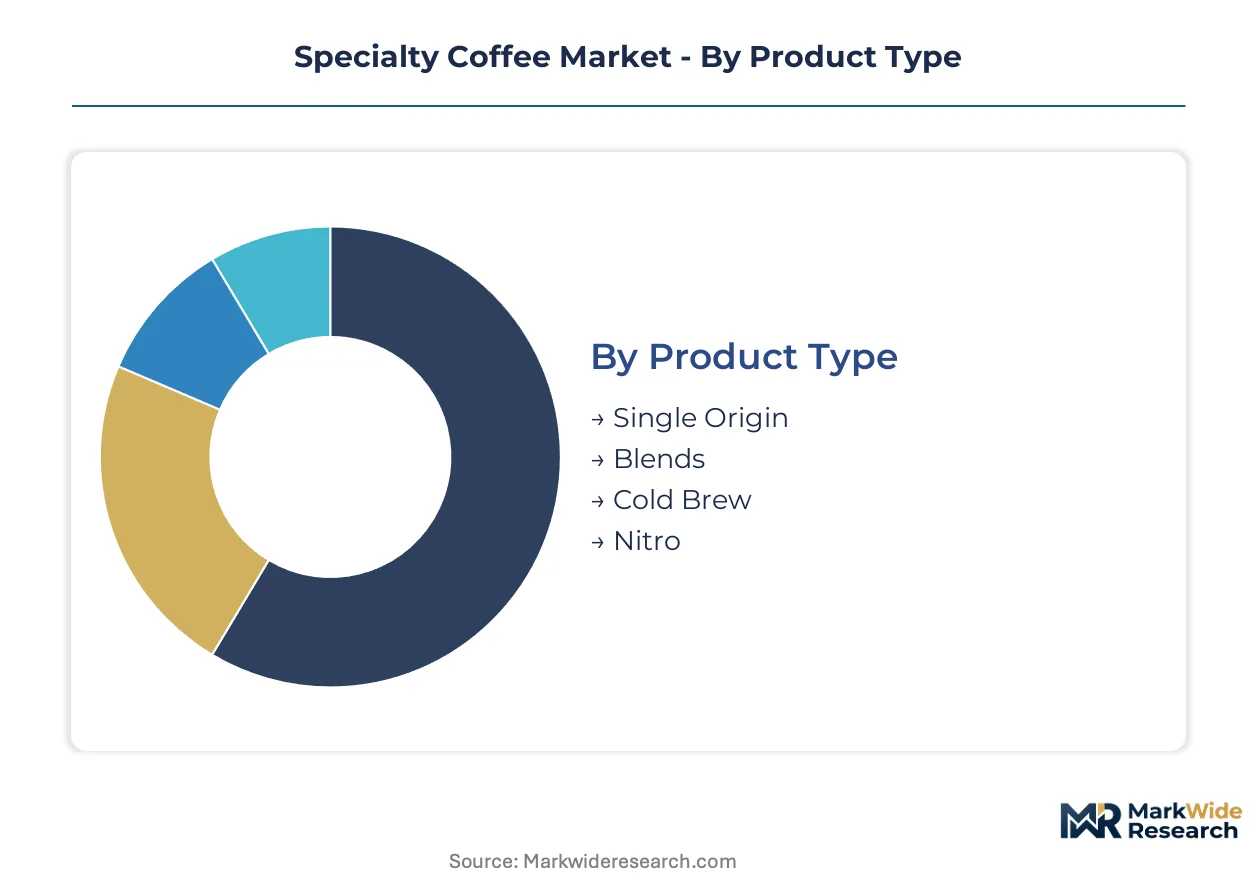
Specialty coffee segmentation reflects divergent certification burdens across consumption contexts. Product origin documentation, brewing equipment safety standards, and channel-specific labeling requirements create distinct compliance cost structures for roasters and retailers.
Product Type:
Single Origin offerings carry the heaviest traceability documentation load under EU Green Deal and EUDR mandates, while Blends and ready-to-drink formats face modified audit pathways.
- Single Origin:Unblended beans from identifiable estates or cooperatives require farm-level polygon mapping and risk assessment documentation for European import. Demand concentrates in Copenhagen, Melbourne, and Portland roasting operations where provenance storytelling commands sustained price premiums over commodity alternatives.
- Blends:Multi-origin Arabica combinations processed through rigorous cupping protocols to achieve consistent sensory profiles. Roasters in Milan and Seattle leverage blending expertise to buffer against origin-specific frost damage and climate-induced yield variability.
- Cold Brew:Extended steeping extraction producing low-acidity concentrate for ready-to-drink distribution. South Korean and Japanese convenience retail channels drive volume expansion.
- Nitro:Nitrogen-infused cold brew delivered through pressurized tap systems. Third-wave cafés in São Paulo and Brooklyn deploy for experiential differentiation.
Leading the category by volume: Blends. Growing fastest: Cold Brew.
Brewing Method:
Equipment safety certifications from FDA and EU machinery directives segment commercial adoption by operational scale and venue type.
- Espresso:High-pressure extraction through 9-bar pump systems producing concentrated shots with crema formation. Italian and Australian café chains standardize on multi-group machines for throughput efficiency.
- Pour Over:Gravity-fed manual brewing through ceramic or glass vessels enabling precise temperature control. Japanese kissaten culture and Nordic coffee bars drive specialist equipment demand.
- French Press:Immersion brewing through metal mesh filtration producing full-bodied extraction. Home consumption in France and North America sustains steady replacement cycle demand.
- AeroPress:Air-pressure manual extraction system popularized through competition circuits. Portable format captures outdoor recreation and travel segments.
Highest certification compliance cost: Espresso. Steepest expansion trajectory: Pour Over.
Flavor Profile:
Terroir expression and processing method determine acidity and aromatic compound development, with organic certification most prevalent in fruit-forward categories.
- Citrus:High-acidity profiles typical of Kenyan and Ethiopian washed processing. Third-wave roasting competitions favor for sensory distinctiveness.
- Berry:Natural and honey processing methods in Yirgacheffe and Sidamo develop fermented fruit notes. Direct-trade subscription platforms feature prominently.
- Chocolate:Low-acidity Brazilian and Sumatran beans with nutty undertones. Blending applications and espresso roasting dominate commercial uptake.
- Nutty:Medium-roast profiles from Colombian and Guatemalan highlands. Food service and institutional procurement favor for crowd-pleasing consistency.
Deepest certification penetration: Berry. Broadest volume base: Chocolate.
Customer Type:
Channel-specific labeling requirements from FDA food safety standards and EU organic protocols create segmented compliance investment thresholds.
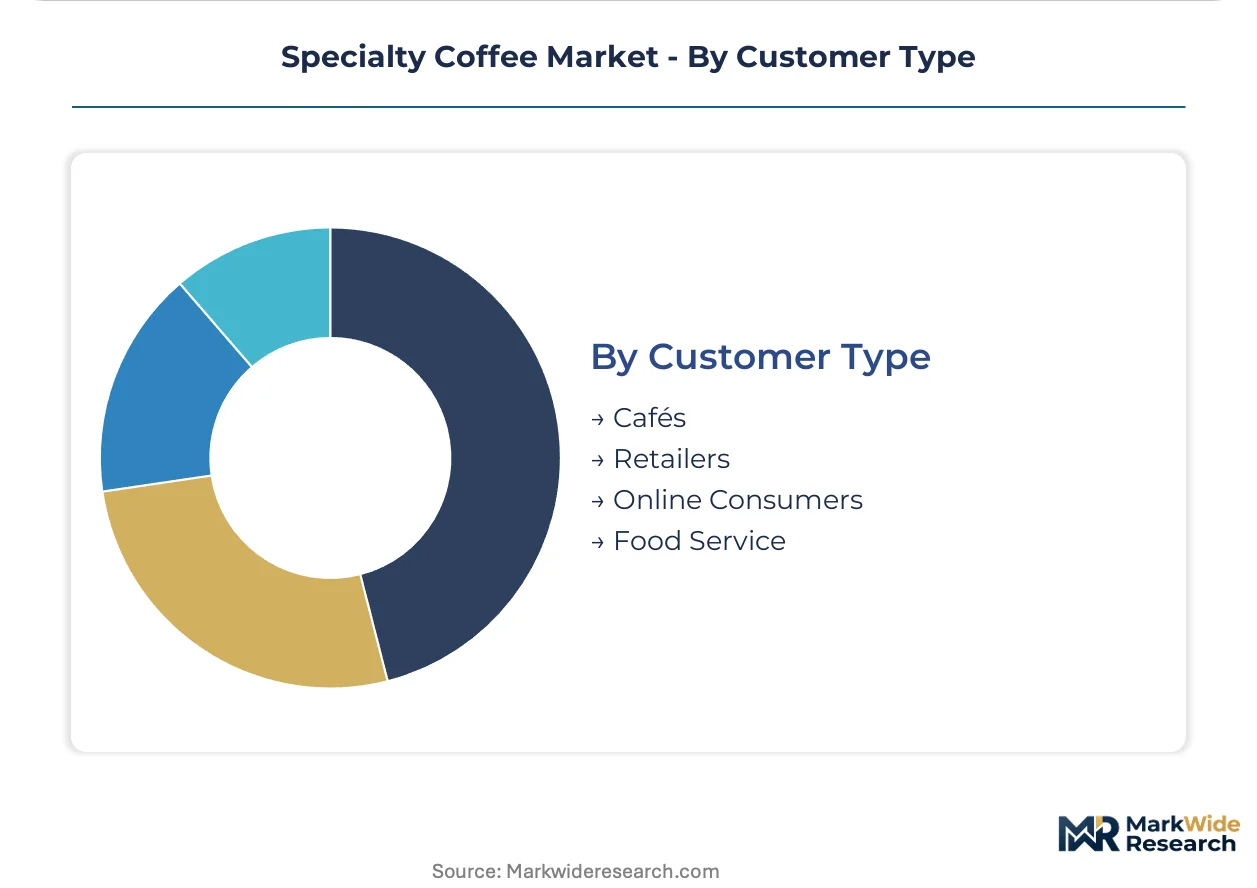
- Cafés:Out-of-home consumption venues requiring batch brew consistency and barista training infrastructure. Copenhagen, Melbourne, and São Paulo third-wave operators lead origin transparency investments.
- Retailers:Grocery and specialty store shelf placement demanding packaged goods labeling compliance. EUDR traceability mandates reshape European procurement specifications.
- Online Consumers:Subscription and direct-to-origin platform users. North American and Australian micro-roasters lock in six-month forward commitments with specific estates.
- Food Service:Institutional and hospitality volume channels. Hotels and corporate catering prioritize supply security over provenance documentation.
Widest margin pool: Online Consumers. Largest throughput volume: Food Service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Dubai and Jebel Ali concentrate roasting infrastructure for Middle East re-export. These zones offer zero customs duties and simplified licensing that attracts multinational operators seeking regional hub positioning.
United States
Specialty café density in Seattle and Portland sustains micro-roaster proliferation and direct-trade subscription growth. FDA food safety standards and USDA organic certification govern import protocols. Brooklyn and Los Angeles roasting clusters compete through experiential retail formats and nitrogen-infused cold brew tap systems.
Brazil
Frost vulnerability in Cerrado and Minas Gerais drives roaster investment in climate-resilient varietal development. ANVISA regulates packaged food labeling for domestic retail distribution. São Paulo's third-wave café corridor integrates on-site roasting theaters that command sustained price premiums through origin storytelling.
Germany
Hamburg and Bremen port infrastructure anchors European green coffee import and storage capacity. EU Green Deal deforestation regulations and REACH chemical compliance reshape procurement documentation requirements. Berlin's specialty roasting district absorbs compliance costs through scale advantages in multi-origin blending operations.
Japan
Kissaten culture and convenience retail channels drive ready-to-drink cold brew volume expansion in Tokyo and Osaka. METI oversees food labeling and import safety standards for roasted products. Kyoto's manual brewing equipment manufacturers supply pour-over specialists across Nordic and Australian markets.
South Korea
Automated retail and convenience store density accelerates nitrogen-infused cold brew adoption in Seoul and Busan. MFDS regulates food contact materials and processing equipment safety for café operators. Gangnam district café clusters compete through sensory differentiation and single-origin reserve programs.
Specialty Coffee Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with out-of-home café operators commanding premium positioning and commodity traders controlling volume throughput. The market structures around three tiers: integrated café-roaster chains with direct estate relationships, independent micro-roasters competing on traceability storytelling, and agricultural conglomerates with multi-origin sourcing scale. Consolidation pressures concentrate among mid-scale roasting operations facing simultaneous EUDR compliance investments and Arabica price volatility. Strategic moves center on backward integration into origin washing stations and forward integration into subscription direct-to-consumer platforms.
Within the integrated café-roaster tier, Starbucks anchors multinational estate network control across Latin American origins. illycaffè occupies a position exemplifying rigorous Arabica blending protocols and single-origin reserve positioning. JDE Peet's represents scale-driven roasting infrastructure concentration across European and Asian distribution hubs. These three operators illustrate divergent competitive vectors: direct trade relationship depth, sensory consistency through blending expertise, and geographic footprint optimization for logistics efficiency.
| Leading Market Players |
|---|
| Luckin Coffee |
| illycaffè |
| Starbucks |
| Dunkin' |
| Tim Hortons |
| Nestlé |
| Lavazza |
| Olam Food Ingredients |
| JDE Peet's |
| Others |
Cost & Logistics Intelligence
Q-Grader talent concentration in Portland, Melbourne, and Oslo creates labor-cost differentials that widen pricing-tier spreads between artisanal micro-roasters and scaled specialty operators.
Pricing Analysis
Short-lead-time premiums for micro-lot releases command sustained markups over spot-market Arabica, while forward-contract discounts reward roasters absorbing six-month volume commitments. Three-tier pricing structure across premium single-origin, standard multi-origin blends, and economy commercial-grade segments reflects certification-grade differentiation. Cost compression in the economy tier intensifies as Brazilian frost cycles squeeze input availability. Food service buyers exhibit highest price sensitivity due to volume procurement mandates, whereas direct-to-consumer subscription segments tolerate premium positioning.
Supply Chain Analysis
EU Green Deal domestic-content traceability mandates reshape sourcing by requiring farm-level polygon documentation for European-bound shipments. Geographic supply concentration centers on Brazil, Colombia, and Vietnam as origin priorities, with Ethiopian and Indonesian estates gaining share as diversification hedges. The chain draws from washed Arabica, natural-process beans, and honey-process micro-lots as core inputs. Single-origin vulnerability to climate-induced yield variability represents the dominant structural risk. Distribution runs through Hamburg and Bremen port infrastructure for European re-export, with Dubai Free Trade Zones serving Middle East hub consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty coffee market reads as a cost-of-compliance story where EU Green Deal deforestation regulations erect barrier-to-entry moats favoring roasters with pre-existing sustainability departments and satellite monitoring capabilities.
For Market Incumbents: Anticipate consolidation pressure among mid-scale roasting operations by absorbing EUDR compliance costs through scale advantages in multi-origin blending. Backward integration into Kenyan and Rwandan washing stations secures volume certainty against auction volatility. Channel control through direct-to-consumer subscription platforms captures lifetime value while transferring price risk from origin partners. For New Entrants and Emerging Players: Launch via curated micro-lot subscription models targeting underpenetrated Indonesian Toraja and Gayo highland estates. The ready-to-drink cold brew segment in South Korean automated retail channels offers the most penetrable white-space opportunity. Carbon-neutral certification alignment with Science Based Targets initiative creates differentiated positioning against established blending houses. For Investors and Strategic Acquirers: The window for entry favors roasting operations with verified Scope 3 accounting and existing blockchain-verified chain-of-custody systems. Long-term viability hinges on first-mover positioning ahead of EU Carbon Border Adjustment Mechanism implementation. Watch Arabica price volatility cycles as the inflection indicator for distressed asset availability among non-compliant mid-tier operators.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Verified Traceability Implementation | EU Green Deal compliance secures preferential shelf placement in Hamburg and Rotterdam retail channels. |
| Backward Integration into Origin Washing Stations | Kenyan and Rwandan direct-trade relationships replace auction dependency with harvest financing certainty. |
| Subscription Platform Direct-to-Consumer Launch | Roast-to-order fulfillment bypasses foodservice intermediaries and locks in recurring revenue models. |
| Carbon-Neutral Certification Program | Science Based Targets alignment creates first-mover positioning ahead of EU Carbon Border Adjustment Mechanism. |
| AI-Driven Roast Profiling Scale-Up | Predictive algorithms unify gas-fired drum and electric fluid-bed technologies across Portland and Berlin production sites. |
Research Approach
Trade databases, customs records, and specialty coffee association cupping score archives formed the secondary backbone, cross-referenced with primary interviews conducted with green coffee importers, roasting operations managers, Q-Grader certification bodies, and sustainability compliance officers. Bottom-up volume modeling triangulated against top-down market sizing from consumption channel analysis.
Historical trendline analysis of Arabica price cycles, certification adoption rates, and cold brew volume expansion informed projection parameters across the analysis window. Segmentation dimensions modeled include product origin type, brewing equipment category, flavor profile tier, and customer channel. CAGRs derived from weighted average of supply-side capacity additions and demand-side consumption shifts, with frost damage frequency and EUDR enforcement timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path for sensor-integrated roasting automation; alternative pathways for AI-driven profile replication would alter the outlook for regional chain competitiveness. Forecasts reflect documented assumptions around climate resilience varietal development and cooperative certification audit timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Espresso Tamper Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
US Instant Coffee Market
Coffee
Brazil Ready-To-Drink (RTD) Coffee Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Butter Coffee Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
Ethiopia Coffee Market
Coffee
Mushroom Coffee Market
Coffee
US Coffee Roaster Market
Coffee
Global Coffee Machine Market
Coffee
Nitrogenated Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Caffeine Market
Coffee
Tea and Coffee Bags Market