
 Space Debris Monitoring and Removal Market | 2026-2036
Space Debris Monitoring and Removal Market Size, Share, and Industry Trends Forecast 2026-2036
Space Debris Monitoring and Removal Market Analysis
Defense organization procurement is broadening the commercial addressable base for debris mitigation services. Astroscale Holdings anchors the active debris removal segment with in-orbit servicing demonstrations. Northrop Grumman Corporation sustains technology leadership through its Mission Extension Vehicle program. Lockheed Martin Corporation leverages its space surveillance heritage to compete in tracking and cataloging contracts.
Space debris monitoring and removal encompasses the detection, tracking, and active elimination of defunct satellites, spent rocket bodies, and fragmentation debris orbiting Earth, utilizing radar arrays, optical telescopes, laser ranging systems, and capture spacecraft with robotic manipulators or adhesive mechanisms. The primary purpose is preserving operational orbital regimes by preventing catastrophic collisions that threaten functional satellites and crewed missions. Laser Systems and Spacecraft technologies dominate current capability investments, while Net Systems represent an emerging structural growth pocket where margin pools remain thin due to limited flight heritage. Removal Services command premium pricing relative to Tracking Services because active de-orbiting missions require bespoke engineering and launch integration.
FCC orbital debris rules, NASA technical standards, and ISO 24113 space systems debris mitigation requirements collectively shape product specifications and market access for debris solution providers. The FCC now mandates disclosure of collision probability, maneuverability, and end-of-life disposal plans as conditions for U.S. spectrum licensing, directly elevating demand for third-party tracking and removal services. Stakeholders must monitor how rapidly evolving national licensing regimes fragment compliance requirements across major spacefaring jurisdictions.
Market Dynamics
Defense procurement of collision avoidance services is restructuring demand composition, pulling commercial debris monitoring providers into classified contracting frameworks and reshaping qualification requirements across the supplier base.
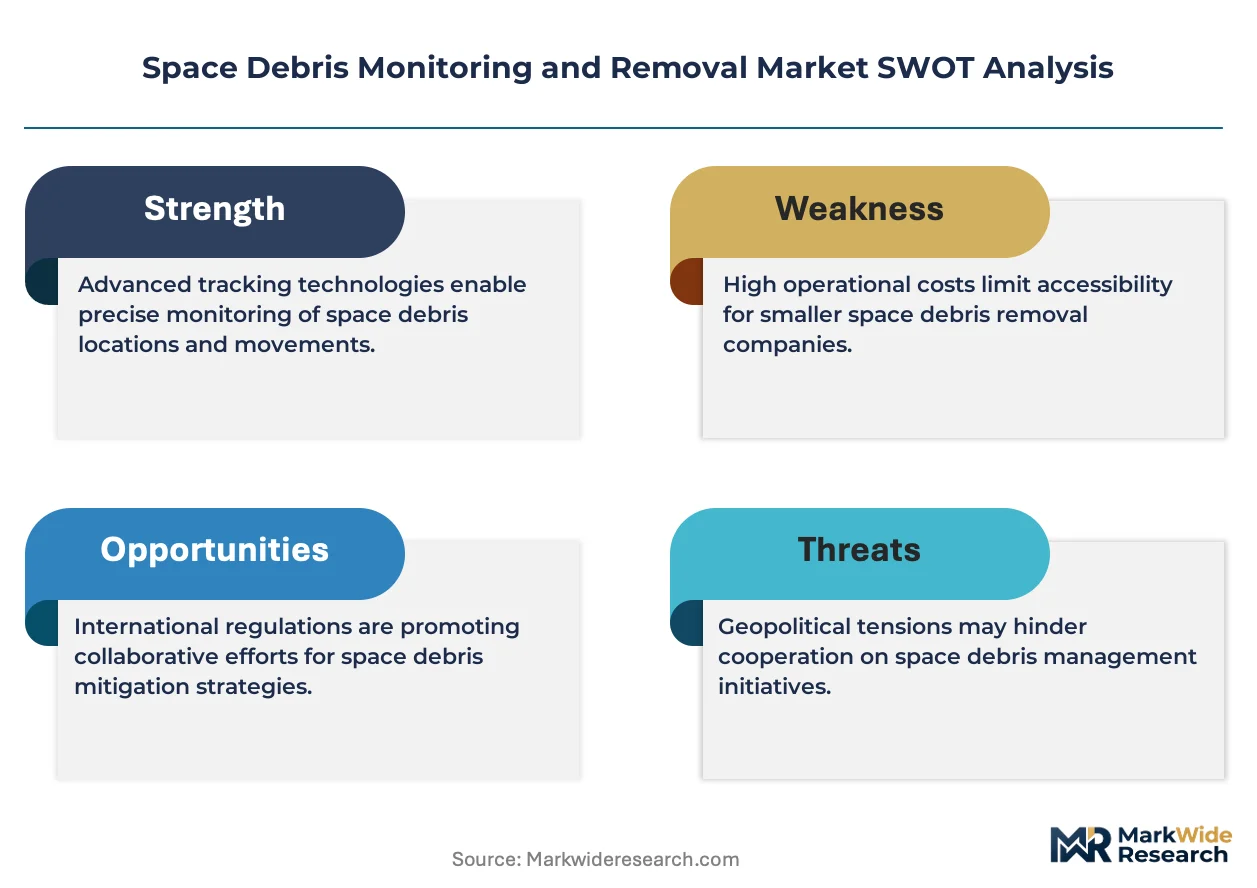
Growth Catalysts
- FCC Orbital Debris Rules:Mandated disclosure of collision probability and end-of-life disposal plans for U.S. spectrum licensing elevates third-party tracking demand.
- Laser Ranging Systems:Optical ground stations in Australia and Chile deliver centimeter-precision tracking for high-value geostationary assets.
- Space Force Contracting:Dedicated procurement streams for space domain awareness expand the addressable base for debris cataloging services.
Market Restraints
- Launch Cost Volatility:Active debris removal missions remain hostage to Falcon Heavy and Ariane 6 pricing swings, compressing mission margins.
- Flight Heritage Scarcity:Net capture and harpoon systems lack operational validation, freezing insurance underwriting for novel removal architectures.
- Jurisdictional Fragmentation:Divergent national licensing regimes between the United States, France, and Japan multiply compliance overhead for cross-border service providers.
Strategic Opportunities
- India's Lagrange Point Missions:ISRO's expanding deep-space activity creates demand for debris monitoring at L1 and L2 halo orbits.
- ISO 24113 Certification Services:Third-party verification of debris mitigation plans opens recurring revenue streams for engineering consultancies.
- Robotic Servicing Convergence:Integration of manipulator arms with refueling infrastructure enables multi-mission revenue per servicer launch.
Industry Challenges
- Orbital Mechanics Talent Gap:Shortage of astrodynamicists capable of conjunction analysis at sub-meter precision limits scaling of tracking operations.
- End-of-Life Certification Timelines:NASA technical standard 8719.14 compliance documentation extends satellite qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Debris Monitoring and Removal Market |
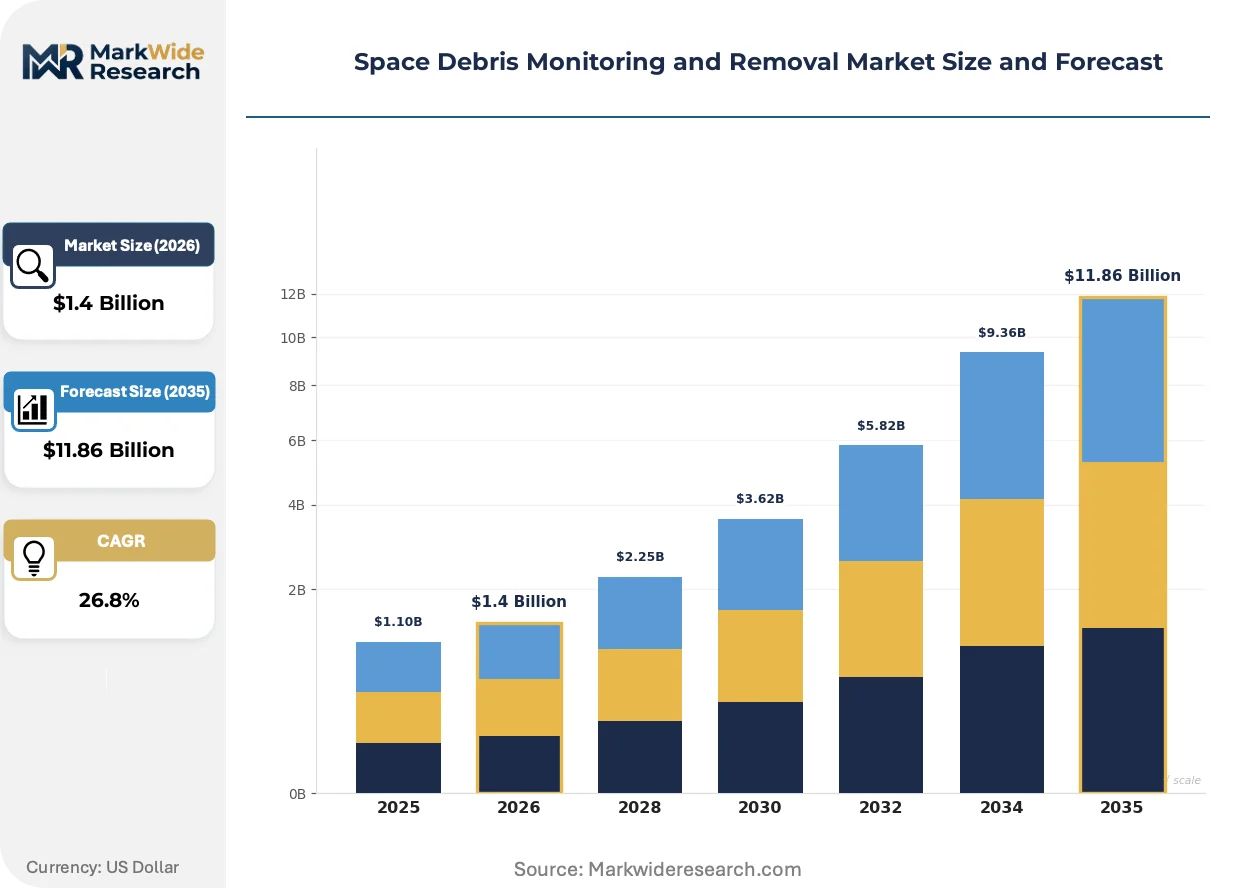
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $11.86 Billion |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Laser Systems, Electrodynamic Tethers, Spacecraft, Net Systems Service Type: Tracking Services, Removal Services, Collision Avoidance, Post-Mission Disposal Application: Satellite Maintenance, Space Mission Support, Research and Development, Safety Assessments End User: Government Agencies, Private Sector Firms, Research Institutions, Defense Organizations |
| Companies Covered | Astroscale Holdings, ClearSpace, Northrop Grumman Corporation, Lockheed Martin Corporation, Airbus SAS, LeoLabs, SpaceX, Electro Optic Systems, Surrey Satellite Technology Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Debris Monitoring and Removal Market Emerging Trajectories
Active capture technologies are displacing passive tracking as the capability differentiator, with servicer spacecraft architectures commanding R&D investment priority over ground-based sensor expansion.
Laser-based debris illumination and ranging is expanding into cislunar trajectory monitoring, with NASA's Artemis support requirements driving adoption. The U.S. Space Force is funding optical terminal upgrades at Maui and Socorro observatories. This capability extension is compressing the competitive window for radar-only tracking providers.
The European Union's proposed Space Traffic Management framework is mandating standardized conjunction data message formats. Satellite operators in France, Germany, and Italy must now integrate certified collision probability assessments into flight software. Small satellite constellations face the steepest adaptation costs under these interoperability requirements.
Defense agencies are consolidating debris monitoring contracts under multi-year space domain awareness agreements. Traditional per-pass pricing for radar tracking is yielding to subscription-based catalog access in the United States and United Kingdom. This shift is most visible in Space Force procurement, where incumbent sensor networks face displacement by commercial data fusion platforms.
Space Debris Monitoring and Removal Market Segmentation
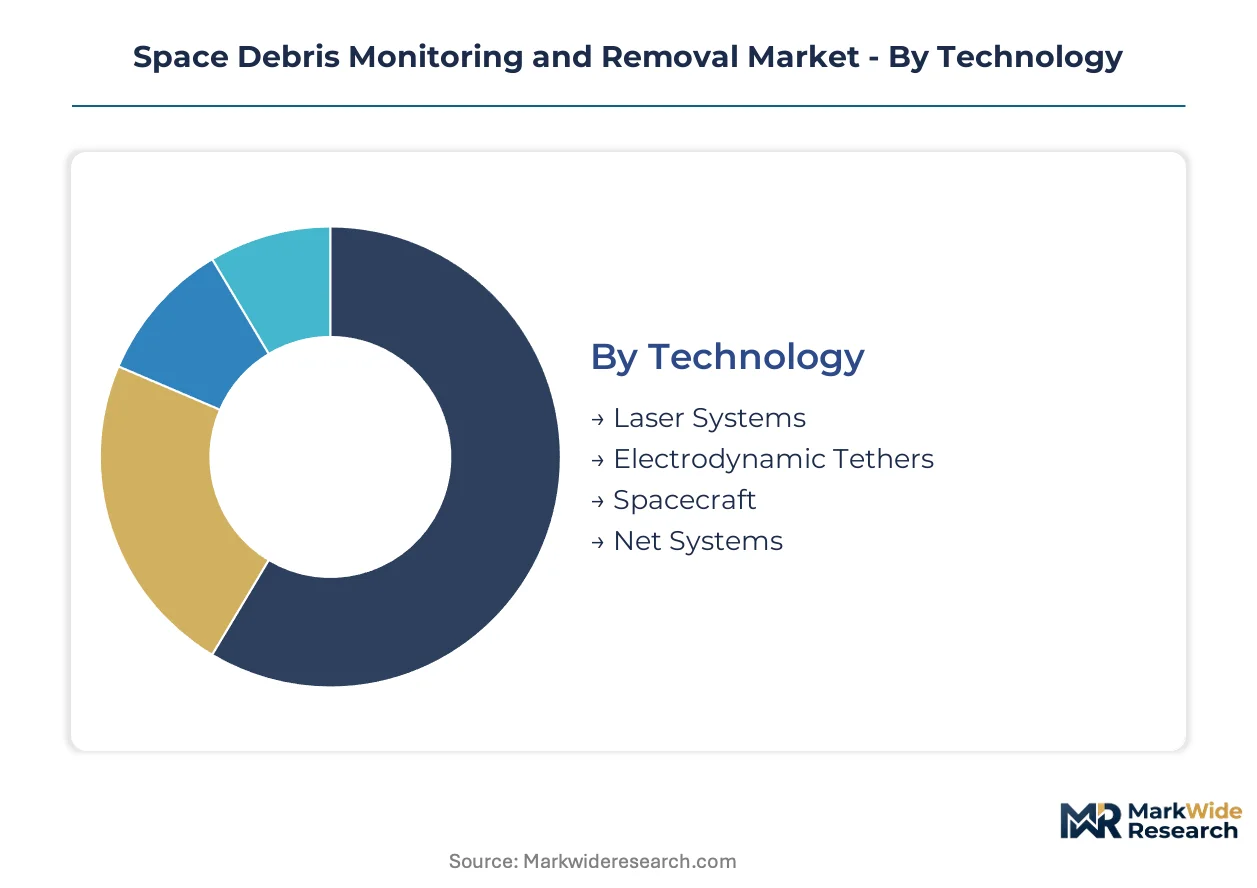
Technology selection in space debris mitigation determines capital intensity, mission cadence, and regulatory compliance pathways. Service type segmentation reveals where pricing power concentrates versus where commodification pressures operate. Application and end-user splits expose which customer relationships sustain multi-year contracting versus transactional procurement.
Technology:
Laser Systems and Spacecraft architectures command the majority of current capability investments, while emerging capture mechanisms reshape competitive positioning.
- Laser Systems:Ground-based optical stations emit pulsed laser energy to illuminate debris trajectories with centimeter-precision ranging. Demand concentrates in Australia and Chile for geostationary asset protection, driven by Space Force funding for Maui and Socorro observatory upgrades.
- Spacecraft:Purpose-built servicer platforms execute proximity operations, rendezvous, and controlled de-orbiting using chemical or electric propulsion. NASA and Space Force contracting activity in the United States anchors procurement, with mission margins compressed by Falcon Heavy pricing volatility.
- Electrodynamic Tethers:Conductive cable systems generate Lorentz force against Earth's magnetic field for propellantless de-orbiting.
- Net Systems:Deployable mesh capture mechanisms target non-cooperative debris without standardized grapple fixtures.
Mature deployment sits with Laser Systems. Newer deployment is concentrated in Net Systems.
Service Type:
Revenue models diverge sharply between subscription-based catalog access and bespoke mission engineering with launch integration.
- Removal Services:Active de-orbiting missions require custom spacecraft design, regulatory licensing, and insured launch procurement. Premium pricing reflects flight heritage scarcity and mission-specific risk underwriting.
- Tracking Services:Radar and optical data feeds deliver conjunction warnings and ephemeris updates through recurring subscription contracts. Space Force procurement is consolidating demand under multi-year space domain awareness agreements.
- Collision Avoidance:Maneuver recommendation services integrate tracking data with satellite operator flight dynamics.
- Post-Mission Disposal:End-of-life compliance verification and disposal mission management address FCC orbital debris rule mandates.
Revenue concentration favors Removal Services. Volume expansion is climbing fastest in Tracking Services.
Application:
Operational imperatives versus experimental funding sources determine contract duration and payment security across application segments.
- Satellite Maintenance:Debris clearance to preserve operational orbital slots for commercial and government constellations. United States operators face steepest adaptation costs under FCC disclosure mandates for collision probability and maneuverability.
- Space Mission Support:Crewed mission trajectory protection and rendezvous corridor clearance for Artemis and ISS operations. NASA technical standard 8719.14 compliance documentation extends qualification cycles.
- Research and Development:Technology demonstration missions validating capture mechanisms and sensor performance.
- Safety Assessments:Third-party verification of debris mitigation plans against ISO 24113 requirements.
Contract maturity sits with Space Mission Support. Steepest expansion trajectory is in Safety Assessments.
End User:
Procurement frameworks and security classification requirements segment addressable markets by customer type.
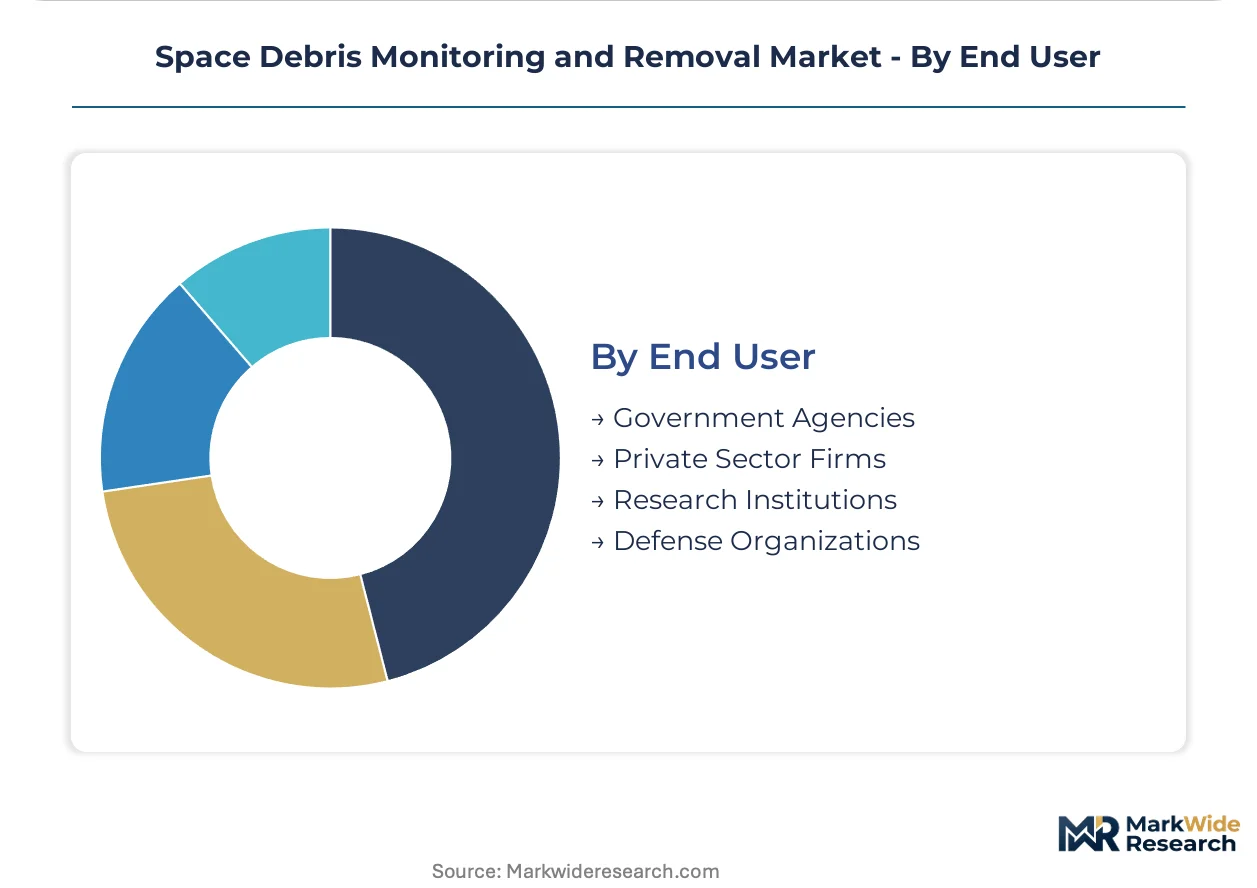
- Government Agencies:Civil space organizations including NASA procure tracking and removal services through technical standards compliance. FCC spectrum licensing mandates directly elevate third-party service demand.
- Defense Organizations:Classified space domain awareness contracts pull commercial providers into restricted frameworks. United States Space Force dedicated procurement streams expand the addressable base.
- Private Sector Firms:Commercial satellite operators purchase collision avoidance subscriptions and end-of-life disposal planning.
- Research Institutions:Universities and national laboratories access tracking data for orbital mechanics research and talent development.
Established procurement sits with Government Agencies. Emerging demand is concentrating in Defense Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Space Force procurement corridors in Colorado and California anchor the highest concentration of debris monitoring contracts. FCC licensing mandates pull commercial operators into compliance frameworks. Specialized clusters in Australia and Chile support laser-ranging infrastructure for geostationary tracking.
United States
Space Force dedicated procurement streams and NASA technical standards compliance dominate demand composition. FCC orbital debris rules mandate collision probability disclosure for spectrum licensing. Colorado Springs and Los Angeles aerospace clusters concentrate mission engineering talent for active removal spacecraft development.
United Kingdom
UK Space Agency funding for debris tracking networks and Ministry of Defence space domain awareness contracts expand service demand. The country's national space regulator enforces alignment with ISO 24113 debris mitigation standards. Harwell Science and Innovation Campus hosts optical sensor development for conjunction assessment services.
Japan
JAXA technology demonstration missions and METI support for commercial debris removal ventures stimulate market formation. The country's national space agency coordinates with ISO standards for end-of-life disposal verification. Tsukuba Space Center anchors R&D concentration for electrodynamic tether systems.
Australia
Space Force funding for Maui and Socorro-equivalent southern hemisphere observatories drives laser-ranging station deployment. The country's national space agency manages debris monitoring coordination with allied defense organizations. Mount Stromlo Observatory near Canberra concentrates optical ground station engineering expertise.
Germany
European Space Agency procurement for active debris removal missions and national space program technology investments shape demand. The country's national aerospace regulator enforces EU Space Traffic Management framework alignment. Bremen and Munich industrial clusters concentrate spacecraft bus manufacturing for servicer platforms.
Space Debris Monitoring and Removal Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated defense primes commanding classified contracts while venture-backed newcomers capture technology demonstration awards. The vendor base concentrates around three strategic archetypes: legacy aerospace conglomerates with space surveillance heritage, pure-play debris removal ventures with in-orbit servicing focus, and sensor network operators with data fusion platforms. Competitive moves center on multi-year space domain awareness agreements and cross-border regulatory certification partnerships.
Among defense-heritage integrators, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify the mission extension and tracking catalog archetypes respectively. Astroscale Holdings occupies a position representing the pure-play active removal segment with demonstrated in-orbit servicing capabilities. These three anchors illustrate how procurement consolidation around Space Force and NASA contracting favors entities with established qualification pathways.
| Leading Market Players |
|---|
| Astroscale Holdings |
| ClearSpace |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Airbus SAS |
| LeoLabs |
| SpaceX |
| Electro Optic Systems |
| Surrey Satellite Technology Ltd |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed defense contractors and venture-funded pure-plays split supply ownership across the debris mitigation value chain, with Space Force procurement concentration in Colorado and California feeding pricing discipline through multi-year catalog access agreements rather than spot transactions.
Pricing Analysis
Premium pricing for expedited collision avoidance maneuver recommendations compresses margins on standard ephemeris subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments buyers by mission criticality and data latency requirements. Pricing pressure stems from Falcon Heavy and Ariane 6 launch cost volatility, which squeezes active removal mission economics. Small satellite constellation operators exhibit highest price sensitivity, while classified defense contracts sustain least sensitivity due to mission assurance mandates.
Supply Chain Analysis
Dual-sourcing requirements from NASA and Space Force mandate multi-supplier qualification for optical sensor components and flight-proven propulsion systems. Manufacturing concentrates in the United States, Germany, and Japan for precision optomechanical assemblies and electric propulsion thrusters. Supply chains draw from specialized beryllium mirror substrates, radiation-hardened electronics, and high-purity propellant formulations. Single-source vulnerability persists in sub-meter precision laser ranging detectors. Distribution runs through prime contractor integration facilities in Los Angeles and Bremen before government acceptance testing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into launch service provision and in-orbit refueling infrastructure is accelerating as players seek to capture margin pools currently leaking to external providers.
For Market Incumbents: Extend flight heritage accumulation through rapid-cycle technology demonstration missions ahead of ISO 24113 certification deadlines. Lock in multi-year space domain awareness contracts before commercial data fusion platforms displace incumbent sensor networks. Pursue backward integration into optical terminal manufacturing to reduce dependency on Maui and Socorro observatory upgrade schedules.
For New Entrants and Emerging Players: Enter via India's Lagrange point mission support services, where ISRO procurement lacks established vendor relationships and collision probability assessment tooling remains underdeveloped. Target Australia's southern hemisphere laser-ranging infrastructure gap, where Space Force funding creates immediate demand without entrenched competition. Lead with ISO 24113 certification consulting to build regulatory credibility before hardware investment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electrodynamic tether specialists in Japan, where METI funding volatility and JAXA mission delays have compressed valuations below replacement cost. Five-to-ten year viability hinges on successful demonstration of propellantless de-orbiting at scale. Monitor Space Force procurement consolidation announcements as inflection indicator for commercial tracking provider displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Active Debris Removal Mission Demonstration | Flight heritage accumulation unlocks insurance underwriting and NASA technical standard compliance pathways. |
| Optical Sensor Network Expansion | Maui and Socorro upgrades compress radar-only provider competitive windows in geostationary tracking. |
| ISO 24113 Certification Service Launch | Third-party verification creates recurring revenue streams from FCC disclosure mandate compliance. |
| Robotic Servicing Convergence | Manipulator arm integration with refueling infrastructure enables multi-mission revenue per servicer launch. |
| Cross-Border Regulatory Partnership | Joint FCC-UK Space Agency certification reduces compliance overhead for transatlantic service providers. |
Methodological Framework
NASA technical standard filings, FCC spectrum licensing databases, and Space Force procurement records formed the secondary backbone, supplemented by customs data on optical component trade flows and ESA active debris removal mission documentation. Primary interviews with satellite operator flight dynamics officers, defense procurement program managers, space domain awareness sensor network engineers, and debris mitigation compliance consultants validated demand assumptions. Bottom-up service provider revenue estimates triangulated against top-down addressable market calculations derived from FCC licensing volume and constellation deployment schedules.
Historical trendline analysis of defense space spending and commercial launch cadence informed projection frameworks across the analysis window. Segmentation modeling incorporated technology type, service delivery model, application criticality, and end-user security classification. CAGRs were derived from fitted growth curves calibrated to procurement announcement velocity and regulatory compliance timeline acceleration. Industry-specific inputs included Space Force budget appropriation trajectories and small satellite constellation deployment manifests.
Forecast precision tightens around the base case; tail outcomes carry wider variance under launch vehicle availability constraints and jurisdictional licensing fragmentation scenarios. Forecasts reflect assumptions on FCC rule enforcement consistency and ISO 24113 adoption velocity across major spacefaring nations. Deviation in Space Force procurement consolidation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space-Based Smart Sensors Market
Space
Space Blanket Market
Space
Space Sensors Market
Space
North America Spacesuit Market
Space
Africa Space Propulsion System Market
Space
Europe Space Electronics Market
Space
Space Launch Services Market
Space
Japan Space Electronics Market
Space
Space Ground Station Equipment Market
Space
India Space Electronics Market
Space
Space Tourism Market
Space
Space Propulsion Systems Market
Space
Space As a Service Market
Space
Space Rover Market
Space
US Space Launch Services Market
Space
China Space Electronics Market