
 Airport Baggage Tracking Systems Market | 2026-2036
Airport Baggage Tracking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Baggage Tracking Systems Market Insights
The gap between premium integrated tracking platforms and commodity barcode-only solutions is repositioning competitive dynamics across the sector. SITA leverages its global airline network relationships to sustain dominance in interline baggage messaging standards. Daifuku anchors its position through vertical integration into automated material handling hardware paired with tracking software. Honeywell International differentiates by competing across both aviation and broader logistics verticals, extending its sensor technology portfolio beyond airport boundaries.
Airport baggage tracking systems encompass hardware and software infrastructure that monitors individual luggage items from check-in through reclaim using automatic identification technologies, typically achieving read rates above 99.5% in RFID-enabled environments. These systems integrate with baggage handling conveyors, security screening equipment, and airline departure control systems to prevent loss, reduce theft, and enable proactive passenger communication. RFID technology leads current deployments due to IATA mandate compliance requirements and superior read performance in high-speed conveyor applications, while Bluetooth Low Energy represents the fastest-growing segment as airports pilot proximity-based passenger notifications and indoor positioning. Cloud-based deployment models are capturing expanding share among mid-tier airports seeking to avoid capital-intensive on-premises infrastructure.
The Federal Aviation Administration coordinates with TSA to enforce baggage screening integration standards that shape tracking system procurement specifications in the United States. IATA Resolution 753 creates binding compliance obligations for member airlines, directly stimulating demand for tracking infrastructure upgrades across international hub airports. Stakeholders must monitor evolving cybersecurity frameworks for aviation IoT devices as connected baggage tags and edge computing nodes expand the attack surface of airport operational networks.
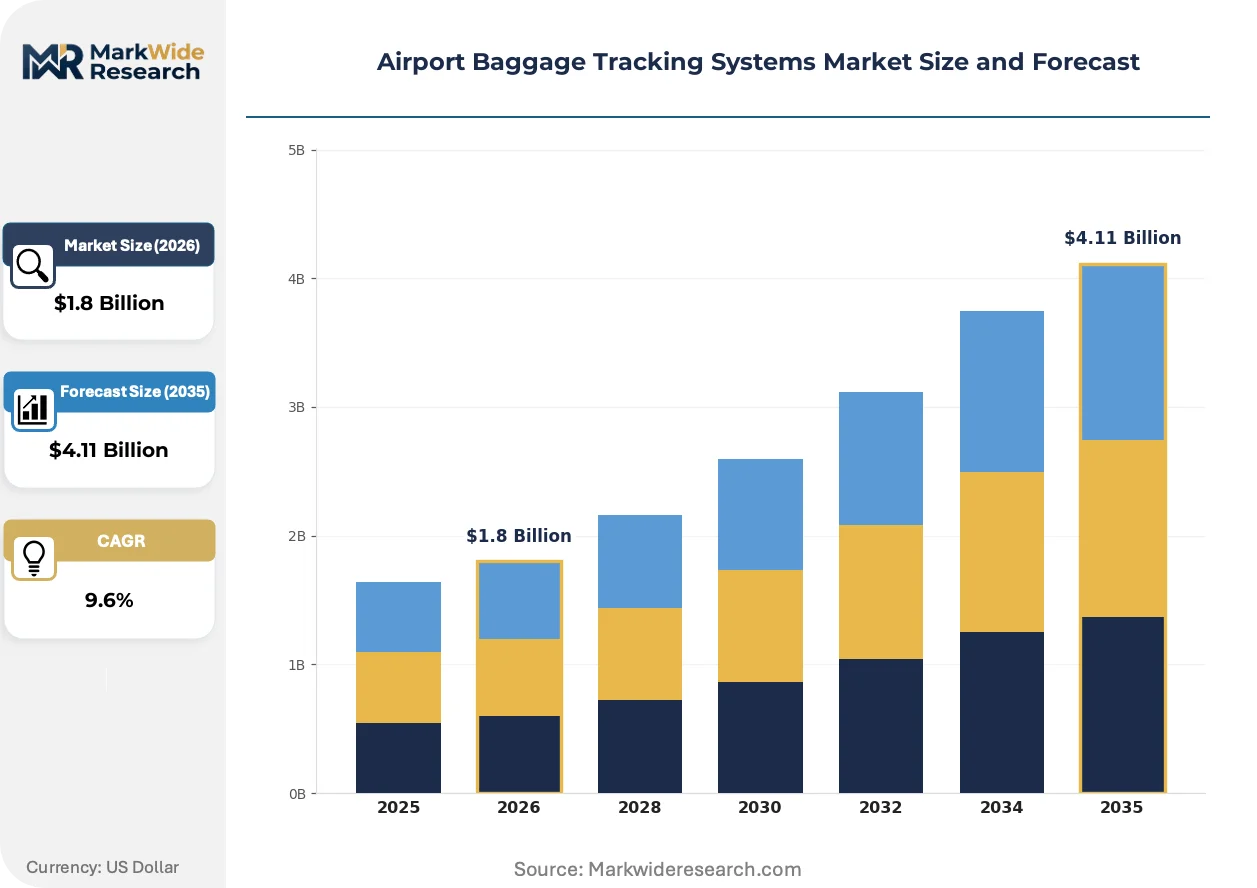
Market Dynamics
IATA Resolution 753 binds member airlines to end-to-end baggage tracking compliance, forcing infrastructure upgrades across hub airports while compressing procurement cycles for RFID and BLE-enabled systems.
Growth Catalysts
- RFID Mandate Enforcement:IATA Resolution 753 requires member airlines to track every bag at four key journey points. Airports in the United States, Germany, and Singapore are accelerating conveyor retrofits to meet these binding obligations.
- Passenger Experience Pressure:Real-time mobile notifications reduce service desk inquiries. Hub operators in Dubai and London Heathrow deploy proximity-based passenger alerts to preempt complaints before they reach social channels.
- Cloud Migration Economics:Mid-tier airports in India and Brazil avoid capital-heavy on-premises deployments by subscribing to hosted tracking platforms with per-bag pricing models.
Market Restraints
- Copper and Semiconductor Input Volatility:RFID inlay production depends on copper antenna etching and specialized ASIC supply. Price swings in these inputs compress hardware margins for system integrators.
- Concentrated Tag Supply:UHF RFID baggage tag manufacturing clusters in East Asia create single-source risk for airports in Latin America and Africa seeking qualified local suppliers.
- Legacy Conveyor Retrofit Complexity:Existing tilt-tray and belt systems at aging terminals require extensive mechanical modification to accommodate RFID tunnel readers without throughput degradation.
Strategic Opportunities
- BLE Proximity Services:Bluetooth Low Energy beacon networks enable indoor wayfinding and automated reclaim notifications. Pilot programs at Amsterdam Schiphol and Tokyo Narita test passenger-owned tag integration with airline apps.
- Interline Data Monetization:Standardized baggage messaging creates asset-tracking data layers usable by cargo handlers and ground transport providers seeking visibility beyond airport boundaries.
- Cybersecurity Certification Services:Connected baggage tags and edge nodes expand attack surfaces. Aviation IoT security frameworks from the FAA and EU Aviation Safety Agency create consultative service revenue for system vendors.
Industry Challenges
- Multi-Protocol Integration Talent:Baggage handling systems must synchronize RFID reads, legacy barcode scans, and emerging BLE signals. Scarce systems integration specialists familiar with aviation messaging standards delay project timelines.
- Inter-Airline Coordination Friction:Code-share agreements require compatible tracking data formats between carriers with disparate technology generations. Disputes over infrastructure cost allocation stall hub-wide deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Baggage Tracking Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, Barcode Scanning, Bluetooth Low Energy, GPS Tracking, NFC, Infrared Sensors Application: Baggage Handling, Security Screening, Passenger Self-Service, Lost & Found Management, Inventory Management, Customs Inspection Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Edge Computing End User: Airports, Airlines, Ground Handling Operators, Logistics Providers, Service Maintenance Firms |
| Companies Covered | Daifuku, Honeywell International, SITA, Lyngsoe Systems, Fives Group, BEUMER Group, Siemens, Quantum ID Technologies, Vanderlande, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Baggage Tracking Systems Market Trends and Innovations
Sensor fusion architectures are collapsing the distinction between baggage tracking, security screening, and passenger communication systems. This convergence demands new interoperability standards while opening service contract structures.
Passive UHF RFID with broadband antenna designs is unifying read performance across high-speed conveyor junctions and manual handling points. Tier-one hub operators in the United States and Germany deploy these tags at rates exceeding ten thousand units per hour. The technology is unifying previously siloed tracking data streams into single-source-of-truth platforms that baggage handlers and customer service agents access through common interfaces.
EU Aviation Safety Agency cybersecurity guidelines for connected ground support equipment impose encryption and access control mandates on baggage tag firmware. These rules accelerate hardware refresh cycles at European hubs while disqualifying uncertified vendors from procurement shortlists. Airlines operating transatlantic routes must reconcile these requirements with FAA TSA integration standards, creating dual-compliance engineering overhead.
Hub airports now unbundle tracking infrastructure from long-term baggage handling contracts. Procurement teams in the Middle East and Asia-Pacific evaluate sensor hardware separately from conveyor maintenance agreements, compressing vendor lock-in periods. This purchasing pattern shift favors modular RFID and BLE providers capable of standalone certification against IATA messaging protocols without exclusive material handling partnerships.
Airport Baggage Tracking Systems Market Segmentation
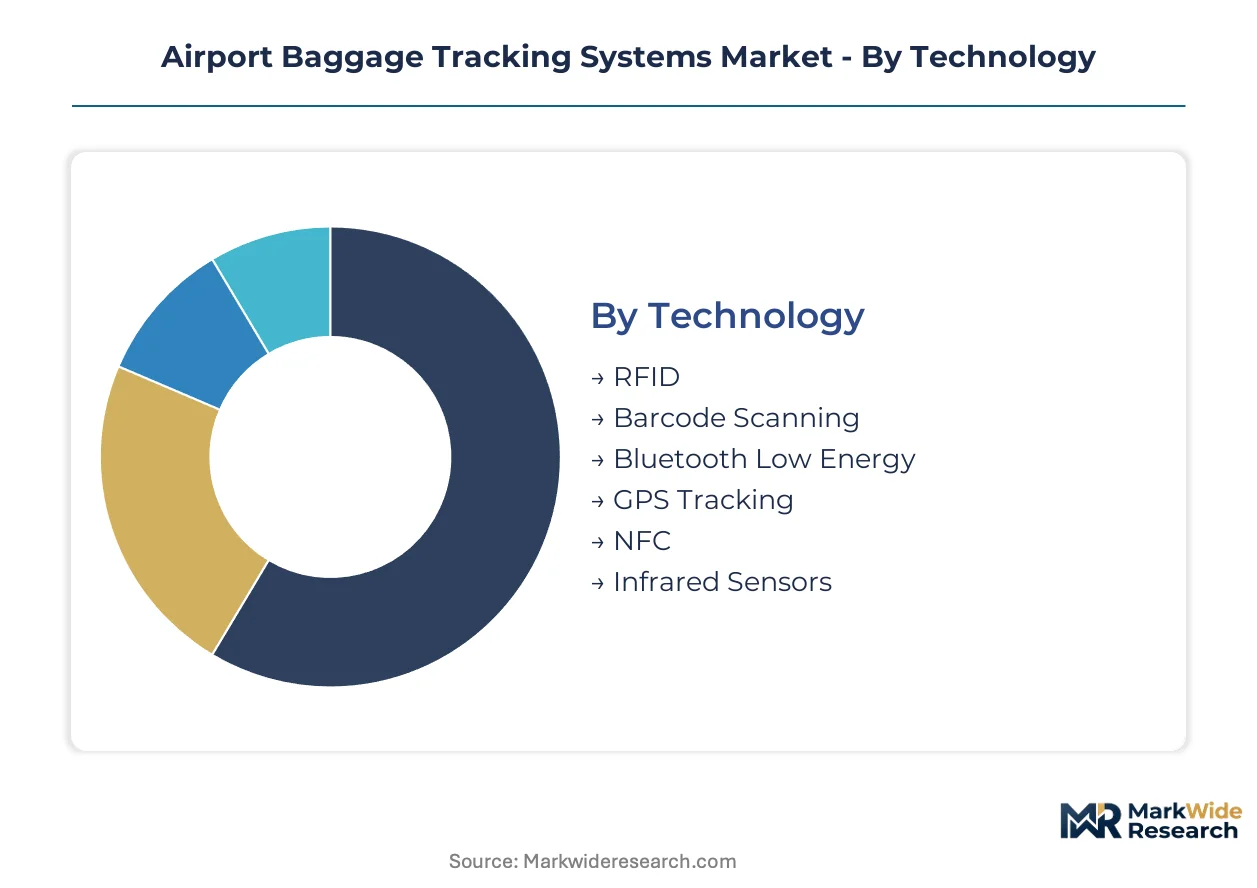
Technology choices in baggage tracking determine capital intensity, read accuracy, and compliance posture. Deployment models reshape vendor relationships and total cost of ownership. Application focus and end-user type dictate integration complexity and data sovereignty requirements.
Technology:
Supply of RFID inlays and BLE chipsets concentrates among East Asian contract manufacturers, creating procurement leverage for tier-one hub operators.
- RFID:Passive UHF tags with broadband antenna designs achieve read rates above 99.5% on high-speed conveyor junctions. Demand concentrates at United States and German hub airports retrofitting legacy tilt-tray systems to meet IATA Resolution 753 mandates. Copper antenna etching costs and ASIC supply volatility constrain hardware margins.
- Bluetooth Low Energy:Beacon networks enable proximity-based passenger notifications and indoor wayfinding. Pilot deployments at Amsterdam Schiphol and Tokyo Narita test passenger-owned tag integration with airline mobile apps. Battery life and firmware certification overhead create deployment friction.
- Barcode Scanning:Legacy laser and camera-based systems persist at regional terminals with constrained capital budgets.
- GPS Tracking:Satellite-based location for tarmac vehicle-mounted containers and remote apron operations.
- NFC:Short-range contactless authentication for premium passenger self-service kiosks.
- Infrared Sensors:Proximity detection for baggage dimensioning and security screening integration.
Today's leader: RFID. Tomorrow's challenger: Bluetooth Low Energy.
Application:
Cost tier differentiation separates premium integrated platforms from point solutions serving single operational functions.
- Baggage Handling:Conveyor-integrated RFID tunnels and tilt-tray sorters form the operational core. Major hub operators in Dubai and London Heathrow prioritize throughput optimization over incremental feature additions. Mechanical retrofit complexity at aging terminals extends procurement cycles.
- Security Screening:Explosive detection system integration demands synchronized tracking data streams for regulatory traceability. TSA and EU Aviation Safety Agency encryption mandates accelerate hardware refresh cycles at transatlantic hubs. Dual-compliance engineering overhead disadvantages smaller system integrators.
- Passenger Self-Service:Mobile-enabled bag drop and reclaim notifications reduce service desk staffing.
- Lost & Found Management:Image-based matching and centralized database query tools.
- Inventory Management:ULD container tracking and spare parts logistics for ground support equipment.
- Customs Inspection:Risk-based targeting integration with border agency data systems.
Security Screening commands premium pricing. Passenger Self-Service expands most quickly.
Deployment:
Volume concentration among mid-tier airports favors hosted models with per-bag pricing over capital-intensive infrastructure ownership.
- Cloud-Based:Subscription platforms eliminate on-premises server maintenance. Airports in India and Brazil adopt hosted tracking to bypass data center construction. Latency sensitivity for real-time conveyor control limits pure-cloud architectures at high-throughput hubs.
- On-Premises:Dedicated hardware and private network segmentation satisfy cybersecurity frameworks from the FAA and EU Aviation Safety Agency. European and United States hub operators retain control over passenger data residency. Upfront capital requirements exclude smaller regional terminals.
- Hybrid:Edge processing for time-critical reads with cloud analytics for reporting.
- SaaS:Software-layer subscriptions decoupled from sensor hardware procurement.
- Edge Computing:Local inference nodes for BLE proximity calculations and baggage image classification.
On-Premises dominates compliance-sensitive installations. Cloud-Based gains share fastest among capital-constrained operators.
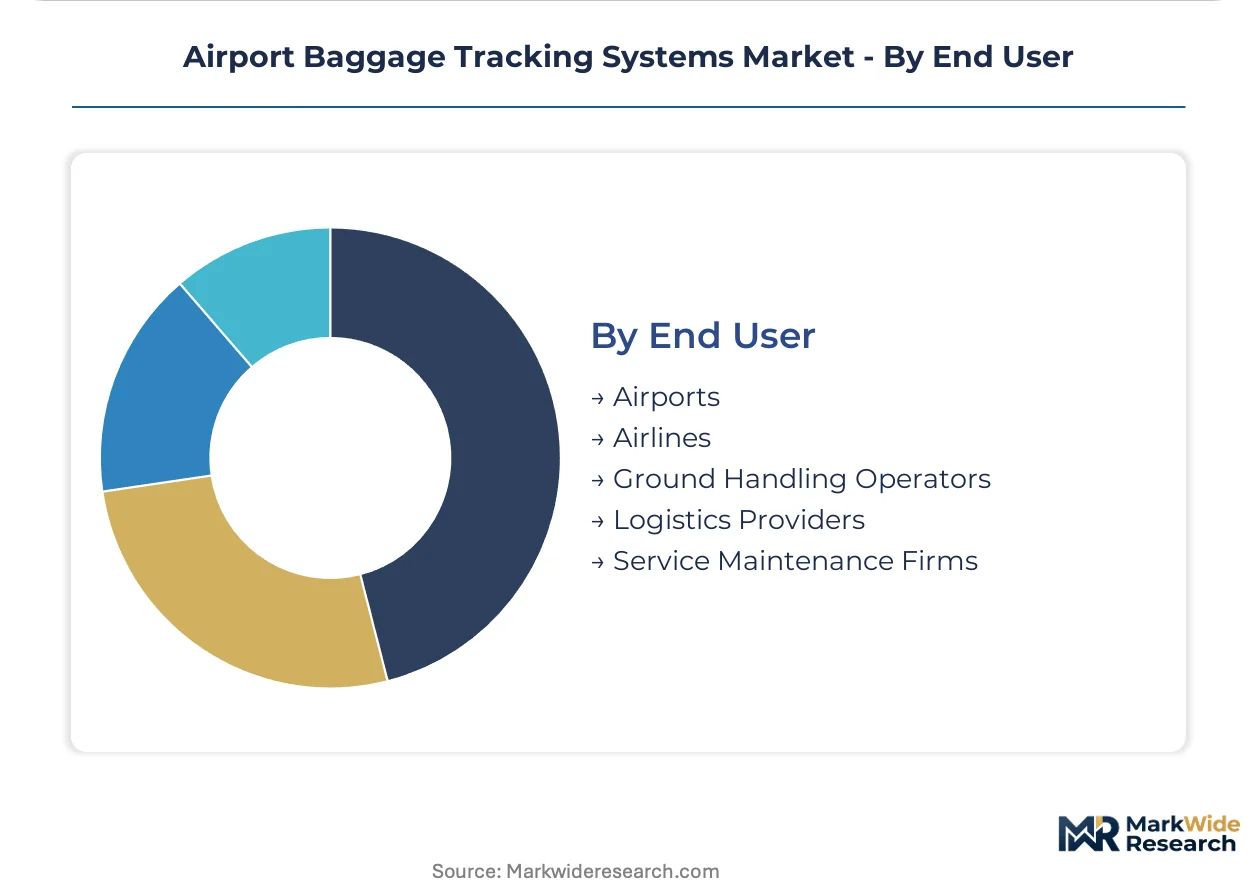
End User:
Customer type determines contract structure, with airports favoring unbundled sensor procurement and airlines prioritizing interline data standardization.
- Airports:Terminal operators procure tracking infrastructure separately from long-term baggage handling contracts. Procurement teams in the Middle East and Asia-Pacific evaluate RFID hardware on standalone IATA messaging certification. Infrastructure cost allocation disputes between code-share partners stall hub-wide deployments.
- Airlines:Network carriers mandate consistent tracking data formats across alliance partners. IATA Resolution 753 compliance obligations force fleet-wide technology standardization. Legacy carrier technology generations create integration friction with newer partners.
- Ground Handling Operators:Third-party service providers seek portable tracking tools across multiple airport contracts.
- Logistics Providers:Cargo handlers and ground transport operators leverage baggage messaging data for asset visibility beyond airport boundaries.
- Service Maintenance Firms:Conveyor OEMs and system integrators bundle tracking hardware with long-term service agreements.
Airports anchor current procurement volume. Airlines drive standardization momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in baggage tracking procurement velocity, with German hub operators prioritizing EU Aviation Safety Agency cybersecurity certification while United States airports emphasize TSA screening integration timelines.
United States
Major hub airports in Atlanta, Chicago, and Dallas-Fort Worth execute billion-dollar terminal modernization programs that embed RFID tunnel infrastructure. FAA coordination with TSA enforces baggage screening integration standards that shape tracking system specifications. Dallas-Fort Worth International Airport exemplifies this convergence, retrofitting legacy tilt-tray systems with automated identification tunnels.
Germany
Frankfurt and Munich airports drive conveyor retrofit demand to meet IATA Resolution 753 mandates ahead of alliance partner deadlines. EU Aviation Safety Agency cybersecurity guidelines for connected ground support equipment impose encryption mandates on baggage tag firmware. Frankfurt Airport anchors this compliance push, refreshing hardware cycles to satisfy dual-certification requirements for transatlantic operations.
Singapore
Changi Airport's Terminal 5 development program concentrates procurement for next-generation baggage handling infrastructure. The Civil Aviation Authority of Singapore mandates seamless interline data standardization across alliance partners. Changi's integrated testing facilities pilot BLE proximity services alongside RFID backbone systems.
United Arab Emirates
Dubai International Airport prioritizes passenger experience differentiation through real-time mobile notification deployment. The General Civil Aviation Authority aligns tracking infrastructure standards with IATA messaging protocols. Dubai's procurement teams unbundle sensor hardware from long-term conveyor maintenance contracts.
India
Mid-tier airports in Mumbai, Delhi, and Bangalore adopt cloud-based tracking platforms to bypass capital-intensive data center construction. The Airports Authority of India facilitates standardized procurement frameworks across public-private partnership terminals. Bangalore's Kempegowda International Airport exemplifies hosted deployment adoption with per-bag pricing models.
Airport Baggage Tracking Systems Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while specialized hardware fabricators and regional system integrators occupy adjacent tiers. The vendor base stratifies across three functional layers: automated material handling OEMs with captive software stacks, aviation-focused messaging specialists, and modular sensor providers serving unbundled procurement patterns. Strategic moves concentrate on M&A for conveyor-software convergence and cloud partnership formations to capture mid-tier airport subscriptions.
Within the integrated systems tier, Daifuku Co., Ltd. and Vanderlande Industries B.V. represent archetypal material handling OEMs with vertical control over hardware production. Honeywell International Inc. occupies a diversified position spanning aviation and broader logistics sensor markets. SITA anchors the aviation-specific messaging layer through interline standard relationships. These three exemplify distinct competitive vectors: captive manufacturing depth, cross-vertical technology extension, and industry protocol dominance.
| Leading Market Players |
|---|
| Daifuku |
| Honeywell International |
| SITA |
| Lyngsoe Systems |
| Fives Group |
| BEUMER Group |
| Siemens |
| Quantum ID Technologies |
| Vanderlande |
| Others |
Pricing and Supply Chain Analysis
Mid-tier airport operators in India and Brazil anchor demand for subscription-based tracking platforms, compressing upfront capital requirements into per-bag operational expenditure models that reshape vendor contract structures.
Pricing Analysis
The bundled-unbundled service split separates integrated material handling contracts from standalone sensor procurement. Three-tier pricing structure across premium certification-grade, standard IATA-compliant, and economy barcode-only levels reflects cybersecurity framework adherence and throughput specifications. Cost compression in the economy tier intensifies because copper antenna etching and ASIC supply volatility squeeze hardware margins. Regional terminals with constrained capital budgets exhibit highest price sensitivity, while transatlantic hub operators prioritizing dual FAA-EU Aviation Safety Agency certification accept premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with East Asian contract manufacturers concentrating UHF RFID inlay and BLE chipset production. Hardware fabrication draws from China, South Korea, and Taiwan for specialized antenna etching and semiconductor assembly. Copper and ASIC input price volatility creates margin instability for system integrators. Distribution runs through aviation-focused system integrators and conveyor OEMs with captive software stacks serving hub airport procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The divergence between FAA-TSA screening integration timelines in the United States and EU Aviation Safety Agency cybersecurity mandates in Germany creates arbitrage opportunities for vendors with dual-certification engineering capabilities.
For Market Incumbents: Deepen backward integration into RFID inlay production to offset copper and semiconductor input volatility threatening hardware margins. Expand cloud partnership formations with mid-tier airport operators in India and Brazil seeking per-bag subscription models, neutralizing emerging modular sensor providers exploiting unbundled procurement patterns. For New Entrants and Emerging Players: Capture the BLE proximity services segment piloting at Amsterdam Schiphol and Tokyo Narita, where passenger-owned tag integration with airline mobile apps remains underdeveloped. Target cloud-based deployment adoption among capital-constrained regional terminals bypassing on-premises infrastructure investment. For Investors and Strategic Acquirers: Material handling OEMs with captive software stacks are the most active acquirer in this space, seeking conveyor-software convergence to defend against modular sensor unbundling. Monitor IATA Resolution 753 enforcement acceleration as the inflection signal indicating procurement cycle compression and hardware refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Partnership Formation | Hosted platforms capture mid-tier airport subscriptions in India and Brazil. |
| RFID Tunnel Infrastructure Deployment | Atlanta and Dallas-Fort Worth embed automated identification in billion-dollar modernizations. |
| BLE Beacon Network Pilot | Amsterdam Schiphol tests passenger-owned tag integration with airline apps. |
| Dual-Certification Engineering Investment | Transatlantic operators reconcile FAA TSA standards with EU Aviation Safety Agency encryption mandates. |
| Sensor Hardware Unbundling | Dubai procurement teams separate RFID hardware from long-term conveyor maintenance contracts. |
Research Methodology
Direct dialogue with airport procurement directors, airline operations executives, baggage handling system integrators, and ground support equipment manufacturers grounded the qualitative assessment, cross-referenced against IATA messaging protocol documentation, FAA regulatory filings, EU Aviation Safety Agency cybersecurity guidelines, and customs trade data for RFID inlay imports. Bottom-up and top-down triangulation validated segment-level estimates.
Bottom-up modeling tracked technology deployment volumes across RFID, BLE, and legacy barcode installations, while top-down analysis calibrated total addressable market expansion against IATA Resolution 753 compliance deadlines and terminal modernization program announcements. The forecast framework incorporated deployment model segmentation by cloud-based, on-premises, and hybrid architectures, alongside end-user differentiation between airports, airlines, and ground handlers. CAGR derivation rested on procurement cycle compression observed at hub airports retrofitting legacy tilt-tray systems.
Copper price volatility, semiconductor supply disruption, and inter-airline cost allocation disputes are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about IATA mandate enforcement timelines and alliance partner technology standardization trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Integrated Proximity and Taxiway Guidance Light Systems on Aircraft Exteriors Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Smart Airport Market
Airport Technologies
Airport Baggage Conveyor System Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Airport Interactive Kiosk Market
Airport Technologies
Middle-East and Africa Smart Airport Market
Airport Technologies
Aviation Beacons Technology Market
Airport Technologies
Helideck Monitoring System Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Airport RFID System Market
Airport Technologies
Smart Airport 2.0 Market
Airport Technologies
Europe Smart Airport Market
Airport Technologies
Smart Airport 3.0 Market