
 Beryllium Aluminum Alloy Market | 2026-2036
Beryllium Aluminum Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Aluminum Alloy Market Outlook
REACH is restructuring the cost-of-entry calculus for European suppliers of beryllium aluminum alloy, forcing investment in closed-loop processing and worker exposure documentation. Materion Corporation leverages captive beryllium mining and refining to sustain integrated supply security across defense and aerospace channels. IBC Advanced Alloys Corp differentiates through specialized casting capabilities for nuclear and satellite applications. Ulba Metallurgical Plant JSC anchors Central Asian supply with state-backed uranium and rare metal processing infrastructure.
Beryllium aluminum alloy combines beryllium content typically ranging from 20% to 75% by weight with aluminum, yielding density near 2.1 g/cm³ and stiffness exceeding titanium alloys, primarily serving applications where structural efficiency under thermal or inertial loading determines system performance. High-strength alloy formulations dominate current aerospace frame procurement, while composite alloy variants represent the fastest-expanding category as satellite manufacturers seek tunable thermal expansion properties. Heat-treatable alloy segments command concentrated margin pools in defense electronics, where batch certification and traceability requirements limit supplier competition.
OSHA beryllium exposure standards and EPA hazardous waste classifications constrain US fabrication economics, while China's GB standards and MIIT industrial guidelines shape domestic capacity expansion and export licensing. The EU F-Gas Regulation and broader EU Green Deal material sustainability criteria are beginning to influence alloy recycling mandates and lifecycle disclosure requirements for European aerospace tier-one suppliers. Stakeholders must monitor evolving dual-use export control lists and national stockpile strategies, as beryllium's critical mineral status in multiple jurisdictions increasingly links alloy procurement to geopolitical alignment decisions.
Market Dynamics
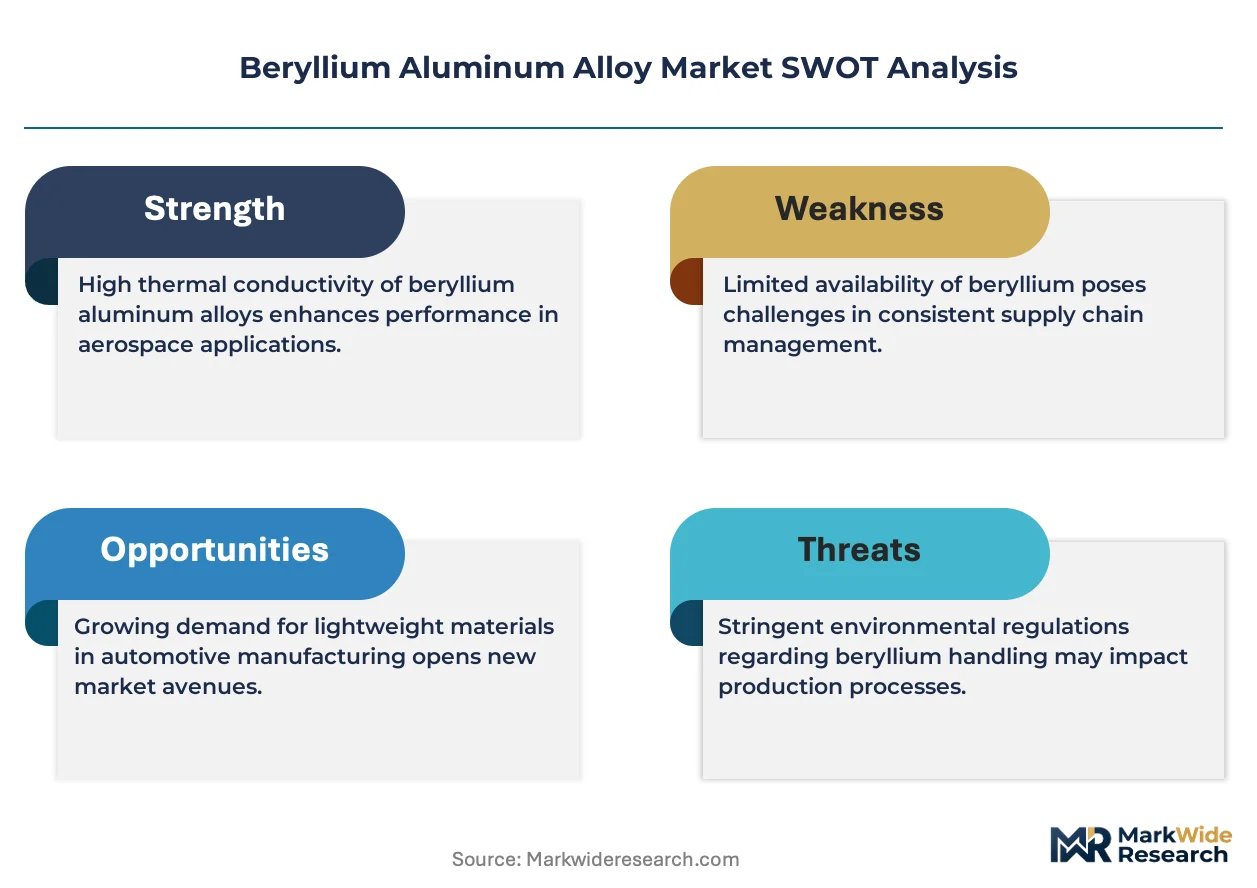
Defense procurement programs in the United States are expanding beryllium aluminum alloy adoption for lightweight military equipment, while REACH regulations in Europe are tightening material handling requirements and reshaping supplier compliance obligations.
Growth Catalysts
- Defense Modernization:US military procurement channels prioritize structural weight reduction in next-generation platforms, driving specification upgrades toward beryllium aluminum formulations with density near 2.1 g/cm³.
- Aerospace Manufacturing Clusters:Demand concentrates in China's aerospace corridor around Xi'an and Chengdu, where domestic alloy production scales rapidly to serve satellite and commercial aircraft programs.
- REACH Compliance Investment:European suppliers are redirecting capital toward closed-loop processing systems to satisfy ECHA exposure documentation mandates, creating competitive differentiation through certified handling protocols.
Market Restraints
- Beryllium Supply Concentration:Captive mining and refining operations in North America create dependency on vertically integrated producers, limiting spot market liquidity and price transparency for downstream fabricators.
- OSHA Exposure Standards:EPA hazardous waste classifications and OSHA worker protection rules constrain US fabrication economics, elevating compliance costs above competing lightweight material alternatives.
- Substitution Pressure from CFRP:Carbon fiber reinforced polymers capture share in non-thermal applications where stiffness-to-weight ratios satisfy design requirements without beryllium's toxicity handling burden.
Strategic Opportunities
- Satellite Thermal Management:Composite alloy variants with tunable thermal expansion coefficients are penetrating small-satellite constellations, where dimensional stability across orbital temperature cycling determines mission reliability.
- Nuclear Instrumentation Castings:Specialized foundry capabilities for neutron-transparent housings serve research reactor and medical isotope production equipment, leveraging beryllium's low atomic cross-section.
- EU Green Deal Recycling Mandates:Lifecycle disclosure requirements and material sustainability criteria are creating first-mover advantage for European tier-one suppliers with documented closed-loop recovery systems.
Industry Challenges
- Certification Timeline Compression:Defense electronics procurement requires batch-level traceability and heat-treatment certification that extends qualification cycles to 18-24 months, freezing out speculative capacity additions.
- Dual-Use Export Control Complexity:Beryllium's critical mineral status across multiple jurisdictions links alloy procurement decisions to geopolitical alignment, complicating long-term supply contracts with cross-border customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Aluminum Alloy Market |
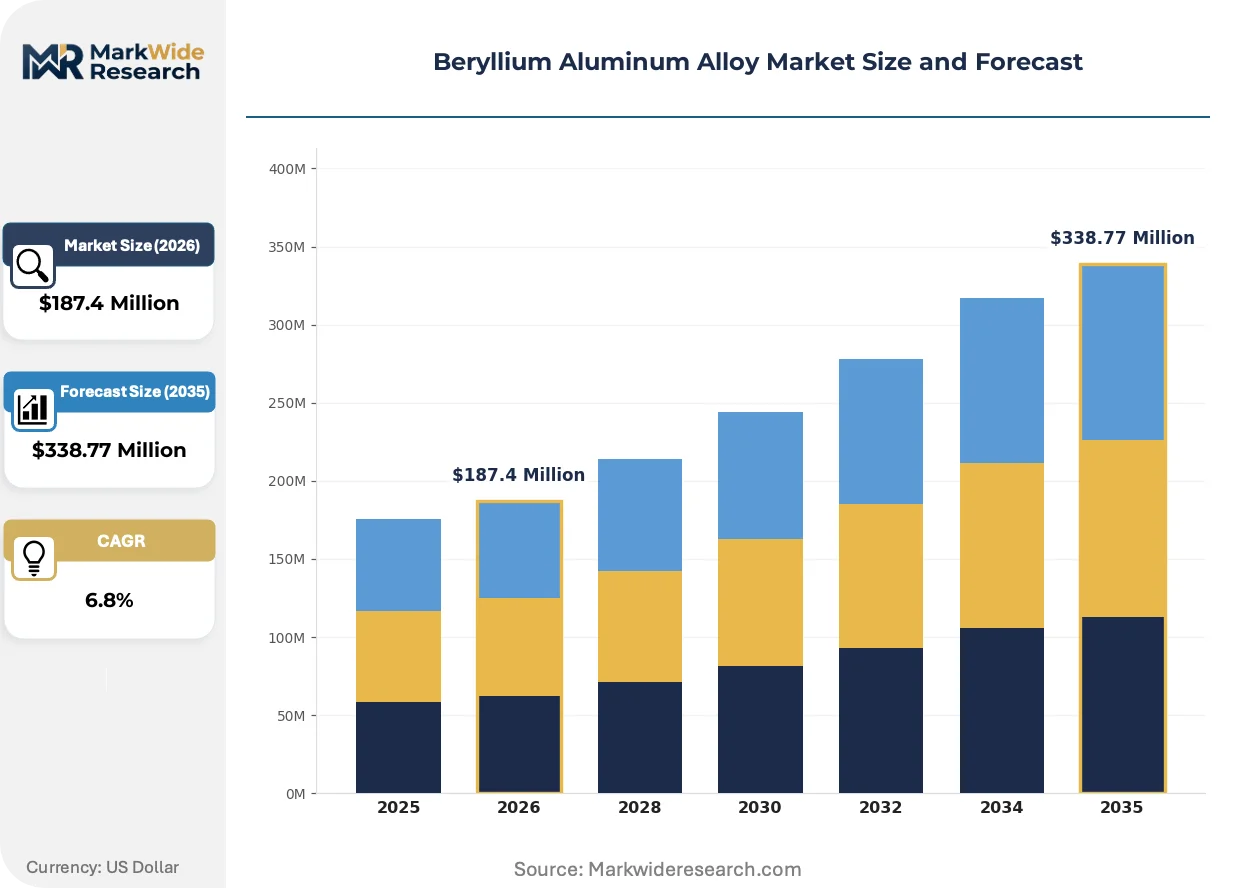
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Strength Alloy, Heat-Treatable Alloy, Non-Heat-Treatable Alloy, Composite Alloy End User: Aerospace, Electronics, Defense, Automotive Application: Structural Components, Electrical Connectors, Aerospace Frames, Military Equipment Form: Sheet, Extrusion, Casting, Bar |
| Companies Covered | Materion Corporation, IBC Advanced Alloys Corp, American Elements, Fuyun Hengsheng Beryllium Industry, Ulba Metallurgical Plant JSC, CNMC, Taiyuan Lutheran Hua Aluminum Processing, Mengzhou Xingda Alloy Chemical, Zhengzhou Shengboda Special Alloy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Aluminum Alloy Market Strategic Shifts
Additive manufacturing feedstock development is reshaping how beryllium aluminum alloys enter production workflows, displacing conventional casting and forging in prototype-to-production transitions.
Powder metallurgy near-net-shape processing is integrating laser powder bed fusion and electron beam melting systems into satellite component fabrication. Lockheed Martin and Northrop Grumman supplier networks are qualifying these processes for antenna boom and optical bench applications. The technology is compressing lead times from 16 weeks to under 4 weeks while reducing material scrap rates below 15 percent.
REACH Annex XIV authorization requirements are forcing European aerospace suppliers to document worker exposure below 0.0002 mg/m³ across machining and finishing operations. Materion Corporation's German subsidiary has invested in automated glovebox systems to maintain production continuity. Heat-treatable alloy segments face the steepest compliance burden due to furnace operation particulate generation.
Buyers are consolidating supplier relationships around integrated material-certification-service bundles, displacing transactional spot purchasing for defense and space programs. Tier-one contractors now require alloy producers to maintain AS9100 and NADCAP heat-treatment accreditation as baseline qualification. This concentration is most visible in the US Department of Defense supply base, where prime contractors have reduced qualified beryllium aluminum sources from 12 to 4 over the past decade.
Beryllium Aluminum Alloy Market Segmentation
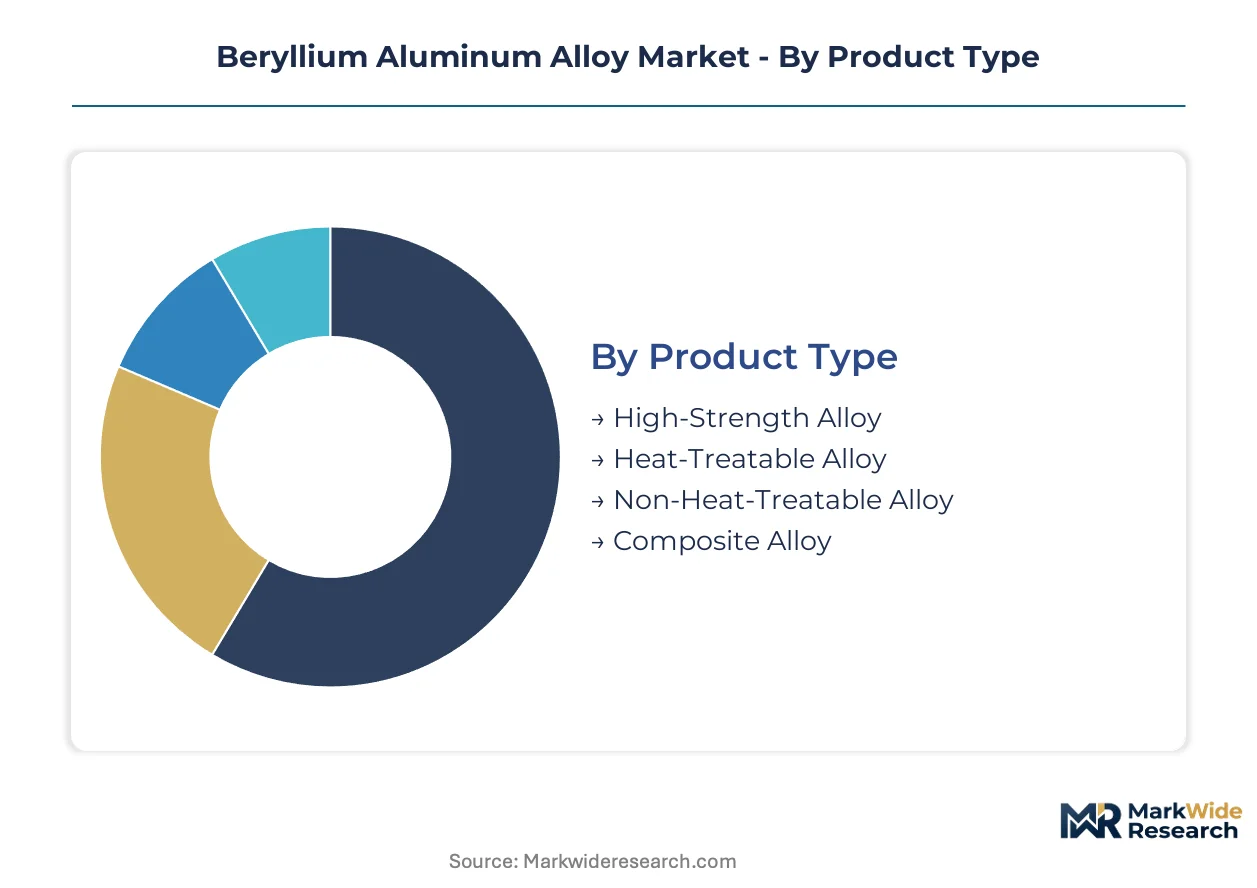
Beryllium aluminum alloy procurement diverges sharply across end-use requirements, with defense electronics demanding certified heat-treatment traceability while satellite manufacturers prioritize tunable thermal expansion in composite formulations. Specification-grade differentiation determines supplier qualification timelines and margin capture.
Product Type:
Buyers in this category separate by structural performance thresholds versus thermal management priorities, with defense contractors paying premiums for batch-certified material and commercial aerospace seeking weight-optimized alternatives.
- High-Strength Alloy:Formulations with beryllium content ranging from 40% to 75% by weight deliver specific stiffness exceeding titanium alloys at density near 2.1 g/cm³. Demand concentrates in US Department of Defense airframe procurement, where specification upgrades toward beryllium aluminum formulations accelerate under next-generation platform development.
- Composite Alloy:Hybrid formulations incorporate ceramic or carbon reinforcements to achieve tunable coefficients of thermal expansion. Satellite manufacturers in China's Xi'an aerospace corridor scale procurement most rapidly, as dimensional stability across orbital temperature cycling determines mission reliability for small-satellite constellations.
- Heat-Treatable Alloy:Precipitation-hardening grades enable strength optimization through controlled thermal processing. Batch certification requirements extend qualification cycles to 18-24 months.
- Non-Heat-Treatable Alloy:Work-hardening grades serve applications where thermal processing risks particulate generation. OSHA exposure standards constrain US fabrication economics.
High-strength alloy leads volumes today; composite alloy is gaining share fastest.
End User:
Customer concentration varies by certification burden, with defense and aerospace programs consolidating supplier relationships around integrated material-certification-service bundles while automotive remains speculative.
- Aerospace:Commercial aircraft and satellite programs drive specification-grade demand, with China's Chengdu manufacturing cluster scaling domestic alloy production to serve indigenous narrow-body and satellite platform development.
- Defense:US military procurement channels prioritize structural weight reduction, with prime contractors reducing qualified beryllium aluminum sources from 12 to 4 over the past decade.
- Electronics:Heat-dissipating housings and thermal management substrates serve high-reliability computing applications. REACH Annex XIV documentation mandates reshape European supplier economics.
- Automotive:Motorsport and limited-production electric vehicle prototypes test beryllium aluminum for unsprung mass reduction. Volume scaling remains constrained by toxicity handling costs.
Defense procurement anchors revenue concentration; aerospace applications are expanding most quickly.
Application:
Functional requirements in this category determine form factor selection and heat-treatment protocol, with structural applications demanding forged integrity and electrical applications prioritizing conductivity consistency.
- Structural Components:Load-bearing brackets and support structures in satellite and aircraft assemblies require forged or extruded integrity with ultrasonic inspection certification.
- Aerospace Frames:Fuselage and wing structural elements in next-generation platforms specify beryllium aluminum for density advantages. Lockheed Martin and Northrop Grumman supplier networks drive qualification protocols.
- Military Equipment:Lightweight armor carriers, weapon system housings, and sighting equipment serve US Army and Marine Corps modernization programs. Additive manufacturing feedstock development compresses lead times from 16 weeks to under 4 weeks.
- Electrical Connectors:High-frequency signal integrity applications leverage beryllium's thermal conductivity and low magnetic susceptibility.
Military equipment commands premium pricing; aerospace frames are climbing the fastest.
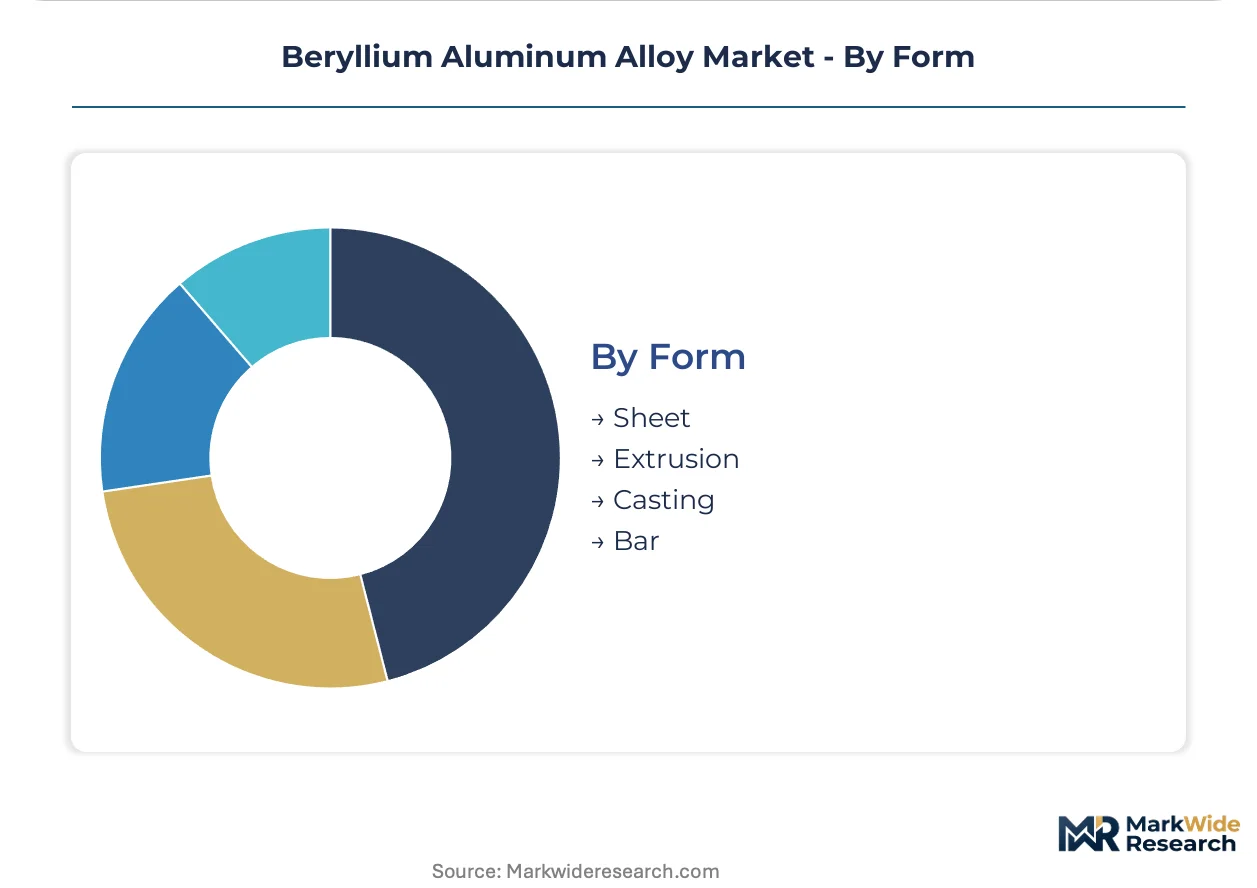
Form:
Processing technology maturity and near-net-shape capability differentiate buyer preferences, with additive manufacturing disrupting traditional wrought product procurement in satellite component fabrication.
- Extrusion:Long-product forms serve antenna booms, optical benches, and structural framing with optimized grain orientation. Powder metallurgy near-net-shape processing integrates laser powder bed fusion systems.
- Casting:Complex geometry realization for neutron-transparent housings in nuclear instrumentation serves research reactor and medical isotope production equipment. IBC Advanced Alloys Corp specializes in this capability.
- Sheet:Rolled plate and foil products supply skin panels and heat-dissipating substrates. Thickness tolerance requirements vary by aerospace tier-one versus electronics subcontractor specifications.
- Bar:Round and rectangular bar stock feeds precision machining operations for connector bodies and fastener systems.
Extrusion dominates current shipment volumes; casting is accelerating most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical workforce clusters in Kazakhstan, the United States, and China anchor global beryllium aluminum alloy supply capacity. These talent concentrations determine regional competitive positioning more than raw material access alone.
United States
Department of Defense procurement channels prioritize structural weight reduction in next-generation platforms, driving specification upgrades toward beryllium aluminum formulations. OSHA beryllium exposure standards and EPA hazardous waste classifications constrain fabrication economics, elevating compliance costs. Utah-based mining and refining operations sustain vertically integrated supply security for defense and aerospace channels.
China
Domestic aerospace manufacturing scales rapidly to serve satellite and commercial aircraft programs, with demand concentrating in the Xi'an and Chengdu manufacturing corridor. MIIT industrial guidelines and GB standards shape capacity expansion and export licensing protocols. State-backed rare metal processing infrastructure accelerates indigenous alloy production for narrow-body and satellite platform development.
Kazakhstan
Ulba Metallurgical Plant JSC anchors Central Asian supply with state-backed uranium and rare metal processing infrastructure, serving neutron-transparent housing applications for research reactor equipment. The country's national industrial regulator oversees dual-use material handling protocols. Ust-Kamenogorsk-based operations leverage legacy Soviet metallurgical expertise for specialized casting capabilities.
Germany
REACH Annex XIV authorization requirements force aerospace suppliers to document worker exposure below 0.0002 mg/m³ across machining operations, reshaping supplier compliance obligations. ECHA exposure documentation mandates redirect capital toward closed-loop processing systems. Materion Corporation's German subsidiary has invested in automated glovebox systems to maintain production continuity under tightening ECHA standards.
Japan
METI industrial policy supports advanced materials development for satellite thermal management applications, where composite alloy variants with tunable thermal expansion coefficients penetrate small-satellite constellations. JIS standards govern material certification protocols for aerospace tier-one suppliers. Tokyo-Osaka industrial corridor fabricators focus on high-reliability electronics substrates and precision connector applications.
Beryllium Aluminum Alloy Market Competitive Environment
The competitive structure tilts toward vertically integrated specialists with captive raw material access. Three to four dominant producers control the majority of qualified supply for defense and aerospace certification programs. The vendor base separates into mining-integrated refiners, specialized foundry operators, and regional fabrication specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with batch certification requirements limiting speculative entry.
Among North American mining-integrated producers, Materion Corporation exemplifies the captive supply archetype through in-house beryllium extraction and refining operations. IBC Advanced Alloys Corp occupies a position within the specialized foundry tier, representing capabilities for nuclear and satellite casting applications. Ulba Metallurgical Plant JSC anchors the state-backed infrastructure archetype, sitting within Central Asian supply networks with rare metal processing heritage.
| Leading Market Players |
|---|
| Materion Corporation |
| IBC Advanced Alloys Corp |
| American Elements |
| Fuyun Hengsheng Beryllium Industry |
| Ulba Metallurgical Plant JSC |
| CNMC |
| Taiyuan Lutheran Hua Aluminum Processing |
| Mengzhou Xingda Alloy Chemical |
| Zhengzhou Shengboda Special Alloy |
| Others |
Value Chain & Pricing Dynamics
Beryllium ore extraction costs in Utah and Kazakhstan feed through captive refining operations to create three distinct pricing tiers for downstream fabricators, with defense contractors absorbing premiums for batch-certified material while commercial aerospace buyers negotiate volume scales.
Pricing Analysis
Bundled material-certification-service contracts dominate defense procurement, while unbundled spot transactions persist for non-critical industrial applications. Price differentiation rests on AS9100 accreditation status and heat-treatment traceability documentation, with certified suppliers commanding substantial premiums over uncertified competitors. Cost compression in commercial aerospace segments is intensifying because Chinese domestic producers scale output in the Xi'an corridor. Defense electronics buyers show lowest price sensitivity due to mission-critical performance requirements, whereas automotive prototyping programs demonstrate highest sensitivity to toxicity-handling cost burdens.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defense and satellite manufacturer demand, with prime contractors consolidating qualified supplier bases from twelve sources to four over the past decade. Geographic supply concentration centers on the United States, Kazakhstan, and China, where captive mining and state-backed rare metal processing infrastructure anchor output. Raw material flows draw from beryllium bertrandite deposits, aluminum master alloys, and specialized ceramic reinforcements for composite formulations. Single-source vulnerability around Materion Corporation's Utah refining complex presents structural risk to non-integrated fabricators. Distribution runs through tier-one aerospace contractors with NADCAP heat-treatment accreditation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beryllium aluminum alloy functions as a stable compounder anchored by defense procurement cycles that refresh platform specifications across multi-decade modernization timelines.
For Market Incumbents: Cement supply security through backward integration into beryllium extraction or long-term offtake agreements with Kazakh state infrastructure. Carbon fiber reinforced polymers threaten structural applications where thermal loading is absent, demanding incumbents deepen certification moats through NADCAP heat-treatment investment. Capacity expansion in China's Chengdu corridor captures satellite constellation growth while insulating against REACH-driven European supply constraints.
For New Entrants and Emerging Players: Enter via specialized casting capabilities for neutron-transparent nuclear instrumentation housings, where IBC Advanced Alloys Corp demonstrates viable positioning outside vertically integrated defense supply chains. Small-satellite thermal management applications in China's Xi'an aerospace corridor offer most penetrable demand segment. Go-to-market execution should leverage powder metallurgy near-net-shape processing to compress qualification timelines against incumbent forging lead times.
For Investors and Strategic Acquirers: Consolidation pressure builds where batch certification requirements extend qualification cycles beyond eighteen months, freezing out speculative capacity additions. Five-to-ten year viability favors mining-integrated refiners with defense channel access over standalone fabrication specialists. Acquisition target archetype: specialized foundry operators with nuclear or satellite casting accreditation. Signal to watch: dual-use export control list revisions linking beryllium procurement to geopolitical alignment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beryllium Extraction | Captive Utah or Kazakh ore access insulates against spot market illiquidity and price opacity. |
| NADCAP Heat-Treatment Accreditation | Defense prime contractor qualification requirements freeze out uncertified competitors from premium segments. |
| Closed-Loop Processing System Deployment | Automated glovebox installations satisfy ECHA exposure mandates below 0.0002 mg/m³ thresholds. |
| Powder Metallurgy Near-Net-Shape Capacity | Laser powder bed fusion integration compresses satellite component lead times from sixteen weeks to under four. |
| Dual-Use Export Control Compliance Investment | Documentation protocols align alloy procurement with national stockpile strategies across multiple jurisdictions. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, aerospace tier-one supplier quality directors, nuclear instrumentation foundry managers, and REACH compliance consultants with secondary validation. Sources included customs trade data for beryllium concentrate flows, SEC filings from mining-integrated producers, ECHA authorization documentation, and MIIT industrial guideline releases. Bottom-up alloy shipment estimates by form factor and end-use were triangulated against top-down defense budget allocation analysis.
Segment-weighting approaches distributed volume and value across the projection horizon by product type, end-user industry, application function, and geographic production cluster. Modeled dimensions included high-strength versus composite versus heat-treatable alloy grades, defense versus aerospace versus electronics demand, and structural versus thermal management applications. CAGRs were derived from regression analysis of historical procurement patterns against platform development timelines, with inputs from satellite constellation deployment schedules and nuclear reactor instrumentation replacement cycles.
The model holds under stable defense modernization funding and continued beryllium critical mineral designation; deviation in dual-use export control enforcement or REACH authorization revocation timelines would shift supply availability assumptions. Periodic stress-testing of base assumptions is recommended against OSHA exposure standard revisions and Chinese export licensing protocol changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Ablative Coatings Market