
 Space Propulsion Systems Market | 2026-2036
Space Propulsion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Space Propulsion Systems Market Intelligence
Aftermarket service revenue for thruster refurbishment and propellant reloading is reshaping margin distribution across the value chain. L3Harris Technologies leverages its satellite integration heritage to sustain long-term service contracts with government end users. ArianeGroup anchors European launch capacity through Ariane 6 propulsion architecture and dominates cryogenic engine production. Northrop Grumman Corporation differentiates via solid rocket motor expertise and controls strategic defense propulsion programs.
Space propulsion systems encompass thrust-generating assemblies—chemical engines, electric thrusters, and emerging nuclear thermal designs—that accelerate spacecraft through controlled expulsion of propellant mass, typically achieving specific impulse values from 300 seconds (chemical) to over 3,000 seconds (ion electric). These systems enable orbit insertion, station-keeping, and deep-space transit for commercial, civil, and military payloads. Chemical propulsion retains the largest installed base for heavy-lift launch while electric propulsion segments capture expanding share in satellite bus applications due to propellant mass efficiency. Green propellant categories within fuel type segmentation are gaining fastest traction as operators replace hydrazine to comply with ground-handling safety protocols and reduce launch preparation complexity.
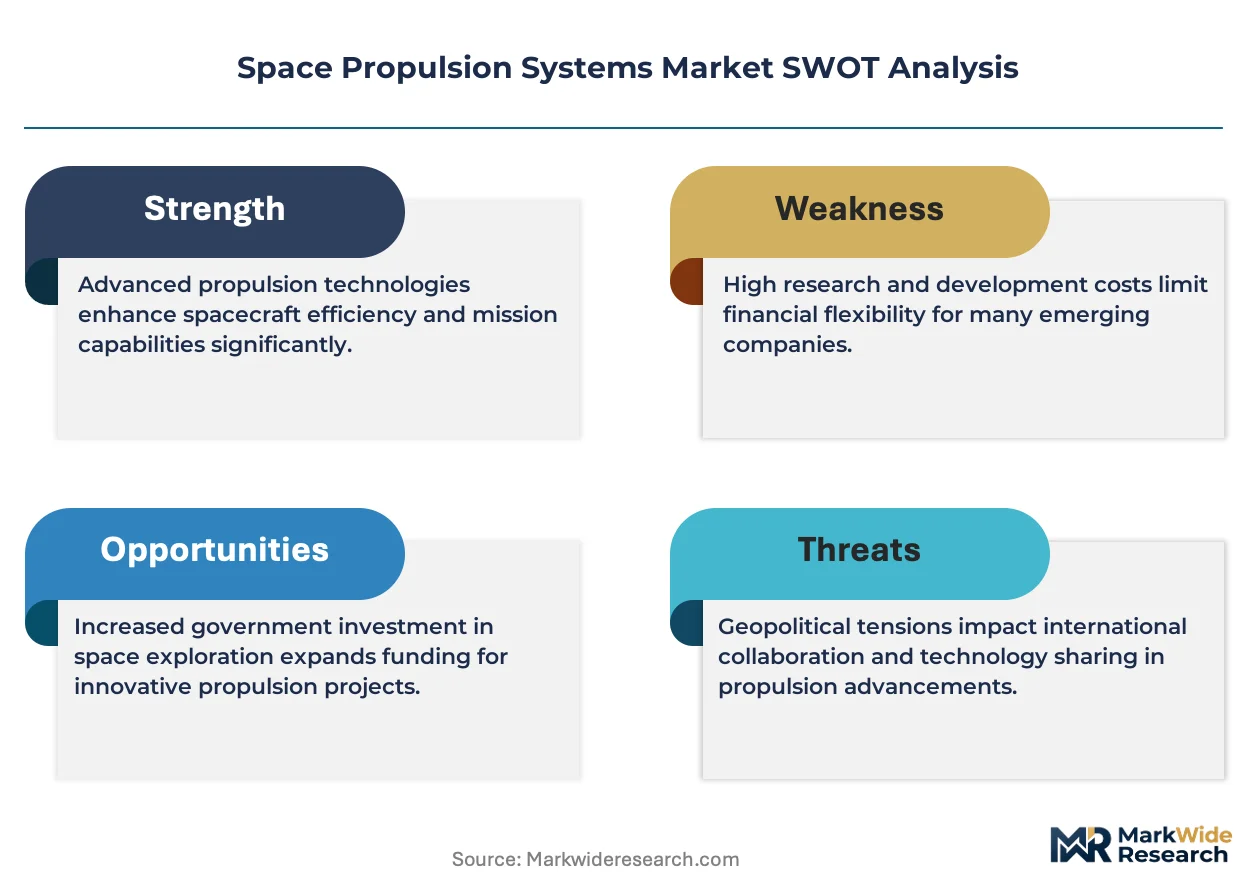
FAA launch licensing requirements, EPA National Emission Standards for Hazardous Air Pollutants, and ESA REACH-aligned propellant restrictions collectively elevate compliance costs and filter market access for non-certified suppliers. NASA's In-Space Propulsion Technology program and the EU Space Programme Agency procurement standards further steer R&D investment toward flight-qualified electric and green propulsion architectures. Stakeholders must monitor evolving debris-mitigation rules and propellant toxicity thresholds to align product roadmaps with operational certification timelines.
Market Dynamics
The transition from toxic hydrazine to green monopropellants and the proliferation of electric thrusters for satellite constellations are restructuring procurement priorities and certification timelines across the propulsion value chain.
Growth Catalysts
- ESA REACH-aligned propellant restrictions:European mandates for reduced toxicity are accelerating qualification programs for ammonium dinitramide-based fuels and LMP-103S alternatives.
- Commercial satellite constellation expansion:Low Earth orbit broadband operators are procuring Hall-effect thrusters for orbit-raising missions, displacing chemical systems in station-keeping roles.
- Reusable launch vehicle programs:Venture-backed developers in the United States are contracting for flight-proven engine architectures, creating sustained demand for refurbishment-capable propulsion modules.
Market Restraints
- Xenon supply concentration:Russia and South Africa control over eighty percent of global xenon refining capacity, exposing electric thruster manufacturers to geopolitical supply interruptions.
- Flight qualification timelines:NASA and ESA heritage certification protocols demand three to five years of on-orbit demonstration before procurement approval, compressing revenue recognition windows.
- Capital intensity of test infrastructure:Vacuum chamber facilities for electric thruster validation require investments exceeding fifty million dollars, filtering market entry to well-capitalized suppliers.
Strategic Opportunities
- In-space manufacturing and assembly:Orbital propellant depots and on-orbit thruster integration are creating demand for modular, refillable propulsion architectures.
- India's space program expansion:ISRO's commercial launch vehicle development and private space participation under IN-SPACe are opening procurement channels for foreign propulsion suppliers.
- Dual-use technology convergence:Missile defense interceptor propulsion and satellite maneuvering systems are sharing component architectures, enabling cross-program economies of scale.
Industry Challenges
- Specialized workforce scarcity:Plasma physics and combustion engineering talent pools are insufficient to support simultaneous scaling of electric and chemical thruster production lines.
- Debris mitigation compliance:Post-mission disposal requirements under FCC and ESA guidelines are forcing redesign of propulsion system duty cycles and fuel reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Propulsion Systems Market |
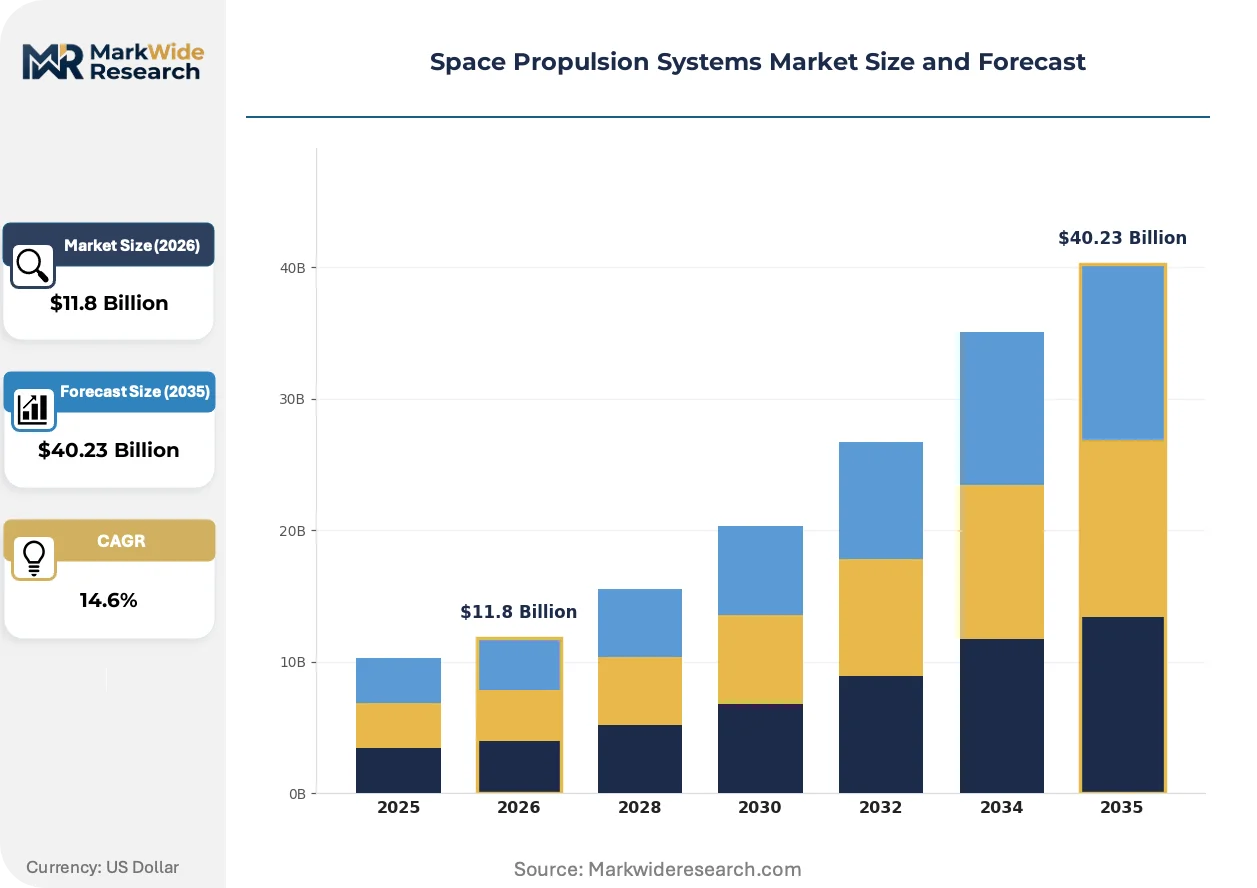
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chemical Propulsion, Electric Propulsion, Hybrid Propulsion, Nuclear Thermal Propulsion Application: Satellite Launch, Space Exploration, Orbital Maneuvering, Interplanetary Missions End User: Government Agencies, Private Companies, Research Institutions, Space Agencies Fuel Type: Liquid Propellant, Solid Propellant, Gaseous Propellant, Green Propellant |
| Companies Covered | L3Harris Technologies, Inc., ArianeGroup GmbH, Northrop Grumman Corporation, Moog Inc., IHI Corporation, Safran SA, Airbus SE, Dawn Aerospace, Thales Alenia Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Propulsion Systems Market Strategic Shifts & Innovations
Propulsion architectures are converging around modularity and reusability, with electric systems capturing satellite bus applications while chemical engines retain heavy-lift dominance through staged combustion refinements.
Hybrid chemical-electric propulsion is hybridizing mission profiles for geostationary satellites, combining chemical engines for rapid orbit insertion with electric thrusters for station-keeping. Operators like SES and Intelsat are retrofitting existing buses with this dual-mode capability, extending operational life while reducing total propellant mass. The structural consequence is hybridizing supplier relationships, as satellite manufacturers now integrate thrusters from separate chemical and electric specialists rather than single-source procurement.
EPA National Emission Standards for Hazardous Air Pollutants are tightening ground-handling protocols for hydrazine fuels, elevating operational costs at US launch facilities. The industrial consequence is accelerated investment in green propellant loading infrastructure at Cape Canaveral and Vandenberg Space Force Base. Small satellite operators and university missions are most affected, with many redirecting procurement toward flight-qualified LMP-103S and AF-M315E systems to avoid compliance delays.
Service-based revenue models are unbundling propulsion hardware from operational support, with constellation operators purchasing thrust-hours rather than thruster units. This disrupts traditional equipment sales channels and replaces them with performance-guaranteed contracts covering refurbishment and on-orbit monitoring. The shift is most visible in the United States, where Space Force and commercial LEO operators are negotiating multi-year service agreements with propulsion suppliers for integrated mission support.
Space Propulsion Systems Market Segmentation
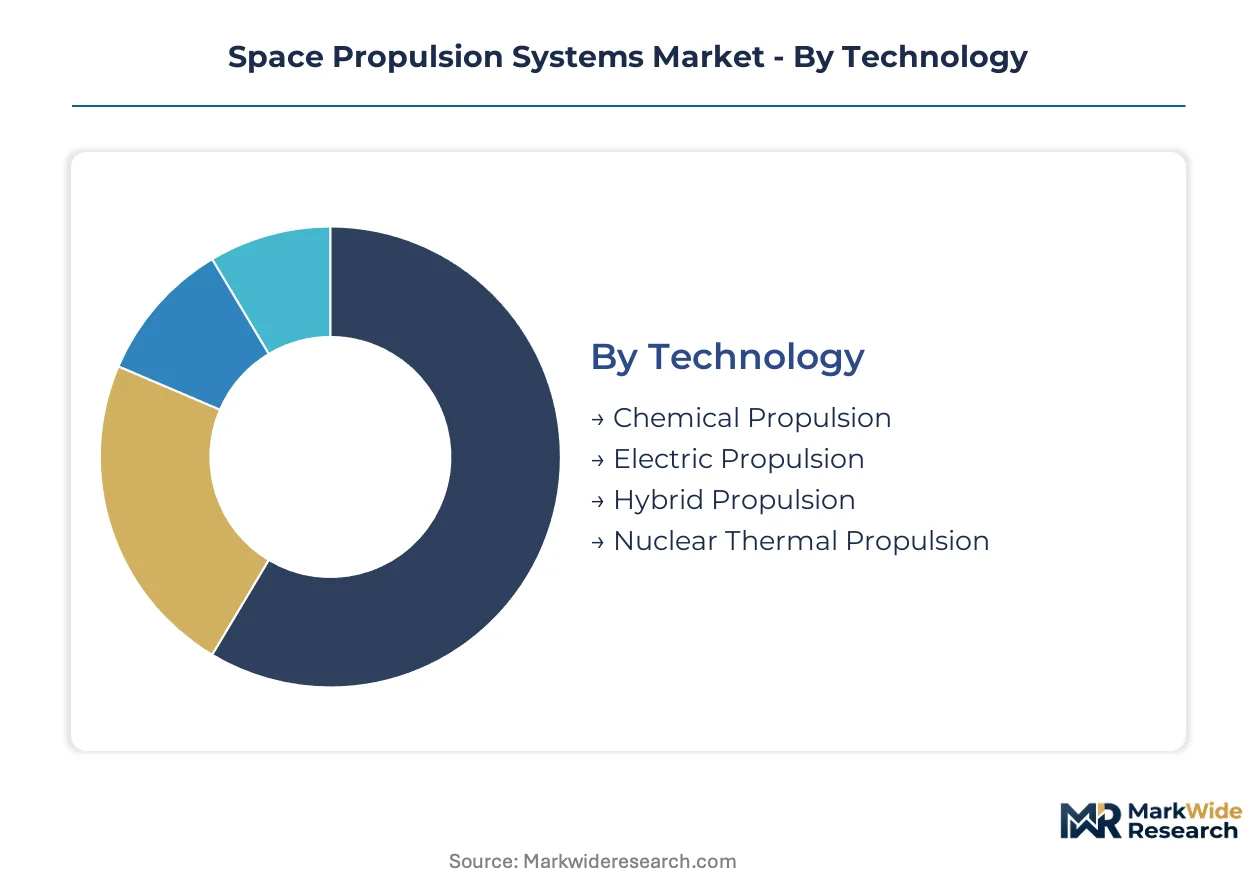
Propulsion system procurement diverges sharply across mission profiles, with chemical engines dominating heavy-lift launch while electric thrusters capture satellite constellation deployment. Technology selection directly determines fuel infrastructure requirements, qualification timelines, and operational lifecycle costs for spacecraft operators.
Technology:
Mature chemical architectures coexist with emerging electric and nuclear designs, creating a tiered innovation landscape with distinct certification barriers and application boundaries.
- Chemical Propulsion:Combustion-based systems using liquid or solid propellants generate thrust through controlled exothermic reactions, achieving specific impulse values around 300-450 seconds. Launch service providers in the United States rely on these systems for Falcon 9 and Vulcan Centaur first-stage propulsion, driven by Space Force national security launch contracts requiring flight-proven heritage.
- Electric Propulsion:Ion thrusters and Hall-effect systems accelerate propellant via electromagnetic fields, delivering specific impulse exceeding 3,000 seconds at the cost of low thrust magnitude. Commercial LEO broadband operators are procuring these units for orbit-raising missions, constrained by xenon supply concentration in Russia and South Africa.
- Hybrid Propulsion:Combines chemical combustion with electric acceleration stages to optimize mission delta-V across orbital transfer phases.
- Nuclear Thermal Propulsion:Uses nuclear reactor heat to expand hydrogen propellant, offering twice the specific impulse of chemical systems for deep-space transit applications.
Chemical propulsion handles the majority of throughput; electric propulsion is the fastest mover on share.
Application:
Cost tier stratification separates high-volume satellite deployment from bespoke deep-space missions with radically different procurement economics.
- Satellite Launch:Booster-stage propulsion for payload insertion into low Earth, medium Earth, or geostationary transfer orbits. Reusable launch vehicle programs in the United States are driving demand for refurbishment-capable engine architectures with rapid turnaround cycles.
- Space Exploration:Crewed and uncrewed missions beyond Earth orbit requiring high-reliability, long-duration propulsion systems. NASA's Artemis program and ESA lunar gateway initiatives are steering investment toward cryogenic engine qualification for cis-lunar operations.
- Orbital Maneuvering:Station-keeping, collision avoidance, and end-of-life deorbit burns for operational spacecraft.
- Interplanetary Missions:Deep-space transit requiring high-efficiency propulsion with multi-year operational lifetimes and autonomous fault management.
Satellite launch absorbs the largest capital deployment; space exploration commands the highest unit margins.
End User:
Customer type fragmentation creates divergent procurement protocols, with government agencies mandating heritage certification while private operators prioritize cost-per-kilogram metrics.
- Government Agencies:National defense and civilian space organizations with mission-assurance requirements and multi-year budgeting cycles. The United States Space Force and NASA impose three-to-five-year qualification protocols that filter supplier participation.
- Private Companies:Venture-backed launch providers and satellite constellation operators with commercial risk tolerance and rapid iteration cycles. SpaceX and Blue Origin are vertically integrating propulsion production to control cost and schedule.
- Research Institutions:University and laboratory missions with constrained budgets and simplified payload requirements.
- Space Agencies:Intergovernmental organizations with multinational procurement processes and technology transfer obligations.
Government agencies anchor procurement volume; private companies are expanding most quickly on contract count.
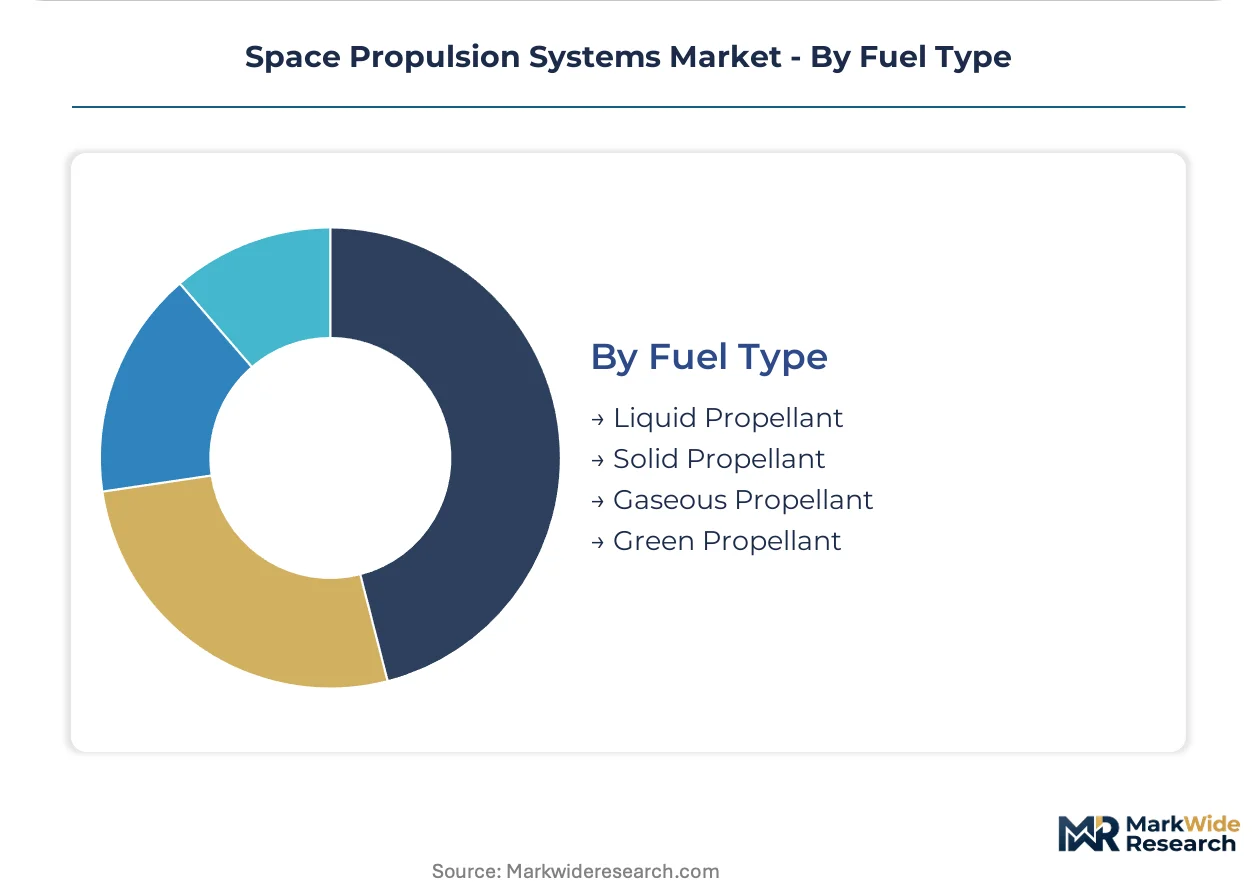
Fuel Type:
Environmental compliance is restructuring fuel selection, with toxicity regulations accelerating displacement of hydrazine-based systems.
- Liquid Propellant:Pump-fed or pressure-fed systems using cryogenic or storable liquids enabling throttleable thrust and engine restart. ArianeGroup's Vulcain and Vinci engines demonstrate European capability in cryogenic liquid hydrogen/oxygen architectures.
- Solid Propellant:Cast composite grain formulations providing high thrust density and storage stability without cryogenic infrastructure. Northrop Grumman dominates strategic defense applications through inert motor production for missile and launch vehicle boosters.
- Gaseous Propellant:Cold-gas and warm-gas systems for precision attitude control on small satellites and reaction control subsystems.
- Green Propellant:Non-toxic alternatives including LMP-103S and AF-M315E replacing hydrazine for ground-handling safety. EPA National Emission Standards for Hazardous Air Pollutants are accelerating infrastructure investment at Cape Canaveral and Vandenberg.
Liquid propellant retains the largest installed base; green propellant is climbing the fastest on regulatory mandate strength.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity, absorbing premium costs for flight-proven heritage systems, while emerging space nations in Asia-Pacific exhibit acute sensitivity to unit economics and qualification timelines.
United States
Space Force national security launch contracts and venture-backed reusable launch vehicle programs drive procurement of refurbishment-capable propulsion modules. FAA launch licensing requirements and EPA National Emission Standards for Hazardous Air Pollutants elevate compliance costs for hydrazine ground-handling. Cape Canaveral and Vandenberg Space Force Base host concentrated test infrastructure and green propellant loading investments.
France
Ariane 6 propulsion architecture sustains European heavy-lift capacity through cryogenic engine production anchored at Vernon and Le Haillan. ESA REACH-aligned propellant restrictions accelerate qualification of ammonium dinitramide-based alternatives. The Paris-Saclay aerospace cluster concentrates ArianeGroup engineering and supplier integration activity.
Japan
IHI Corporation and JAXA steer investment toward HTV-X resupply vehicle propulsion and commercial launch vehicle development. METI technology roadmaps prioritize electric thruster miniaturization for small satellite constellations. The Tanegashima and Uchinoura space centers anchor domestic launch infrastructure with expanding private sector access.
India
ISRO's commercial launch vehicle development and IN-SPACe private participation frameworks open procurement channels for foreign propulsion suppliers. The country's national space regulator establishes qualification protocols for indigenized cryogenic and semi-cryogenic engines. The Sriharikota spaceport and emerging Ahmedabad-Gandhinagar aerospace corridor concentrate manufacturing and test activities.
Germany
Airbus Defence and Space and OHB System anchor satellite bus integration demand for electric and chemical thruster procurement. ESA technology programs administered from Darmstadt and Noordwijk steer R&D toward flight-qualified green propulsion architectures. The Bremen-Ottobrun aerospace cluster concentrates propulsion subsystem engineering and Arianespace launch operations support.
Space Propulsion Systems Market Key Industry Players
Defense-heritage conglomerates and commercial launch specialists split the market along mission-assurance versus cost-per-kilogram fault lines. The vendor base concentrates around three strategic archetypes: integrated prime contractors controlling end-to-end satellite and launch vehicle production; specialized propulsion houses supplying thruster subsystems to multiple platform integrators; and venture-backed newcomers attacking the small satellite and reusable launch segments. Dominant competitive moves include backward integration into engine production by launch service providers and strategic partnerships between electric thruster developers and constellation operators for multi-year service agreements.
Among defense-heritage conglomerates, Northrop Grumman Corporation exemplifies the solid rocket motor specialist archetype, while L3Harris Technologies, Inc. occupies a position within the integrated mission systems tier. ArianeGroup GmbH anchors the European prime contractor segment. These three represent contrasting strategic postures: captive production for strategic defense programs, long-term service contracting with government end users, and transnational launch infrastructure stewardship respectively.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| ArianeGroup GmbH |
| Northrop Grumman Corporation |
| Moog Inc. |
| IHI Corporation |
| Safran SA |
| Airbus SE |
| Dawn Aerospace |
| Thales Alenia Space |
| Others |
Cost & Logistics Intelligence
Vernon and Le Haillan anchor European cryogenic engine production capacity, concentrating supply-side leverage for ArianeGroup's Vulcain and Vinci architectures while downstream pricing power accrues to flight-qualified suppliers with heritage certification. This geographic concentration of liquid hydrogen/oxygen expertise shapes procurement economics across heavy-lift launch segments.
Pricing Analysis
Thruster refurbishment and propellant reloading service contracts now drive lifetime value capture, displacing pure equipment sales. Pricing stratifies across flight-proven heritage tiers, with NASA and ESA qualification status commanding substantial premiums over commercial-grade alternatives. Cost compression in small satellite propulsion stems from standardized Hall-effect thruster platforms displacing custom chemical designs. Research institutions and university missions exhibit acute price sensitivity, while Space Force national security launch contracts absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Xenon feedstock refining concentrates in Russia and South Africa, exposing electric thruster manufacturers to geopolitical supply interruptions. Propulsion system production draws from specialized vacuum chamber facilities, precision-machined combustion chambers, and high-purity propellant formulations. Single-source vulnerability runs through South African xenon capacity and Russian noble gas exports. Distribution runs through prime contractor integration channels and direct constellation operator procurement, with service-based contracts unbundling hardware from operational support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Space propulsion markets track launch cycle recovery, with reusable launch vehicle program cadence and satellite constellation deployment schedules serving as the primary cyclical driver.
For Market Incumbents: Build certification heritage moats through accelerated on-orbit demonstration programs to compress ESA and NASA qualification timelines. Anchor capacity addition in United States Space Force procurement corridors and European Ariane 6 supply chains. Defensive consolidation should prioritize captive xenon storage agreements and green propellant loading infrastructure investments to neutralize supply interruption threats and EPA compliance cost escalation. For New Entrants and Emerging Players: India's IN-SPACe private participation frameworks and ISRO commercial launch vehicle development represent the most penetrable entry point for foreign propulsion suppliers seeking qualification pathway access. Small satellite electric thruster miniaturization for LEO broadband constellations offers secondary white-space targeting. Go-to-market positioning should emphasize modular, refillable architectures aligned with emerging orbital propellant depot demand. For Investors and Strategic Acquirers: Long-term, this sits as a defense-civil convergence play because missile defense interceptor propulsion and satellite maneuvering systems increasingly share component architectures. Acquisition targets should concentrate on specialized plasma physics and combustion engineering talent pools with dual-use technology portfolios. Monitor Space Force multi-year service agreement negotiations as the inflection signal for performance-guaranteed contract adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Green Propellant Infrastructure Investment | EPA National Emission Standards compliance at Cape Canaveral and Vandenberg accelerates LMP-103S and AF-M315E adoption. |
| Xenon Supply Security Agreements | Long-term offtake contracts with South African and Russian refiners mitigate geopolitical interruption exposure for Hall-effect thruster production. |
| Heritage Certification Acceleration | Compressed ESA and NASA on-orbit demonstration timelines unlock procurement approval for next-generation electric architectures. |
| Service-Based Revenue Unbundling | Thrust-hour contracting with Space Force and commercial LEO operators displaces traditional equipment sales channels. |
| Dual-Use Technology Convergence | Missile defense interceptor and satellite maneuvering system component sharing enables cross-program economies of scale. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade data, and technical literature. Interviews with propulsion subsystem engineers, satellite bus procurement leads, launch vehicle program managers, and space agency technology directors informed demand-side dynamics. Secondary validation drew from FAA launch licensing records, ESA procurement standards, NASA In-Space Propulsion Technology program documentation, and customs trade data for xenon and specialty propellant flows. Bottom-up unit economics and top-down market sizing underwent iterative triangulation.
Forecast inputs span technology adoption curves across chemical, electric, hybrid, and nuclear thermal architectures; application segmentation by satellite launch, space exploration, orbital maneuvering, and interplanetary missions; end-user procurement protocols distinguishing government agency heritage requirements from private operator cost-per-kilogram metrics; and fuel type transitions from hydrazine to green propellant alternatives. CAGRs were derived from installed base growth, replacement cycle analysis, and regulatory mandate acceleration effects across the projection horizon.
Practitioners should monitor ESA REACH-aligned propellant restriction implementation timelines, Space Force national security launch contract award cadence, and xenon supply chain disruption indicators for early signals of forecast revision. Cross-checking against FAA launch licensing volume trends and satellite constellation operator procurement announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
LAMEA Space As a Service Market
Space
Space Blanket Market
Space
Private Space Travel Market
Space
Space Debris Monitoring and Removal Market
Space
Africa Space Electronics Market
Space
Space Service Market
Space
India Space Electronics Market
Space
Space-Based Solar Power Market
Space
Space Robots Market
Space
Space Frame Market
Space
North America Spacesuit Market
Space
Asteroid Mining Market
Space
Canada Space Electronics Market
Space
Space Battery Market
Space
Astronaut Spacesuit Market
Space
Asia-Pacific Space Electronics Market