
 Space Tourism Market | 2026-2036
Space Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Space Tourism Market Intelligence
Reusable rocket propulsion is reconfiguring spacecraft economics and flight cadence for tourism operators. Blue Origin leverages vertical landing architectures to sustain rapid turnaround between suborbital passenger missions. SpaceX anchors orbital tourism through its Crew Dragon platform, while Virgin Galactic competes with air-launch systems designed for runway flexibility.
Space tourism encompasses commercial passenger travel beyond Earth's atmosphere, typically reaching altitudes above the Kármán line at 100 kilometers for suborbital experiences or achieving sustained orbital velocity for multi-day missions. Reusable rockets and space capsules constitute the primary technology platforms, with thermal protection systems and life support infrastructure determining operational safety margins. Suborbital flights currently dominate transaction volumes due to lower technical barriers and compressed development timelines. Orbital flights command premium pricing tiers and attract researcher and corporate customer segments seeking extended microgravity exposure. Space hotels represent an emerging segment where habitat technology maturity will dictate market timing.
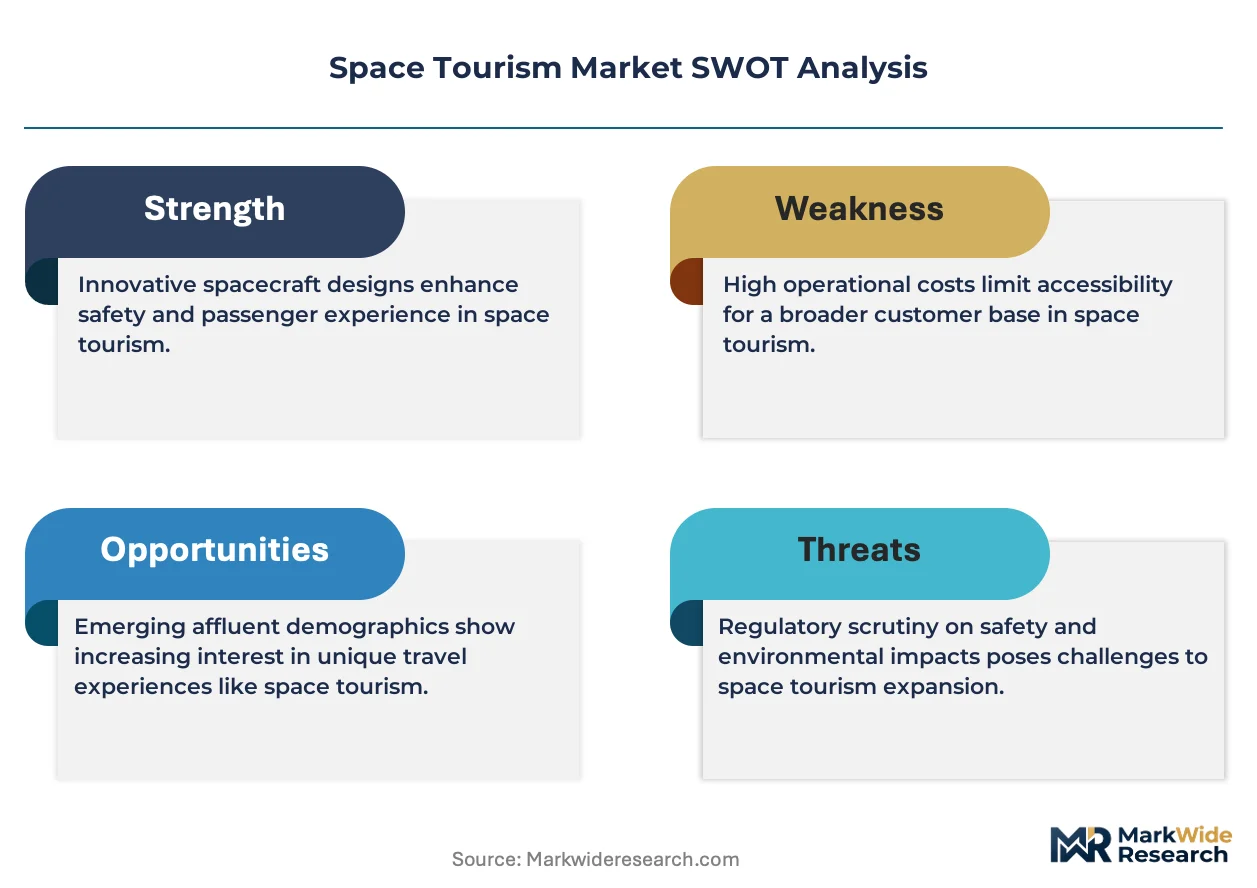
The FAA Office of Commercial Space Transportation governs launch licensing and passenger safety protocols for US operators, while the International Space Station Intergovernmental Agreement shapes orbital destination access. NASA's Commercial Low Earth Orbit Development Program is transitioning station operations toward private platforms, directly expanding addressable destinations for tourism providers. Stakeholders must monitor how orbital debris mitigation standards and passenger informed-consent frameworks evolve, as these will determine insurance structures and operational boundaries.
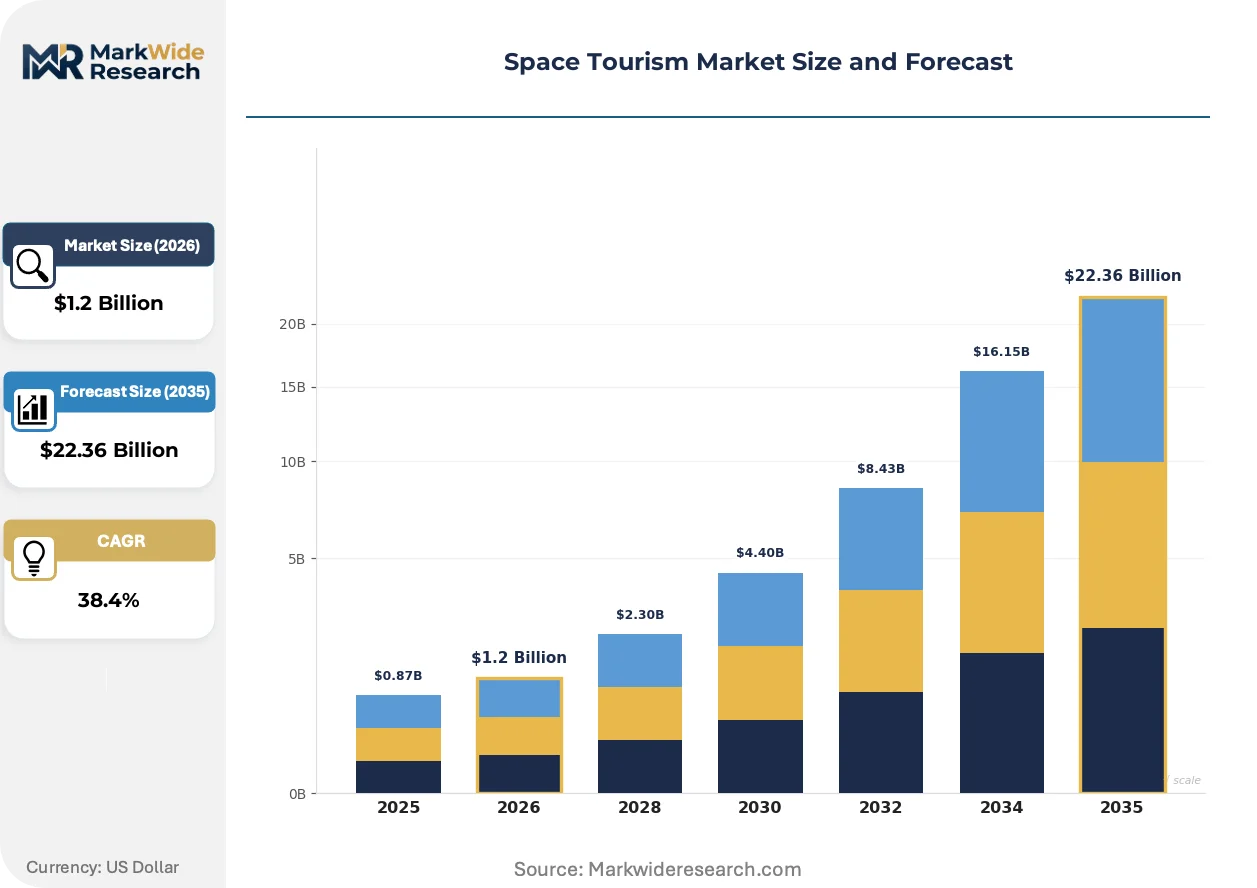
Market Dynamics
Reusable propulsion architectures are compressing per-launch economics and compressing turnaround cycles, fundamentally restructuring how tourism operators scale seat inventory and flight cadence.
Growth Catalysts
- FAA Commercial Space Licensing:Streamlined launch authorization frameworks in the United States reduce regulatory friction for new entrants seeking operational clearance.
- High-net-worth leisure travelers:This customer segment is expanding fastest as orbital experiences become accessible, driving demand for premium suborbital and multi-day missions.
- Thermal protection systems:Advances in reusable heat shield materials are extending vehicle lifecycle economics and improving safety margins for repeated atmospheric reentries.
Market Restraints
- Launch site concentration:Operational dependency on a limited number of coastal facilities creates geographic bottlenecks and weather-related scheduling vulnerabilities.
- Life support infrastructure costs:Pressurized cabin systems, oxygen regeneration, and waste management equipment impose fixed cost burdens that resist scale economies.
- Orbital debris mitigation standards:Emerging collision avoidance protocols and end-of-life disposal requirements add compliance layers and insurance complexity.
Strategic Opportunities
- Space hotel habitats:Modular orbital accommodation platforms represent unaddressed white space where habitat technology maturity will unlock extended-stay revenue models.
- Corporate research missions:Microgravity manufacturing and pharmaceutical development applications are creating B2B demand streams beyond leisure tourism.
- Air-launch flexibility:Runway-based deployment systems reduce weather dependency and open inland operational bases currently unserved by vertical launch infrastructure.
Industry Challenges
- Astronaut training standardization:No unified medical certification or preparation protocol exists across operators, creating customer friction and liability exposure.
- Passenger informed-consent frameworks:Evolving legal standards for risk disclosure and liability waiver enforceability vary across jurisdictions, complicating cross-border booking.
- Vehicle integration complexity:Crew capsule-to-booster mating systems require precision engineering that extends pre-flight processing timelines and demands specialized ground crews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Tourism Market |
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $22.36 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Suborbital Flights, Orbital Flights, Space Hotels, Lunar Tourism Customer Type: Leisure Travelers, Adventurers, Researchers, Corporates Pricing Model: All-Inclusive Packages, Pay-Per-Flight, Membership Plans, Auctions Technology: Reusable Rockets, Space Capsules, Habitats, Launch Systems |
| Companies Covered | Space Adventures, Sierra Space, Virgin Galactic, Bigelow Aerospace, Orbital Assembly Corporation, Blue Origin, Axiom Space, Space Perspective, SpaceX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Tourism Market Strategic Shifts & Innovations
Propulsion economics, regulatory frameworks, and customer segmentation are converging to reshape how tourism providers structure offerings and price access to orbital and suborbital experiences.
Hybrid rocket motor technology is hybridizing propulsion architectures by combining solid fuel reliability with liquid oxidizer throttling precision. Suborbital operators are adopting these systems to enable abort capabilities and variable thrust profiles during passenger ascent. This convergence is hybridizing vehicle design tradeoffs that previously forced binary choices between simplicity and controllability.
The FAA Office of Commercial Space Transportation is expanding its safety inspection protocols and experimental permit frameworks for reusable vehicles. These regulatory refinements are clarifying liability boundaries and accelerating the transition from developmental to operational licensing phases. US-based operators are responding by front-loading certification documentation and establishing dedicated regulatory affairs functions.
Corporate buyers are unbundling research missions from traditional government procurement channels and contracting directly with commercial providers for dedicated microgravity access. Pharmaceutical and materials science divisions are displacing legacy payload allocation models that required multi-year queue positions on government platforms. This purchasing shift is most pronounced among North American and European life sciences firms seeking iterative experiment cadences.
Space Tourism Market Segmentation
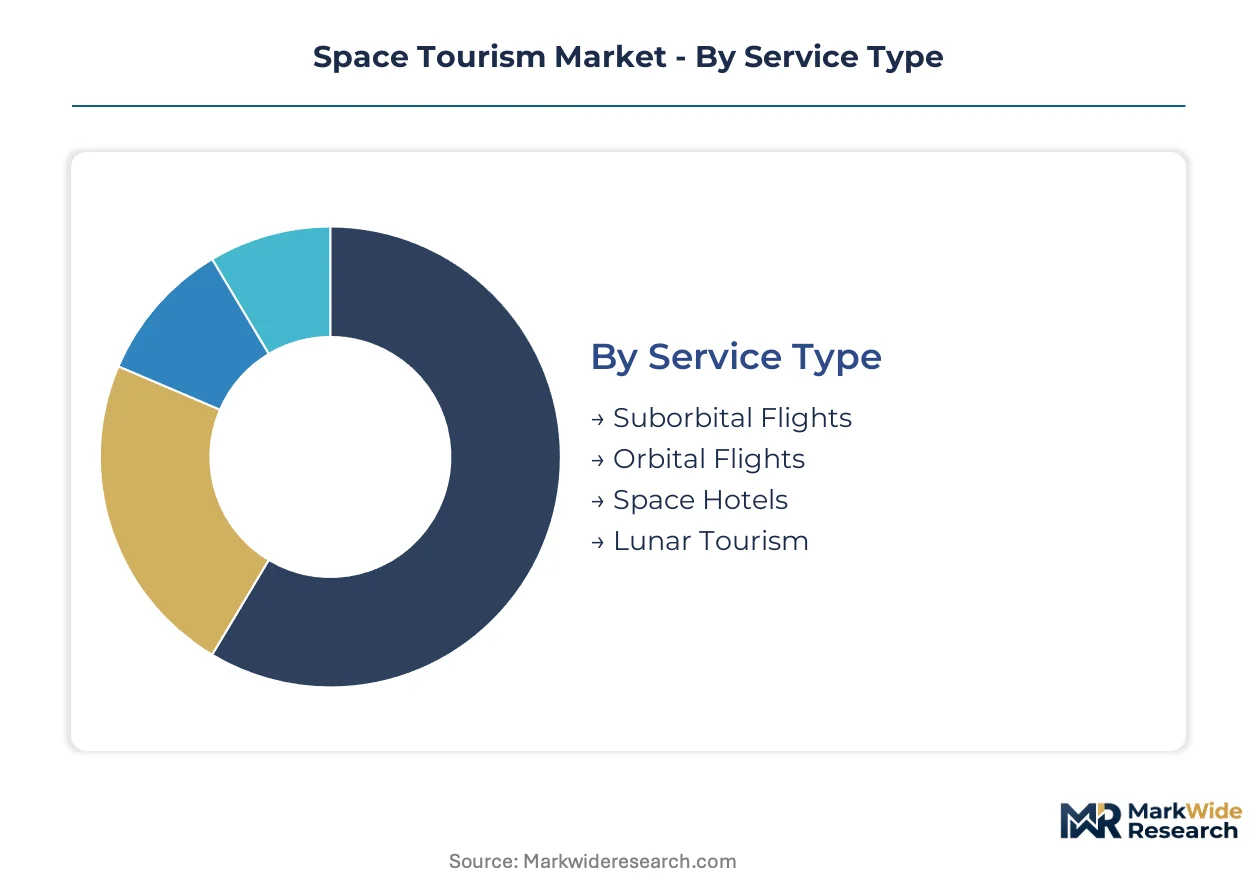
Segmentation in space tourism reveals how operators balance technical complexity against customer willingness to pay. Each dimension—service altitude, buyer motivation, payment structure, and vehicle platform—creates distinct operational requirements and margin profiles that shape provider strategy.
Service Type:
The use-case spectrum spans brief suborbital experiences to multi-week orbital habitation, with each tier demanding exponentially greater propulsion energy and life support infrastructure.
- Suborbital Flights:These missions reach the Kármán line at 100 kilometers altitude for several minutes of weightlessness before atmospheric reentry. Demand concentrates among high-net-worth leisure travelers in the United States seeking accessible entry points, constrained by limited daily flight cadence from coastal launch sites.
- Orbital Flights:Crew Dragon and similar platforms achieve sustained orbital velocity for multi-day missions to the International Space Station or private destinations. Research institutions and corporate buyers in North America drive bookings, limited by vehicle availability and astronaut training timelines.
- Space Hotels:Modular orbital accommodation platforms remain in development, with habitat technology maturity dictating market timing and regulatory clearance for extended-stay operations.
- Lunar Tourism:Circumlunar trajectories and surface missions represent the frontier tier, requiring heavy-lift propulsion and deep-space life support systems not yet commercially operational.
The dominant share belongs to Suborbital Flights, while Orbital Flights is closing the gap fastest as reusable vehicle economics improve.
Customer Type:
Cost tier stratification separates recreational impulse buyers from institutional procurement budgets with multi-year planning horizons.
- Leisure Travelers:Individuals purchasing experiences for personal milestone celebration or status signaling. United States-based ultra-high-net-worth individuals dominate this segment, with booking windows extending 12-24 months due to training requirements.
- Adventurers:Extreme experience seekers prioritizing physical challenge and risk exposure over comfort. This cohort accepts abbreviated training protocols and higher physical fitness standards in exchange for reduced pricing.
- Researchers:Academic and government scientists requiring dedicated microgravity access for experiment iteration. European and North American universities are displacing legacy payload allocation models with direct commercial contracting.
- Corporates:Pharmaceutical and materials science divisions seeking iterative manufacturing process development. Life sciences firms in Switzerland and Germany are expanding fastest among this buyer type.
Leisure Travelers command the largest transaction volume, though Corporates are expanding most quickly as B2B applications mature.
Pricing Model:
Payment structure innovation is concentrating around subscription mechanics and dynamic allocation systems that maximize seat utilization.
- All-Inclusive Packages:Bundled offerings covering training, flight, accommodation, and insurance. These dominate the premium tier where customers prioritize convenience over cost optimization.
- Pay-Per-Flight:Single-transaction pricing for specific missions. This model attracts occasional buyers and gift purchasers with lower commitment thresholds.
- Membership Plans:Annual or multi-year subscriptions securing priority queue positions and discounted per-flight rates. Operators in the United States are piloting these structures to improve revenue predictability.
- Auctions:Dynamic price discovery for limited high-demand inventory. Blue Origin and competitors have deployed this mechanism for inaugural seats and celebrity passenger missions.
All-Inclusive Packages retain the largest revenue share, while Membership Plans are gaining traction fastest among repeat-customer development strategies.
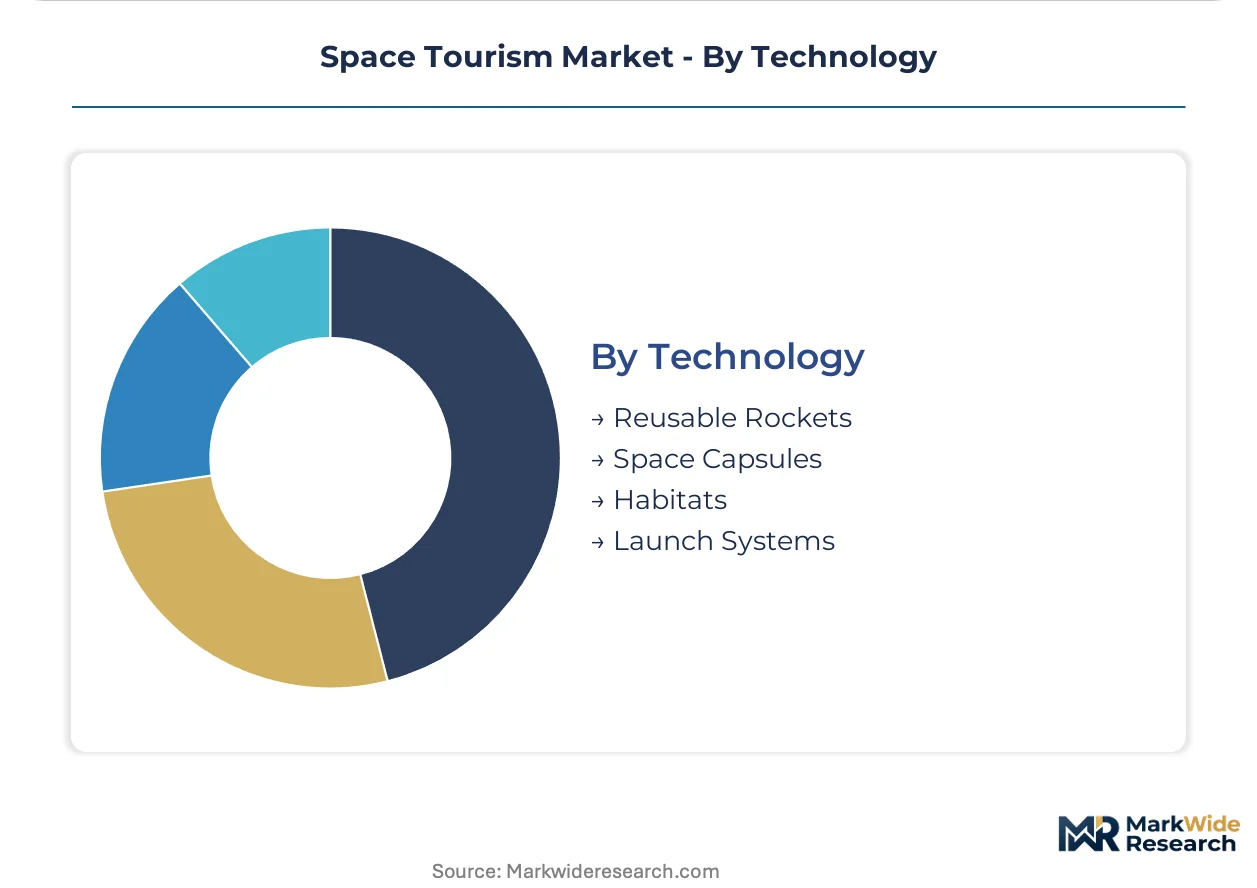
Technology:
Platform maturity determines which providers can compress turnaround cycles and extend vehicle lifecycle economics.
- Reusable Rockets:Vertical landing architectures from SpaceX and Blue Origin enable rapid reuse. These systems anchor suborbital and orbital tourism economics through per-launch cost reduction.
- Space Capsules:Crew-rated pressure vessels with integrated life support and thermal protection. Crew Dragon represents the operational benchmark for orbital passenger transport.
- Habitats:Modular orbital accommodation systems including sleeping quarters, exercise equipment, and research facilities. Axiom Space and Orbital Assembly are advancing prototypes toward operational status.
- Launch Systems:Air-launch platforms from Virgin Galactic and similar operators provide runway flexibility. These reduce weather dependency and open inland operational bases unserved by vertical infrastructure.
Reusable Rockets hold the dominant platform position, though Habitats are advancing fastest as space hotel construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth leisure travelers concentrate in the United States, Germany, and the United Arab Emirates, with each geography presenting distinct regulatory pathways and infrastructure maturity levels for commercial spaceflight operators.
United States
High-net-worth individuals in California, Texas, and Florida drive suborbital booking volumes, with demand concentrated around milestone celebration and status signaling. The FAA Office of Commercial Space Transportation governs launch licensing and passenger safety protocols, streamlining operational clearance for reusable vehicle operators. Coastal launch sites in Florida and Texas anchor commercial activity, while SpaceX's Crew Dragon platform sustains orbital tourism economics through rapid turnaround cycles.
Germany
Corporate research buyers in pharmaceutical and materials science divisions represent the fastest-expanding customer segment, displacing legacy government payload allocation models. The country's national space regulator aligns with ESA frameworks for orbital destination access and debris mitigation standards. Industrial clusters in Bavaria and Baden-Württemberg host life sciences firms contracting directly with commercial providers for iterative microgravity experiment cadences.
United Arab Emirates
Luxury leisure travelers in Dubai and Abu Dhabi seek premium orbital experiences as accessible entry points into space tourism. The country's national commercial space regulator is developing informed-consent frameworks and liability waiver enforceability standards for cross-border booking. Dubai's hospitality infrastructure is piloting pre-flight training facilities and astronaut preparation programs adjacent to existing luxury tourism corridors.
Japan
Research institutions and academic scientists requiring dedicated microgravity access are expanding commercial contracting beyond traditional government channels. METI shapes industrial policy for private space station development and orbital habitat technology maturation. The Kanto region around Tokyo concentrates aerospace engineering talent and corporate headquarters for firms evaluating B2B mission procurement.
United Kingdom
Adventurer archetype buyers accepting abbreviated training protocols and higher physical fitness standards are emerging as a price-sensitive demand cohort. The UK Space Agency coordinates with international frameworks for passenger safety certification and cross-border operational licensing. Scotland's vertical launch sites and Cornwall's horizontal launch capabilities are developing complementary infrastructure for suborbital and small-satellite tourism applications.
Space Tourism Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers. Vertically integrated operators with reusable rocket platforms command premium pricing and rapid flight cadence, while air-launch specialists and habitat developers occupy specialized niches with distinct operational economics. Three strategic archetypes dominate: propulsion-integrated platform operators, experience-focused suborbital providers, and orbital infrastructure developers. Competitive moves concentrate on capacity expansion through vehicle fleet scaling and strategic partnerships for destination access.
Within the integrated platform tier, SpaceX and Blue Origin exemplify the propulsion-economics archetype through vertical landing architectures and rapid reuse capabilities. Virgin Galactic occupies a distinct position among air-launch specialists, leveraging runway flexibility to reduce weather dependency and open inland operational bases. Axiom Space represents the orbital infrastructure vector, advancing modular habitat prototypes toward commercial space hotel operations.
| Leading Market Players |
|---|
| Space Adventures |
| Sierra Space |
| Virgin Galactic |
| Bigelow Aerospace |
| Orbital Assembly Corporation |
| Blue Origin |
| Axiom Space |
| Space Perspective |
| SpaceX |
| Others |
Cost & Logistics Intelligence
Florida's Space Coast logistics corridor compresses payload transport costs for vertical launch operators, concentrating supply-side leverage among coastal facility owners and forcing three-tier pricing stratification across suborbital, orbital, and extended-stay mission tiers.
Pricing Analysis
Cost-plus contracts with aluminum-lithium alloy indexation dominate reusable vehicle procurement, anchoring baseline mission economics. Price differentiation separates FAA-certified orbital platforms from experimental permit suborbital systems, with thermal protection system refurbishment cycles driving tier boundaries. Cost compression in suborbital tourism intensifies as air-launch alternatives expand inland operational bases. Adventurer archetype buyers exhibit highest price sensitivity, while corporate research divisions accept premium orbital rates for dedicated microgravity access.
Supply Chain Analysis
Export control regimes under ITAR and EAR restrict thermal protection system composites and cryogenic propulsion components from flowing to non-US entities, fragmenting supplier networks. Manufacturing concentrates in the United States, Germany, and Japan for precision propulsion hardware. Supply chains draw from titanium forgings, carbon-fiber pressure vessels, and regenerative life support subassemblies. Single-source vulnerability pervades crew-rated capsule production. Distribution runs through direct operator-to-customer contracting with minimal intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable propulsion economics represent a high-growth disruption, with FAA operational licensing transitions compressing developmental-to-commercial timelines for qualified operators.
For Market Incumbents: Entrench rapid turnaround capabilities through captive refurbishment facilities at coastal launch sites, defending against air-launch entrants seeking inland operational flexibility. Pursue backward integration into thermal protection system recoating operations to capture margin currently flowing to specialized subcontractors. Lock in multi-year corporate research contracts before habitat platforms expand addressable destination supply.
For New Entrants and Emerging Players: Build out runway-based deployment systems targeting weather-constrained coastal markets, penetrating price-sensitive adventurer segments underserved by vertical launch bottlenecks. Prioritize abbreviated training protocols as a go-to-market wedge against incumbent 12-24 month preparation timelines. Target corporate pharmaceutical buyers in Germany and Switzerland with iterative microgravity experiment cadences.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors habitat developers with NASA Commercial Low Earth Orbit Development Program partnerships over pure-launch operators facing seat oversupply. Long-term viability rests on destination scarcity rather than transportation commoditization. Watch for FAA informed-consent framework finalization as the signal distinguishing operational-ready platforms from developmental-stage liabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Vehicle Fleet Expansion | SpaceX Crew Dragon rapid turnaround compresses per-seat economics and extends flight cadence for orbital tourism operators. |
| Orbital Habitat Construction | Axiom Space modular platforms unlock extended-stay revenue models beyond current ISS destination constraints. |
| Air-Launch System Deployment | Virgin Galactic runway flexibility reduces weather dependency and opens inland operational bases unserved by vertical infrastructure. |
| Corporate Research Mission Contracting | Direct pharmaceutical and materials science procurement displaces legacy government payload allocation queues. |
| Regulatory Certification Investment | FAA operational licensing transitions accelerate market access while experimental permit holders face extended developmental timelines. |
Research Approach
Operator-level perspectives from launch vehicle program managers, spaceport facility directors, astronaut training providers, and commercial habitat developers anchored the qualitative base. Primary interviews combined with secondary validation against FAA licensing databases, NASA procurement disclosures, and ESA framework documents. Bottom-up seat inventory modeling and top-down addressable wealthy population triangulation cross-checked volume assumptions.
Scenario bracketing across reusable vehicle turnaround rates, habitat technology maturation timelines, and regulatory clearance velocities shaped the analytical framework. Segmentation dimensions modeled include service altitude tier, customer motivation archetype, pricing structure, and vehicle platform type. CAGRs derived from seat capacity expansion curves and willingness-to-pay elasticity functions, with propulsion cost trajectories and life support infrastructure scaling as primary forecast inputs across the projection horizon.
Stress conditions across launch site weather interruption frequencies, astronaut training completion rates, and orbital debris mitigation compliance costs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding FAA regulatory trajectory and reusable vehicle reliability maturation. Material shifts in international space station privatization timelines or passenger informed-consent liability rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
India Space Electronics Market
Space
Rocket Launchpad Market
Space
Asia-Pacific Space Electronics Market
Space
Space Ground System Market
Space
Space As a Service Market
Space
India Aviation, Defense, and Space Market
Space
Carrier Rocket Market
Space
Space Robots Market
Space
Space Robotics Market
Space
UK Space Electronics Market
Space
Space Mobile Service Market
Space
Space Traffic Management Market
Space
Space Burial Service Market
Space
LAMEA Space As a Service Market
Space
Orbital Spaceflight Market
Space
Space in Orbit Refueling Market