
 Space Debris Monitoring Market | 2026-2036
Space Debris Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Space Debris Monitoring Market Analysis
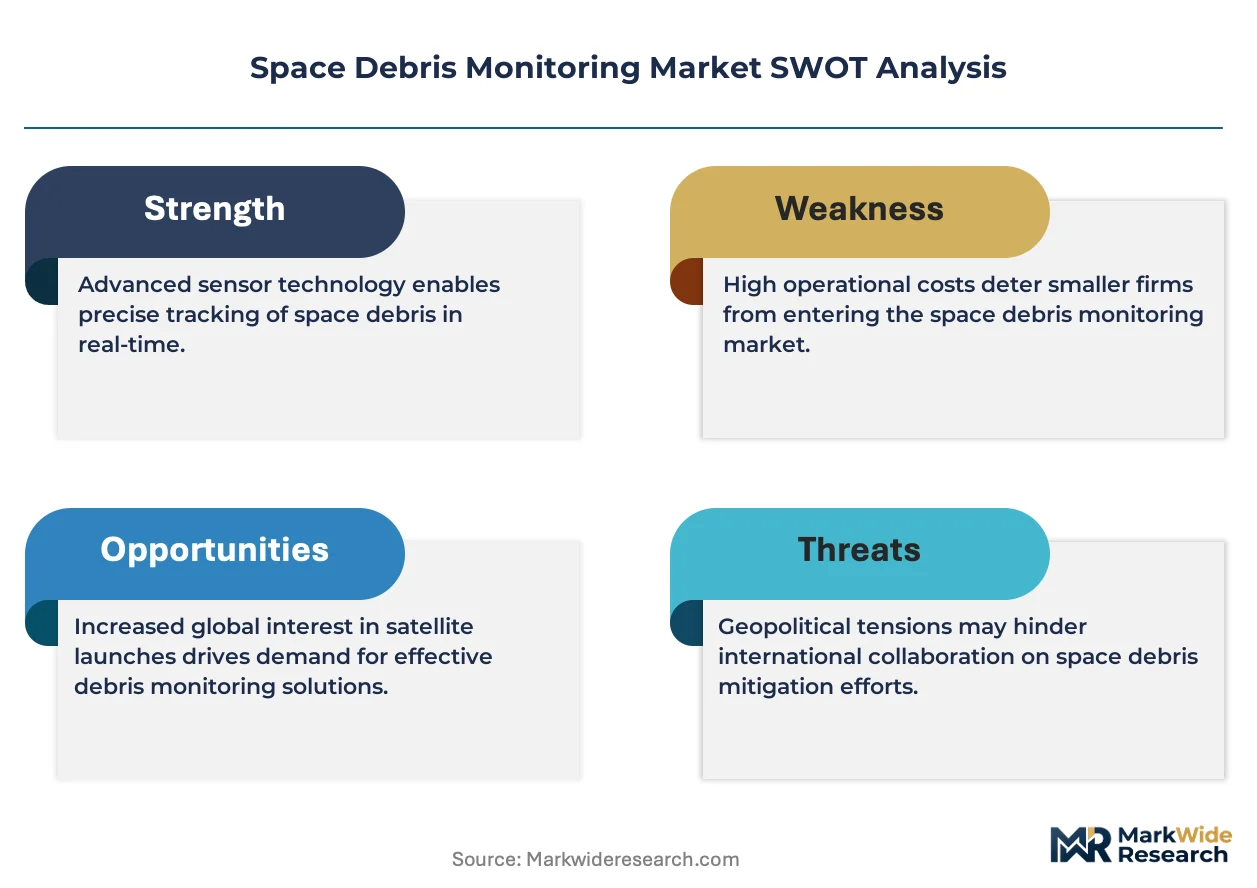
Astrophysicist and radar engineer talent scarcity is bifurcating the competitive landscape into capital-heavy incumbents and niche specialists. Lockheed Martin Corporation leverages decades of defense sensor integration to dominate high-resolution orbital tracking contracts. Electro Optic Systems anchors its position through ground-based laser ranging stations spanning three continents. LeoLabs competes by operating the largest commercial radar network dedicated to low-Earth orbit cataloging.
Space debris monitoring encompasses the detection, tracking, characterization, and predictive analysis of artificial objects orbiting Earth, including defunct satellites, spent rocket bodies, and fragmentation debris down to centimeter-scale dimensions, using phased-array radar with sub-degree precision and electro-optical telescopes with adaptive optics correction. Its primary purpose is to prevent catastrophic collisions that threaten operational spacecraft and human spaceflight missions. Radar Systems currently occupy the largest technology share due to all-weather operational reliability and mature signal-processing chains. Optical Sensors represent the fastest-expanding segment as charge-coupled device arrays and photon-counting detectors drive resolution improvements for geostationary regime coverage. Mission Planning applications concentrate margin pools because operators pay premiums for conjunction assessment integrated directly into maneuver optimization workflows.
The U.S. Federal Communications Commission now mandates debris disclosure for all new satellite licenses, while the European Space Agency's Space Debris Mitigation Guidelines shape procurement standards across member state programs. Japan's Cabinet Office coordinates national debris tracking through METI-funded radar upgrades and bilateral data-sharing protocols with U.S. Space Command. Stakeholders must decide whether to build proprietary sensor networks or subscribe to commercial catalogs as orbital traffic management transitions from government monopoly to hybrid public-private architecture.
Market Dynamics
The U.S. Federal Communications Commission's orbital debris mitigation rules are compressing compliance timelines for satellite operators, forcing rapid procurement of tracking infrastructure and predictive analytics platforms.
Growth Catalysts
- Constellation Deployment Surge:Satellite constellation operators now require continuous debris monitoring for collision avoidance as launch cadence multiplies across low-Earth orbit regimes.
- FCC Debris Disclosure Mandates:The U.S. Federal Communications Commission now requires debris impact assessments for all new satellite licenses, creating binding demand for characterization services.
- Phased-Array Radar Maturation:All-weather operational reliability and mature signal-processing chains are expanding deployable sensor networks for centimeter-scale object detection.
Market Restraints
- Specialized Talent Scarcity:Astrophysicist and radar engineer shortages limit network expansion velocity and drive compensation inflation for qualified personnel.
- Sensor Hardware Concentration:High-resolution orbital tracking radar production concentrates among defense-integrated suppliers, creating procurement bottlenecks for commercial buyers.
- Optical Sensor Weather Dependency:Electro-optical telescope systems face operational interruptions from cloud cover and atmospheric turbulence, constraining all-hours coverage.
Strategic Opportunities
- Geostationary Orbit Coverage Gap:Charge-coupled device arrays and photon-counting detectors enable resolution improvements for geostationary regime monitoring where radar returns weaken.
- Japan's METI-Funded Infrastructure:The country's Cabinet Office coordinates national debris tracking through bilateral data-sharing protocols with U.S. Space Command, opening partnership pathways.
- Mission Planning Integration:Conjunction assessment tools embedded directly into maneuver optimization workflows command premium pricing from satellite operators seeking unified platforms.
Industry Challenges
- Adaptive Optics Calibration Complexity:Ground-based telescope networks require continuous atmospheric distortion correction, demanding specialized maintenance crews and extending deployment timelines.
- Hybrid Architecture Transition Friction:Orbital traffic management shifts from government monopoly to public-private models, creating data-sharing standardization disputes between military and commercial catalog providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Debris Monitoring Market |
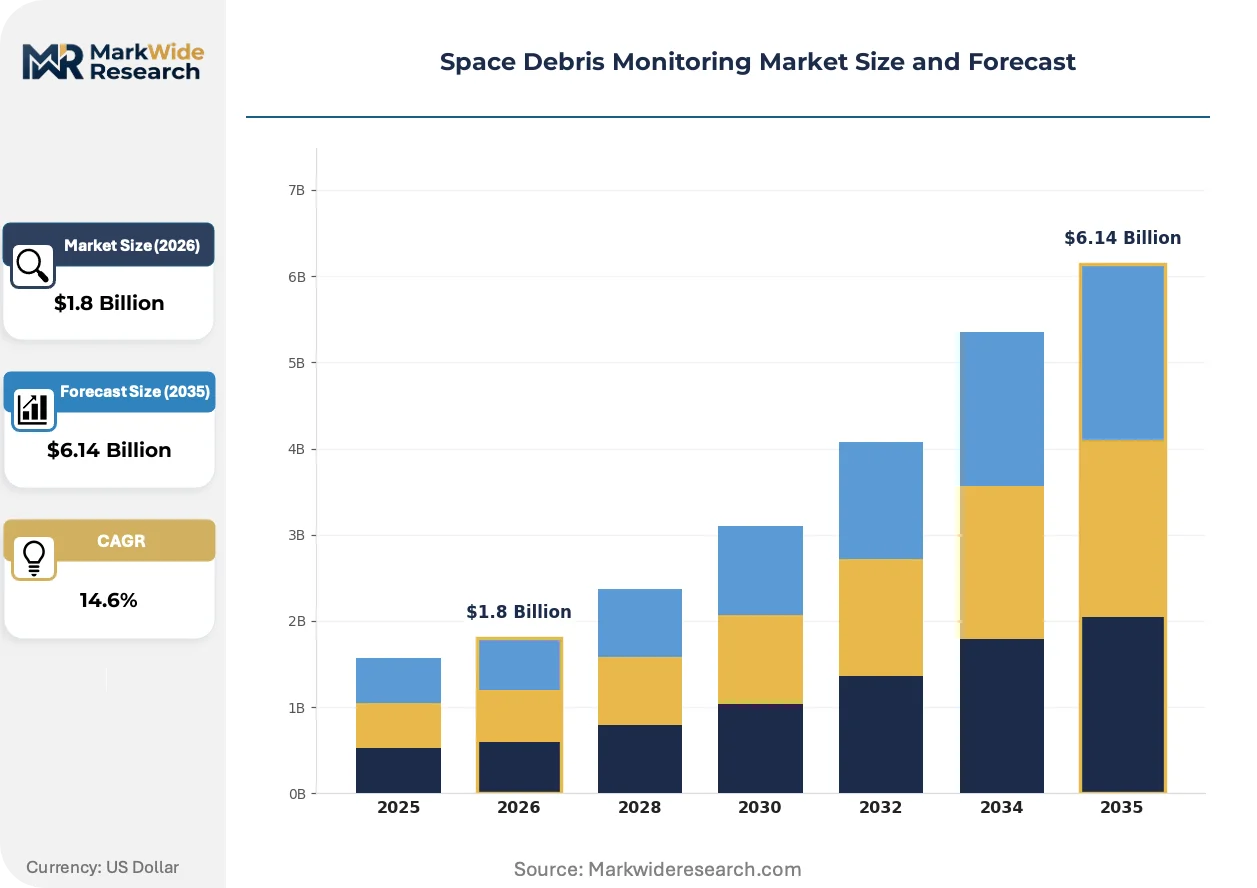
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Tracking Services, Analysis Services, Data Management, Reporting Services End User: Government Agencies, Research Organizations, Commercial Operators, Defense Technology: Radar Systems, Optical Sensors, Simulation Software, Ground Stations Application: Collision Avoidance, Risk Assessment, Mission Planning, Spacecraft Safety |
| Companies Covered | Altius Space Machines, Electro Optic Systems, Airbus SAS, Northrop Grumman Corporation, Lockheed Martin Corporation, Astroscale Holdings, D-Orbit, LeoLabs, ClearSpace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Debris Monitoring Market Emerging Trajectories
Sensor fusion architectures and autonomous tracking algorithms are compressing detection-to-alert timelines, reshaping how operators manage collision risk across proliferating orbital traffic.
Photon-counting detector arrays are supplanting traditional charge-coupled devices in geostationary monitoring stations. Satellite operators with assets above 35,786 kilometers now specify single-photon sensitivity for debris characterization. This transition is compressing the minimum detectable object size while extending operational range for optical ground stations.
Europe's Space Debris Mitigation Guidelines are hardening into procurement standards across member state programs. The European Space Agency mandates debris impact disclosure for institutional missions, forcing prime contractors to integrate third-party tracking data into mission assurance packages. Small satellite manufacturers in Germany and France now pre-qualify debris monitoring subscriptions before launch manifesting.
Subscription-based catalog access is displacing perpetual license purchases among emerging constellation operators. New entrants favor usage-tiered data feeds over capital-intensive proprietary sensor networks. This preference shift concentrates most visible in the United States, where venture-backed launch services prioritize operational expenditure flexibility over infrastructure ownership.
Space Debris Monitoring Market Segmentation
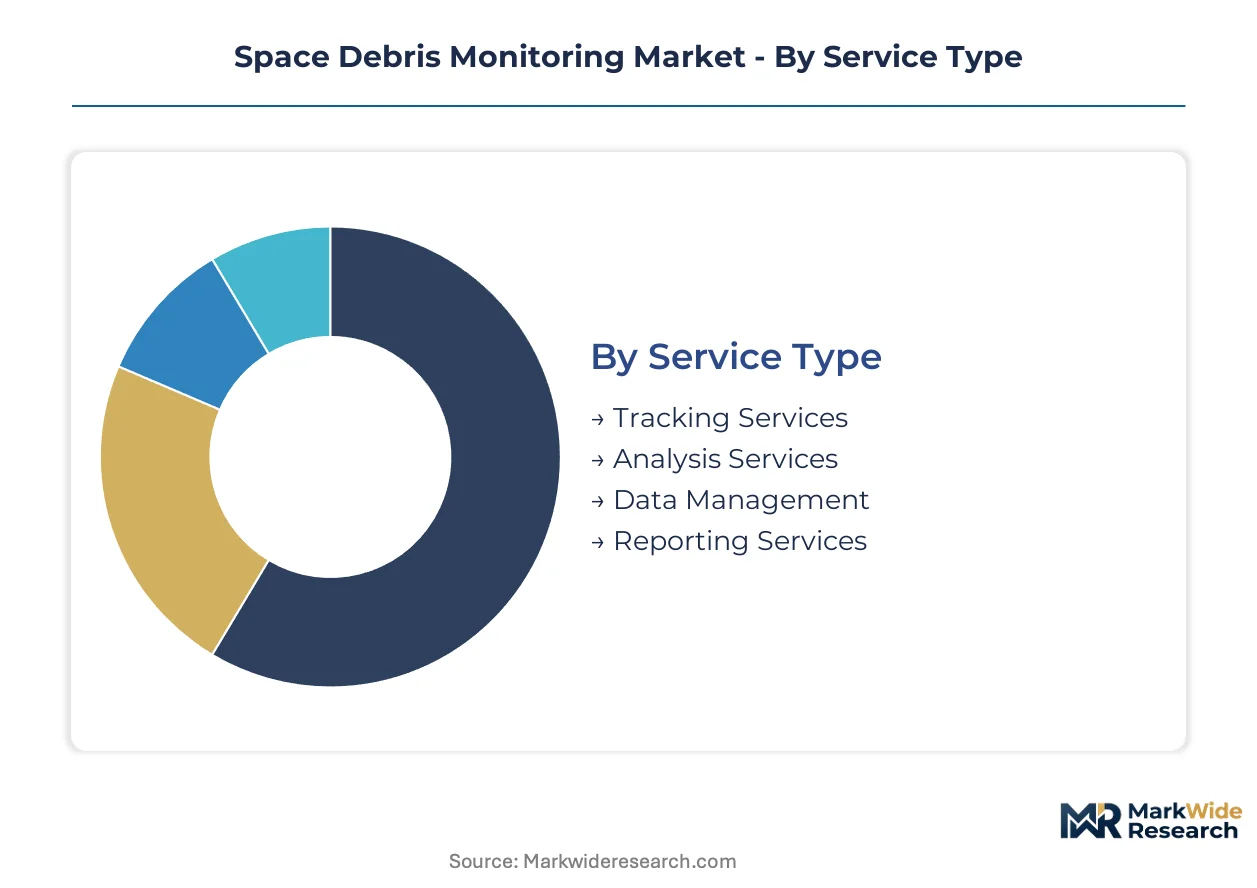
Segmentation in space debris monitoring reveals how regulatory pressure and operational complexity fragment procurement patterns across service tiers and technology platforms. Operators select capabilities based on orbital regime, asset value, and compliance mandates rather than uniform standards.
Service Type:
FCC debris disclosure mandates create divergent service procurement between licensed satellite operators seeking integrated compliance packages and research entities purchasing discrete analytical modules.
- Tracking Services:Continuous radar and optical surveillance generates raw orbital ephemeris data for object state vectors. Constellation operators in the United States purchase these services under multi-year subscriptions to satisfy FCC license conditions for collision avoidance capability.
- Analysis Services:Conjunction assessment algorithms process tracking data to compute collision probabilities and maneuver recommendations. Commercial operators pay premiums for these services when integrated directly into flight dynamics workflows.
- Data Management:Catalog maintenance and historical trajectory archival services support long-term statistical modeling.
- Reporting Services:Regulatory documentation and debris impact assessment preparation for license applications.
Established volume favors Tracking Services; emerging adoption favors Analysis Services.
End User:
Cost tier differentiation separates capital-intensive government sensor networks from subscription-dependent commercial operators.
- Government Agencies:National space commands and civil space agencies operate sovereign tracking infrastructure and maintain classified catalogs. The U.S. Space Force anchors the densest sensor network worldwide through its Space Surveillance Network.
- Commercial Operators:Satellite constellation ventures purchase catalog access and conjunction assessment on operational expenditure models. This segment is expanding most quickly as launch cadence multiplies across low-Earth orbit regimes.
- Research Organizations:Universities and national laboratories access tracking data for orbital dynamics modeling and debris evolution studies.
- Defense:Military satellite operators require high-assurance tracking with classified data handling protocols.
Defense and government procurement dominate absolute spending; commercial subscription models gain share fastest.
Technology:
Application requirements dictate technology selection—radar for all-weather low-Earth orbit coverage, optical systems for geostationary precision.
- Radar Systems:Phased-array radar with sub-degree precision detects centimeter-scale debris through all weather conditions. These systems occupy the largest technology share due to mature signal-processing chains and operational reliability.
- Optical Sensors:Electro-optical telescopes with adaptive optics correction achieve resolution improvements for geostationary regime monitoring where radar returns weaken. Charge-coupled device arrays and photon-counting detectors are climbing the fastest.
- Simulation Software:Orbital propagation and collision probability modeling tools for mission planning integration.
- Ground Stations:Physical infrastructure for sensor hosting, data processing, and network coordination.
Hardware concentration favors Radar Systems; resolution demands favor Optical Sensors.
Application:
Margin pools concentrate where debris monitoring integrates directly into operational decision workflows rather than standalone assessment.
- Mission Planning:Conjunction assessment embedded into maneuver optimization commands premium pricing from satellite operators seeking unified platforms. This application concentrates margin pools due to workflow integration value.
- Collision Avoidance:Real-time alerting and maneuver recommendation services for active spacecraft operations.
- Risk Assessment:Debris impact probability modeling for satellite design and insurance underwriting.
- Spacecraft Safety:Shielding specification and operational constraint definition for human spaceflight missions.
Operational integration favors Mission Planning; regulatory compliance favors Collision Avoidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC anchors the densest commercial sensor infrastructure through its orbital debris mitigation rules, which compress compliance timelines for licensed spacecraft operators across the United States.
United States
LeoLabs operates the largest commercial radar network dedicated to low-Earth orbit cataloging, while the Space Force maintains the Space Surveillance Network. The FCC mandates debris disclosure for all new satellite licenses, creating binding demand for characterization services. Colorado and California host the primary ground station clusters where phased-array radar installations multiply.
Japan
METI-funded radar upgrades coordinate national debris tracking through the Cabinet Office, with bilateral data-sharing protocols linking to U.S. Space Command. The country's space policy prioritizes conjunction assessment capabilities for its growing commercial constellation sector. Kyushu and Tokyo metropolitan areas concentrate ground-based electro-optical telescope networks.
Germany
Small satellite manufacturers in Bavaria and Baden-Württemberg now pre-qualify debris monitoring subscriptions before launch manifesting. The European Space Agency's procurement standards shape institutional mission requirements across member state programs. Stuttgart and Munich anchor the densest clusters of mission planning software developers.
United Kingdom
Scotland's spaceport development drives demand for integrated tracking and collision avoidance services among emerging launch providers. The UK Space Agency coordinates national participation in ESA debris mitigation frameworks while funding domestic sensor capabilities. Harwell and Glasgow concentrate satellite operators purchasing subscription-based catalog access.
Australia
Electro Optic Systems anchors its position through ground-based laser ranging stations spanning three continents including Australian facilities. The country's geographic advantages support southern hemisphere coverage gaps in geostationary orbit monitoring. Canberra and Perth host the primary optical sensor installations serving Asia-Pacific satellite operators.
Space Debris Monitoring Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-heavy incumbents leveraging defense sensor integration against niche radar and optical specialists. The competitive landscape bifurcates around talent scarcity in astrophysics and radar engineering, which limits network expansion velocity for new entrants. Three archetypes dominate: defense-integrated conglomerates with classified contract experience, commercial sensor network operators with dedicated low-Earth orbit infrastructure, and debris removal ventures with monitoring-to-servicing integration. M&A activity concentrates on acquiring phased-array radar capabilities, while strategic partnerships proliferate around data-sharing protocols between military and commercial catalog providers.
Within the defense-integrated tier, Lockheed Martin Corporation and Northrop Grumman Corporation represent established positions in high-resolution orbital tracking contracts. LeoLabs occupies a distinct archetype as the largest commercial radar network operator. Electro Optic Systems exemplifies the ground-based optical specialist model with laser ranging station networks. Airbus SAS anchors European institutional participation through ESA contracting relationships.
| Leading Market Players |
|---|
| Altius Space Machines |
| Electro Optic Systems |
| Airbus SAS |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Astroscale Holdings |
| D-Orbit |
| LeoLabs |
| ClearSpace |
| Others |
Supply Flow & Price Mechanics
Eighteen-month lead times for phased-array radar subassemblies concentrate pricing power among defense-integrated suppliers in the United States, while subscription-based catalog access compresses capital expenditure barriers for emerging constellation operators seeking FCC compliance.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates mission-integrated conjunction assessment from raw ephemeris feeds and archival catalog access. Price differentiation hinges on data latency guarantees and sensor network exclusivity, with premium tiers commanding multiples for sub-minute alert-to-maneuver workflows. Cost compression in standard-tier subscriptions is intensifying because venture-backed launch services prioritize operational expenditure flexibility over infrastructure ownership. Commercial constellation operators exhibit highest price sensitivity; defense satellite operators with classified handling requirements show lowest.
Supply Chain Analysis
Inventory buffers for gallium nitride transmit-receive modules rarely exceed ninety days, exposing network expansion timelines to semiconductor foundry scheduling in the United States, Germany, and Japan. Hardware production draws from specialized radar component suppliers, precision optical glass manufacturers, and photon-counting detector fabricators. Single-source vulnerability concentrates in high-power amplifier assemblies qualified for space-grade environmental testing. Distribution runs through direct procurement contracts for government sensor networks and SaaS-platform intermediation for commercial catalog subscribers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital traffic management is shifting from government monopoly toward hybrid public-private architecture, with data-sharing standardization disputes between military and commercial catalog providers creating platform interoperability premiums.
For Market Incumbents: Consolidate phased-array radar capabilities through targeted acquisitions of niche sensor specialists facing talent scarcity constraints. Lockheed Martin Corporation and Northrop Grumman Corporation should deepen backward integration into gallium nitride semiconductor fabrication to defend margin position against commercial network operators. FCC disclosure mandates create captive demand for integrated compliance packages. For New Entrants and Emerging Players: Anchor in geostationary orbit coverage gaps where radar returns weaken and photon-counting detector demand outstrips installed optical station capacity. Japan's METI-funded infrastructure expansion offers partnership pathways through bilateral U.S. Space Command protocols. Lead with subscription-tiered data feeds rather than capital-intensive proprietary networks. For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates spinning off non-core space situational awareness divisions as orbital traffic management commercializes. Five-to-ten-year viability favors operators controlling physical sensor infrastructure rather than pure-play analytics layers. Monitor FCC license application volumes as inflection indicator for tracking service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Network Expansion | LeoLabs extends phased-array radar coverage to address FCC compliance timelines for constellation operators. |
| Photon-Counting Detector Deployment | Electro Optic Systems upgrades geostationary stations to capture single-photon sensitivity demand from satellite operators. |
| Mission Planning Integration | Conjunction assessment tools embed into flight dynamics workflows commanding premium pricing from unified platform seekers. |
| Defense-Civilian Data Sharing Protocols | U.S. Space Command bilateral agreements with Japan's Cabinet Office establish interoperability standards for hybrid architecture transition. |
| Specialist Talent Acquisition | Astrophysicist and radar engineer recruitment accelerates network expansion velocity constrained by compensation inflation. |
Methodological Framework
Operator-level perspectives from satellite constellation flight dynamics directors, FCC regulatory compliance officers, Space Force sensor network program managers, and commercial radar network engineering leads anchored the qualitative base. Secondary validation drew from U.S. Federal Communications Commission licensing databases, U.S. Space Command public data releases, European Space Agency procurement records, and Japan Cabinet Office space policy white papers. Bottom-up segment sizing triangulated against top-down market envelope checks.
Sensitivity analysis tested forecast outputs against alternative launch cadence scenarios and regulatory compliance deadline shifts across the analysis window. Segmentation dimensions modeled include service type, end-user category, technology platform, orbital regime application, and geographic regulatory cluster. CAGRs were derived from installed sensor capacity expansion curves and subscription pricing trajectory assumptions. Industry-specific inputs incorporated FCC license application pipelines and ESA institutional mission procurement schedules.
Material uncertainties — launch failure rates affecting constellation deployment timelines, phased-array radar production bottlenecks, and international data-sharing standardization disputes — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory mandate enforcement intensity and sensor technology maturation curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Africa Space Electronics Market
Space
Europe Space Logistics Market
Space
Space Lander and Rover Market
Space
Space Radar Market
Space
Japan Space Electronics Market
Space
Near Space Robotics Market
Space
Space Transportation Market
Space
Space Rover Market
Space
US Space Launch Services Market
Space
Space-Based C4ISR Market
Space
Orbital Spaceflight Market
Space
Space Semiconductor Market
Space
Space Tourism Market
Space
Mexico Space Electronics Market
Space
Space Ground System Market
Space
Space Propulsion Systems Market