
 Space As a Service Market | 2026-2036
Space As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Space As a Service Market Analytics
North American property technology providers is rebalancing supply toward asset-light management contracts rather than direct lease arbitrage. SpaceX leverages its launch infrastructure to anchor orbital service offerings that extend terrestrial facility concepts into extraterrestrial logistics. Blue Origin competes through vertical integration of propulsion and habitation modules. IWG sustains geographic dominance across suburban and secondary-city footprints where enterprise clients seek satellite offices without capital commitment.
Space As a Service denotes the commercial provision of physical environments—office, laboratory, manufacturing, or orbital—through contractual access rather than ownership, typically incorporating IoT sensors, cloud-based booking platforms, and remote access protocols to optimize utilization rates. The offering type dimension shows office space and co-working space commanding established revenue pools while event space captures premium pricing for short-duration, high-specification deployments. Subscription-based service models anchor enterprise relationships with predictable occupancy costs, whereas pay-as-you-go structures attract project-based users seeking temporal flexibility without covenant obligations.
The FCC governs spectrum allocation for satellite-linked facility management systems, while OSHA standards govern terrestrial workplace safety in flexible environments where tenant turnover complicates hazard assessment. GDPR in Europe and state-level biometric privacy laws in Illinois and California constrain IoT data collection from occupant tracking sensors, forcing providers to architect edge-computing solutions that minimize personal data transmission. Stakeholders must weigh regulatory fragmentation against the operational efficiency gains of centralized building intelligence platforms.
Market Dynamics
Enterprise hybrid work mandates are compressing lease tenures and forcing providers to embed IoT sensors and cloud-native access systems into every square foot of inventory. This technological retrofit is the dominant structural force reshaping competitive economics across office, laboratory, and orbital facility segments.
Growth Catalysts
- OSHA workplace safety modernization:Flexible workspace providers in the United States must demonstrate compliance with evolving hazard assessment protocols for high-turnover tenant environments, accelerating investment in automated safety monitoring systems.
- Enterprise satellite office deployment:Fortune 500 technology and financial services firms are establishing distributed footprints across secondary metropolitan corridors without capital lease commitments, sustaining subscription revenue pools.
- Edge computing architectures:GDPR and Illinois biometric privacy constraints on occupant tracking sensors are forcing providers to process data locally rather than transmitting to centralized clouds, driving hardware refresh cycles.
Market Restraints
- Real estate carry cost volatility:Direct lease arbitrage models expose operators to rent escalations in supply-constrained urban cores, particularly Manhattan and San Francisco, where landlord bargaining power remains elevated.
- Spectrum allocation bottlenecks:FCC licensing timelines for satellite-linked building management systems extend 18-24 months, delaying orbital-terrestrial service integration for facility operators.
- Technical interoperability gaps:Proprietary IoT sensor networks from incumbent building automation vendors resist integration with cloud-native access platforms, fragmenting operational data lakes.
Strategic Opportunities
- EU Green Deal compliance services:CSRD reporting mandates for commercial real estate energy performance are creating advisory and retrofit revenue streams for providers capable of certifying carbon-neutral workspace inventory.
- Orbital manufacturing facilities:Microgravity laboratory and production environments represent an emerging application category where launch infrastructure operators can extend terrestrial facility management expertise.
- Pharmaceutical R&D satellite labs:FDA-regulated drug discovery firms are adopting flexible wet-lab space on subscription terms, reducing capital deployment for early-stage therapeutic programs.
Industry Challenges
- Building systems engineering talent scarcity:Integration of legacy HVAC and security infrastructure with modern IoT platforms requires specialized technicians, with labor markets tight in major metropolitan technology corridors.
- Biometric data compliance fragmentation:California's CCPA amendments and Illinois BIPA create conflicting consent and retention requirements for occupant tracking systems, forcing jurisdiction-specific platform configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space As a Service Market |
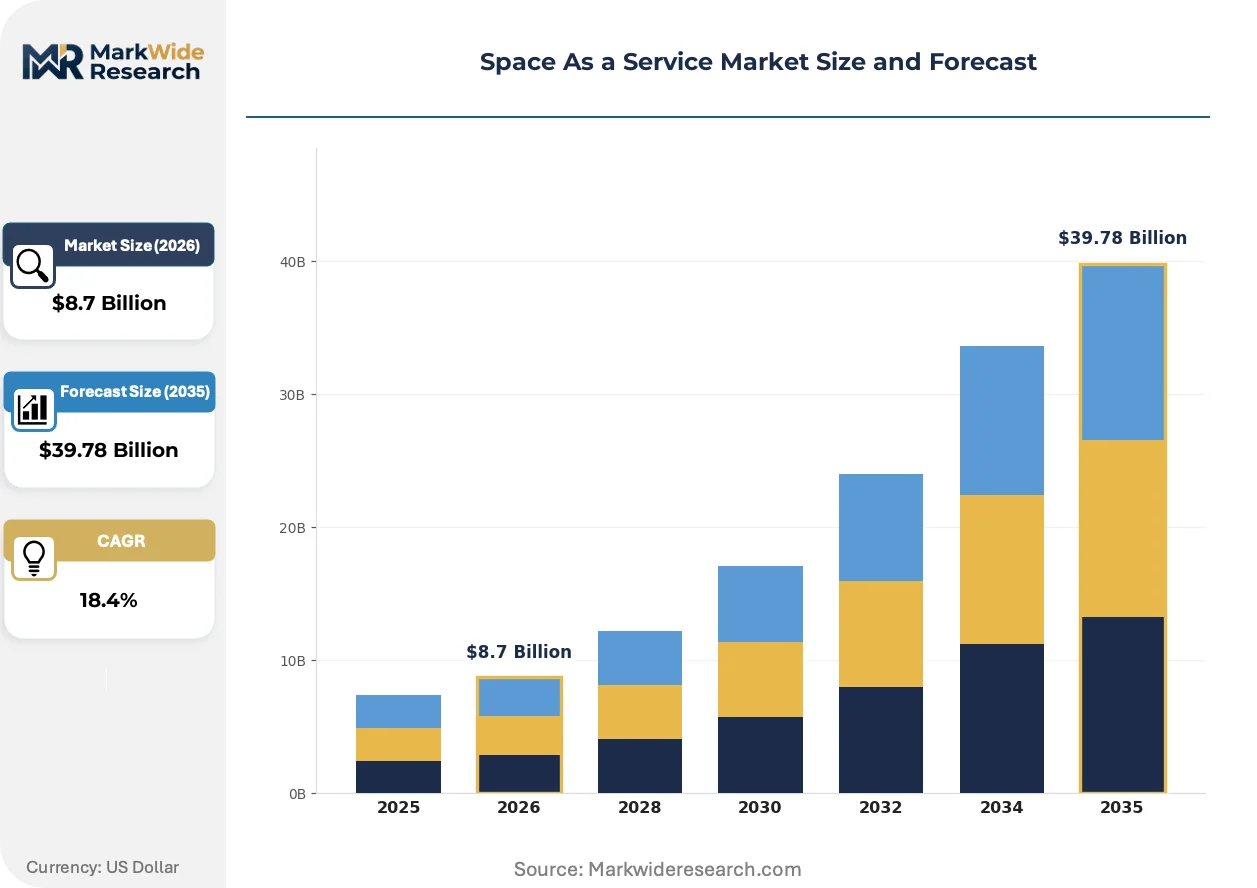
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Offering Type: Office Space, Co-Working Space, Retail Space, Event Space Customer Type: Startups, Enterprises, Freelancers, Non-Profits Service Model: Subscription-Based, Pay-As-You-Go, Long-Term Lease, Short-Term Lease Technology Used: IoT Integration, Cloud Services, Virtual Platforms, Remote Access |
| Companies Covered | SpaceX, Blue Origin, Axiom Space, Virgin Galactic, Rocket Lab, Relativity Space, Northrop Grumman, Maxar Technologies, Airbus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space As a Service Market Evolving Landscape
Digitization of physical space access is collapsing traditional boundaries between real estate, technology services, and orbital logistics. Three distinct vectors are compressing time-to-occupancy and expanding addressable facility categories.
Digital twin platforms are rewriting how operators simulate occupancy patterns and energy loads before physical fit-out. Enterprise tenants in pharmaceutical and financial services verticals now mandate virtual commissioning of satellite offices, compressing design-to-occupancy timelines from months to weeks. This simulation capability is rewriting competitive bidding dynamics for large-scale managed service contracts.
GDPR Article 25 data protection by design mandates are forcing European providers to architect edge-first sensor networks that minimize personal data transmission. Building management system vendors must now certify that occupant movement tracking never crosses jurisdictional boundaries, increasing hardware complexity but reducing liability exposure. French and German operators are responding fastest, embedding CNIL-compliant privacy architectures as standard.
Consumption patterns among enterprise real estate procurement teams are rotating from long-term managed service agreements toward modular, project-based workspace subscriptions. Technology sector buyers now unbundle event space, laboratory access, and executive meeting rooms across multiple providers rather than consolidating with single vendors. This fragmentation is most visible in Austin, Boston, and Seattle technology corridors, where procurement teams optimize for specific facility specifications over relationship continuity.
Space As a Service Market Segmentation
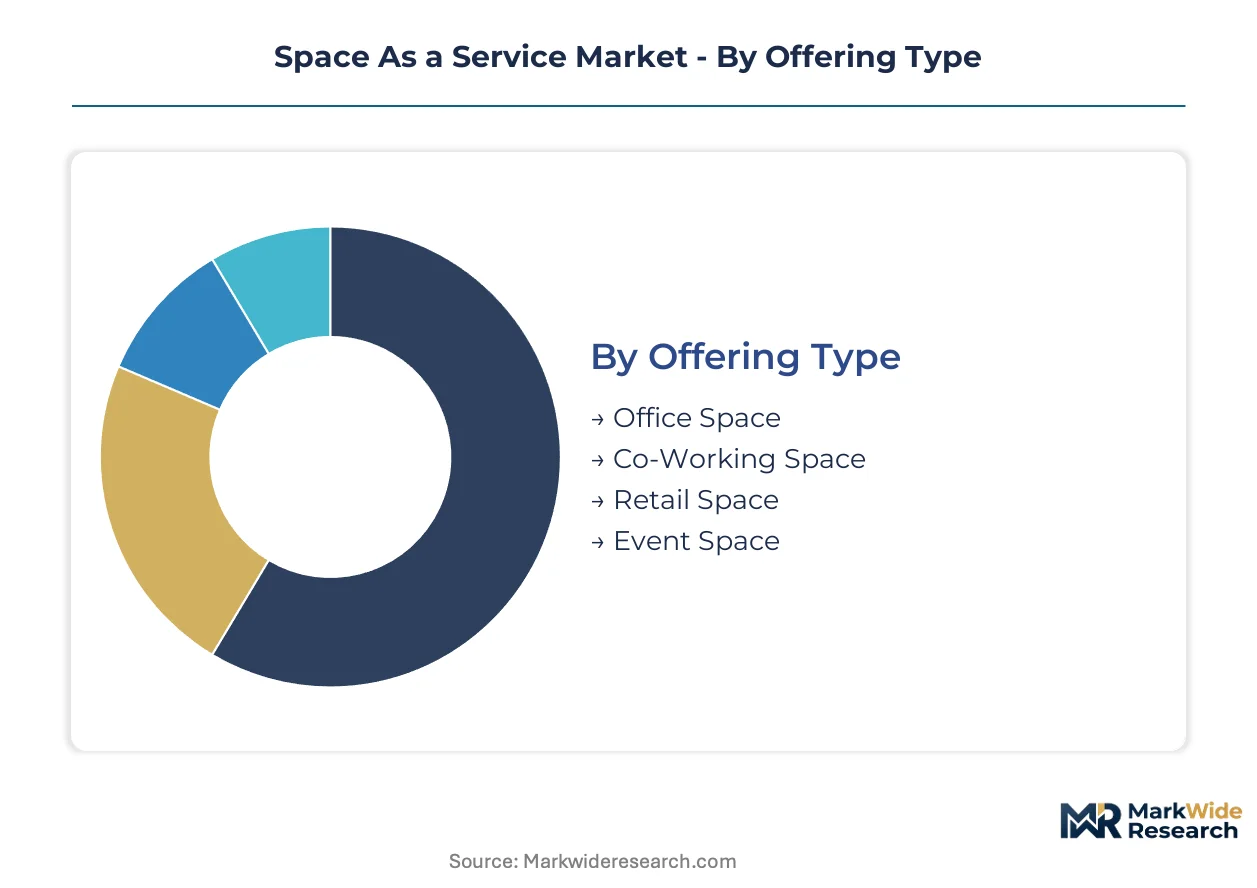
Space As a Service providers must align inventory configuration with distinct buyer risk profiles and operational cadences. Enterprise procurement teams evaluate subscription elasticity against capital lease avoidance, while technology integration requirements vary sharply across facility types.
Offering Type:
Buyers prioritize location flexibility and specification grade over ownership, with contract duration and amenity density driving selection across four facility categories.
- Office Space:Dedicated private suites with embedded IoT building management systems serve legal, financial, and pharmaceutical tenants requiring controlled access protocols. Demand concentrates in Manhattan, London, and Singapore where enterprise satellite office mandates compress lease tenures below traditional commercial terms.
- Co-Working Space:Open-plan hot-desking environments with cloud-native booking platforms attract technology sector distributed teams. Secondary metropolitan corridors in the United States and Germany sustain volume as hybrid work policies normalize.
- Retail Space:Pop-up storefronts and showroom concepts with short-fit-out timelines serve direct-to-consumer brands testing geographic expansion. Seasonal demand spikes around product launch windows.
- Event Space:High-specification conference and exhibition halls command premium per-day rates for corporate gatherings and industry conventions. GDPR-compliant biometric access systems differentiate European inventory.
Volume sits with Office Space and Co-Working Space; growth tilts toward Event Space as enterprise procurement teams unbundle meeting requirements from core lease commitments.
Customer Type:
Contract value and churn risk diverge sharply across organizational maturity stages, forcing providers to architect distinct onboarding and retention protocols.
- Enterprises:Fortune 500 technology and financial services firms negotiate multi-location subscription agreements with standardized security and compliance terms. FDA-regulated pharmaceutical clients drive wet-lab specification requirements.
- Startups:Venture-backed companies prioritize month-to-month flexibility and proximity to talent clusters. Burn-rate sensitivity compresses per-seat willingness-to-pay versus enterprise benchmarks.
- Freelancers:Individual operators generate fill-rate volatility but require minimal service overhead. Day-pass and hot-desk utilization patterns concentrate in urban cores with transit accessibility.
- Non-Profits:Mission-driven organizations seek below-market rate structures and grant-compliant lease documentation. Volume remains fragmented across education, advocacy, and cultural institutions.
Revenue concentration favors Enterprises; expansion velocity clusters with Startups in Austin, Boston, and Berlin technology corridors.
Service Model:
Payment structure selection reflects balance sheet strategy and occupancy predictability, with subscription terms displacing traditional lease arbitrage.
- Subscription-Based:Fixed monthly fees for guaranteed access rights anchor enterprise relationships with predictable occupancy costs and simplified procurement workflows.
- Pay-As-You-Go:Per-hour or per-day billing attracts project-based users and event-driven demand without covenant obligations or security deposits.
- Long-Term Lease:Direct landlord contracts with provider management overlays persist for flagship corporate headquarters requiring customization.
- Short-Term Lease:Three-to-twelve month commitments bridge gap requirements for expansion teams awaiting permanent facilities.
Margin stability flows through Subscription-Based contracts; addressable market expansion rides Pay-As-You-Go adoption among non-traditional workspace users.
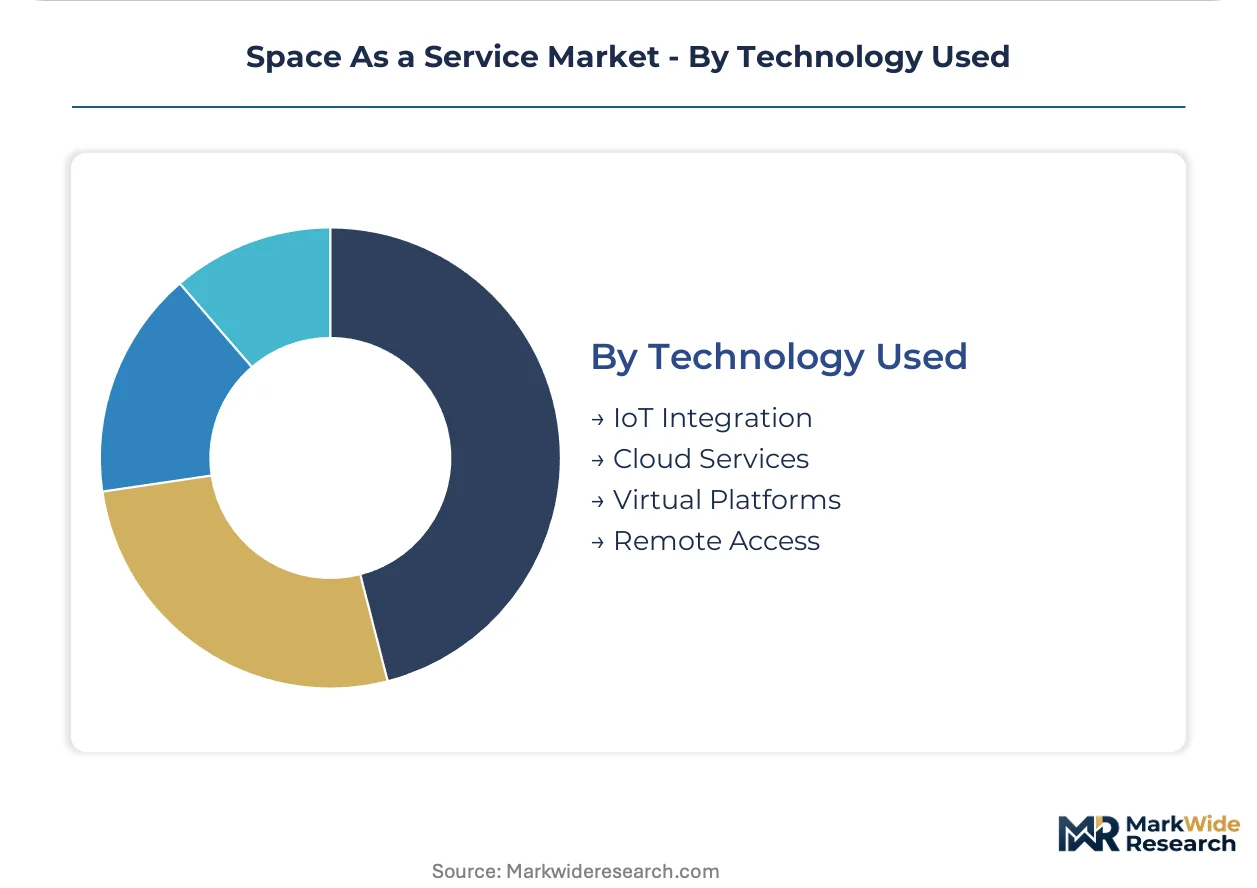
Technology Used:
Operational efficiency and regulatory compliance hinge on architecture choices for sensor deployment, data residency, and access authentication.
- IoT Integration:Occupancy sensors and environmental monitors optimize HVAC loads and space utilization rates. Illinois BIPA and California CCPA constrain biometric data collection, forcing edge-computing configurations.
- Cloud Services:Centralized building management platforms enable remote facility oversight but face GDPR Article 25 data localization requirements in European deployments.
- Virtual Platforms:Digital twin simulations compress design-to-occupancy timelines for enterprise satellite offices in pharmaceutical and financial services verticals.
- Remote Access:Mobile credentialing and cloud-based door control reduce physical key management overhead while integrating with enterprise identity systems.
Deployment scale currently centers on IoT Integration; compliance complexity is accelerating Cloud Services architecture redesign toward edge-first models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Launch infrastructure and terrestrial real estate capital flows anchor geographic concentration. Orbital facility operators cluster near existing spaceports, while flexible workspace providers concentrate in metropolitan technology corridors.
United States
Enterprise satellite office mandates drive demand across secondary metropolitan corridors. OSHA workplace safety modernization accelerates automated monitoring system deployment. Austin, Boston, and Seattle technology corridors sustain volume as procurement teams unbundle workspace requirements.
Germany
GDPR Article 25 compliance mandates reshape edge-computing architectures for occupant tracking systems. CNIL-aligned privacy certifications differentiate facility operators in Frankfurt and Munich. Bavarian industrial clusters absorb flexible manufacturing space on subscription terms.
United Kingdom
Financial services firms compress lease tenures for satellite offices in London and regional hubs. CSRD reporting requirements for commercial real estate energy performance create advisory revenue streams. Manchester and Birmingham secondary corridors expand inventory for distributed enterprise teams.
France
CNIL-compliant privacy architectures become standard for IoT-enabled building management systems. EU Green Deal carbon-neutral workspace certification drives retrofit investment. Paris and Lyon metropolitan areas concentrate premium event space and laboratory facilities.
Singapore
Pharmaceutical R&D satellite labs adopt flexible wet-lab space for early-stage therapeutic programs. Enterprise procurement teams mandate digital twin commissioning for regional headquarters. Biomedical and fintech clusters drive specification requirements for controlled-access environments.
Space As a Service Market Competitive Landscape
Global majors compete with regional champions across launch infrastructure and terrestrial facility management dimensions. The vendor base separates into orbital service operators, flexible workspace incumbents, and hybrid platform providers. Three strategic archetypes dominate: launch-anchored orbital facility operators, asset-light property technology managers, and vertically integrated aerospace-defense conglomerates. M&A activity concentrates on satellite services and IoT building management capabilities; geographic expansion targets secondary metropolitan corridors with enterprise satellite office demand.
Within the launch-anchored tier, SpaceX and Blue Origin occupy positions extending terrestrial facility concepts into orbital logistics. Among aerospace-defense conglomerates, Northrop Grumman exemplifies backward integration into habitation modules and on-orbit servicing. IWG represents the asset-light property technology archetype, sustaining geographic dominance across suburban and secondary-city footprints where enterprise clients seek satellite offices without capital commitment.
| Leading Market Players |
|---|
| SpaceX |
| Blue Origin |
| Axiom Space |
| Virgin Galactic |
| Rocket Lab |
| Relativity Space |
| Northrop Grumman |
| Maxar Technologies |
| Airbus |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up flexible workspace operators have consolidated fragmented urban inventory across Manhattan, London, and Singapore, concentrating pricing power with scaled providers while compressing margins for sub-scale competitors locked into direct lease arbitrage. This ownership pattern feeds supply discipline—rolled-up platforms negotiate master lease terms that smaller operators cannot match, embedding cost advantages into subscription pricing.
Pricing Analysis
Warranty and service bundling separates premium managed-service contracts from bare-metal space rentals. Three-tier pricing structure across premium, standard, and economy levels reflects amenity density and IoT integration depth. Price differentiation flows from certification grade—GDPR-compliant edge-computing architectures command premium positioning in Frankfurt and Paris—while cost compression in economy tiers intensifies due to fill-rate volatility in secondary corridors. Startups exhibit highest price sensitivity; Fortune 500 satellite office mandates show lowest elasticity.
Supply Chain Analysis
Certification and qualification gating restricts sensor hardware sourcing to vendors with CNIL-aligned privacy certifications and FCC spectrum licensing. Supply concentrates in the United States, Germany, and China for IoT sensor modules and cloud-native access platforms. Component dependencies include edge-computing processors, biometric readers, and building automation controllers. Single-source vulnerability runs through proprietary IoT networks resisting integration. Distribution runs through direct vendor relationships with facility operators and master system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
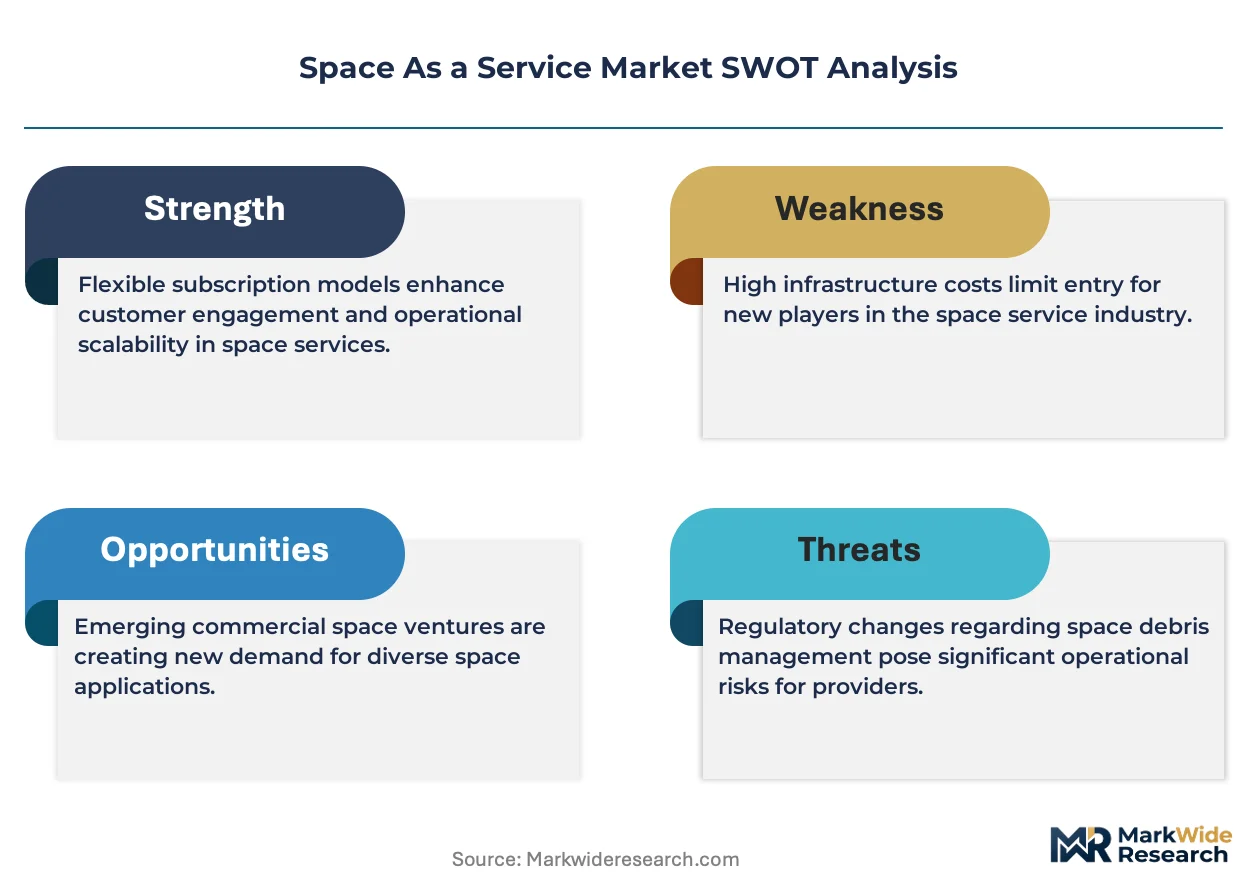
Real estate carry cost volatility and regulatory compliance fragmentation are accelerating consolidation, forcing sub-scale operators into distressed asset sales or management contract exits.
For Market Incumbents: Deepen backward integration into IoT sensor networks and edge-computing hardware to reduce vendor lock-in from proprietary building automation vendors. Expand asset-light management contract footprints across Austin, Boston, and Seattle technology corridors to escape rent escalation exposure in Manhattan and San Francisco. For New Entrants and Emerging Players: Begin with pharmaceutical R&D satellite labs and FDA-regulated wet-lab space, where compliance complexity deters generalist competitors and subscription terms displace capital deployment. Target EU Green Deal carbon-neutral workspace certification advisory services as a white-space entry point with recurring revenue potential. For Investors and Strategic Acquirers: FCC spectrum licensing backlog clearing for satellite-linked building management systems is the leading indicator that orbital-terrestrial service integration will unlock new facility categories. Long-term viability favors operators with launch infrastructure anchoring extraterrestrial logistics capabilities. Acquisition targets should demonstrate CNIL-compliant privacy architectures and digital twin commissioning capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Architecture Deployment | GDPR Article 25 compliance mandates force hardware refresh cycles in European facilities. |
| Digital Twin Platform Integration | Pharmaceutical and financial services tenants mandate virtual commissioning for satellite offices. |
| Orbital Manufacturing Facility Development | Microgravity laboratory access extends terrestrial facility management expertise for launch operators. |
| Carbon-Neutral Certification Program | CSRD reporting requirements create advisory revenue streams for EU commercial real estate. |
| Biometric Privacy Compliance Investment | Illinois BIPA and California CCPA amendments force jurisdiction-specific platform configurations. |
Research Methodology
Multi-period observation of enterprise satellite office deployment patterns, IoT sensor installation rates, and subscription contract tenures anchored the trend analysis, supplemented by interviews with flexible workspace operators, building management system vendors, commercial real estate brokers, and pharmaceutical facility procurement leads. Secondary validation drew from FCC spectrum licensing databases, OSHA workplace safety modernization filings, EU Green Deal implementation reports, and property technology venture financing disclosures. Bottom-up facility inventory counts triangulated against top-down enterprise real estate spending estimates.
Segment-weighting across offering type, customer maturity, service model structure, and technology architecture informed value distribution modeling across the projection horizon. CAGRs derived from fitted growth curves applied to subscription revenue pools and pay-as-you-go utilization patterns. Forecast inputs included hybrid work policy persistence rates, edge-computing hardware cost decline trajectories, and orbital launch cadence assumptions for extraterrestrial facility development.
Regulatory enforcement intensity shifts, spectrum allocation timeline extensions, and enterprise return-to-office mandate reversals are the dominant revision risks to modeled outcomes. A model refresh is warranted upon material change in OSHA workplace safety protocol finalization or GDPR biometric data precedent rulings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Asia-Pacific Space Logistics Market
Space
Spacecraft Market
Space
Spacesuit Market
Space
Suborbital Space Tourism Market
Space
Space Robotics Market
Space
Carrier Rocket Market
Space
Near Space Robotics Market
Space
Space Management Solutions Market
Space
Germany Space Electronics Market
Space
Space Traffic Management Market
Space
Europe Space Logistics Market
Space
Africa Space Propulsion System Market
Space
India Aviation, Defense, and Space Market
Space
Space Robots Market
Space
Rocket Launchpad Market
Space
China Space Electronics Market