
 Space-Based Smart Sensors Market | 2026-2036
Space-Based Smart Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Space-Based Smart Sensors Market Insights
Defense surveillance is restructuring the end-use mix for space-based smart sensors as military constellations displace legacy civilian-only demand patterns. Northrop Grumman Corporation leverages its heritage in strategic space payloads to anchor high-margin defense contracts. Thales Alenia Space competes through European sovereign satellite programs and dual-use Earth observation platforms. Honeywell International Inc. dominates radiation-hardened sensor electronics for geostationary and medium-Earth-orbit missions.
Space-based smart sensors integrate photonic, thermal, and electromagnetic detection elements onto compact orbital platforms operating in vacuum and radiation environments; these systems typically achieve spatial resolutions below one meter and thermal sensitivities of fractions of a degree Kelvin, serving missions from weather prediction to missile launch detection. Optical and radar sensor types lead current procurement volumes, though hyperspectral instruments command premium pricing for mineral exploration and agricultural monitoring applications. Low Earth Orbit deployments represent the fastest-expanding segment as proliferated constellations from commercial operators and defense agencies drive unit demand into thousands of satellites.
US Space Force acquisition directives, FCC spectrum and orbital debris rules, and ESA's Clean Space initiative collectively tighten qualification requirements and extend development cycles for new sensor entrants. NASA's Technology Readiness Level gating and the EU Space Programme's security component further segment market access between allied and non-allied suppliers. Stakeholders must monitor evolving ITAR and export control classifications as geopolitical competition intensifies for sensitive remote sensing capabilities.
Market Dynamics
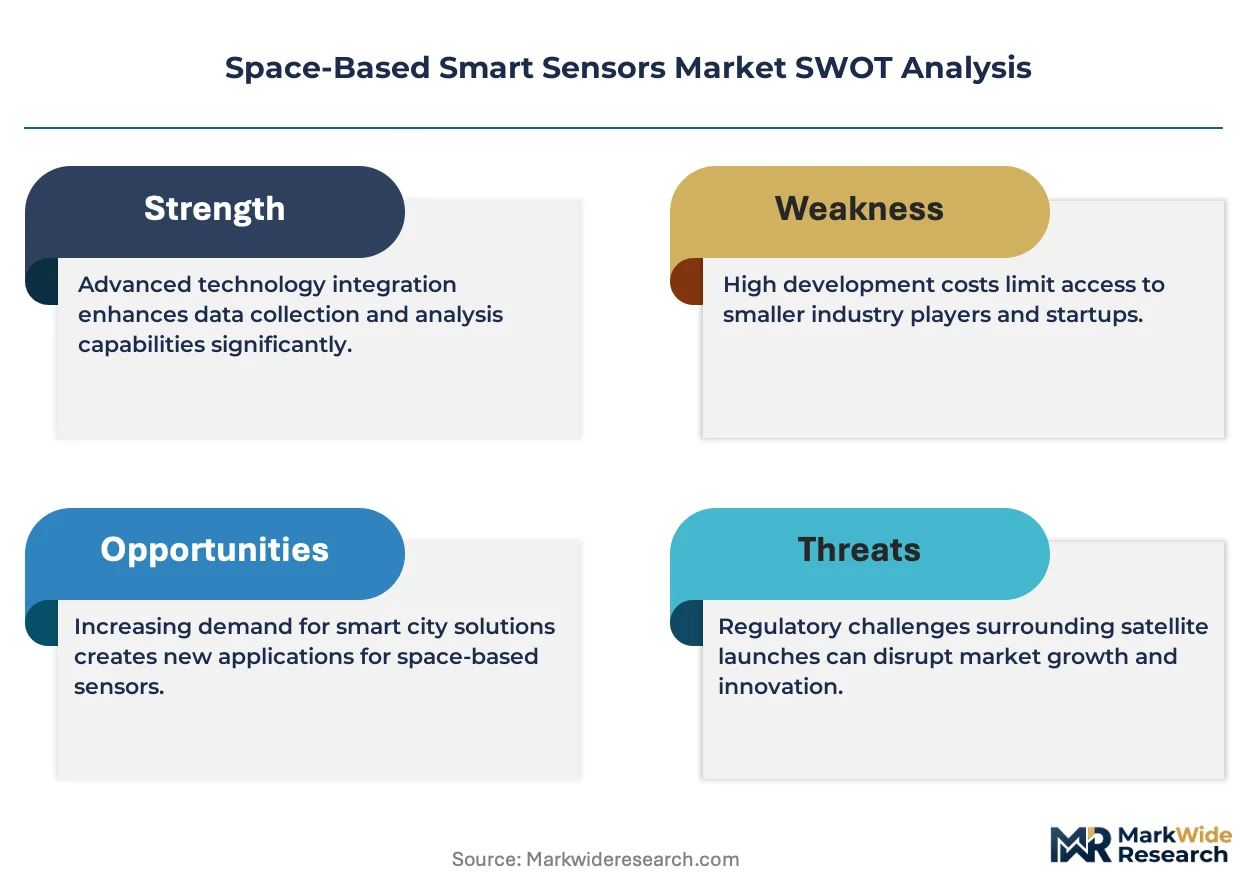
Defense procurement directives from the US Space Force and allied military agencies are restructuring demand patterns, displacing legacy civilian-only satellite missions with proliferated constellations designed for missile tracking and tactical intelligence.
Growth Catalysts
- MEMS Miniaturization:Micro-electromechanical systems are slashing payload mass below 50 kilograms while preserving detection sensitivity, enabling batch production of orbital sensor nodes.
- NATO Space Endorsement:The alliance's 2022 Strategic Concept designates space as an operational domain, triggering coordinated procurement across member states for shared early-warning architectures.
- Radiation-Hardened Electronics:Advances in silicon-on-insulator fabrication extend operational lifespans in geostationary and medium-Earth orbits, reducing replacement frequency for high-altitude missions.
Market Restraints
- Launch Cost Volatility:Dependence on a concentrated supplier base for heavy-lift vehicles creates input cost uncertainty for large constellation deployments.
- ITAR Classification Friction:US State Department export controls on remote sensing components restrict technology transfer to non-allied programs, fragmenting supplier access.
- Orbital Debris Qualification:FCC licensing mandates for post-mission disposal and collision avoidance systems extend development timelines and certification costs for new entrants.
Strategic Opportunities
- India's Space Programme Expansion:ISRO's commercial arm and private launch operators create entry points for foreign sensor vendors seeking non-Western constellation contracts.
- Hyperspectral Agriculture:Mineral exploration and precision farming applications command premium pricing for instruments resolving hundreds of spectral bands.
- AI-Edge Convergence:Onboard machine learning inference is compressing data transmission requirements, enabling real-time anomaly detection without ground station dependency.
Industry Challenges
- Radiation Effects Engineering Talent:Scarcity of specialists in single-event upset mitigation and total ionizing dose hardening constrains design team scaling.
- TRL-8 Certification Timelines:NASA's Technology Readiness Level gating for spaceflight heritage creates 18-to-36-month validation bottlenecks before operational deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space-Based Smart Sensors Market |
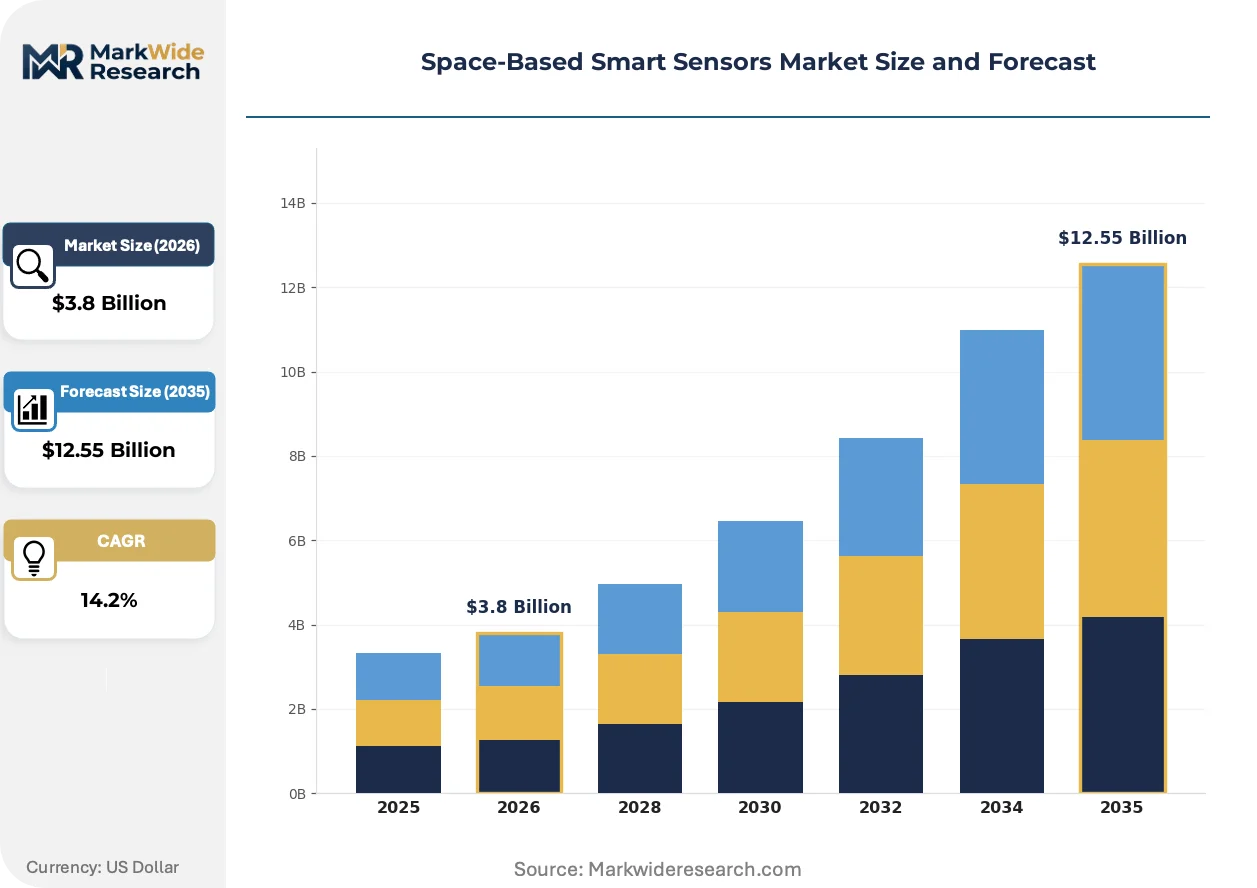
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Optical, Infrared, Lidar, Radar, Magnetometer, Hyperspectral Application: Earth Observation, Weather Monitoring, Disaster Management, Space Exploration, Telecommunications, Defense Surveillance Orbit Type: Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Highly Elliptical Orbit, Sun-Synchronous Orbit, Polar Orbit End User: Space Agencies, Commercial Satellite Operators, Defense Contractors, Research Laboratories, Telecommunication Firms, Environmental Organizations |
| Companies Covered | Honeywell International Inc., Teledyne Technologies Incorporated, RTX Corporation, Northrop Grumman Corporation, Airbus Defence and Space, Moog Inc., BAE Systems plc, Thales Alenia Space, Ball Aerospace & Technologies Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space-Based Smart Sensors Market Trends and Innovations
Autonomous onboard processing and sovereign data security requirements are compressing the traditional ground-segment architecture, shifting intelligence extraction from terrestrial supercomputing to orbital edge nodes.
Photonic integrated circuits are automating optical beam steering and spectral filtering functions previously executed by mechanical gimbals and discrete filters. The Space Development Agency and commercial Earth observation operators are deploying these devices in proliferated low-Earth-orbit constellations. This automation is collapsing sensor package volumes by 60 percent while maintaining sub-meter resolution performance.
REACH substance restrictions and the EU Space Programme's security component are tightening material qualification for European satellite missions. Manufacturers must now document full supply chain provenance for adhesives, coatings, and semiconductor substrates. Small and mid-sized payload integrators in France, Germany, and Italy face the steepest compliance cost increases.
Subscription-based data access is displacing traditional satellite imagery ownership models among agricultural and insurance verticals. Analytics platforms bundle sensor tasking with machine-learning-derived insights, unbundling raw pixel delivery from value-added products. This shift concentrates most visibly in North American and Australian markets where farm management software penetration exceeds 40 percent.
Space-Based Smart Sensors Market Segmentation
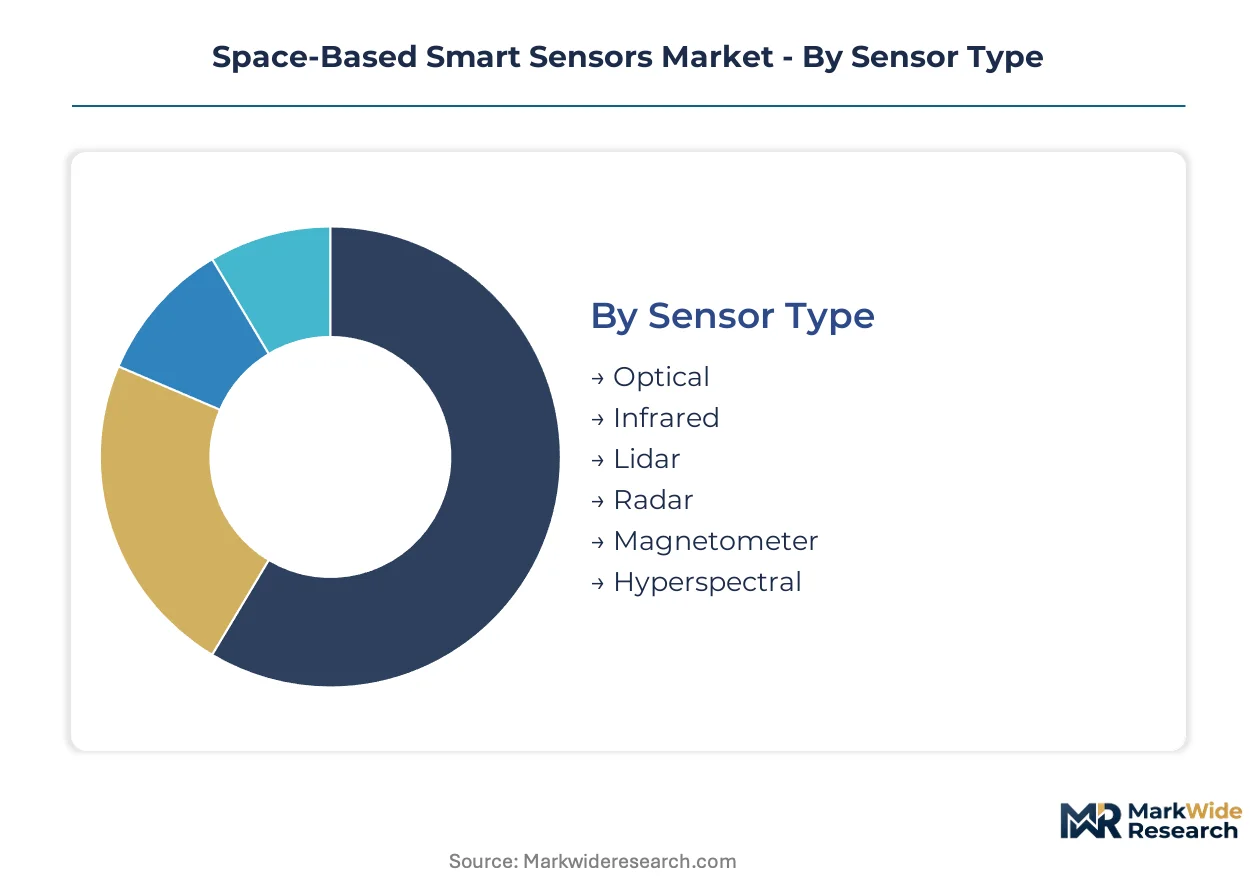
Segmentation in space-based smart sensors reveals how mission requirements dictate payload specifications across orbital regimes. Procurement patterns diverge sharply between defense-classified programs and commercial Earth observation services, with each segment imposing distinct qualification thresholds on component suppliers.
Sensor Type:
Detection modality determines resolution limits, atmospheric penetration capability, and data processing architectures for orbital platforms.
- Optical:Silicon CCD and CMOS arrays capture panchromatic and multispectral imagery with sub-meter ground sample distance. US Space Force and European Earth observation constellations drive procurement for tactical intelligence and agricultural monitoring missions.
- Radar:Synthetic aperture radar transmits microwave pulses through cloud cover and darkness, enabling all-weather surveillance. Defense agencies in the United States and NATO members prioritize this modality for maritime domain awareness and missile launch detection.
- Infrared:Cooled and uncooled focal plane arrays detect thermal signatures for wildfire monitoring and industrial emissions tracking.
- Lidar:Pulsed laser ranging generates three-dimensional terrain models for forestry biomass assessment and coastal erosion measurement.
- Magnetometer:Vector magnetic field sensors map geophysical anomalies and support space weather prediction for satellite operations.
- Hyperspectral:Hundreds of contiguous spectral bands identify mineral compositions and vegetation stress indicators for precision agriculture.
Mature deployment sits with optical systems. Newer deployment is concentrated in hyperspectral instruments for commercial analytics platforms.
Application:
Mission purpose segments procurement budgets between sovereign security programs and commercial data services.
- Defense Surveillance:Missile tracking, signals intelligence, and tactical reconnaissance command premium pricing for radiation-hardened payloads with encrypted downlinks. The US Space Development Agency and allied military programs are displacing legacy civilian-only demand patterns with proliferated constellation architectures.
- Earth Observation:Land use mapping, urban planning, and environmental compliance generate recurring revenue through subscription data access. North American agricultural software platforms and Australian mining operations represent the most concentrated commercial demand.
- Weather Monitoring:Atmospheric sounding and precipitation radar support national meteorological services and aviation routing.
- Disaster Management:Rapid response imaging for flood, earthquake, and wildfire damage assessment serves insurance and humanitarian organizations.
- Space Exploration:Deep space navigation and planetary science instruments require extreme reliability for extended missions.
- Telecommunications:RF interference monitoring and spectrum management support satellite communication network operators.
Defense Surveillance commands the steepest expansion trajectory as military constellations proliferate. Earth Observation retains the largest installed base of operational sensors.
Orbit Type:
Altitude selection trades revisit frequency against sensor swath width and radiation exposure tolerance.
- Low Earth Orbit:Altitudes below 2,000 kilometers enable high-resolution imaging with rapid revisit cycles. Commercial operators and defense agencies are deploying thousands of small satellites in this regime, driving unit demand for miniaturized MEMS-based sensors.
- Geostationary Orbit:Fixed positioning at 35,786 kilometers supports persistent regional surveillance and communications relay. Radiation-hardened electronics from Honeywell and legacy suppliers dominate this high-altitude, long-lifespan segment.
- Medium Earth Orbit:Intermediate altitudes balance coverage area with latency for navigation augmentation and weather monitoring.
- Highly Elliptical Orbit:Extended dwell time over high latitudes serves arctic communications and missile warning missions.
- Sun-Synchronous Orbit:Consistent solar illumination angles support change detection for land imaging constellations.
- Polar Orbit:Global coverage patterns serve meteorological and oceanographic monitoring programs.
Geostationary Orbit hosts the longest-operational heritage platforms. Low Earth Orbit is gaining share fastest through commercial constellation deployments.
End User:
Customer category determines contracting mechanisms, security clearances, and data rights frameworks.
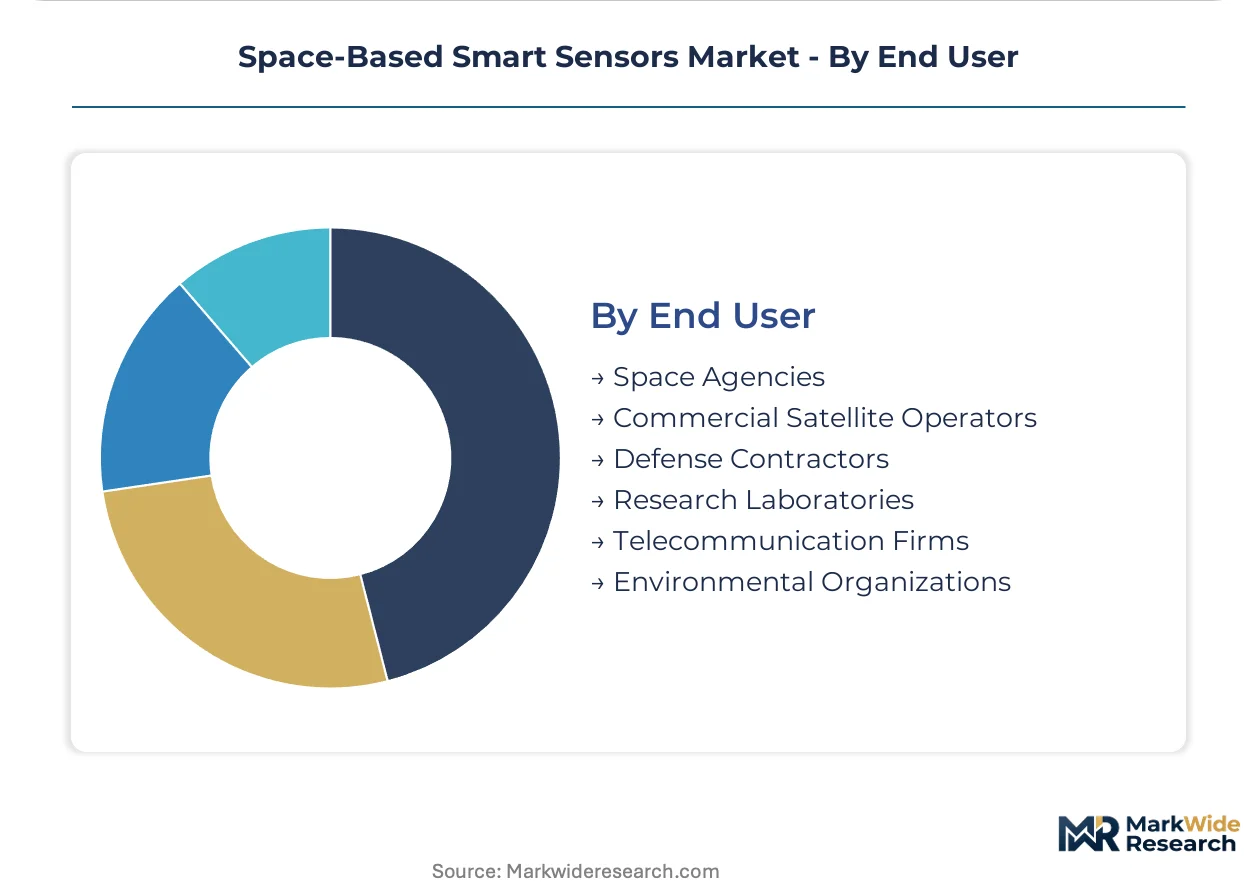
- Space Agencies:NASA, ESA, and national programs fund technology demonstration missions and climate science constellations with extended development timelines and rigorous TRL certification requirements.
- Defense Contractors:Classified programs from the US Space Force and NATO members drive demand for sovereign manufacturing and encrypted supply chains.
- Commercial Satellite Operators:Planet Labs, Maxar, and emerging ventures pursue volume production of standardized payloads for recurring Earth observation services.
- Research Laboratories:University and government science programs access hosted payload opportunities and rideshare launches for experimental instruments.
- Telecommunication Firms:Satellite operators procure RF monitoring sensors for spectrum coordination and interference geolocation.
- Environmental Organizations:Non-governmental monitoring programs leverage open data policies and commercial tasking services for conservation and climate accountability.
Space Agencies retain established procurement relationships with heritage suppliers. Commercial Satellite Operators are forcing supplier adaptation toward batch production and rapid iteration cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spaceport development zones in the United States concentrate sensor payload engineering talent and radiation-hardened electronics manufacturing. Sovereign satellite programs across allied nations drive qualification demand for export-controlled components.
United States
NASA's Earth System Observatory and Space Development Agency constellations anchor procurement volume for miniaturized MEMS arrays. FCC orbital debris rules and ITAR classifications from the State Department tighten qualification timelines for non-allied suppliers. Colorado and California host the densest clusters of payload integrators serving defense-classified missions.
France
Thales Alenia Space anchors European sovereign Earth observation programs with dual-use platform demand. ESA's Clean Space initiative and REACH substance restrictions impose supply chain documentation burdens on adhesive and coating suppliers. Toulouse and Paris-Saclay concentrate photonic integrated circuit development for automated optical beam steering.
Germany
Bavaria-based sensor electronics specialists serve ESA security component programs with radiation-hardened qualification requirements. The EU Space Programme's security classification segments market access between allied and non-allied component vendors. Munich and Oberpfaffenhofen host clusters for hyperspectral instrument calibration and thermal focal plane array testing.
United Kingdom
BAE Systems plc and defense contractors drive demand for encrypted downlink payloads under NATO's 2022 Strategic Concept space endorsement. UK Space Agency funding for national Earth observation infrastructure competes with commercial constellation operators for component supply. Harwell Space Cluster and Glasgow's satellite manufacturing corridor concentrate small satellite payload integration.
Japan
METI-funded commercial Earth observation ventures expand procurement for standardized optical and radar sensors. JAXA technology demonstration missions impose NASA-equivalent TRL-8 certification requirements on domestic suppliers. Tsukuba and Tokyo host clusters for silicon-on-insulator fabrication serving geostationary orbit mission lifespans.
Space-Based Smart Sensors Market Competitive Landscape
Top-tier vendors anchor defense-classified procurement, while mid-tier specialists compete for commercial constellation batch contracts. The vendor base stratifies across radiation-hardened heritage suppliers, MEMS miniaturization specialists, and photonic integration disruptors. Strategic archetypes include sovereign manufacturing champions, commercial volume producers, and dual-use platform integrators. Competitive moves concentrate on vertical integration into sensor electronics fabrication and strategic partnerships for constellation data services.
Within the defense heritage tier, Northrop Grumman Corporation and RTX Corporation exemplify strategic payload integration positions anchored in US Space Force acquisition channels. Thales Alenia Space occupies a parallel European sovereign manufacturing position serving ESA and NATO member state programs. Honeywell International Inc. represents the radiation-hardened electronics specialization archetype, with qualification heritage spanning geostationary and medium-Earth orbit mission profiles.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Teledyne Technologies Incorporated |
| RTX Corporation |
| Northrop Grumman Corporation |
| Airbus Defence and Space |
| Moog Inc. |
| BAE Systems plc |
| Thales Alenia Space |
| Ball Aerospace & Technologies Corp. |
| Others |
Pricing and Supply Chain Analysis
MEMS miniaturization and batch production methods for orbital sensor nodes are compressing unit economics while concentrating supply relationships among radiation-hardened foundries in the United States, Japan, and Germany. This manufacturing transition simultaneously lowers per-satellite payload costs and raises barriers for entrants lacking certified fabrication partnerships, embedding pricing power with heritage suppliers.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with defense agencies paying substantial markups for ITAR-compliant components deliverable under accelerated schedules. The market operates on a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by NASA TRL-8 certification status and radiation-hardening grade. Cost compression in commercial LEO constellations is intensifying because standardized MEMS arrays enable volume purchasing, though sovereign defense programs remain least price-sensitive due to mission-critical reliability requirements.
Supply Chain Analysis
Certification gating through NASA Technology Readiness Level requirements and FCC orbital debris mandates restricts qualified supplier pools to established radiation-hardened electronics specialists. Supply concentrates in the United States, Japan, and Germany for silicon-on-insulator fabrication, with critical dependencies on gallium arsenide substrates, specialized optical coatings, and space-grade adhesives. Single-source vulnerability sits with domestic rare earth processing for permanent magnet components in attitude control systems. Distribution runs through prime defense contractors and commercial constellation operators directly sourcing from qualified payload integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiation-hardened foundry capacity constraints prop pricing power for certified suppliers, as defense and commercial constellation demand outpaces qualified fabrication expansion.
For Market Incumbents: Deploy backward integration into captive silicon-on-insulator wafer production to secure supply continuity against emerging foundry competition. Lock in multi-year offtake agreements with gallium arsenide substrate suppliers before commodity volatility escalates. Reinforce certification moats by accelerating NASA TRL-8 validation pipelines for next-generation photonic integrated circuits.
For New Entrants and Emerging Players: Agricultural analytics platforms in Australia and North America represent the most penetrable buyer archetype, with farm management software penetration creating bundled sensor-data demand. India's expanding commercial launch capacity offers constellation deployment partnerships outside ITAR-restricted channels. Pursue hosted payload rideshare arrangements with established satellite buses to bypass full qualification timelines.
For Investors and Strategic Acquirers: Re-rating potential sits with dual-use platform integrators given NATO's 2022 space domain endorsement accelerating member state procurement coordination. Long-term viability favors vendors with sovereign manufacturing footprints spanning both US Space Force and ESA security component programs. Monitor FCC licensing backlogs as an inflection indicator for commercial constellation deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Development | Automated optical beam steering collapses sensor package volumes by sixty percent while preserving sub-meter resolution. |
| Radiation-Hardened Electronics Certification | NASA TRL-8 validation creates eighteen-to-thirty-six-month bottlenecks that protect incumbent supplier positions. |
| Constellation Data Service Partnerships | Subscription-based analytics platforms unbundle raw pixel delivery from machine-learning-derived agricultural insights. |
| MEMS Miniaturization Scale-Up | Batch production of sub-fifty-kilogram sensor nodes enables proliferated LEO architectures for defense surveillance. |
| Sovereign Manufacturing Footprint Expansion | ITAR and EU Space Programme security classifications segment market access between allied and non-allied component vendors. |
Research Methodology
SEC 10-K filings, ESA procurement databases, and FCC licensing records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with satellite payload engineering directors, defense procurement officers at Space Development Agency programs, radiation-hardened electronics fabrication managers, and commercial constellation operators validated demand assumptions and pricing dynamics. Bottom-up unit economics for MEMS sensor arrays and top-down budget analysis for NASA and ESA programs were triangulated to anchor volume projections.
Historical trendline analysis across defense surveillance, Earth observation, and weather monitoring applications established baseline growth patterns without assuming discontinuities. The analytical framework segmented by sensor type, orbit regime, and end-user category across the projection horizon, with CAGRs derived from procurement pipeline visibility and constellation deployment schedules. Industry-specific inputs included Space Development Agency proliferated architecture timelines and ESA Clean Space initiative compliance cost trajectories.
Revisions become necessary when ITAR classification expansions, launch cost volatility spikes, or orbital debris regulatory tightening materialize beyond baseline assumptions. Forecasts reflect documented assumptions about radiation-hardening yield rates and qualification timeline stability. A model refresh is warranted upon material change in US Space Force acquisition directive pacing or commercial launch provider consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Rover Market
Space
Space Travel Market
Space
India Aviation, Defense, and Space Market
Space
Space Mobile Service Market
Space
Europe Space Electronics Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Ground System Market
Space
Space Designing Market
Space
Space As a Service Market
Space
China Space Electronics Market
Space
China Space Propulsion System Market
Space
Germany Space Electronics Market
Space
Space Wheel Market
Space
Space Mining Market
Space
Space Launch Services Market
Space
Space Service Market