
 Japan Coffee and Tea Capsules Market | 2026-2036
Japan Coffee and Tea Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Coffee and Tea Capsules Market Intelligence
Convenience store distribution is tilting toward premium capsule lines as Lawson and 7-Eleven expand dedicated beverage sections. UCC Holdings Co., Ltd. leverages its integrated roasting infrastructure to control quality from bean to capsule. Nestle SA anchors the competitive set through Nespresso's boutique retail presence in Osaka and Tokyo. Ajinomoto AGF, Inc. differentiates via instant-coffee-to-capsule migration strategies targeting aging household brewers.
Coffee and tea capsules are single-serve, sealed containers—typically aluminum or plastic—containing pre-portioned ground coffee or leaf tea designed for extraction under pressure at 9-19 bar. These units eliminate measurement variance and reduce preparation time to under 60 seconds, serving both commercial foodservice and residential morning-ritual applications. Coffee commands the dominant value pool, while green tea capsules capture fastest volume growth as domestic consumers seek familiar flavors in compatible formats. The packaging type dimension shows cup-format dominance in household channels, whereas pouch variants gain traction in office procurement for their reduced storage footprint.
METI's resource circulation policies and the Container and Packaging Recycling Law compel manufacturers to fund collection infrastructure and meet material-specific recovery targets, directly raising compliance costs for imported brands. JIS standards for food-contact materials further constrain capsule shell composition, favoring domestic suppliers with established testing protocols. Stakeholders must monitor METI's evolving extended producer responsibility guidelines and assess whether aluminum recycling investments or biodegradable material pivots offer superior long-term cost positions.
Market Dynamics
Japan's Container and Packaging Recycling Law is forcing manufacturers to fund aluminum and plastic recovery infrastructure, raising compliance costs while METI's extended producer responsibility guidelines push domestic suppliers toward biodegradable shell materials.
Growth Catalysts
- Office Breakroom Modernization:Employers across Greater Tokyo are installing single-serve brewing systems to attract hybrid workers, expanding commercial procurement channels beyond traditional retail.
- METI Resource Circulation Policies:Government mandates for material recovery are accelerating investment in closed-loop aluminum collection networks, creating compliant supply advantages for domestic producers.
- Green Tea Format Migration:Domestic consumers are adopting leaf tea capsules as a bridge between traditional brewing rituals and convenience demands, driving fastest volume expansion in household channels.
Market Restraints
- Aluminum Input Volatility:Global commodity price swings for cup-format shell materials compress margin stability for premium product lines.
- Import Brand Compliance Burden:Foreign manufacturers face JIS food-contact material testing protocols and recycling law fund contributions that domestic incumbents have already amortized.
- Instant Coffee Substitution:Ajinomoto AGF's established instant coffee infrastructure retains price-sensitive household segments resistant to capsule conversion.
Strategic Opportunities
- Biodegradable Material Pivot:PLA and paper-based shell innovations aligned with METI's carbon neutrality roadmap offer first-mover positioning against aluminum-dependent competitors.
- Convenience Store Premiumization:Lawson and 7-Eleven dedicated beverage sections create direct-to-consumer channels for specialty capsule lines previously confined to boutique retail.
- Osaka-Kobe Manufacturing Cluster:Western Japan's packaging technology corridor enables co-location of roasting and shell-forming operations for integrated cost control.
Industry Challenges
- Extended Producer Responsibility Timeline:Manufacturers must retrofit collection infrastructure to meet escalating recovery targets under the Container and Packaging Recycling Law without guaranteed consumer participation rates.
- Cross-Format Compatibility Fragmentation:Proprietary brewing system architectures force capsule producers to maintain multiple tooling configurations, inflating SKU complexity and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Coffee and Tea Capsules Market |
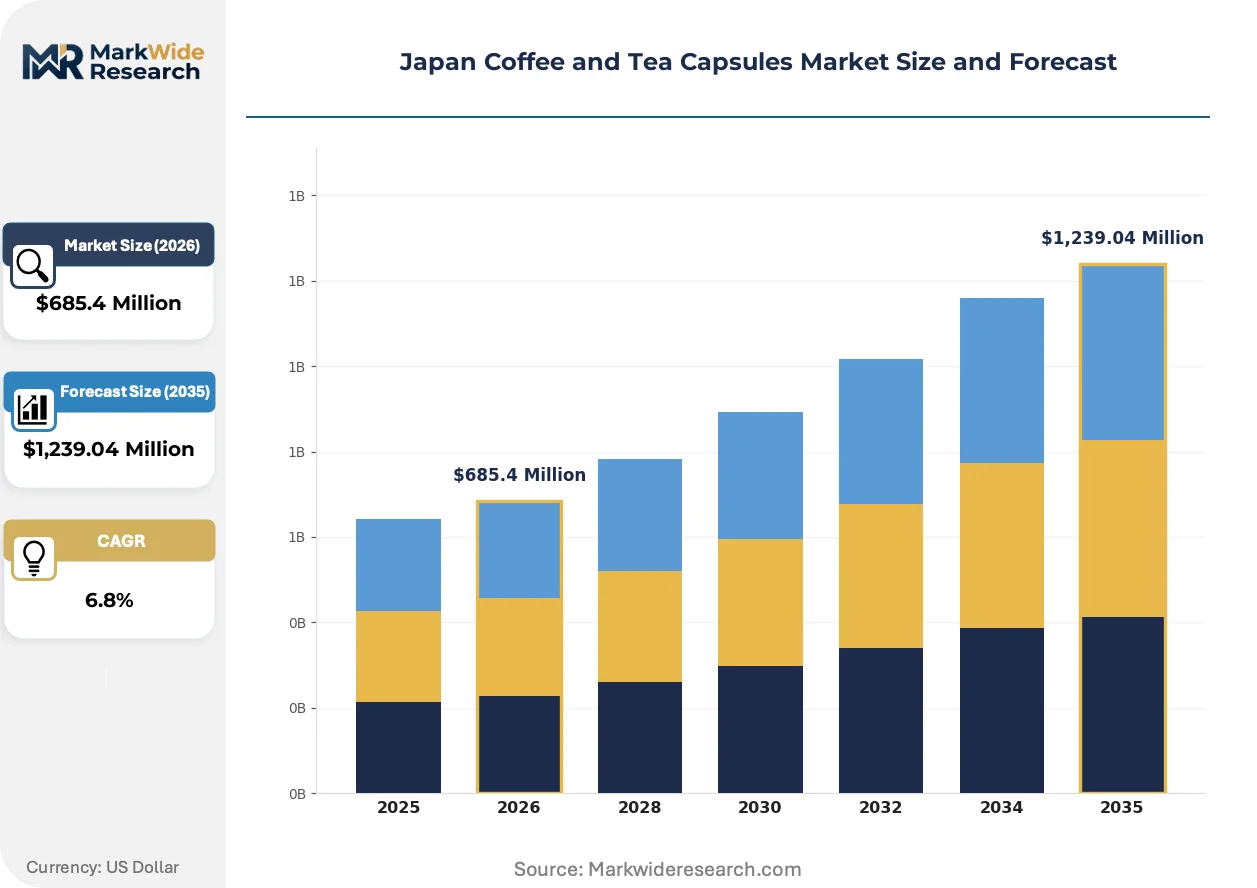
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee, Herbal Tea, Green Tea, Instant Coffee Packaging Type: Cup, Pouch, Box, Sleeve End User: Households, Offices, Cafes, Retailers Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | Key Coffee Inc., UCC Holdings Co., Ltd., Nestle SA, Sapporo Holdings Ltd., Kataoka & Co., Ltd., Starbucks Corp., Ajinomoto AGF, Inc., Melitta Japan Ltd., The Coca Cola Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Coffee and Tea Capsules Market Strategic Shifts & Innovations
Pressure-extraction brewing systems are digitizing flavor profiling while regulatory compliance requirements and channel consolidation reshape how capsules reach Japanese consumers.
Smart brewing connectivity is digitizing extraction parameter control across office and residential installations. Nespresso's Bluetooth-enabled machines transmit usage telemetry to roasters, enabling predictive replenishment and personalized intensity recommendations. This data layer is digitizing traditional brand-consumer relationships into subscription-driven recurring revenue models.
METI's evolving extended producer responsibility guidelines are tightening material recovery mandates for aluminum and plastic capsules. Manufacturers must now fund dedicated collection infrastructure and report transparent recovery rates to prefectural authorities. Domestic incumbents with established testing protocols under JIS food-contact standards are responding faster than import brands facing dual compliance burdens.
Convenience store beverage sections are displacing supermarket dominance as the primary discovery channel for premium capsule trials. Lawson and 7-Eleven dedicated shelf space allows single-unit purchases that lower trial barriers for aging household brewers migrating from instant formats. This channel rotation is most visible in Greater Tokyo's dense commercial corridors where grab-and-go consumption patterns dominate morning rituals.
Japan Coffee and Tea Capsules Market Segmentation
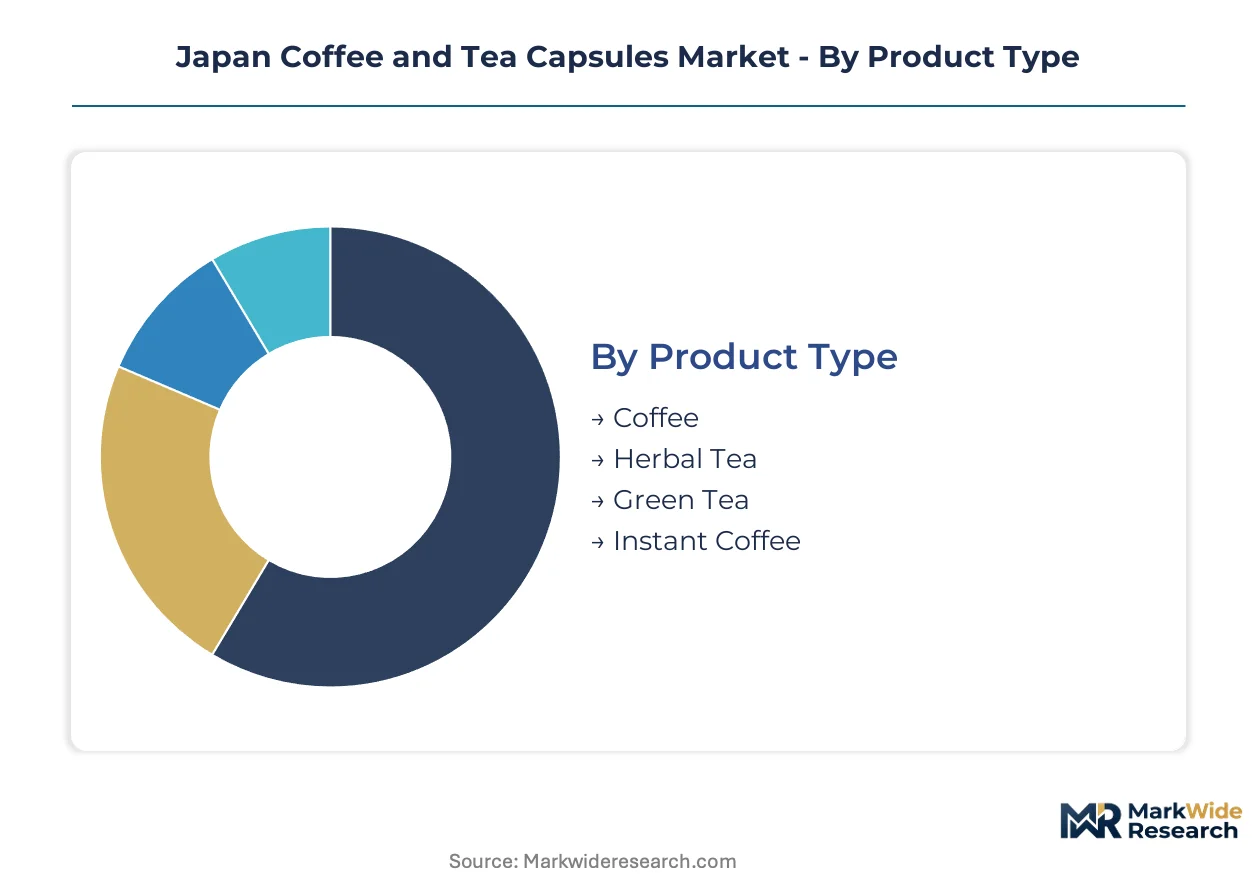
Japan's coffee and tea capsules market fragments across four dimensions that determine service intensity, margin structure, and compliance exposure. Each category reveals distinct procurement patterns shaped by METI recycling mandates and channel consolidation in Greater Tokyo.
Product Type:
After-sales service intensity varies sharply by product type, with coffee capsules requiring machine calibration support while tea formats demand less technical intervention.
- Coffee:Roasted and ground arabica or robusta formulations sealed in aluminum or plastic shells for 9-19 bar extraction systems. Demand concentrates in Greater Tokyo office corridors where employers modernize breakroom amenities to attract hybrid workers, though aluminum input volatility compresses margin stability for premium lines.
- Green Tea:Sencha and matcha powders adapted to pressure-extraction brewing, capturing domestic consumers seeking familiar flavors in compatible formats. Volume expansion runs fastest in household channels as aging brewers migrate from traditional teapots.
- Herbal Tea:Caffeine-free infusions including barley and brown rice variants targeting evening consumption occasions.
- Instant Coffee:Spray-dried or freeze-dried granules in capsule-compatible formats bridging price-sensitive segments resistant to full conversion.
By volume, coffee leads. By growth pace, green tea is ahead.
Packaging Type:
Cost tier stratification separates premium aluminum cup formats from economy pouch variants, with material choice directly impacting METI compliance fund obligations.
- Cup:Aluminum or plastic shells with foil lids enabling pressure-sealed freshness barriers. Household channels in Osaka and Tokyo dominate procurement, though manufacturers face escalating Container and Packaging Recycling Law fund contributions per unit.
- Pouch:Flexible film sachets with reduced storage footprint and lower material recovery costs. Office procurement channels across Greater Tokyo favor this format for inventory efficiency in constrained breakroom spaces.
- Box:Multi-unit cardboard enclosures for pantry-stock purchasing patterns in suburban households.
- Sleeve:Band-wrapped configurations for promotional bundling in convenience store channels.
Cup formats command value share leadership. Pouch variants are expanding most quickly in commercial procurement.
End User:
Application context determines brewing system specifications, with offices requiring high-throughput durability and households prioritizing compact footprint.
- Households:Residential morning-ritual consumption across single-family and multi-unit dwellings. Greater Tokyo's dense corridors concentrate demand, with aging consumers driving green tea capsule trials as a bridge from instant formats.
- Offices:Commercial foodservice installations in corporate towers and shared workspaces. Hybrid work policies are accelerating single-serve system deployment as amenity competition intensifies.
- Cafes:Specialty coffee shops leveraging capsules for consistency in high-turnover environments.
- Retailers:Convenience store and supermarket beverage sections using capsules for in-store preparation and sampling.
Households anchor volume. Offices are climbing the fastest as breakroom modernization budgets expand.
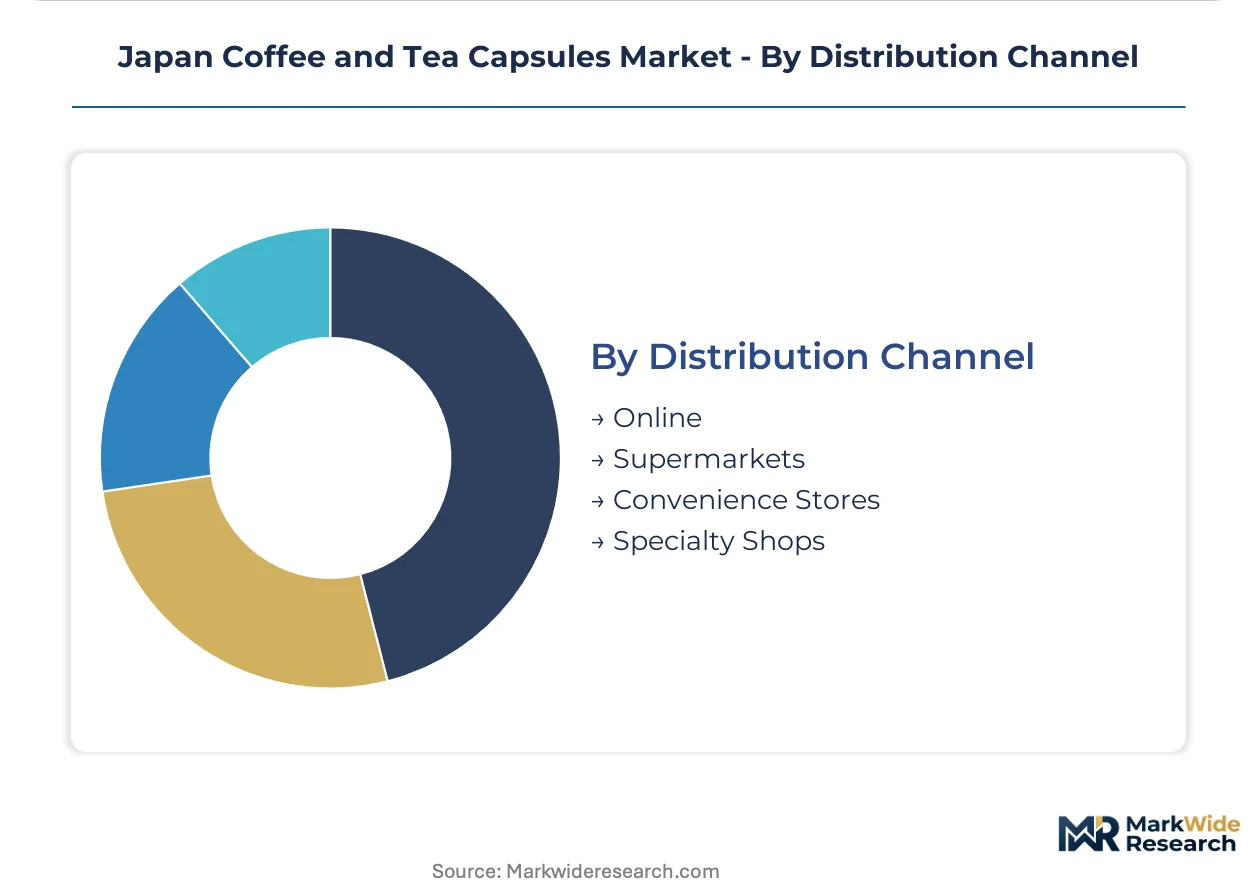
Distribution Channel:
Channel consolidation is displacing traditional supermarket dominance, with convenience stores capturing premium trial occasions through dedicated beverage sections.
- Convenience Stores:Lawson and 7-Eleven dedicated shelf space enabling single-unit purchases. Greater Tokyo's grab-and-go corridors concentrate this channel's importance for premium line discovery.
- Online:Direct-to-subscription platforms and marketplace fulfillment. Smart brewing connectivity enables predictive replenishment models tied to machine telemetry.
- Supermarkets:Multi-brand pantry-stock purchasing with declining share as convenience formats capture immediate consumption occasions.
- Specialty Shops:Boutique retail in Osaka and Tokyo offering machine demonstration and flavor profiling services.
Convenience stores lead by transaction velocity. Online channels are gaining share fastest through subscription conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's Container and Packaging Recycling Law shapes manufacturer obligations across Japan's coffee and tea capsules market, with compliance requirements varying by prefectural industrial density and collection infrastructure maturity.
Greater Tokyo
Corporate breakroom modernization drives single-serve system procurement in Shinjuku and Marunouchi towers. The Tokyo Metropolitan Government enforces stricter recovery reporting than national baselines. Dense residential corridors in Setagaya and Minato concentrate household green tea capsule trials among aging consumers migrating from instant formats.
Kansai
Osaka's boutique retail presence anchors premium discovery channels through machine demonstration services. Kyoto Prefecture's traditional tea culture accelerates matcha capsule format experimentation. The Osaka-Kobe manufacturing cluster enables co-location of roasting and shell-forming operations for integrated cost control.
Chubu
Nagoya's automotive supplier offices adopt commercial brewing systems as hybrid work amenities. Aichi Prefecture's packaging technology base supports biodegradable material pilot programs. Toyota City corporate campuses generate concentrated demand for high-throughput office installations.
Kyushu
Fukuoka's startup ecosystem experiments with smart brewing connectivity and subscription models. Local governments in Saga and Kumamoto trial rural collection infrastructure for aluminum recovery. Kitakyushu's industrial heritage supports secondary material processing partnerships.
Hokkaido
Sapporo's distinct seasonal consumption patterns create demand for hot beverage convenience formats. The prefecture's lower population density challenges cost-effective collection network deployment. Otaru's logistics hub position enables northern distribution efficiency for domestic brands.
Japan Coffee and Tea Capsules Market Key Industry Players
Integrated beverage conglomerates and specialized coffee roasters split the market into complementary competitive spheres. Domestic incumbents leverage amortized compliance infrastructure under METI guidelines, while import brands absorb dual regulatory burdens. Two strategic archetypes dominate: vertically integrated roasters controlling bean-to-capsule quality chains, and format-agnostic distributors spanning instant, roast, and capsule portfolios. Competitive moves concentrate on convenience store channel expansion and biodegradable material pivots aligned with carbon neutrality roadmaps.
Among Japan-based operators, UCC Holdings Co., Ltd. and Ajinomoto AGF, Inc. exemplify contrasting archetype positioning. Nestle SA occupies a distinct tier through boutique retail presence and smart brewing ecosystem development. Key Coffee Inc. represents the mid-market roasting specialist segment with regional distribution density.
| Leading Market Players |
|---|
| Key Coffee Inc. |
| UCC Holdings Co., Ltd. |
| Nestle SA |
| Sapporo Holdings Ltd. |
| Kataoka & Co., Ltd. |
| Starbucks Corp. |
| Ajinomoto AGF, Inc. |
| Melitta Japan Ltd. |
| The Coca Cola Company |
| Others |
Cost & Logistics Intelligence
Overcapacity in aluminum cup-format shell production across Greater Tokyo is compressing supplier margins while forcing manufacturers toward biodegradable material pivots. This utilization squeeze simultaneously intensifies price competition in premium tiers and accelerates consolidation among domestic incumbents with amortized METI compliance infrastructure.
Pricing Analysis
Greater Tokyo commands a 15-20% premium over Kansai and Kyushu for identical capsule SKUs due to breakroom amenity competition and dense commercial corridor demand. Three-tier pricing structure across premium, standard, and economy levels separates boutique retail lines from convenience store mid-tier and private-label economy formats. Pricing pressure stems from aluminum input volatility and import brand compliance burdens under JIS testing protocols. Household segments in suburban corridors exhibit highest price sensitivity, while corporate procurement in Marunouchi towers prioritizes service bundling over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced biodegradable polymer formulations from European suppliers limit domestic access to next-generation shell materials. Raw material sourcing draws from Indonesia for aluminum ore, Germany for precision-forming equipment, and domestic Aichi Prefecture for packaging technology. Single-source vulnerability concentrates in aluminum foil lid supply from concentrated Asian smelters. Distribution runs through Osaka-Kobe manufacturing clusters for western supply, with Tokyo Metropolitan hub handling Greater Tokyo final-mile deployment to convenience store and office channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's coffee and tea capsules market is approaching a platform-economics inflection as smart brewing connectivity and proprietary system architectures create winner-take-most dynamics. Interoperability fragmentation across Nespresso, UCC, and third-party formats is locking consumers into ecosystem-specific capsule portfolios.
For Market Incumbents: Harden defensive moats by deepening backward integration into Aichi Prefecture packaging technology corridors and securing exclusive convenience store shelf space agreements with Lawson and 7-Eleven. METI's escalating extended producer responsibility timelines threaten import competitors with unamortized compliance costs; domestic incumbents should accelerate aluminum recovery network deployment to widen this structural advantage. For New Entrants and Emerging Players: Build out white-space positions in biodegradable material segments aligned with carbon neutrality roadmaps, where established players face sunk-cost constraints in aluminum infrastructure. Kyushu's Fukuoka startup ecosystem offers lowest competitive density for smart brewing connectivity experiments; target subscription-enabled direct-to-consumer models bypassing fragmented retail gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable shell R&D and closed-loop collection infrastructure. Long-term viability favors vertically integrated roasters with captive bean-to-capsule quality control over format-agnostic distributors exposed to instant coffee substitution. Watch for METI recovery target announcements as inflection signals: accelerated timelines would force aluminum-dependent competitors into expensive retrofit cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Pivot | PLA and paper-based shell innovations align with METI carbon neutrality mandates and reduce compliance fund obligations. |
| Convenience Store Premiumization | Lawson and 7-Eleven dedicated beverage sections enable single-unit trial purchases lowering household conversion barriers. |
| Smart Brewing Connectivity | Bluetooth-enabled machines transmitting usage telemetry enable predictive replenishment and subscription revenue lock-in. |
| Osaka-Kobe Manufacturing Cluster Expansion | Co-location of roasting and shell-forming operations reduces logistics costs and JIS compliance testing timelines. |
| Closed-Loop Collection Infrastructure | Dedicated aluminum recovery networks satisfy Container and Packaging Recycling Law targets ahead of prefectural enforcement. |
Research Approach
Operator-level perspectives from category buyers at Lawson and 7-Eleven, procurement managers in Tokyo corporate towers, and plant engineers at Aichi packaging facilities anchored the qualitative base. These primary interviews combined with METI policy filings, JIS standards documentation, Container and Packaging Recycling Law enforcement records, and customs trade data for aluminum and polymer inputs. Bottom-up demand modeling across household, office, and foodservice channels triangulated against top-down manufacturer capacity assessments.
Scenario-bracketing framed projections across conservative, baseline, and accelerated adoption paths for biodegradable materials and smart brewing penetration. Segmentation dimensions modeled include product type, packaging format, end-user application, and distribution channel, with additional granularity on brewing system compatibility. CAGRs derived from elasticity-adjusted volume trajectories and value-per-unit trends across the projection horizon, incorporating aluminum commodity price scenarios and compliance cost escalations under evolving extended producer responsibility guidelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-led entrants or platform-ecosystem players would shift outcomes. Material shifts in METI recovery target timelines, biodegradable material performance breakthroughs, or cross-format compatibility standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Office Coffee Service (OCS) Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
North America Specialty Coffee Market
Coffee
Cold Brew Coffee Market
Coffee
Coffee Syrup Market
Coffee
Middle East and Africa Coffee Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Portable Espresso Machines Market
Coffee
Single Origin Coffee Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Coffee Roaster Machine Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market