
 Coffee Brewers Market | 2026-2036
Coffee Brewers Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Brewers Market Outlook
Market Context
A shift from single-source component procurement toward multi-source supplier networks is pivoting how coffee brewer manufacturers manage cost volatility and resin availability. Keurig Dr Pepper leverages its captive pod ecosystem to control recurring revenue streams. De'Longhi Group anchors its competitiveness in European espresso engineering heritage. Breville Group differentiates through PID temperature control systems targeting enthusiast households.
Technical Definition and Segment Structure
Coffee brewers encompass electromechanical appliances designed to heat water to precise temperatures between 195°F and 205°F and distribute it across ground coffee under controlled pressure or gravity for extraction. These devices serve commercial foodservice operators and residential consumers seeking consistent beverage quality without manual intervention. Drip coffee makers occupy the mature volume tier with thin margins concentrated in big-box retail channels, while single serve brewers capture the fastest-growing installed base through pod-based convenience protocols. Smart technology integration represents the emerging margin pool as programmable connectivity commands premium positioning across household and office end users.
Regulatory Environment
The US Department of Energy enforces standby power limits under appliance efficiency standards, while the EU Ecodesign Directive and REACH chemical frameworks constrain material selection and energy profiles for brewers sold in member states. China's GB standards and NMPA-equivalent quality certifications shape import requirements for foreign manufacturers accessing domestic retail channels. Stakeholders must monitor evolving extended producer responsibility mandates for single-use pod waste recovery across multiple jurisdictions.
Market Dynamics
Precision temperature control systems and pod-based convenience protocols are compressing traditional drip coffee maker margins while reshaping supplier relationships across resin-dependent electromechanical supply chains.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits are accelerating R&D investment in low-energy heating elements across German and Italian manufacturing bases.
- Specialty cafe chains:Seoul and Tokyo espresso bars are driving specification upgrades for PID-controlled machines with ±1°F accuracy in commercial foodservice procurement.
- Multi-source resin networks:Diversified polymer procurement is insulating assemblers from single-supplier price volatility in polycarbonate and ABS housing materials.
Market Restraints
- Copper and aluminum input volatility:Heating element raw material costs swing with LME pricing, compressing margin on entry-level drip models.
- Single-use pod extended producer responsibility:France and Germany are implementing mandatory recovery schemes that add compliance overhead to pod-dependent revenue models.
- Thermal carafe technical ceiling:Vacuum insulation performance plateaus against consumer expectations for four-hour heat retention without volume sacrifice.
Strategic Opportunities
- Smart home integration:Matter protocol adoption is enabling voice-activated brewing schedules through Alexa and Google Home ecosystems in North American households.
- India premium household segment:Underpenetrated espresso machine ownership among urban upper-middle-class consumers offers whitespace for 15-bar pump systems.
- China GB standards alignment:NMPA-equivalent quality certification streamlines import pathways for European manufacturers targeting tier-one city retail channels.
Industry Challenges
- Embedded systems firmware talent:Shortage of IoT security specialists delays smart brewer app development and OTA update pipelines.
- REACH chemical compliance timelines:Substance of very high concern screenings extend new material qualification cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Brewers Market |
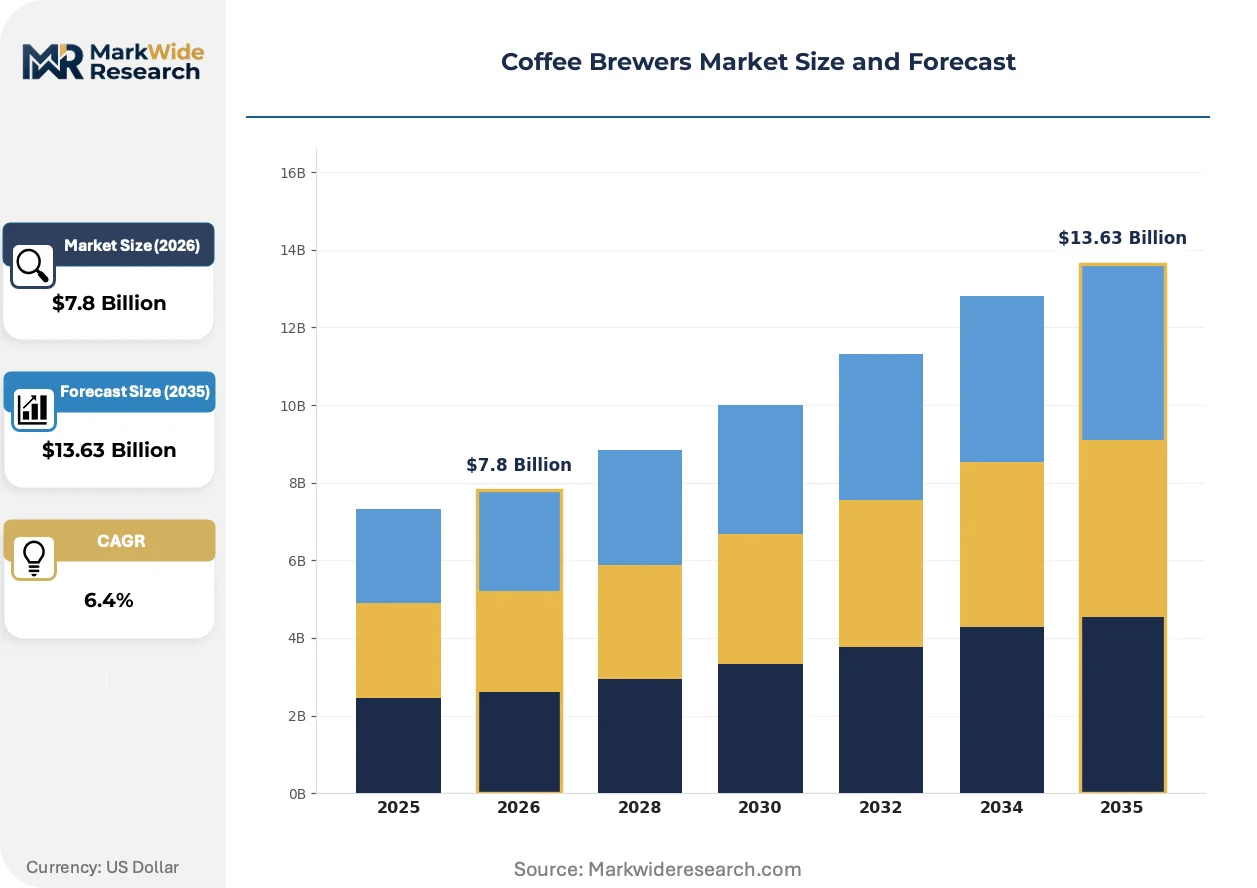
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Coffee Makers, Espresso Machines, French Presses, Single Serve Brewers Technology: Automatic, Manual, Programmable, Smart Technology End User: Households, Cafes, Offices, Restaurants Price Tier: Premium, Mid Range, Budget, Luxury |
| Companies Covered | Keurig Dr Pepper, Nestlé Nespresso, De’Longhi Group, Breville Group, Philips, Hamilton Beach Brands, BUNN, SharkNinja Operating, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Brewers Market Strategic Shifts
Brewing technology is converging around connectivity, sustainability mandates, and precision extraction control that elevates enthusiast-grade features into mass-market price bands.
PID temperature controllers with integrated pressure profiling are unifying espresso and drip functionality within single appliances. Enthusiast households in the US and Australia are adopting these hybrid systems at triple the rate of conventional single-format machines. This convergence is compressing the addressable market for standalone drip brewers while expanding average selling prices in the premium tier.
REACH chemical frameworks and RoHS substance restrictions are constraining heating element alloys and plasticizer selection for EU-bound production. Manufacturers are substituting brominated flame retardants with phosphorus-based alternatives in control board housings. German and Dutch assemblers are absorbing six to nine month material requalification cycles to maintain CE marking compliance.
Direct-to-consumer subscription models for consumables are displacing traditional retail pod replenishment patterns. Roaster-owned channels in the US and UK are capturing recurring revenue through auto-ship algorithms tied to usage telemetry. This channel shift is most visible among millennial and Gen Z households in coastal metropolitan areas where brand loyalty concentrates around single-origin sourcing narratives.
Coffee Brewers Market Segmentation
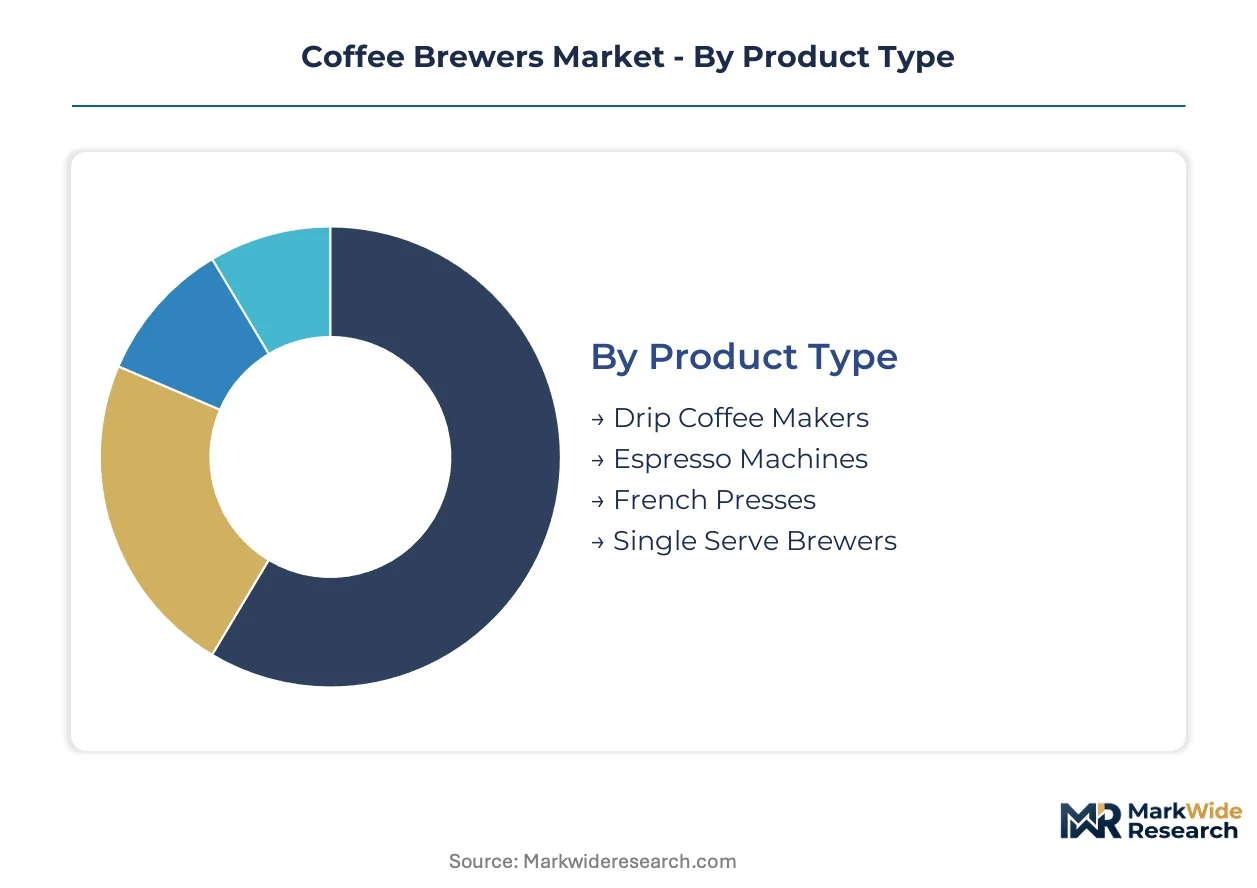
Coffee brewer segmentation reveals how extraction method, automation level, and procurement context shape margin structures differently. Manufacturers must align R&D pipelines and channel strategies to the specific performance expectations and price elasticity within each slice.
Product Type:
Buyers in this category separate by their tolerance for preparation time versus beverage consistency guarantees.
- Drip Coffee Makers:Gravity-fed systems with flat-bottom or conical filter baskets dominate household volume through sub-$100 price accessibility. Demand concentrates in US big-box retail where replacement cycles average five to seven years and brand loyalty remains thin.
- Single Serve Brewers:Pod-based systems with pressurized water injection deliver portion-controlled convenience through proprietary capsule ecosystems. German and Japanese households drive specification upgrades toward recyclable aluminum pods as extended producer responsibility schemes tighten compliance overhead.
- Espresso Machines:Pump-driven systems generating 9-15 bar pressure for crema extraction target enthusiast households and commercial operators seeking café-grade output.
- French Presses:Immersion brewing devices with mesh-plunger filtration appeal to manual-preference consumers prioritizing equipment simplicity and zero electricity dependency.
Drip coffee makers lead volumes today; single serve brewers are gaining share fastest.
Technology:
Automation depth determines component cost structures and firmware development requirements across this dimension.
- Smart Technology:WiFi-enabled systems with app-based scheduling, usage telemetry, and OTA firmware updates command premium positioning in North American households. Matter protocol adoption is accelerating voice integration through Alexa and Google Home ecosystems.
- Programmable:Timer-based systems with LCD interfaces and thermal carafe warming plates balance convenience against cost in mid-market positioning.
- Automatic:One-touch operation with integrated grinders and milk frothing systems targets European households seeking espresso-bar replication without manual skill acquisition.
- Manual:Lever-operated or stove-top systems with no electrical components serve price-sensitive segments and outdoor recreation use cases.
Automatic systems anchor current revenue; smart technology shows the steepest expansion trajectory.
End User:
Procurement authority and usage intensity create divergent durability and certification requirements here.
- Cafes:Commercial espresso bars in Seoul and Tokyo specify PID temperature controllers with ±1°F accuracy for extraction consistency under high-volume operation. These operators prioritize NSF certification and rapid service response networks.
- Households:Residential buyers across Germany's premium segment and India's urban upper-middle class drive divergent demand—precision engineering versus first-time espresso penetration.
- Offices:Workplace procurement favors high-capacity drip systems with thermal carafe distribution and minimal maintenance protocols.
- Restaurants:Foodservice operators balance front-of-house aesthetic requirements against back-of-house throughput needs in equipment selection.
Households dominate installed base; cafes are expanding procurement most aggressively.
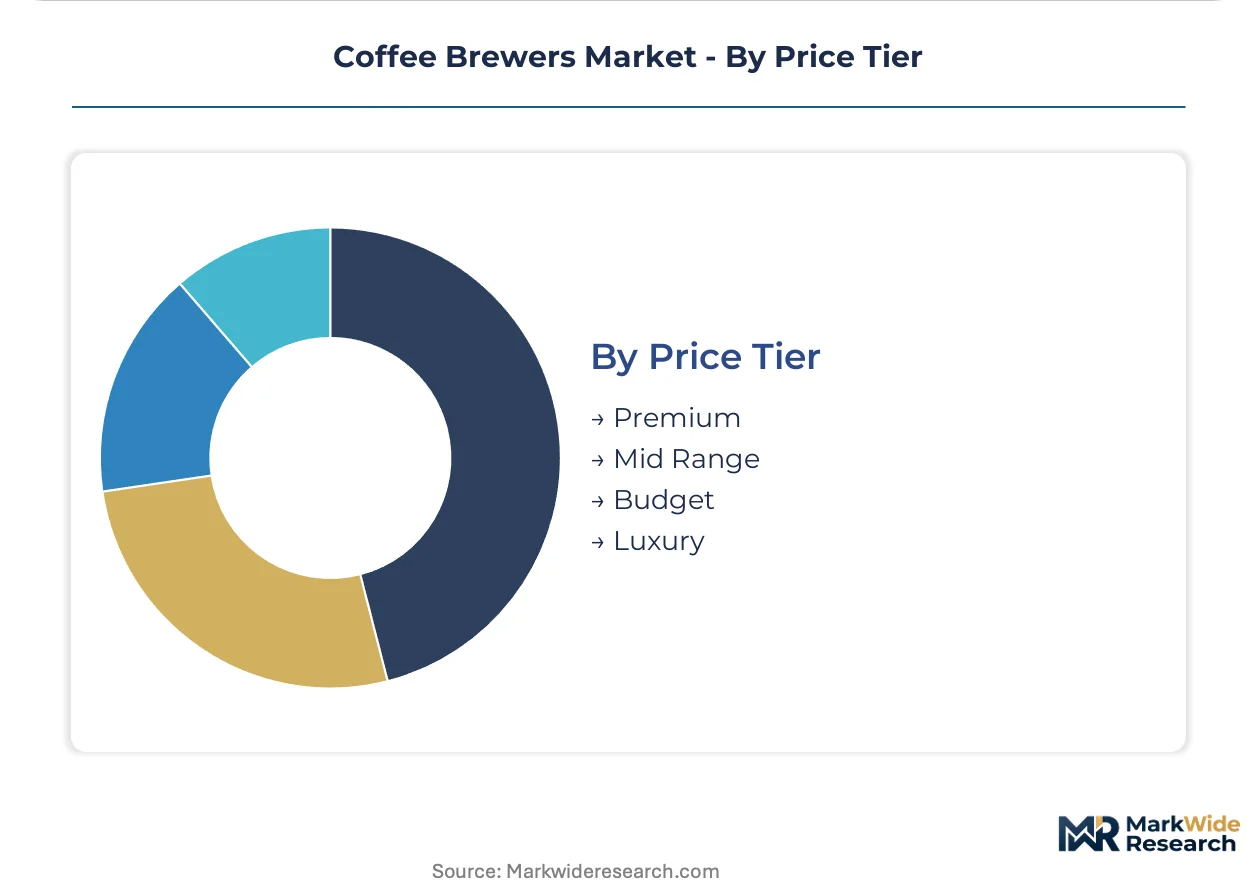
Price Tier:
Margin structure and channel access separate meaningfully across this final dimension.
- Premium:$300-$800 positioning with stainless steel construction, PID control, and dual-boiler systems captures enthusiast households in Australia and the US seeking café-grade extraction.
- Luxury:Custom-finished machines with pressure profiling and integrated grinders target design-conscious buyers in Milan and Tokyo where kitchen appliance aesthetics signal status.
- Mid Range:$100-$300 systems with programmable timers and thermal carafes serve replacement-driven demand in mature markets with moderate feature expectations.
- Budget:Sub-$100 drip systems with plastic construction and glass carafes dominate emerging market penetration and dormitory use cases.
Mid range systems move the highest unit volumes; premium tier is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration patterns in coffee brewer production reflect divergent cost-of-compliance trajectories across jurisdictions. The EU Ecodesign Directive's standby power mandates are accelerating facility relocation toward jurisdictions with lighter appliance efficiency enforcement. Assembly plants in Southeast Asia and Eastern Europe are absorbing capacity shifts from higher-regulation Western European bases.
Germany
Premium household demand for PID-controlled espresso systems drives specification upgrades in Bavaria and North Rhine-Westphalia. The EU Ecodesign Directive enforces standby power limits below one watt for appliances sold in member states. Stuttgart's engineering cluster hosts precision heating element manufacturers supplying temperature control modules to domestic assemblers.
United States
Smart home integration through Matter protocol adoption is reshaping procurement patterns in California and Texas households. The Department of Energy maintains appliance efficiency standards under 10 CFR Part 430 covering standby power consumption. Seattle's Pacific Northwest tech corridor concentrates firmware development talent for IoT-enabled brewing systems.
China
GB standards alignment is streamlining import pathways for European manufacturers targeting Shanghai and Beijing retail channels. The National Medical Products Administration equivalent quality certification shapes domestic market access requirements. The Yangtze River Delta manufacturing belt dominates plastic housing and control board assembly for export-bound production.
Japan
Specialty cafe chains in Tokyo specify commercial espresso equipment with pressure profiling capabilities. The Ministry of Economy, Trade and Industry oversees JIS standards for electrical appliance safety and energy performance. Osaka's Kansai industrial region concentrates precision pump manufacturing for 15-bar extraction systems.
India
Urban upper-middle-class consumers in Maharashtra and Karnataka are driving first-time espresso machine penetration among premium households. The Bureau of Indian Standards mandates ISI certification for electrical heating appliances sold domestically. Bangalore's technology corridor is emerging as a service hub for smart appliance firmware localization.
Coffee Brewers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smart connectivity and subscription-based consumables models. The vendor base clusters around three archetypes: heritage European engineering houses, North American pod-ecosystem operators, and Asian electronics conglomerates with appliance divisions. Consolidation pressure is intensifying as heating element raw material volatility compresses margins on entry-level drip systems. Dominant competitive moves include backward integration into polymer housing production and strategic partnerships with specialty roasters for co-branded equipment.
Among North American pod-ecosystem operators, Keurig Dr Pepper exemplifies the recurring-revenue archetype through captive capsule networks. De'Longhi Group and Breville Group occupy positions within the European heritage engineering tier, anchoring premium positioning through temperature control engineering credibility. These three companies represent distinct strategic postures: ecosystem lock-in, continental engineering heritage, and enthusiast-grade feature democratization respectively.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Nestlé Nespresso |
| De'Longhi Group |
| Breville Group |
| Philips |
| Hamilton Beach Brands |
| BUNN |
| SharkNinja Operating |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Firmware engineering talent concentration in Seattle's Pacific Northwest tech corridor drives labor-cost differentials that widen pricing-tier spreads between smart-enabled premium systems and basic programmable units. These wage premiums for IoT security specialists translate into retail price gaps exceeding two hundred dollars across adjacent feature tiers.
Pricing Analysis
Distributor margin layers absorb fifteen to twenty-five points before retail markup, compressing manufacturer netbacks on entry-level drip systems sold through big-box channels. Three-tier pricing structure across premium, standard, and economy levels separates PID-controlled espresso systems from programmable drip makers from basic gravity-fed units. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the budget tier is intensifying because copper and aluminum LME volatility erodes heating element margins. Dormitory and first-time buyer segments exhibit highest price sensitivity; enthusiast households in Australia and Germany show least elasticity.
Supply Chain Analysis
Returns and refurbishment flows for smart brewers with firmware defects are creating reverse-logistics cost centers that manufacturers now internalize rather than outsource. Component assembly concentrates in China's Yangtze River Delta, Germany's Stuttgart engineering cluster, and Vietnam's emerging electronics belt. Polycarbonate housings, precision heating elements, and control boards draw from resin-dependent electromechanical networks. Single-source vulnerability in specialty pump manufacturing exposes assemblers to disruption. Distribution runs through OEM-direct contracts for commercial foodservice, big-box retail for household volume, and roaster-owned subscription channels for consumables replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Ecodesign Directive's standby power mandates compound demand for low-energy heating elements, creating regulatory-driven upgrade cycles across German and Italian manufacturing bases.
For Market Incumbents: Lock in backward integration into polymer housing production to insulate margin from resin price volatility and REACH compliance delays. Capture channel control through exclusive service networks for commercial espresso bars in Seoul and Tokyo, where NSF certification requirements create switching costs. Prioritize firmware talent retention in Seattle and Bangalore to defend smart product pipelines against emerging Asian electronics conglomerates. For New Entrants and Emerging Players: Voice-activated brewing schedules through Matter protocol adoption offer a technology-first wedge into North American smart home ecosystems. Target India's urban upper-middle-class households in Maharashtra and Karnataka, where first-time espresso penetration remains underdeveloped. Pursue direct-to-consumer subscription models with auto-ship algorithms tied to usage telemetry, displacing traditional retail pod replenishment among millennial coastal metropolitan buyers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier programmable system manufacturers lacking smart connectivity roadmaps. Long-term viability favors players with captive pod ecosystems or precision temperature control IP. Monitor extended producer responsibility scheme implementation across France and Germany as inflection indicator for compliance cost burdens that reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | Matter protocol adoption enables voice-activated brewing through Alexa and Google Home ecosystems. |
| Backward Integration into Polymer Production | Captive supply of polycarbonate housings insulates margin from REACH-driven material requalification cycles. |
| Direct-to-Consumer Subscription Launch | Auto-ship algorithms tied to usage telemetry capture recurring revenue from millennial households. |
| Low-Energy Heating Element R&D | EU Ecodesign Directive compliance below one watt standby power secures CE marking for German retail. |
| Specialty Roaster Partnership | Co-branded equipment with single-origin sourcing narratives builds brand loyalty in coastal metropolitan markets. |
Study Parameters
Multiple input streams — regulatory filings, customs trade records, and appliance retail audit data — were reconciled against primary interviews with heating element manufacturers, firmware development leads, and commercial foodservice procurement directors. Secondary validation drew from EU Ecodesign Directive documentation, GB standards publications, and SEC filings of publicly traded appliance manufacturers. Bottom-up unit economics and top-down market sizing were triangulated to constrain estimate variance.
Data-stream reconciliation across product type, automation technology, and end-user segmentation dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from fitted growth curves against historical replacement cycle patterns and regulatory compliance deadlines. Forecast inputs incorporated resin price volatility assumptions and smart home penetration trajectories specific to North American and European household adoption curves.
The model holds under stable regulatory enforcement timelines; deviation in extended producer responsibility acceleration or REACH substance restriction expansion would shift replacement demand patterns. Practitioners should monitor EU Ecodesign Directive amendment proposals and LME copper pricing volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Butter Coffee Market
Coffee
North America Instant Coffee Market
Coffee
Coffee Fruit Extract Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Europe Coffee Market
Coffee
Sparkling Coffee Market
Coffee
Espresso Tamper Market
Coffee
South America Coffee Market
Coffee
Green Coffee Market
Coffee
India Coffee Roaster Market
Coffee
Nitrogenated Coffee Market
Coffee
Germany Coffee Market
Coffee
China Ready-To-Drink (RTD) Coffee Market
Coffee
Adaptogen Coffee Market
Coffee
Coffee Crystal Market