
 Coffee Bottle Market | 2026-2036
Coffee Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Coffee Bottle Market Outlook
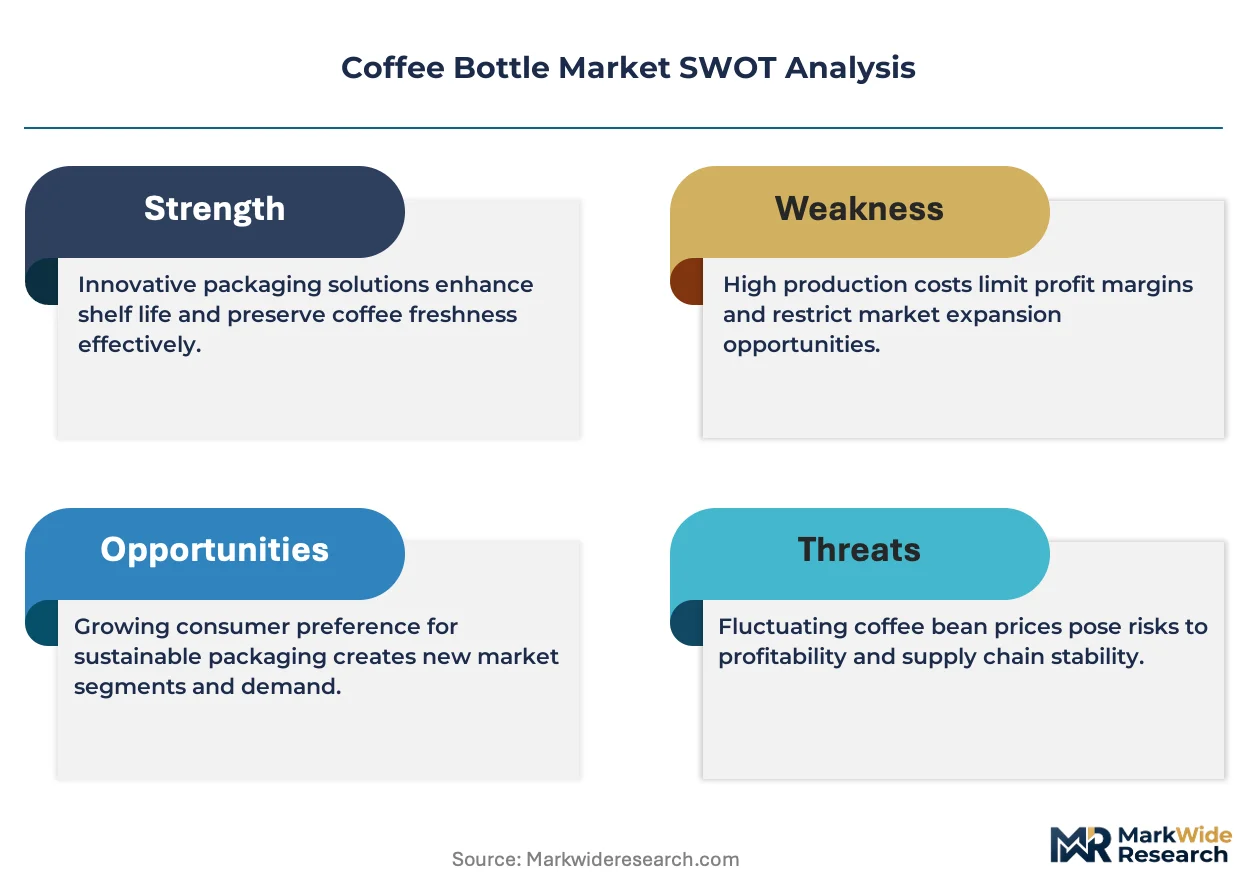
EU REACH compliance is pivoting how manufacturers source coatings and adhesives for coffee bottle production. Nestlé S.A. leverages its vertically integrated bottling network across Western Europe to sustain cost advantages in glass formats. Starbucks Corporation anchors its premium positioning through controlled retail channel distribution. PepsiCo, Inc. competes aggressively on volume scale in the ready-to-drink segment.
A coffee bottle is a sealed or resealable container, typically constructed from glass, stainless steel, or polyethylene terephthalate, designed to preserve beverage freshness through oxygen barrier properties and thermal stability across shelf temperatures. Glass bottles dominate premium positioning due to inert surface chemistry and consumer perception of taste purity, while stainless steel variants command the insulated functionality segment with vacuum-sealed double-wall construction. The 500ml capacity tier leads volume throughput in commuter-oriented retail, whereas single-use plastic faces structural decline as deposit-return schemes expand across European markets.
The U.S. FDA governs food-contact substance migration limits for plastic coffee bottles, while the EU F-Gas Regulation constrains blowing-agent chemistry in insulated formats. Germany's national packaging law tightens extended producer responsibility thresholds, reshaping how brands finance collection infrastructure. Stakeholders must monitor how divergent transatlantic recycling-credit systems alter the economic viability of regional manufacturing footprints.
Market Dynamics
The EU Single-Use Plastics Directive is forcing material transitions across European supply chains, compressing demand for virgin PET while accelerating refillable glass system deployment in commuter retail channels.
Growth Catalysts
- Urban Commuter Density:Germany's metropolitan transit corridors concentrate ready-to-drink consumption in 500ml formats, anchoring volume throughput for resealable stainless steel and glass variants.
- REACH Compliance Pivot:ECHA substance restrictions on bisphenol-based coatings are redirecting manufacturer R&D toward bio-based barrier technologies for metal and plastic substrates.
- Deposit-Return Scheme Expansion:Extended producer responsibility laws in France, Germany, and the Netherlands are financing closed-loop collection infrastructure that improves glass bottle circularity economics.
Market Restraints
- Aluminum Input Volatility:LME price swings for aluminum sheet directly compress margins on insulated double-wall stainless steel production.
- Glass Furnace Concentration:European container glass production clusters in Italy and Germany, creating geographic supply risk for brands without multi-sourcing agreements.
- PET Substitution Pressure:Recycled polyethylene terephthalate flake shortages limit scale-up of food-grade rPET bottles to sub-premium price tiers.
Strategic Opportunities
- Refillable System Underpenetration:Spain and Poland retain single-use dominance in convenience retail, presenting whitespace for deposit-return infrastructure investment.
- Smart Bottle Convergence:NFC-enabled temperature logging is merging with vacuum-insulated construction to create traceable cold-chain assurance for premium ready-to-drink distribution.
- EU Green Deal Tailwind:Carbon border adjustment mechanisms favor low-emission glass furnace operations in France and Sweden over import-dependent PET supply chains.
Industry Challenges
- Coating Chemist Scarcity:Food-contact barrier formulation expertise sits concentrated with legacy glass and canning suppliers, constraining new entrant scale-up timelines.
- Multi-Material Separation:Adhesive-labeled glass and sleeved PET require advanced optical sorting infrastructure that municipal recyclers in Eastern Europe lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffee Bottle Market |
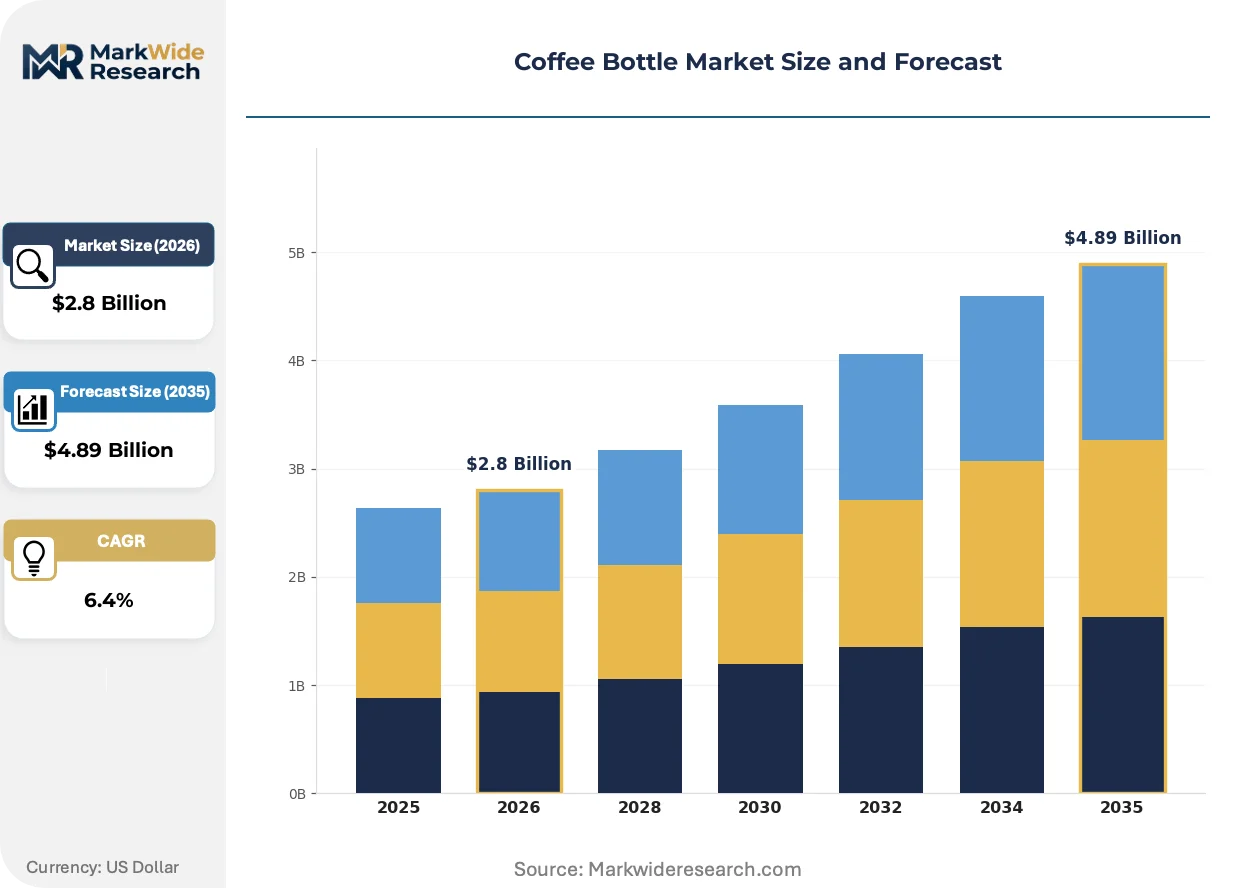
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Stainless Steel, Plastic, Ceramic Capacity: 250ml, 500ml, 750ml, 1L Design Style: Contemporary, Classic, Vintage, Minimalist Functionality: Insulated, Reusable, Single-use, Portable |
| Companies Covered | Nestlé S.A., Starbucks Corporation, PepsiCo, Inc., The Coca-Cola Company, Keurig Dr Pepper, JDE Peet's, O-I Glass, Ardagh Group, Bormioli Rocco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffee Bottle Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to reshape container performance standards and manufacturing footprints across European bottling operations.
Vacuum-insulated stainless steel construction with copper-lined inner walls is overtaking single-wall aluminum in premium commuter formats. Urban professionals in German and Dutch metropolitan areas are adopting these vessels for multi-hour temperature retention. This technology is compressing addressable volume for disposable insulated sleeves and secondary packaging.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick interior coatings from metal bottle production. Manufacturers must qualify ceramic-based or silicone-polymer alternatives through ECHA notification procedures. The insulated metal segment faces 12-18 month reformulation timelines to maintain food-contact compliance.
Direct-to-consumer subscription models for seasonal ready-to-drink releases are bypassing traditional grocery slotting fees. Specialty roasters in Copenhagen and Amsterdam are leveraging this channel to test limited-edition glass bottle formats. This pattern concentrates in Nordic markets where digital payment penetration and urban logistics density support last-mile cold delivery economics.
Coffee Bottle Market Segmentation
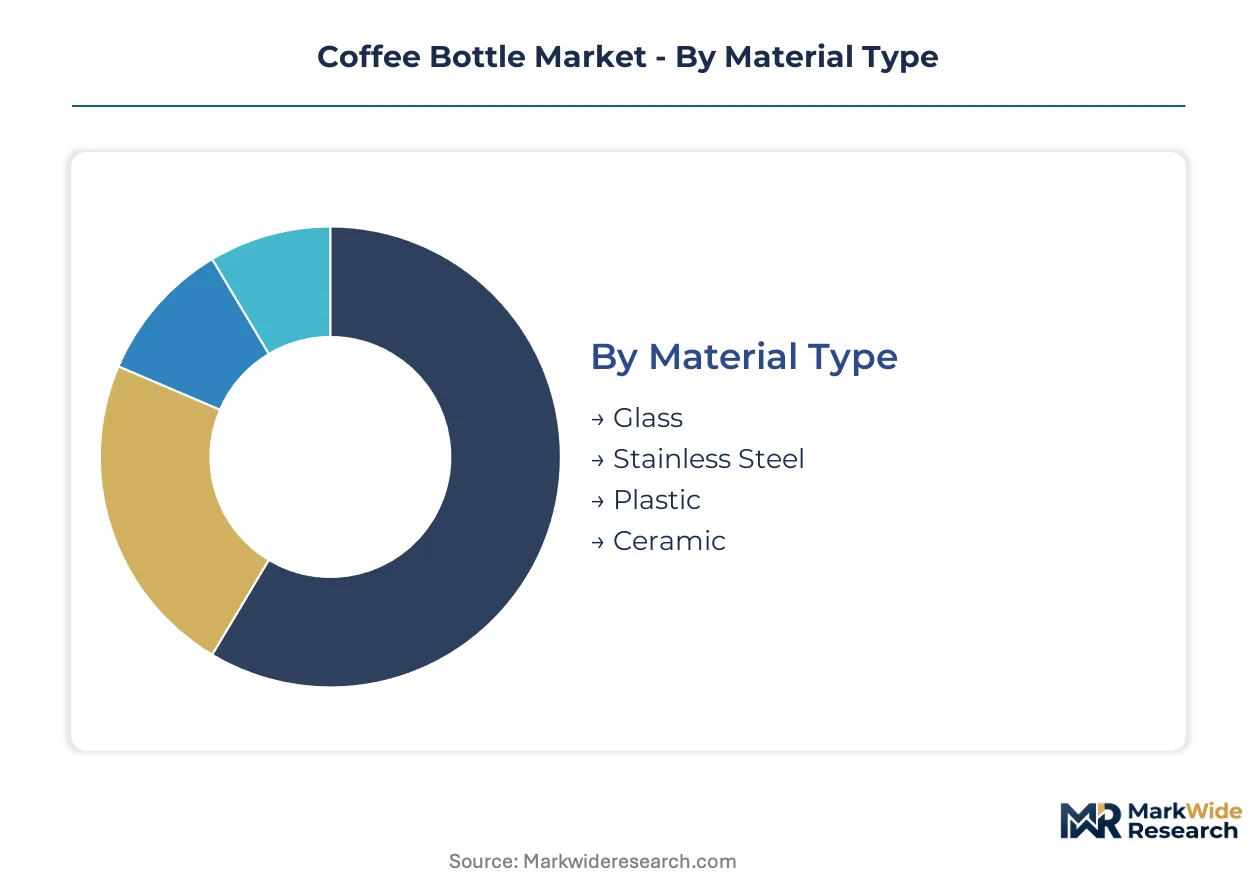
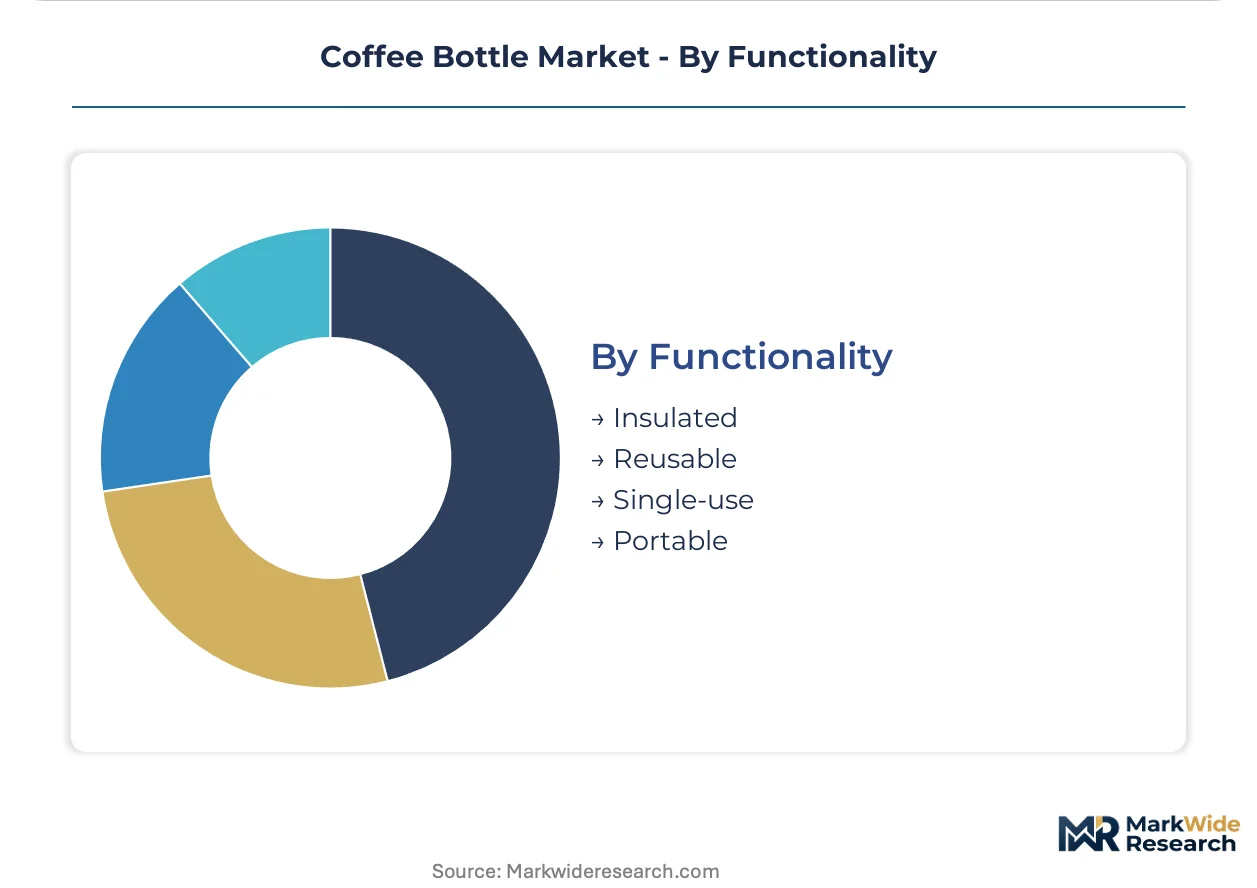
Material chemistry, capacity optimization, and functional design converge to define competitive positioning in coffee bottle procurement. Buyers segment demand across thermal performance tiers, aesthetic differentiation, and regulatory compliance requirements. Each category presents distinct margin structures and supply chain configuration challenges.
Material Type:
Standardization dominates at the commodity end while customization concentrates in premium barrier specifications and coating chemistries.
- Glass:Inert borosilicate and soda-lime formulations provide oxygen barrier properties essential for cold-brew shelf stability. German deposit-return infrastructure and French extended producer responsibility laws anchor demand for refillable formats in commuter corridors.
- Stainless Steel:Vacuum-insulated double-wall construction with copper lining achieves multi-hour temperature retention for urban professionals. REACH Annex XVII restrictions on legacy non-stick coatings are forcing 12-18 month reformulation timelines toward ceramic-based alternatives.
- Plastic:Virgin and recycled PET variants face structural decline as EU Single-Use Plastics Directive implementation accelerates across member states.
- Ceramic:Glazed stoneware and porcelain formats serve specialty café retail with limited scale due to fragility and weight constraints.
Leading the category by volume: Glass. Growing fastest: Stainless Steel.
Capacity:
Volume throughput correlates directly with transit-oriented consumption patterns and single-serve versus multi-serve use cases.
- 250ml:Espresso-focused formats concentrate in Italian and Portuguese café culture where concentrated consumption dominates morning rituals.
- 500ml:The dominant commuter tier aligns with German metropolitan transit corridor density and Dutch cycling infrastructure. Standardized dimensions fit automotive cup holders and bicycle bottle cages.
- 750ml:Shared consumption and office carafe applications drive demand in Nordic workplace coffee cultures.
- 1L:Bulk cold-brew and concentrate dilution formats serve hospitality and foodservice procurement in Belgian and Austrian markets.
Widest distribution footprint: 500ml. Steepest expansion trajectory: 750ml.
Design Style:
Aesthetic differentiation separates mass retail commoditization from specialty channel premium capture.
- Contemporary:Matte finishes and geometric profiles dominate Scandinavian design-influenced retail in Copenhagen and Stockholm.
- Classic:Traditional silhouettes with heritage branding sustain market share in Italian and French established retail channels.
- Vintage:Retro aesthetic revival captures specialty roaster limited editions in Amsterdam and Berlin direct-to-consumer channels.
- Minimalist:Unbranded and single-color formats align with private-label grocery expansion in Dutch and Belgian markets.
Highest margin capture: Contemporary. Fastest share gain: Minimalist.
Functionality:
Performance specifications determine material selection, manufacturing complexity, and end-of-life handling requirements.
- Insulated:Vacuum-sealed construction commands premium positioning through temperature stability certification. ECHA F-Gas Regulation constraints on blowing agents complicate foam-insulated variant production.
- Reusable:Deposit-return scheme compatibility drives design standardization in German, Dutch, and Danish markets with established collection infrastructure.
- Single-use:Regulatory compression from EU packaging waste directives is accelerating format obsolescence across Western European convenience retail.
- Portable:Leak-proof sealing mechanisms and carabiner-compatible lids target outdoor recreation and cycling demographics in Alpine regions.
Dominant revenue contribution: Insulated. Regulatory headwinds concentrated: Single-use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German packaging law incentives and Dutch deposit-return infrastructure anchor European supply chain concentration. Transit corridor density in metropolitan clusters drives commuter-format demand. Regulatory chemistry constraints reshape manufacturing footprints across member states.
Germany
Urban transit corridors in Berlin and Hamburg concentrate 500ml format consumption among cycling commuters. The national packaging law tightens extended producer responsibility thresholds, forcing brands to finance collection infrastructure. Glass furnace operations in Bavaria and North Rhine-Westphalia supply refillable borosilicate formats for deposit-return retail channels.
Netherlands
Randstad metropolitan logistics density supports direct-to-consumer cold delivery economics for specialty roasters. ECHA REACH Annex XVII restrictions on per- and polyfluoroalkyl substances eliminate legacy non-stick coatings from metal bottle production. Amsterdam and Rotterdam harbor clusters facilitate rPET import handling for food-grade flake processing.
France
Extended producer responsibility laws in Île-de-France anchor closed-loop collection infrastructure for glass circularity. The EU Green Deal carbon border adjustment mechanisms favor low-emission furnace operations in northern industrial zones. Paris commuter rail corridors sustain demand for insulated stainless steel formats with ceramic-based interior barriers.
Italy
Espresso-focused 250ml formats concentrate in Milan and Turin café culture where concentrated morning consumption dominates. Container glass production clusters in Lombardy and Veneto create geographic supply concentration for premium brands. Italian regulators enforce EFSA food-contact migration limits for ceramic-glazed specialty formats.
Sweden
Nordic workplace coffee cultures in Stockholm and Gothenburg drive 750ml shared consumption and office carafe applications. EU F-Gas Regulation constraints on blowing agents complicate foam-insulated variant production for outdoor recreation demographics. Swedish digital payment penetration supports subscription-model direct-to-consumer seasonal releases.
Coffee Bottle Market Competitive Environment
Western European producers anchor the premium glass and insulated metal tier; North American beverage conglomerates hold volume-scale ready-to-drink positions. The vendor base separates into three strategic archetypes: vertically integrated roaster-bottlers, specialized container manufacturers, and diversified beverage multinationals. Capacity expansion and portfolio diversification toward sustainable materials represent dominant competitive moves.
Among diversified beverage multinationals, Nestlé S.A., PepsiCo, Inc., and Starbucks Corporation exemplify distinct strategic positioning archetypes. Nestlé S.A. occupies a position reflecting captive supply chain control across Western European bottling networks. PepsiCo, Inc. sits within the volume-driven ready-to-drink segment where scale economics dominate competitive dynamics. Starbucks Corporation anchors premium positioning through controlled retail channel distribution rather than commodity grocery slotting.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Starbucks Corporation |
| PepsiCo, Inc. |
| The Coca-Cola Company |
| Keurig Dr Pepper |
| JDE Peet's |
| O-I Glass |
| Ardagh Group |
| Bormioli Rocco |
| Others |
Value Chain & Pricing Dynamics
EU REACH Annex XVII substance restrictions gate qualified supply for food-contact barrier coatings, compressing manufacturer margins while propelling premium-tier pricing for compliant ceramic-based and silicone-polymer alternatives. Brands without ECHA-notified formulations face 12-18 month qualification delays, forcing procurement premiums on validated suppliers.
Pricing Analysis
Short lead-time premiums of 15-25% apply to spot orders from qualified glass furnace operators in Bavaria and North Rhine-Westphalia, while volume commitments of 12+ months unlock standard-tier contract pricing. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-insulated stainless steel with ceramic barriers from single-wall aluminum and commodity PET variants. Pricing pressure stems from LME aluminum volatility compressing margins on double-wall insulated production. Private-label grocery buyers in Dutch and Belgian markets exhibit highest price sensitivity, whereas specialty roasters in Nordic direct-to-consumer channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Dual-sourcing mandates from Nestlé S.A. and Starbucks Corporation require qualified suppliers in both Germany and Italy for borosilicate glass, mitigating geographic concentration risk from Lombardy furnace clusters. Raw material dependencies center on soda ash from Turkey, aluminum sheet from Norway, and copper lining from Finnish refiners. Supply chain risk concentrates in single-source vulnerability for ECHA-compliant ceramic coating chemistries, where formulation expertise sits concentrated with legacy canning suppliers. Distribution runs through deposit-return scheme operators in German and Dutch retail, with direct-to-consumer cold delivery emerging in Amsterdam and Copenhagen metropolitan logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass furnace capacity constraints in Italy and Germany prop pricing premiums, as qualified borosilicate supply fails to match refillable format demand acceleration across EU deposit-return expansion.
For Market Incumbents: Deploy captive coating chemistry R&D to lock in ECHA-compliant formulation supply before 18-month qualification windows close. Nestlé S.A.'s vertically integrated bottling network demonstrates defensive value against aluminum input volatility through backward integration into Bavarian furnace operations. Capacity addition in Swedish low-emission glass production hedges carbon border adjustment exposure. Channel control through direct retail relationships insulates margin capture from grocery slotting fee compression. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier entry path, bypassing established deposit-return infrastructure requirements that favor incumbents. Spain and Poland present whitespace for refillable system penetration where single-use dominance persists in convenience retail. Specialty ceramic-glazed formats for Copenhagen and Amsterdam roasters enable premium positioning without competing on glass furnace scale economics. For Investors and Strategic Acquirers: ECHA notification approval for ceramic-based barrier coatings is the leading indicator that mid-tier manufacturers have cleared regulatory moats and warrant acquisition premium. Five-to-ten year viability favors specialists with dual-material competence across glass and insulated metal, not pure-play PET converters facing structural decline. Target acquisition archetype: German or Italian container manufacturers with validated REACH compliance and existing relationships with deposit-return scheme operators.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Chemistry Qualification | ECHA notification for ceramic barriers unlocks premium-tier stainless steel positioning against legacy non-stick competitors. |
| Deposit-Return Infrastructure Investment | Closed-loop collection financing in Spain and Poland captures whitespace before regulatory mandates force compliance costs. |
| Low-Emission Furnace Conversion | Swedish and French carbon-efficient glass production aligns with EU Green Deal border adjustment mechanisms favoring domestic supply. |
| Direct-to-Consumer Channel Launch | Nordic digital payment penetration and urban logistics density support cold delivery economics for seasonal ready-to-drink releases. |
| Multi-Sourcing Agreement Structuring | Dual qualification across German and Italian furnace clusters mitigates geographic supply risk from Lombardy production concentration. |
Study Parameters
Document review covered ECHA REACH substance restriction filings, EU Single-Use Plastics Directive implementation timelines, and national packaging law amendments across member states, complemented by interviews with container glass procurement directors, specialty roaster supply chain managers, and deposit-return scheme operators. Secondary validation drew from customs trade data for soda ash and aluminum sheet imports, SEC 10-K filings of diversified beverage multinationals, and Nordic retail audit databases tracking direct-to-consumer penetration. Bottom-up volume modeling triangulated against top-down category spend estimates from grocery and foodservice channels.
Cross-referencing historical capacity utilization patterns against expert panel input on furnace expansion timelines anchored the projection framework across the analysis window. Segmentation dimensions modeled include material chemistry tier, thermal performance specification, capacity format, design aesthetic cluster, and functionality category. CAGRs derived from weighted regression of commuter transit density correlations, regulatory implementation schedules, and substitution elasticity between refillable glass and insulated metal formats. Industry-specific inputs incorporated ECHA notification approval timelines and deposit-return scheme rollout phasing by member state.
The model holds under sustained EU packaging waste directive enforcement and stable aluminum LME pricing; deviation in REACH Annex XVII expansion scope or glass furnace energy cost spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Pods Market
Coffee
Coffee Grinder Market
Coffee
Italy Coffee Market
Coffee
Single Origin Coffee Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Global Nespresso Capsules Market
Coffee
North America Specialty Coffee Market
Coffee
Coffee Extracts Market
Coffee
Brazil Ready-To-Drink (RTD) Coffee Market
Coffee
RTD Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
Middle East and Africa Coffee Market
Coffee
Middle East Coffee Market
Coffee
Global Coffee Machine Market