
 Global Automatic Coffee Machines Market | 2026-2036
Global Automatic Coffee Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automatic Coffee Machines Market Analysis
Modular pod-to-bean configurability is realigning buyer choice across residential and commercial channels. De'Longhi Group leverages in-house production of thermoblock systems to control component quality. JURA Elektroapparate AG anchors its position through proprietary pulse extraction process technology. Robert Bosch GmbH competes via integrated grinder-brewer platforms that reduce countertop footprint.
Automatic coffee machines encompass electromechanical brewing systems that heat water to precise temperatures, apply pressurized extraction, and dispense measured volumes without manual intervention. Units typically operate at 9-15 bar pressure with integrated conical burr grinders and programmable dose control for consistent output. Single-serve machines lead volume sales through pod-based convenience, while super-automatic espresso systems capture the strongest margin pools in commercial channels. Drip machines remain mature in North American residential settings where batch brewing dominates morning routines.
The EU F-Gas Regulation and Ecodesign Directive constrain refrigerant selection and standby power consumption for appliance manufacturers. The US Department of Energy sets minimum efficiency standards under federal appliance regulations. China's GB standards and NMPA guidelines govern electrical safety and material contact compliance for imported units. Stakeholders must monitor evolving efficiency thresholds and material restriction lists that determine market access across major economies.
Market Dynamics
Super-automatic espresso systems are compressing the competitive landscape in commercial channels as hotels and quick-service restaurants consolidate equipment procurement around single-vendor platforms that bundle grinding, brewing, and milk frothing.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits for kitchen appliances are forcing manufacturers to redesign thermal systems, creating first-mover advantage for firms with thermoblock efficiency patents.
- Pod-to-bean configurability:Modular brewing architectures let residential buyers switch between single-serve convenience and whole-bean freshness without replacing the entire unit.
- Commercial hospitality procurement:Hotel chains in Germany and Italy are standardizing on super-automatic platforms to reduce training costs and beverage inconsistency across properties.
Market Restraints
- Stainless steel and copper input costs:Volatility in metal commodity markets squeezes margin on premium boiler components sourced from European foundries.
- Thermoblock supply concentration:Three Italian component houses control the majority of rapid-heating element production, creating single-source risk for mid-tier assemblers.
- Refrigerant compliance friction:The EU F-Gas Regulation restricts hydrofluorocarbon use in integrated milk cooling systems, forcing costly redesigns of commercial units.
Strategic Opportunities
- Underpenetrated residential markets in India:Urban households with rising disposable income lack exposure to automated espresso systems, presenting greenfield demand for entry-level super-automatic units.
- Connected machine ecosystems:Convergence of IoT telemetry and predictive maintenance software enables subscription-based consumable replenishment models.
- US Inflation Reduction Act efficiency incentives:Federal appliance rebates for Energy Star-certified equipment tilt procurement toward heat pump and thermoblock designs over traditional boiler systems.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for pressure profiling and grinder calibration competes with automotive and medical device sectors for talent in Germany and Switzerland.
- Multi-jurisdiction certification timelines:Simultaneous UL, CE, and GB standard testing extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automatic Coffee Machines Market |
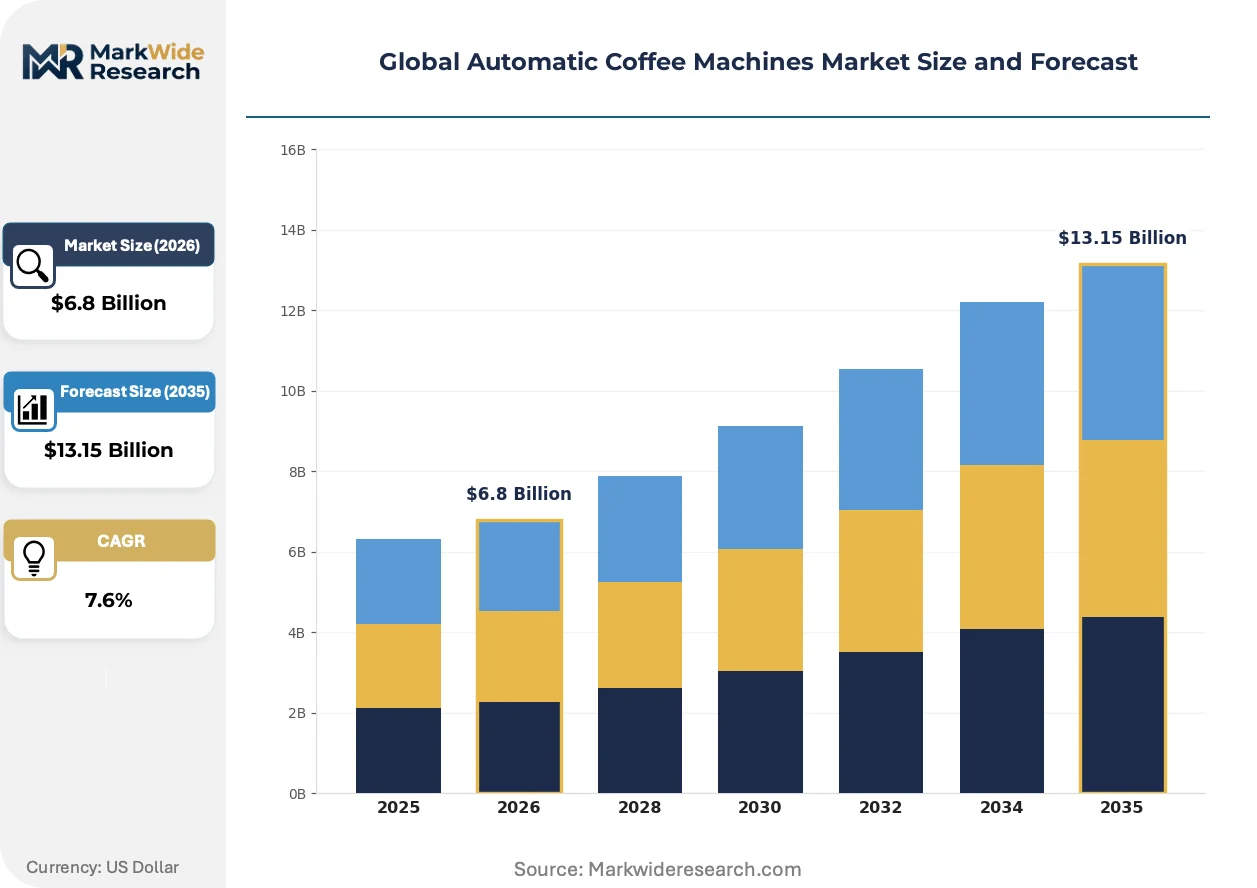
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Machines, Espresso Machines, Single-Serve Machines, Percolators Customer Type: Residential Users, Commercial Establishments, Office Use, Coffee Shops Technology: Fully-Automatic, Semi-Automatic, Super-Automatic, Manual Distribution Channel: Online Retail, Brick-and-Mortar Stores, Specialty Shops, Distributors |
| Companies Covered | De’Longhi Group, JURA Elektroapparate AG, Melitta Group, BSH Hausgeräte GmbH, Koninklijke Philips N.V., Nestlé Nespresso S.A., Robert Bosch GmbH, WMF Coffeemachines, Keurig Dr Pepper Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automatic Coffee Machines Market Emerging Trajectories
Brewing system architectures are converging around platform modularity, regulatory efficiency mandates, and digitally enabled service models that reshape how manufacturers capture lifetime value.
Thermoblock heating technology is consolidating market share in residential super-automatic segments by eliminating the warm-up latency of traditional boilers. German and Italian manufacturers are embedding these compact thermal engines into countertop units priced at mainstream drip machine levels. This compression is consolidating the mid-market tier where boiler-based systems previously held performance differentiation.
The EU F-Gas Regulation is tightening refrigerant selection for integrated milk cooling in commercial espresso systems. Manufacturers must now qualify alternative cooling loops or external refrigeration modules that comply with phasedown schedules. Commercial hospitality procurement in Italy and France is accelerating qualification timelines for F-Gas-compliant platforms ahead of 2027 enforcement thresholds.
Corporate procurement departments are centralizing beverage equipment decisions under facilities management rather than decentralized hotel or restaurant operations. This shift compresses vendor negotiation cycles and favors multi-year service contracts with predictive maintenance clauses. The pattern is most visible in United States hotel chains where procurement standardization reduces per-property equipment variation.
Global Automatic Coffee Machines Market Segmentation
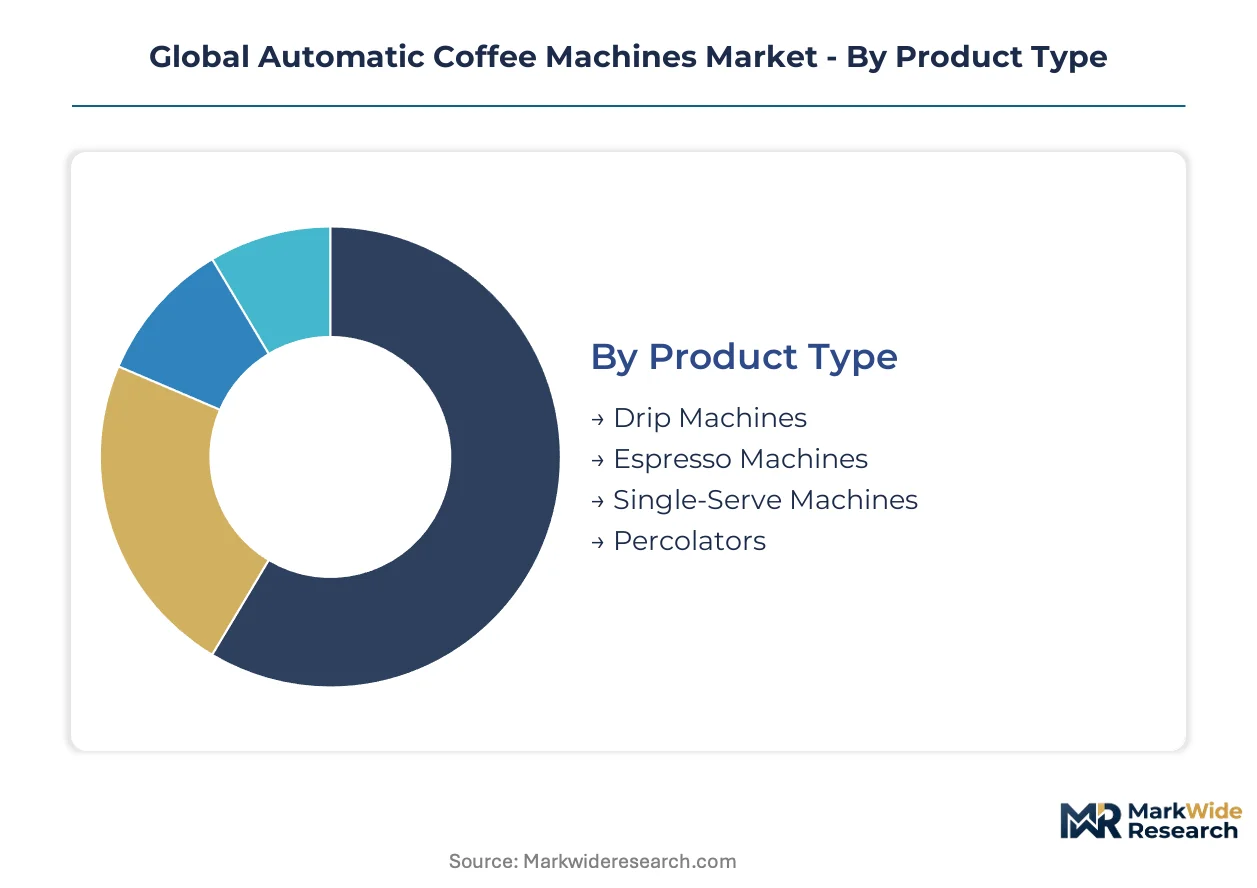
Automatic coffee machines fragment across brewing architectures, end-use intensity, and automation depth. Each dimension reshapes margin structures and vendor selection criteria differently.
Product Type:
Volume concentration favors convenience formats, while premium capture concentrates in pressure-based extraction systems.
- Espresso Machines:Pressure systems operating at 9-15 bar with integrated conical burr grinders and programmable dose control. Demand concentrates in Italy and Germany where premium residential users and hospitality operators standardize on super-automatic platforms to reduce training overhead and beverage inconsistency.
- Single-Serve Machines:Pod-based electromechanical systems that heat water to precise temperatures and dispense measured volumes without manual intervention. Procurement in the United States dominates volume sales through convenience-driven morning routines in residential settings and office breakrooms.
- Drip Machines:Batch brewing systems prevalent in North American residential kitchens where multi-cup output dominates household consumption patterns.
- Percolators:Recirculating extraction devices retaining niche deployment in institutional settings and traditional hospitality environments.
Mature deployment sits with drip machines. Newer deployment is concentrated in super-automatic espresso systems.
Customer Type:
Procurement authority is shifting from decentralized property management to centralized facilities departments, compressing vendor negotiation cycles.
- Commercial Establishments:Hotels and quick-service restaurants consolidating equipment procurement around single-vendor platforms that bundle grinding, brewing, and milk frothing. Germany and Italy lead standardization as corporate procurement departments centralize beverage equipment decisions under facilities management.
- Coffee Shops:Specialty operators demanding pressure profiling and grinder calibration precision. Firmware development competes with automotive and medical device sectors for embedded systems engineering talent in Germany and Switzerland.
- Residential Users:Urban households with rising disposable income in underpenetrated markets seeking entry-level super-automatic units with pod-to-bean configurability.
- Office Use:Workplace breakroom procurement favoring connected machine ecosystems with IoT telemetry and predictive maintenance software enabling subscription-based consumable replenishment.
Margin capture concentrates in commercial establishments. Volume expansion is climbing the fastest in residential channels.
Technology:
Automation depth determines thermal system architecture and regulatory compliance burden.
- Super-Automatic:Integrated platforms combining grinding, tamping, extraction, and milk texturing without manual intervention. EU Ecodesign Directive standby power limits are forcing manufacturers to redesign thermal systems, creating first-mover advantage for firms with thermoblock efficiency patents in Germany and Italy.
- Fully-Automatic:One-touch operation with automated brewing sequences but limited grinder integration. Deployment concentrates in mid-tier residential segments across the United States where countertop footprint reduction drives selection.
- Semi-Automatic:User-controlled extraction timing with automated pressure delivery. Niche positioning among enthusiast residential users seeking manual override capabilities.
- Manual:Lever-operated systems with no electromechanical automation. Artisanal coffee shops and specialty operators in Italy retain limited procurement for theatrical preparation rituals.
Technology maturation centers on semi-automatic platforms. Steepest expansion trajectory belongs to super-automatic systems.
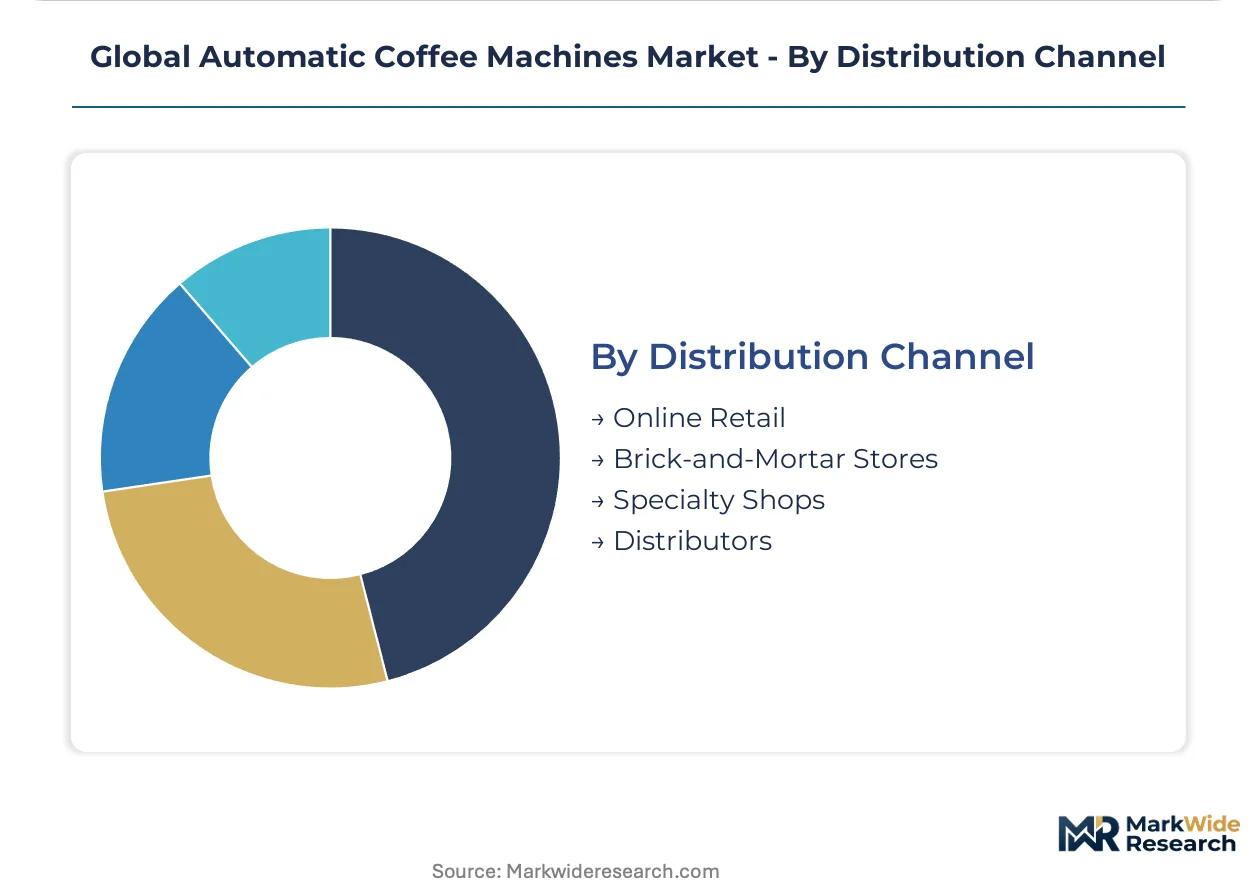
Distribution Channel:
Channel selection determines service attachment rates and lifetime value capture.
- Specialty Shops:Curated retail environments with demonstration capabilities and extended service contracts. Concentrated in Italian and German urban centers where premium espresso system penetration is deepest.
- Online Retail:Direct-to-consumer platforms enabling subscription-based consumable replenishment models through connected machine telemetry. United States market leadership in IoT-enabled ecosystem deployment.
- Brick-and-Mortar Stores:Mass-market retailers with limited technical service infrastructure. Dominant in North American residential drip machine procurement.
- Distributors:B2B intermediaries serving commercial hospitality procurement with multi-year service contracts and predictive maintenance clauses. Consolidating vendor relationships as hotel chains standardize equipment across properties.
Established procurement flows through brick-and-mortar stores. Emerging deployment is concentrating in online retail with connected service attachments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in German and Italian industrial corridors, while consumption tilts toward premium residential markets in the United States and hospitality procurement across Western Europe. The regulatory divergence between EU efficiency mandates and US federal appliance standards creates distinct compliance pathways for manufacturers serving multiple geographies.
United States
Hotel chains and quick-service restaurants are consolidating beverage equipment procurement under centralized facilities management. The US Department of Energy sets minimum efficiency standards under federal appliance regulations. Corporate procurement standardization is compressing vendor negotiation cycles across properties in the Southeast and Southwest corridors.
Germany
Super-automatic espresso systems dominate hospitality procurement as chains seek to reduce training overhead and beverage inconsistency. The EU Ecodesign Directive mandates standby power limits for kitchen appliances, forcing thermal system redesigns. Industrial clusters in North Rhine-Westphalia and Bavaria host thermoblock manufacturing and embedded systems engineering talent.
Italy
Premium residential users and hospitality operators standardize on super-automatic platforms with integrated grinding and milk texturing. The EU F-Gas Regulation restricts hydrofluorocarbon use in integrated milk cooling systems. Manufacturing concentration in Lombardy and Veneto supplies rapid-heating elements and pressure profiling components to assemblers across Europe.
China
Urban households with rising disposable income present greenfield demand for entry-level super-automatic units with pod-to-bean configurability. GB standards and NMPA guidelines govern electrical safety and material contact compliance for imported units. Yangtze River Delta manufacturing zones produce thermoblock components and conical burr grinders for domestic and export markets.
India
Residential penetration of automated espresso systems remains underdeveloped despite growing urban affluence. BIS certification requirements and DGFT import regulations shape market access for foreign manufacturers. Metropolitan clusters in Maharashtra and Karnataka are emerging as early adoption centers for connected machine ecosystems with IoT telemetry.
Global Automatic Coffee Machines Market Vendor Landscape
The competitive structure tilts toward integrated platform specialists with captive thermoblock production and proprietary extraction technologies. German and Swiss manufacturers anchor the premium tier through in-house component fabrication, while Italian fabricators dominate rapid-heating element supply. Three strategic archetypes define positioning: vertically integrated thermal system producers, modular platform assemblers, and pod-based ecosystem operators. Competitive moves concentrate on thermoblock efficiency patents and multi-year service contract bundling for commercial hospitality accounts.
Among German-based manufacturers, Robert Bosch GmbH and BSH Hausgeräte GmbH exemplify the integrated grinder-brewer platform archetype with countertop footprint reduction as a core design principle. Swiss specialist JURA Elektroapparate AG occupies a position within the premium super-automatic segment through proprietary pulse extraction process technology. Italian manufacturer De'Longhi Group represents the thermoblock efficiency patent holder archetype with in-house production of rapid-heating elements controlling component quality and supply security.
| Leading Market Players |
|---|
| De'Longhi Group |
| JURA Elektroapparate AG |
| Melitta Group |
| BSH Hausgeräte GmbH |
| Koninklijke Philips N.V. |
| Nestlé Nespresso S.A. |
| Robert Bosch GmbH |
| WMF Coffeemachines |
| Keurig Dr Pepper Inc. |
| Others |
Supply Flow & Price Mechanics
The EU Ecodesign Directive's standby power mandates gate qualified supply access and premium-tier pricing eligibility for thermoblock-equipped super-automatic platforms. Manufacturers lacking certified thermal systems face exclusion from hospitality procurement in Germany and Italy, compressing margin capture to unverified component assemblers.
Pricing Analysis
Margin tightening in mid-tier residential segments reflects thermoblock commoditization as Chinese Yangtze River Delta producers replicate rapid-heating architectures. Three-tier pricing structure across premium, standard, and economy levels differentiates by grinder calibration precision and milk system integration. Cost-down pressure accelerates because stainless steel and copper input volatility squeezes boiler component foundries in Italy. Quick-service restaurant procurement teams exhibit highest price sensitivity, while German hotel chains prioritize consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from De'Longhi and JURA procurement teams mandate qualified secondary suppliers for conical burr grinders and thermoblock elements. Component manufacturing concentrates in Italy, Germany, and China. Supply chains draw from European copper foundries, Swiss embedded systems firmware houses, and Chinese precision machining clusters. Single-source vulnerability concentrates in Italian rapid-heating element houses controlling patent-protected thermoblock designs. Distribution runs through B2B distributors serving commercial hospitality accounts with multi-year service attachments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic coffee machine market is consolidating around vertically integrated thermal system producers as EU F-Gas and Ecodesign compliance costs force sub-scale assemblers toward exit. Surviving players will capture disproportionate share in commercial hospitality procurement.
For Market Incumbents: Hedge against thermoblock patent expiration by accelerating proprietary pulse extraction and grinder calibration firmware development. Secure captive supply of rapid-heating elements through backward integration into Lombardy and Veneto manufacturing zones. Lock multi-year service contracts with US hotel chains before centralized procurement standardization completes vendor consolidation. For New Entrants and Emerging Players: IoT-enabled predictive maintenance platforms offer a technology-first wedge into underpenetrated Indian metropolitan markets where BIS certification barriers deter established European brands. Target Maharashtra and Karnataka residential clusters with entry-level super-automatic units featuring pod-to-bean configurability. Deploy direct-to-consumer online retail with subscription-based consumable replenishment to bypass distributor margin extraction. For Investors and Strategic Acquirers: Accelerated US hotel chain procurement centralization under facilities management is the leading indicator that commercial hospitality vendor consolidation is entering its terminal phase. Five-to-ten-year viability favors acquiring mid-tier Italian fabricators with thermoblock efficiency patents and existing CE/F-Gas compliance documentation. Watch for embedded systems engineering talent migration from automotive to appliance sectors as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoblock Patent Acquisition | Captures EU Ecodesign-compliant thermal architecture for super-automatic platform differentiation. |
| Predictive Maintenance Software Launch | Enables subscription consumable models through IoT telemetry integration with office breakroom deployments. |
| Indian Market Entry Partnership | Navigates BIS certification and DGFT import regulations through local assembly joint ventures. |
| Commercial Hospitality Service Contract Bundling | Locks multi-year revenue streams as US hotel chains consolidate procurement under facilities management. |
| F-Gas-Compliant Milk Cooling Redesign | Qualifies commercial espresso platforms for Italy and France hospitality procurement ahead of enforcement thresholds. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with appliance procurement managers at German hotel chains, Italian espresso system engineers, and US facilities management directors validated thermal system adoption patterns. Secondary sources included EU Ecodesign Directive implementation reports, US Department of Energy appliance efficiency databases, and Chinese GB standards documentation. Bottom-up unit shipment estimates triangulated against top-down value projections across the analysis window.
Segmentation granularity modeled product type at the brewing architecture level, technology tier by automation depth, and customer channel by procurement authority concentration. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics in mature North American drip machine markets and penetration velocity in Indian residential segments. Forecast inputs included thermoblock cost curves, EU F-Gas phasedown schedules, and hospitality industry capital expenditure surveys.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to EU Ecodesign standby power thresholds and geopolitical disruptions affecting Yangtze River Delta component exports. Deviation in stainless steel and copper commodity volatility would shift manufacturer margin outlooks materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
North America Coffee Market
Coffee
Italy Coffee Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Coffee Crystal Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Coffee Concentrate Market
Coffee
North America Instant Coffee Market
Coffee
Singapore Coffee Roaster Market
Coffee
Global Cafe Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Global Coffee Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
US Instant Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Australia Coffee Market