
 Thailand Coffee and Tea Capsules Market | 2026-2036
Thailand Coffee and Tea Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Coffee and Tea Capsules Market Intelligence
Thai contract packers and regional roasters is rebalancing supply chains toward localized capsule filling to offset import dependency. Nestlé S.A. dominates the premium coffee capsule tier through its Nespresso and Dolce Gusto brands, leveraging deep distribution into Thai modern trade channels. Luigi Lavazza S.p.A. competes aggressively on price-positioned aluminum systems, while Jacobs Douwe Egberts B.V. anchors the office and foodservice segment with L'Or and Pilão brand availability.
Coffee and tea capsules are sealed, pre-dosed single-serve containers—typically aluminum, plastic, or compostable fiber—designed for pressure-brewing extraction at standardized temperatures and bar pressures. These products deliver portion-controlled convenience for households, workplaces, and hospitality settings where speed and consistency override manual preparation methods. Coffee Capsules command the dominant revenue share given entrenched espresso culture and machine installed base, while Specialty Capsules represent the fastest-growing margin pool as Thai consumers trade toward origin-specific arabica and functional blends. Distribution Channel dynamics favor Supermarkets for impulse and replenishment purchases, though Online Retail captures the highest growth velocity as direct-to-subscription models penetrate Bangkok and Chiang Mai metro areas.
The Thai Food and Drug Administration enforces food contact material safety and labeling standards that directly shape capsule composition choices and import clearance pathways for foreign manufacturers. BIS-aligned voluntary standards for plastics in food applications, coupled with Thailand's national sustainable packaging roadmap under the Ministry of Natural Resources and Environment, are pushing brands toward biodegradable and aluminum-recyclable formats. Stakeholders must monitor regulatory timelines for extended producer responsibility implementation and decide whether to front-run compliance through material transitions or absorb later adaptation costs.
Market Dynamics
The Thai Food and Drug Administration's tightening labeling mandates for pre-packaged food products is compressing import clearance timelines and forcing material transitions across capsule formats. This regulatory pressure is accelerating localization investments among contract packers and regional roasters seeking supply chain autonomy from European and Japanese parent operations.
Growth Catalysts
- Urban household density:Greater Bangkok's café culture penetration and modern retail expansion create concentrated demand nodes for single-serve convenience. Metro corridor households upgrade from instant powder to pressure-brewed capsules at accelerating velocity.
- FDA labeling harmonization:The Thai Food and Drug Administration's alignment with ASEAN pre-packaged food standards reduces technical barriers for regional manufacturers. Cross-border capsule movements from Malaysia and Vietnam gain compliance efficiency.
- Aluminum recycling infrastructure:Thailand's national sustainable packaging roadmap under the Ministry of Natural Resources and Environment incentivizes closed-loop aluminum systems. Brand owners capture green positioning through recyclable format transitions.
Market Restraints
- Arabica bean price volatility:Thai roasters face margin compression from Brazilian and Colombian green coffee futures swings. Input cost instability constrains promotional depth in supermarket channels.
- Machine installed base concentration:Nestlé's Nespresso and Dolce Gusto patent-protected brewing systems lock competitors into licensing fees or format exclusion. Alternative capsule geometries struggle for retail shelf space.
- Extended producer responsibility timelines:Pending Ministry of Natural Resources and Environment mandates for post-consumer packaging recovery threaten compliance cost absorption. Uncertain implementation dates freeze long-term capital commitments.
Strategic Opportunities
- Chiang Mai metro expansion:Northern Thailand's second-tier urban center exhibits subscription-commerce penetration gaps versus Bangkok. Direct-to-consumer models capture untapped specialty arabica demand among remote workers and digital nomads.
- Compostable fiber convergence:Plant-based barrier coatings meeting BIS-aligned food contact standards enable petroleum-free capsule shells. Material innovators partner with Thai contract packers for ASEAN export hub positioning.
- Office foodservice channel:Post-pandemic workplace beverage service reinvestment creates white space for private-label capsule programs. Corporate procurement shifts from communal brewing equipment to hygienic single-serve formats.
Industry Challenges
- Food contact material certification timelines:Novel biodegradable polymers require 12-18 month Thai Food and Drug Administration safety reviews. Product launch schedules compress against regulatory clock uncertainty.
- Capsule filling equipment retrofit costs:Transitioning from plastic to aluminum or fiber formats demands line changeovers and technician retraining. Contract packers weigh dedicated versus flexible manufacturing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Coffee and Tea Capsules Market |
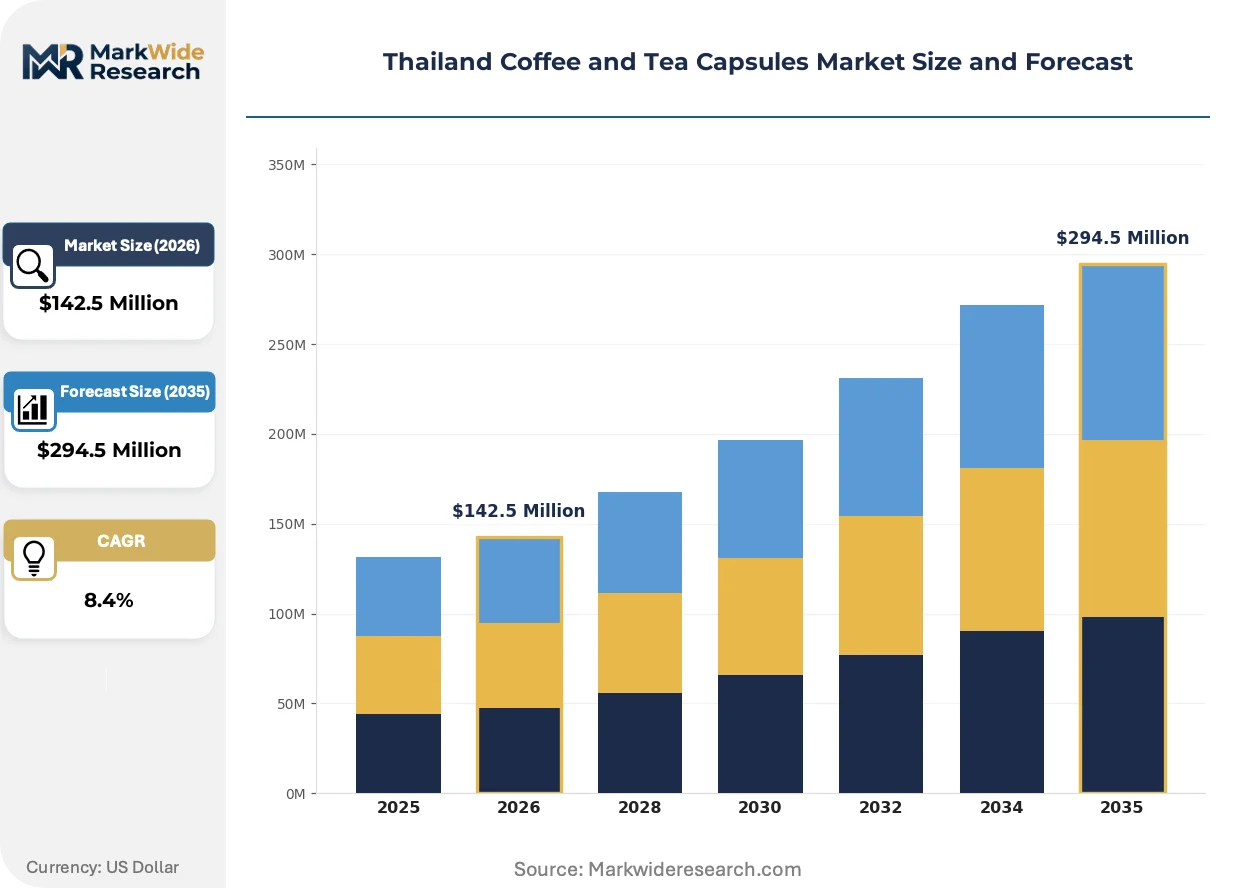
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $294.5 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee Capsules, Tea Capsules, Mixed Capsules, Specialty Capsules Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores End User: Households, Offices, Cafes, Restaurants Packaging Type: Box, Sleeve, Jar, Pouch |
| Companies Covered | Caffitaly System S.p.A., Mondelez International, Inc., Nestlé S.A., Tchibo GmbH, Dualit Limited, The J.M. Smucker Company, Luigi Lavazza S.p.A., Belmoca NV, Jacobs Douwe Egberts B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Coffee and Tea Capsules Market Strategic Shifts & Innovations
Thailand's coffee and tea capsule sector is experiencing format diversification and supply chain compression as regulatory deadlines approach and consumer sophistication deepens. Three interconnected developments are restructuring competitive positioning and procurement patterns.
Compostable fiber capsule technology with oxygen-barrier plant-derived coatings is modularizing production workflows for Thai contract packers. Regional roasters in Samut Prakan and Pathum Thani industrial zones adopt these systems to preempt extended producer responsibility mandates. The technology is modularizing quality control protocols by separating biodegradable batch runs from aluminum lines, reducing cross-contamination risk and enabling parallel certification tracks.
The Thai Food and Drug Administration's evolving pre-packaged food labeling requirements are tightening nutritional disclosure and origin documentation standards. Importers face extended customs clearance scrutiny for European and Japanese capsule shipments lacking Thai-language ingredient specifications. Premium arabica specialty capsules encounter the heaviest compliance friction, driving brand owners toward localized filling partnerships that bypass import documentation complexity.
Subscription-based replenishment models are displacing impulse supermarket purchases among Greater Bangkok's dual-income professional households. Online direct channels capture recurring revenue through machine-plus-capsule bundling and personalized roast profiles. This behavioral pivot concentrates most visibly in Bangkok's Sukhumvit and Silom central business district corridors, where delivery logistics density supports same-day fulfillment promises.
Thailand Coffee and Tea Capsules Market Segmentation
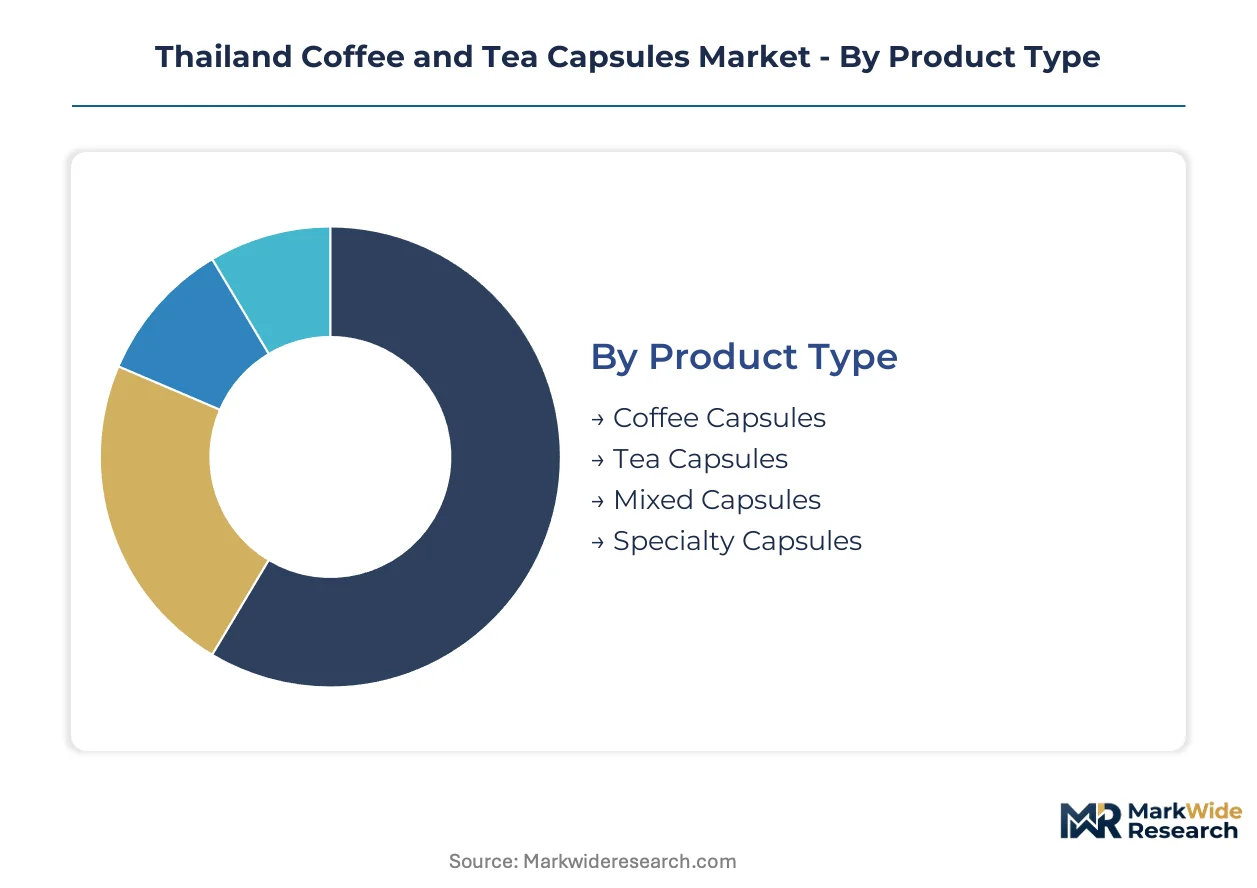
Capsule segmentation in Thailand reveals divergent growth mechanics across consumption occasions and procurement channels. Understanding these splits enables targeted positioning against Bangkok's café culture density versus emerging provincial demand.
Product Type:
Coffee Capsules dominate absolute volume while Specialty Capsules command premium margin expansion. The volume-premium split reflects entrenched espresso consumption habits versus trading-up behavior among urban professionals.
- Coffee Capsules:Aluminum and plastic shells containing roasted arabica or robusta blends calibrated for 9-bar pressure extraction. Demand concentrates in Greater Bangkok condominium households where machine penetration exceeds provincial averages. Nestlé's Nespresso and Dolce Gusto brewing systems lock in format compatibility requirements.
- Specialty Capsules:Single-origin arabica or micro-lot blends with traceable provenance and lighter roast profiles. Chiang Mai's remote worker and digital nomad communities drive subscription-based procurement for origin-specific offerings. Thai FDA labeling harmonization with ASEAN standards reduces import friction for regional specialty roasters.
- Tea Capsules:Sealed containers for pressure-brewed green, oolong, and herbal infusions targeting wellness-positioned households.
- Mixed Capsules:Assorted variety packs enabling trial across coffee and tea formats for new machine adopters.
Mature deployment sits with Coffee Capsules. Newer deployment is concentrated in Specialty Capsules.
Distribution Channel:
Channel strategy pivots on replenishment frequency versus discovery mechanics. Supermarkets anchor routine restocking while Online Retail captures subscription lock-in.
- Supermarkets:Modern trade formats including Tesco Lotus, Big C, and Gourmet Market stock impulse-facing displays near checkout zones. Bangkok's Sukhumvit and Silom corridors exhibit highest shelf-space allocation for premium aluminum systems.
- Online Retail:Direct-to-consumer platforms and marketplace storefronts enable machine-plus-capsule bundling with personalized roast profiling. Same-day fulfillment density in metropolitan Bangkok supports recurring revenue models.
- Convenience Stores:7-Eleven and FamilyMart locations stock emergency replenishment SKUs for immediate consumption needs.
- Specialty Stores:Department store home appliance sections and dedicated coffee equipment retailers provide consultation-driven purchases.
Volume concentration rests with Supermarkets. Margin expansion concentrates in Online Retail.
End User:
User segmentation tracks hygiene sensitivity and preparation speed requirements across consumption environments. Post-pandemic workplace reinvestment is reshaping office procurement patterns.
- Households:Dual-income professional families in Bangkok's metropolitan corridor represent core demand for portion-controlled morning preparation. Machine ownership correlates with condominium unit size and modern kitchen renovation rates.
- Offices:Corporate facilities and coworking spaces shift from communal brewing equipment to single-serve formats for hygiene assurance. Private-label programs gain traction among procurement managers seeking cost visibility.
- Cafes:Quick-service coffee chains deploy capsules for consistency in secondary locations with lower barista skill availability.
- Restaurants:Full-service dining establishments utilize capsules for post-meal espresso service without dedicated coffee infrastructure.
Established penetration sits with Households. Accelerating deployment targets Offices.
Packaging Type:
Packaging configuration balances shelf presence, protection, and sustainability signaling. Format choice intersects with retail channel requirements and extended producer responsibility anticipation.
- Box:Rigid paperboard containers with 10-20 count configurations dominate supermarket displays. Thai Ministry of Natural Resources and Environment sustainable packaging roadmap pressures fiber sourcing disclosures.
- Sleeve:Minimalist wrapping reduces material intensity for online-direct shipments where protective function is secondary.
- Jar:Reusable rigid containers targeting refill and bulk purchase behaviors in specialty retail environments.
- Pouch:Flexible film formats for promotional trial sizes and hospitality single-serve distribution.
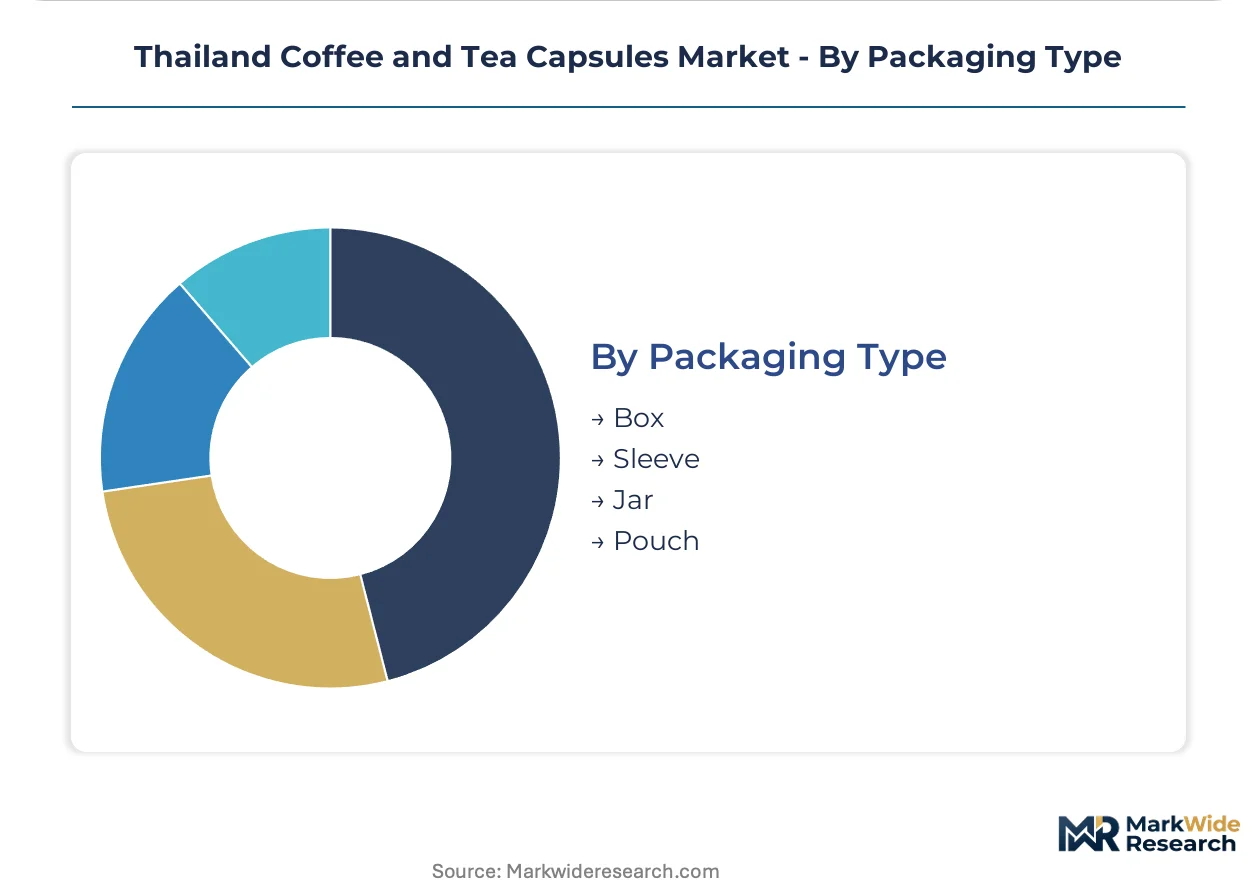
Standard deployment favors Box formats. Experimental deployment tests Sleeve and Jar configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arabica cultivation in northern Thailand's highland provinces anchors the country's specialty coffee supply base. Bean sourcing from Chiang Rai and Chiang Mai feeds regional roasting clusters. Domestic capsule filling operations concentrate in industrial zones surrounding Greater Bangkok.
Greater Bangkok Metropolitan Corridor
Condominium density and dual-income professional households drive single-serve machine penetration. The Thai Food and Drug Administration's pre-packaged food labeling mandates compress import clearance timelines for European capsule shipments. Samut Prakan and Pathum Thani industrial zones host contract packers rebalancing supply chains toward localized filling.
Chiang Mai Metro Area
Remote workers and digital nomads generate subscription-commerce demand for origin-specific arabica capsules. The Ministry of Natural Resources and Environment's sustainable packaging roadmap incentivizes biodegradable format trials. Specialty roasters in the city center partner with northern highland cooperatives for traceable micro-lot sourcing.
Eastern Economic Corridor
Industrial estate expansion attracts foreign beverage manufacturers seeking ASEAN export hub positioning. Board of Investment incentives for food processing equipment reduce capital expenditure barriers. Laem Chabang port proximity enables efficient green coffee bean import logistics for regional roasting operations.
Phuket and Southern Tourism Belt
International hotel chains and resort foodservice operations create demand for portion-controlled hospitality formats. Provincial FDA offices enforce food contact material standards for imported capsule inventories. Patong and Kata beach hospitality clusters favor hygienic single-serve systems over communal brewing equipment.
Northeastern Region
Khon Kaen and Udon Thani urban centers exhibit emerging modern trade penetration for supermarket capsule displays. Lower household machine ownership rates sustain instant powder substitution patterns. Regional distributors test aluminum-recyclable format acceptance ahead of extended producer responsibility implementation.
Thailand Coffee and Tea Capsules Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty arabica and sustainable format differentiation. Nestlé's Nespresso and Dolce Gusto brewing systems lock competitors into licensing dependencies or format exclusion. Three archetypes dominate: multinational beverage conglomerates with patent-protected ecosystems, European roasting houses competing on aluminum system pricing, and regional contract packers enabling localization. Competitive moves center on material format transitions and direct-to-subscription channel development.
Among European-based roasting specialists, Luigi Lavazza S.p.A. and Tchibo GmbH exemplify price-competitive aluminum system positioning. Nestlé S.A. anchors the premium tier through proprietary brewing ecosystem control. Jacobs Douwe Egberts B.V. occupies the office and foodservice procurement segment. These three represent divergent strategic archetypes: patent-locked ecosystem dominance, open-system price competition, and B2B channel specialization.
| Leading Market Players |
|---|
| Caffitaly System S.p.A. |
| Mondelez International, Inc. |
| Nestlé S.A. |
| Tchibo GmbH |
| Dualit Limited |
| The J.M. Smucker Company |
| Luigi Lavazza S.p.A. |
| Belmoca NV |
| Jacobs Douwe Egberts B.V. |
| Others |
Cost & Logistics Intelligence
Thai FDA labeling harmonization with ASEAN pre-packaged food standards is compressing import clearance timelines for European and Japanese capsule shipments, forcing brand owners toward localized filling partnerships that absorb compliance costs into landed pricing. This procurement preference shift toward domestic contract packers in Samut Prakan and Pathum Thani industrial zones is restructuring tiered pricing across premium aluminum systems and standard plastic formats.
Pricing Analysis
Machine-plus-capsule bundling with personalized roast profiles and same-day fulfillment warranties commands subscription premiums in Bangkok's Sukhumvit and Silom corridors, while unbundled transactional purchases at supermarkets face sharper price sensitivity. Price differentiation separates Nespresso-compatible aluminum systems from Dolce Gusto plastic formats through after-sales service inclusion and origin documentation tiers. Cost compression in standard plastic segments is intensifying because Thai roasters pass through Brazilian and Colombian green coffee futures volatility. Office procurement managers exhibit lowest price sensitivity due to hygiene-assurance budgeting, while provincial households in Khon Kaen and Udon Thani remain most responsive to promotional depth.
Supply Chain Analysis
Thai FDA food contact material certification and BIS-aligned voluntary standards for plastics create 12-18 month safety review gating for novel biodegradable polymers, slowing material transitions. Geographic supply concentration draws from Italy and Switzerland for premium aluminum capsule shell forming equipment, Vietnam and Malaysia for regional green coffee bean sourcing, and domestic Samut Prakan industrial zones for filling line operations. Raw material dependencies rest on Brazilian and Colombian arabica futures, aluminum sheet from ASEAN smelters, and plant-derived barrier coatings from experimental Thai biopolymer developers. Single-source vulnerability runs through Nestlé's patent-protected brewing system licensing. Distribution runs through modern trade supermarkets for impulse replenishment and direct-to-consumer platforms for subscription lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Thailand coffee and tea capsules market reads as a cost-of-compliance story where Thai FDA labeling mandates and pending extended producer responsibility timelines erect barrier-to-entry moats favoring pre-certified incumbents with localized filling infrastructure.
For Market Incumbents: To counter Jacobs Douwe Egberts' office channel penetration, Nestlé and Lavazza should deepen backward integration into Samut Prakan contract packing capacity and accelerate aluminum-recyclable format transitions ahead of Ministry of Natural Resources and Environment implementation deadlines. Certification investment in Thai FDA pre-approved packaging materials preserves import clearance speed advantages over European competitors facing documentation friction. For New Entrants and Emerging Players: Specialty roasters in Chiang Mai represent the most penetrable white-space target, where subscription-commerce density lags Bangkok and remote worker demand for traceable micro-lot arabica outstrips supply. Direct-to-consumer platforms with personalized roast profiling and same-day fulfillment partnerships bypass supermarket shelf-space competition locked by multinational display contracts. For Investors and Strategic Acquirers: The window for entry favors Thai contract packers with Thai FDA pre-certification and flexible manufacturing lines capable of parallel aluminum and compostable fiber runs. Acquisition targets should demonstrate established relationships with northern highland cooperatives for traceable bean sourcing. The signal to watch is Ministry of Natural Resources and Environment extended producer responsibility implementation date announcements, which will trigger capital deployment urgency for compliant format transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Filling Partnership | Bypasses Thai FDA import documentation complexity for European specialty arabica capsules. |
| Aluminum-Recyclable Format Transition | Captures green positioning ahead of Ministry of Natural Resources and Environment mandates. |
| Subscription-Commerce Platform Launch | Locks recurring revenue from Bangkok dual-income professionals through machine bundling. |
| Compostable Fiber Certification Track | Enables parallel BIS-aligned and Thai FDA approval for plant-based barrier coatings. |
| Office Channel Private-Label Program | Addresses post-pandemic workplace hygiene procurement shifts away from communal brewing. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with Thai FDA compliance officers, contract packing operations managers, modern trade category buyers, specialty roaster procurement leads, and office facilities managers. Secondary validation drew from Thai Ministry of Natural Resources and Environment sustainable packaging roadmap disclosures, ASEAN pre-packaged food standard harmonization documents, and Board of Investment food processing incentive filings. Bottom-up volume modeling across capsule format types triangulated with top-down value estimates from retail audit channels.
Granularity-level modeling disaggregated volume and value outputs by product type, distribution channel, end user, and packaging configuration across the projection horizon. CAGRs were derived from segment-level growth trajectory assessments incorporating machine installed base expansion rates, urban household density projections, and regulatory timeline assumptions. Forecast inputs included green coffee futures price volatility patterns, Thai FDA certification queue durations, and subscription-commerce penetration rates in metropolitan versus provincial clusters.
Caveats apply where Brazilian and Colombian arabica price spikes, Thai FDA labeling requirement acceleration, or extended producer responsibility implementation delays could materially shift the outlook. Forecasts reflect assumptions regarding machine replacement cycles and modern trade shelf-space allocation stability. A model refresh is warranted upon material change in Ministry of Natural Resources and Environment mandate announcement timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Coffee Grinder Market
Coffee
Cold Brew Coffee Makers Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Global Portable Coffee Makers Market
Coffee
Portable Espresso Machines Market
Coffee
GCC Instant Coffee Market
Coffee
Robusta Coffee Beans Market
Coffee
Global Nespresso Capsules Market
Coffee
US Coffee Machine Market
Coffee
Tea and Coffee Bags Market
Coffee
Latin America Coffee Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Mushroom Coffee Market
Coffee
Single-Serve Coffee Containers Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market