
 Europe Ready-To-Drink (RTD) Coffee Market | 2026-2036
Europe Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ready-To-Drink (RTD) Coffee Market Foresight
Barista-trained labor shortages across Southern Europe is unwinding production capacity for premium cold brew lines. Nestlé SA leverages its dairy-beverage infrastructure to sustain refrigerated distribution density in France and Spain. Starbucks Coffee Company anchors brand recognition through licensed café placements in UK transport hubs. PepsiCo Inc. competes via broad convenience store penetration with ambient-stable formulations.
Ready-To-Drink (RTD) Coffee denotes pre-brewed, shelf-stable or chilled coffee beverages packaged for immediate consumption, typically formulated with stabilizers and either dairy or plant-based milk systems, manufactured through hot extraction followed by aseptic or retort processing to preserve flavor integrity and food safety over extended distribution cycles. Cold Brew and Nitro variants command premium positioning as consumer palate sophistication rises in Scandinavia and the Netherlands. Aluminum Can packaging dominates volume throughput due to recycling infrastructure alignment with EU circular economy targets, while Tetra Pak occupies cost-sensitive retail tiers in Eastern Europe.
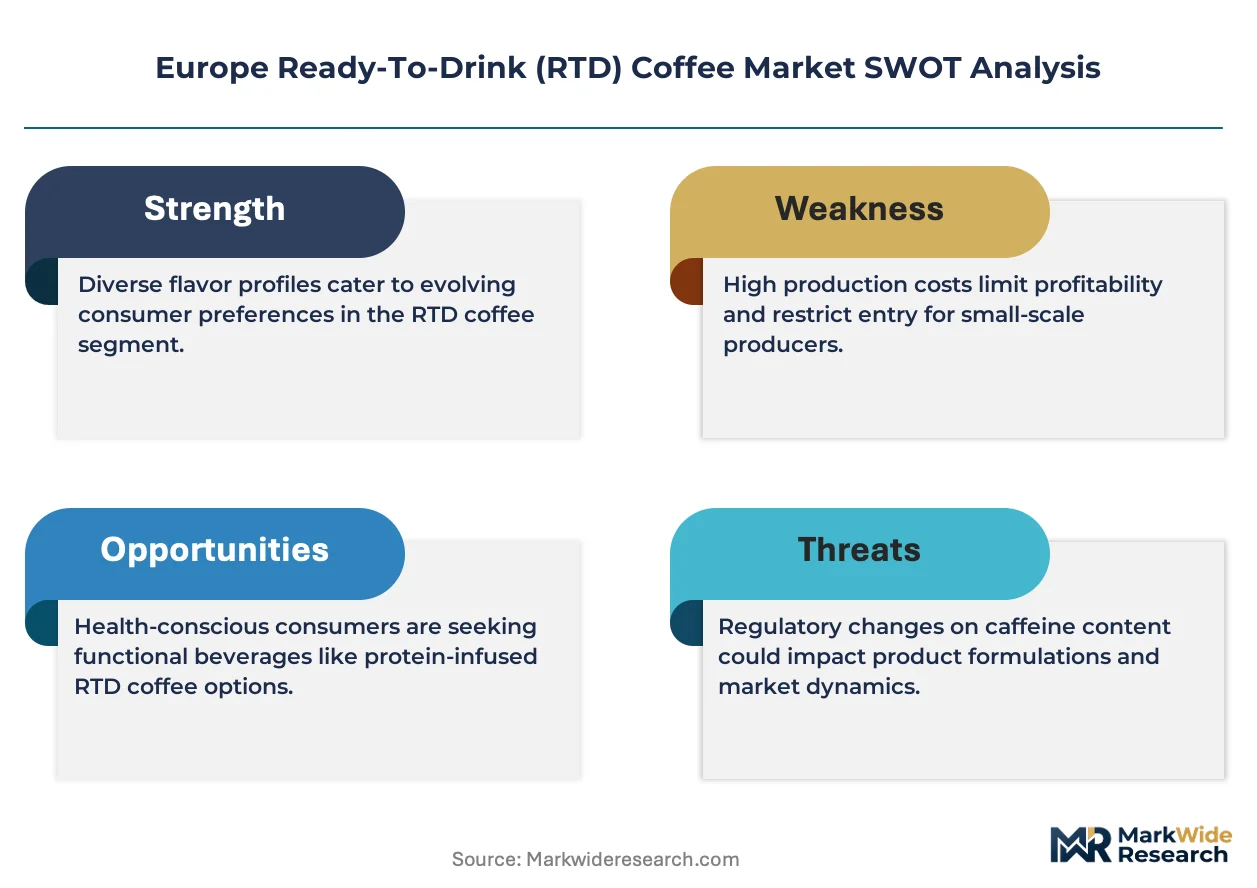
EFSA guidelines on added sugar labeling and the EU Green Deal packaging reduction frameworks are tightening formulation and material specifications across member states. REACH compliance for flavor additives and ECHA substance evaluations are extending R&D timelines for new product introductions. Stakeholders must monitor pending CSRD supply-chain disclosure requirements and their downstream effects on ingredient sourcing transparency.
Market Dynamics
Hybrid work patterns across Germany and France are restructuring consumption occasions, pulling RTD coffee from traditional convenience channels into home-office hybrid purchasing and corporate pantry replenishment cycles.
Growth Catalysts
- EU Green Deal packaging mandates:Aluminum can recycling targets are accelerating format conversion from plastic bottles, creating infrastructure pull-through in Germany and Scandinavia.
- Cold brew extraction technology:Ambient-stable nitrogen infusion systems are extending shelf life without refrigeration, unlocking convenience store distribution in Southern Europe.
- Metropolitan corridor densification:Germany's urban retail networks are concentrating demand in Berlin, Munich, and Hamburg transit-adjacent formats.
Market Restraints
- Arabica coffee price volatility:Input cost swings from Brazilian weather disruptions are compressing margin buffers for mid-tier formulations.
- Barista-trained labor scarcity:Southern Europe's skilled cold brew production workforce shortages are capping premium line expansion in Spain and Italy.
- EFSA added sugar labeling thresholds:Reformulation requirements for reduced-sugar claims are extending R&D cycles and retesting costs.
Strategic Opportunities
- Eastern European Tetra Pak tiers:Cost-sensitive retail channels in Poland and Romania present volume expansion paths for ambient-stable formats.
- Plant-based milk convergence:Oat and pea protein extraction technologies are opening clean-label positioning for lactose-intolerant segments in the Netherlands.
- CSRD supply-chain disclosure preparation:Early compliance with pending ingredient transparency mandates is creating first-mover sourcing advantages.
Industry Challenges
- REACH flavor additive evaluation timelines:ECHA substance reviews are delaying new product introductions by 12-18 months.
- Refrigerated distribution density gaps:Cold chain infrastructure limitations in rural France and Spain are constraining chilled RTD penetration.
- Aseptic processing certification backlogs:Equipment validation queues are bottlenecking production scale-up for emerging brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ready-To-Drink (RTD) Coffee Market |
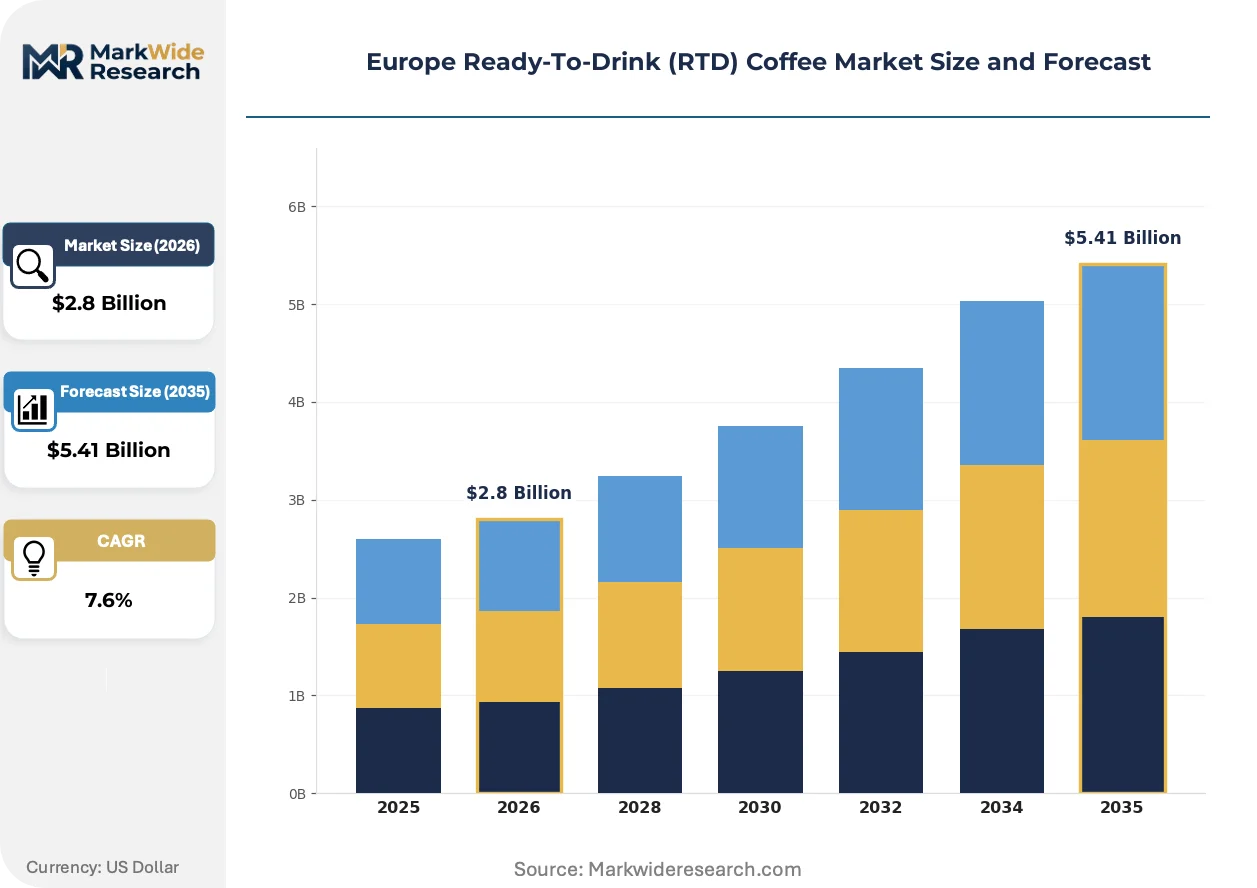
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeinated, Decaffeinated, Cold Brew, Nitro Flavor Profile: Mocha, Vanilla, Caramel, Hazelnut Packaging Type: Aluminum Can, Glass Bottle, Tetra Pak, PET Bottle Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Cafés |
| Companies Covered | Nestlé SA, The Coca-Cola Company, PepsiCo Inc., Starbucks Coffee Company, Luigi Lavazza S.p.A., Arla Foods amba, Emmi AG, Danone S.A., Keurig Dr Pepper, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ready-To-Drink (RTD) Coffee Market Shifts & Advancements
Nitrogen infusion and plant-based formulation advances are converging with regulatory packaging shifts to redefine product architecture and channel access across European markets.
Flash-chilled extraction systems using counter-current heat exchange are displacing traditional hot-brew-then-cool methods in Scandinavian production facilities. Premium cold brew manufacturers in Sweden and Denmark are adopting these systems to preserve volatile aromatic compounds. The technology is displacing retort-processed ambient lines in convenience retail, compressing shelf-life differentiation as a competitive moat.
REACH authorization requirements for synthetic flavor precursors are tightening formulation palettes across member states. ECHA's expanded substance evaluation list now covers key coffee flavor modulators used in vanilla and caramel variants. Northern European manufacturers are accelerating natural extract substitution programs to preempt authorization withdrawals.
Corporate pantry procurement through foodservice distributors is fragmenting traditional grocery-dominant purchasing patterns. Facility management providers in German and French office complexes are consolidating beverage contracts with direct-to-site delivery models. This channel rotation is most pronounced in Frankfurt and Paris business districts, where hybrid occupancy rates sustain bulk-format demand.
Europe Ready-To-Drink (RTD) Coffee Market Segmentation
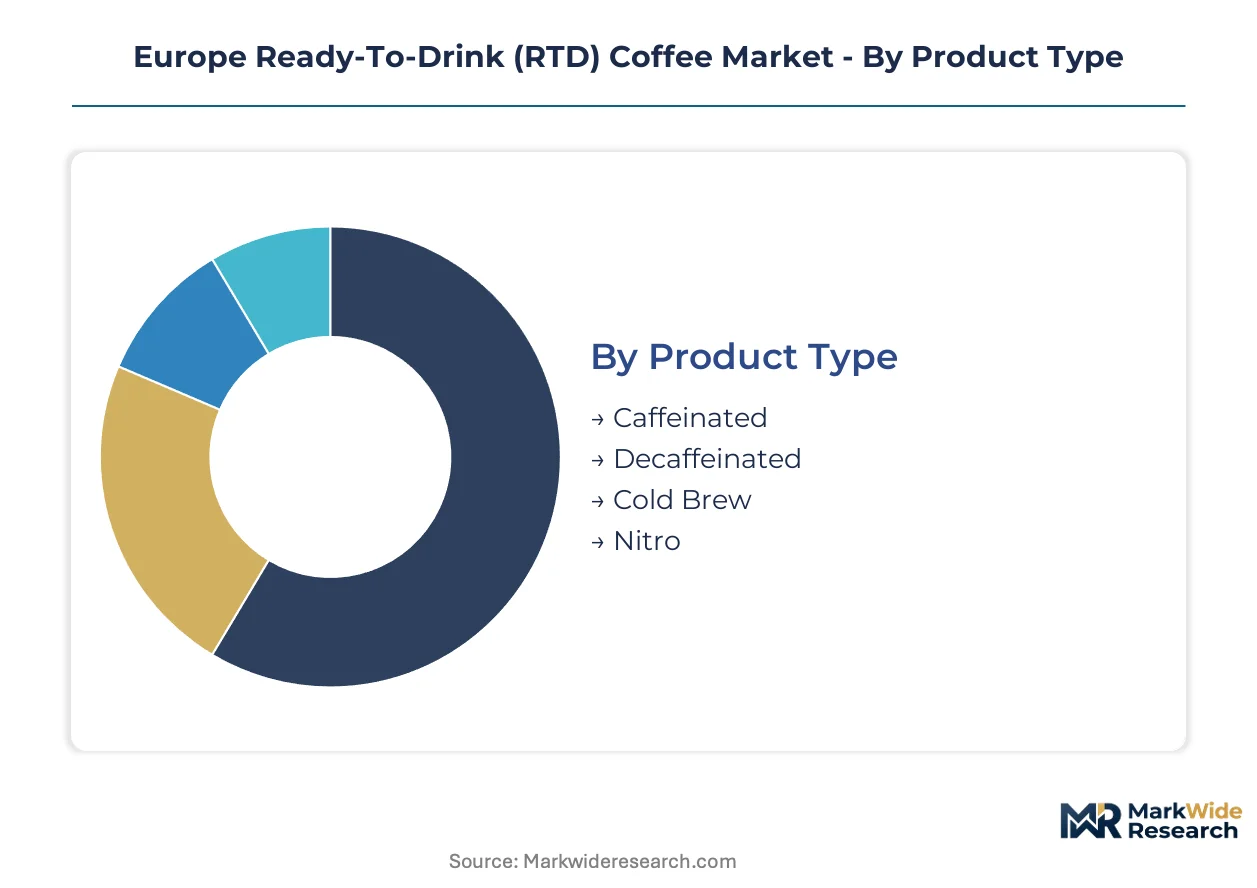
RTD coffee segmentation in Europe maps directly to channel access and regulatory compliance pathways. Each dimension carries distinct margin profiles and shelf-life requirements that determine viable geographic expansion.
Product Type:
Caffeinated formulations flow through high-velocity convenience retail, while decaffeinated and premium variants concentrate in supermarket premium tiers and corporate pantry channels.
- Caffeinated:Standard hot-extraction formulations with stabilizer systems dominate volume throughput in German and French transit-adjacent retail. Demand concentrates among hybrid office workers seeking morning consumption occasions in Berlin and Munich metropolitan corridors, with aluminum can formats aligning with EU Green Deal recycling mandates.
- Cold Brew:Ambient-stable nitrogen infusion systems extend shelf life without refrigeration, unlocking convenience store distribution in Southern Europe where cold chain density remains limited. Scandinavian manufacturers deploy flash-chilled extraction to preserve volatile aromatics.
- Decaffeinated:Solvent-free Swiss water process variants command shelf space in UK and Netherlands health-focused retail tiers.
- Nitro:Widget-can dispensing systems create draft-style texture for premium positioning in Dutch and Swedish café placements.
Caffeinated dominates installed base. Cold Brew is where expansion concentrates.
Flavor Profile:
Flavor selection determines REACH compliance burden and reformulation cycle length, with natural extract substitution programs accelerating in Northern Europe.
- Mocha:Cocoa-coffee hybrid formulations with dairy or oat milk systems anchor standard-tier supermarket placement across Germany and France. EFSA added sugar labeling thresholds are forcing reduced-sugar reformulation in these core markets.
- Vanilla:Natural bourbon extract variants face ECHA substance evaluation timelines that extend R&D cycles. Demand concentrates in UK transport hub licensed café placements where Starbucks anchors brand recognition through consistent flavor delivery.
- Caramel:Synthetic precursor substitution programs are underway in Sweden and Denmark to preempt authorization withdrawals.
- Hazelnut:Nut-allergen labeling requirements constrain formulation flexibility in German retail.
Mocha commands volume leadership. Vanilla faces the steepest regulatory headwinds.
Packaging Type:
Material selection directly determines recycling infrastructure alignment and access to EU member state retail networks.
- Aluminum Can:Dominates volume throughput due to alignment with EU circular economy targets and existing German and Scandinavian recycling infrastructure. Cold chain independence enables rural distribution expansion.
- Tetra Pak:Aseptic carton systems occupy cost-sensitive retail tiers in Poland and Romania where ambient stability outweighs premium positioning. Eastern European volume expansion paths rely on this format.
- Glass Bottle:Premium positioning in Italian and Spanish traditional retail with higher per-unit margins but constrained by weight-based distribution economics.
- PET Bottle:Facing format conversion pressure as EU Green Deal packaging reduction frameworks tighten plastic specifications.
Aluminum Can leads volume share. Tetra Pak offers the deepest cost-tier penetration.
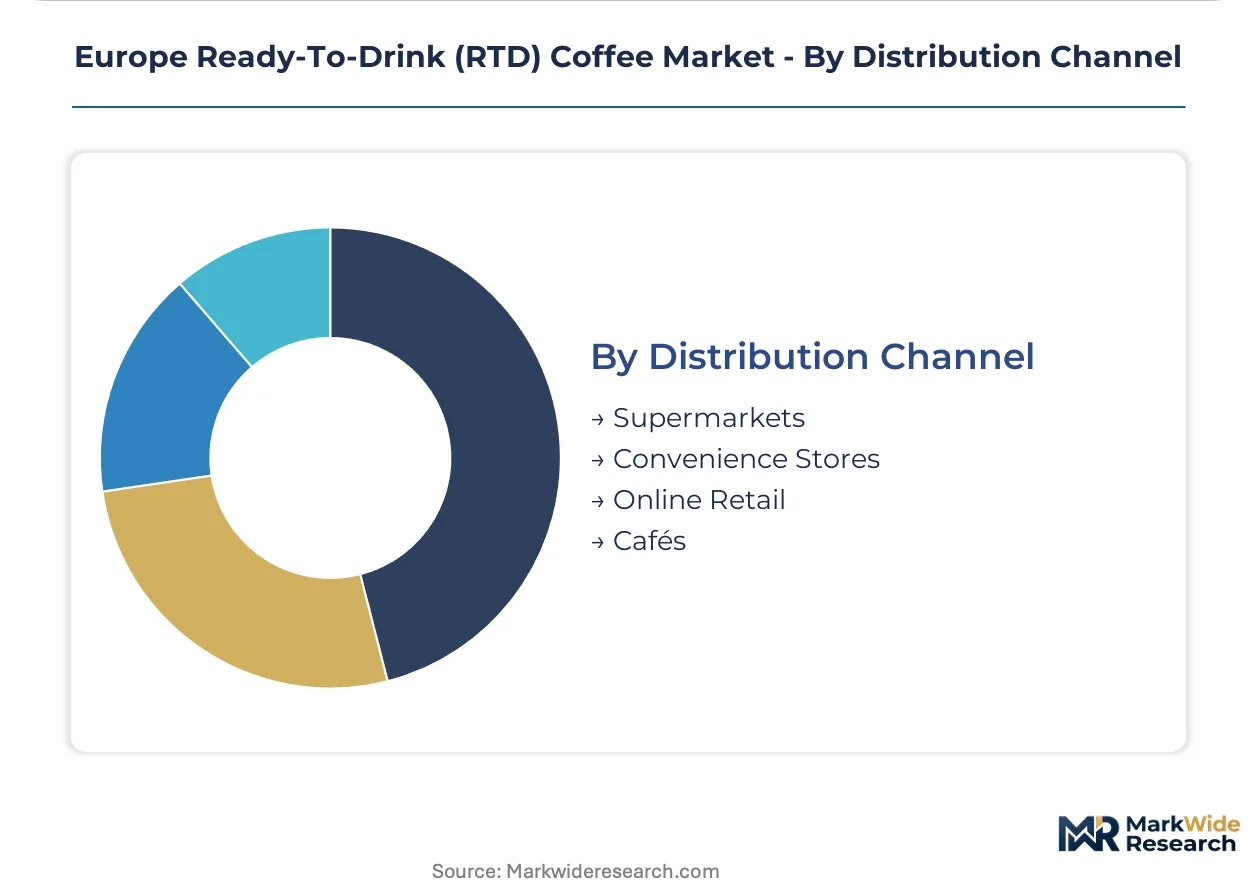
Distribution Channel:
Channel mix is restructuring as hybrid work patterns fragment traditional grocery-dominant purchasing.
- Supermarkets:Concentrated demand in Germany's urban retail networks with Berlin, Munich, and Hamburg transit-adjacent formats driving premium cold brew placement. Refrigerated case space allocation determines brand visibility.
- Convenience Stores:Ambient-stable nitrogen infusion systems unlock Southern European penetration where PepsiCo competes via broad format coverage. Rural France and Spain cold chain gaps constrain chilled alternatives.
- Online Retail:Direct-to-consumer subscription models gain traction in Netherlands and UK for plant-based oat and pea protein variants.
- Cafés:Licensed placement in UK transport hubs and German office complexes consolidates through facility management providers in Frankfurt and Paris business districts.
Supermarkets retain volume dominance. Corporate pantry procurement through foodservice distributors is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA guidelines on added sugar labeling and EU Green Deal packaging mandates anchor regulatory momentum across the continent. Germany's metropolitan retail corridors concentrate demand, while hybrid work patterns reshape consumption geography in France and the UK.
Germany
Berlin, Munich, and Hamburg transit-adjacent formats drive premium cold brew placement through refrigerated case space allocation. The EU Green Deal aluminum can recycling targets accelerate format conversion from plastic bottles, creating infrastructure pull-through in Bavaria and North Rhine-Westphalia. Corporate pantry procurement through facility management providers in Frankfurt business districts consolidates bulk-format demand among hybrid office workers.
France
Paris business districts sustain corporate pantry replenishment cycles through direct-to-site delivery models from foodservice distributors. REACH compliance requirements for flavor additives extend R&D timelines for new product introductions in Île-de-France. Cold chain infrastructure limitations in rural Auvergne-Rhône-Alpes constrain chilled RTD penetration, favoring ambient-stable nitrogen infusion systems.
United Kingdom
Licensed café placements in London transport hubs anchor brand recognition through consistent flavor delivery. ECHA substance evaluations on vanilla flavor modulators accelerate natural extract substitution programs among Northern English manufacturers. Scotland and Wales health-focused retail tiers command shelf space for solvent-free Swiss water process decaffeinated variants.
Netherlands
Oat and pea protein extraction technologies open clean-label positioning for lactose-intolerant segments in Amsterdam and Rotterdam metropolitan areas. CSRD supply-chain disclosure preparation creates first-mover sourcing advantages for Dutch manufacturers ahead of pending mandates. Premium nitro widget-can dispensing systems create draft-style texture positioning in Utrecht and Eindhoven café placements.
Spain
Barista-trained labor shortages across Catalonia and Andalusia unwind production capacity for premium cold brew lines. Ambient-stable formulations unlock convenience store distribution where PepsiCo competes via broad format coverage. Madrid's traditional retail maintains glass bottle premium positioning despite weight-based distribution economics constraints.
Europe Ready-To-Drink (RTD) Coffee Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational beverage conglomerates leveraging dairy infrastructure and licensed café networks against emerging cold brew specialists. The market structure reflects consolidation around refrigerated distribution density and aluminum can format dominance. Three archetypes define competitive positioning: dairy-integrated beverage giants, coffee-origin specialists with roasting heritage, and convenience-store-focused ambient-stable formulators. Capacity expansion in nitrogen infusion systems and strategic partnerships for plant-based milk sourcing represent the dominant competitive moves reshaping supply architecture.
Among Switzerland-based dairy-integrated conglomerates, Nestlé SA and Emmi AG exemplify the infrastructure-heavy archetype leveraging refrigerated distribution density across France and Spain. Starbucks Coffee Company anchors the coffee-origin specialist position through licensed placement strategies. PepsiCo Inc. occupies the ambient-stable convenience penetration tier, competing through broad format coverage where cold chain gaps persist.
| Leading Market Players |
|---|
| Nestlé SA |
| The Coca-Cola Company |
| PepsiCo Inc. |
| Starbucks Coffee Company |
| Luigi Lavazza S.p.A. |
| Arla Foods amba |
| Emmi AG |
| Danone S.A. |
| Keurig Dr Pepper |
| Others |
Supply & Pricing Matrix
Aluminum can substitution for PET formats across German and Scandinavian retail networks simultaneously compresses per-unit packaging costs and redraws procurement geography toward suppliers with EU Green Deal-certified recycling infrastructure. This material pivot tightens margin structures for plastic-dependent producers while rewarding early format converters with preferential shelf placement.
Pricing Analysis
Long-term offtake contracts between roasters and Brazilian arabica suppliers dominate input cost management, insulating premium cold brew manufacturers from spot market volatility that erodes mid-tier ambient formulations. Three-tier pricing structure across premium, standard, and economy levels reflects cold chain density, with refrigerated SKUs commanding shelf-space premiums in Berlin and Munich transit-adjacent retail. Pricing pressure stems from EFSA added sugar labeling mandates forcing reformulation investments. Corporate pantry procurement exhibits lowest price sensitivity; Eastern European Tetra Pak tiers face acute cost compression.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German supermarket chains, while Southern European distributors maintain strategic stockpiles of ambient-stable nitrogen-infused formats to bridge cold chain gaps in rural France and Spain. Arabica sourcing concentrates in Brazil, Vietnam, and Colombia; aluminum sheet supply draws from German and Norwegian smelters. Single-source vulnerability in Swiss water process decaffeination equipment creates bottlenecks. Distribution runs through temperature-controlled hubs in Rotterdam and Hamburg before last-mile fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal packaging mandates constitute a structural inflection, forcing format conversion investments that will separate viable scale players from stranded plastic-dependent operations. Cold brew nitrogen infusion technology compounds this disruption by unlocking ambient distribution in previously inaccessible Southern European corridors.
For Market Incumbents: Fortify refrigerated distribution density in French and Spanish metropolitan corridors through facility management partnerships, while accelerating backward integration into aluminum can manufacturing to preempt supply bottlenecks. Barista-trained labor scarcity in Catalonia and Andalusia threatens premium line expansion; automated flash-chilled extraction investment mitigates this workforce risk. For New Entrants and Emerging Players: Corporate pantry procurement consolidation among hybrid office complexes in Frankfurt and Paris presents a service-layer gap where incumbents under-serve direct-to-site delivery requirements. Target this channel with bulk-format oat milk cold brew subscriptions. Poland and Romania Tetra Pak tiers offer the most penetrable geography for ambient-stable volume entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cold brew specialists possessing nitrogen infusion patents but lacking refrigerated distribution scale. Five-to-ten year viability hinges on EU Green Deal compliance certification and CSRD supply-chain transparency readiness. Watch for ECHA flavor additive authorization withdrawals as the inflection signal triggering consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Can Format Conversion | Aligns packaging with EU Green Deal recycling targets in Germany and Scandinavia. |
| Nitrogen Infusion Capacity Buildout | Extends ambient shelf life for Southern European convenience store penetration. |
| Plant-Based Milk Sourcing Partnership | Secures oat and pea protein supply for Netherlands lactose-intolerant positioning. |
| Corporate Pantry Channel Expansion | Captures hybrid worker demand through Frankfurt and Paris facility management contracts. |
| Natural Extract Substitution Program | Preempts ECHA authorization withdrawals on vanilla and caramel flavor modulators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with RTD coffee brand managers, category buyers at German and French retailers, cold chain logistics operators, and flavor house technical directors; and secondary validation against EFSA guidance documents, ECHA substance evaluation registers, EU Green Deal implementation texts, and Nielsen retail audit data. Bottom-up volume modeling triangulated with top-down category spend estimates.
Across the projection horizon, the analytical framework segmented volume and value by product type, packaging material, flavor profile, and distribution channel, with hybrid work pattern intensity modeled as a demand shifter. CAGRs derived from trend extrapolation of aluminum can adoption curves and nitrogen infusion penetration rates in Southern Europe.
Forecasts assume regulatory continuity in EFSA labeling regimes and ECHA authorization timelines; material policy shifts would require re-modeling. Arabica price volatility, REACH evaluation delays, and cold chain infrastructure buildout pace constitute primary revision triggers. Revision becomes warranted when aluminum recycling infrastructure deployment crosses critical mass thresholds in Eastern Europe.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
GCC Instant Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Specialty Coffee Market
Coffee
Europe Coffee Market
Coffee
South America Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Oceania Coffee Market
Coffee
North America Coffee Market
Coffee
North America Specialty Coffee Market
Coffee
Global Coffee Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Tea and Coffee Bags Market
Coffee
Global Professional Coffee Machine Market
Coffee
Coffea Arabica (Coffee) Seed Oil Market
Coffee
UK Coffee Roaster Market