
 United States Coffee Market | 2026-2036
United States Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
United States Coffee Market Outlook
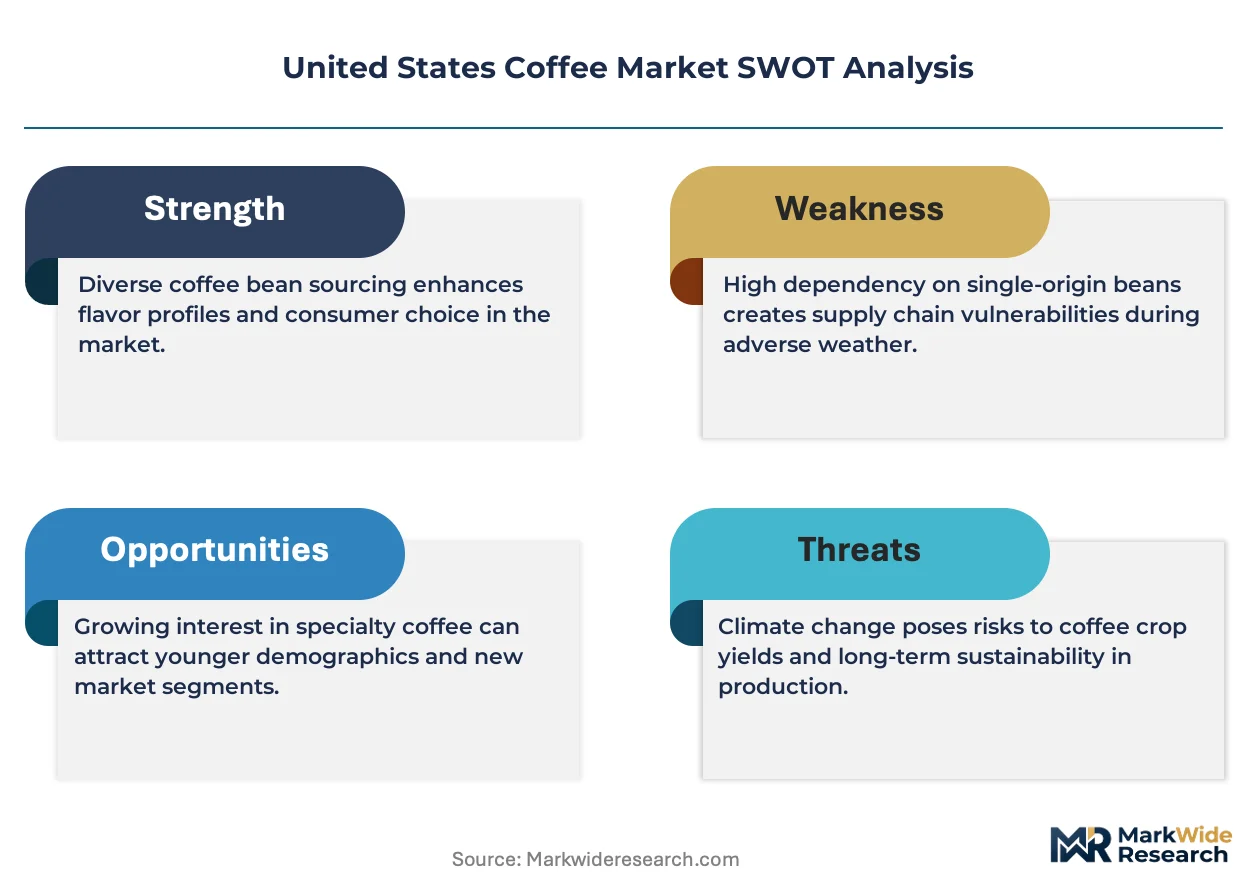
Cold brew nitrogen infusion and precision roasting software is reshaping production workflows across the United States coffee supply chain. Starbucks Corporation leverages its captive roasting network to sustain quality consistency at scale. Keurig Dr Pepper Inc anchors the single-serve pod segment through proprietary brewing systems. Nestlé S.A. competes in premium instant formulations with specialized freeze-drying infrastructure.
Coffee comprises roasted seeds from Coffea arabica and Coffea canephora (Robusta) species, processed through wet or dry methods to develop flavor compounds via Maillard reactions at temperatures exceeding 200°C, then ground and extracted for beverage consumption. Arabica Beans dominate specialty retail channels where margin pools concentrate on traceability certifications and origin narratives. Cold Brew preparation methods represent the fastest-growing segment as younger consumers shift toward lower-acidity, ready-to-drink formats. Ground Coffee retains volume leadership in traditional household brewing but faces gradual displacement from pod and cold formats.
The FDA enforces food safety standards under the Food Safety Modernization Act, requiring hazard controls across roasting and packaging facilities, while the USDA administers organic certification pathways that command price premiums in retail channels. State-level regulations in California, administered through Cal/OSHA and the California Department of Public Health, impose additional workplace exposure limits and processing facility standards that elevate operational compliance costs. Stakeholders must monitor evolving single-use packaging restrictions in municipal jurisdictions and assess whether biodegradable pod investments align with anticipated enforcement trajectories.
Market Dynamics
Cold brew nitrogen infusion and precision roasting software are compressing production cycles while reshaping capital allocation across roasting networks. The FDA's updated food labeling requirements are forcing simultaneous reformulation of packaged coffee portfolios.
Growth Catalysts
- Specialty channel expansion:Urban millennial demand in California's metropolitan corridors drives premium single-origin adoption and traceability investments.
- FSMA compliance infrastructure:Hazard control mandates under FDA's Food Safety Modernization Act accelerate automation in roasting and packaging facilities.
- Cold brew format innovation:Ready-to-drink lower-acidity products capture younger consumer preference shifts in convenience retail channels.
Market Restraints
- Arabica supply concentration:Weather volatility in Brazil and Colombia elevates input cost unpredictability for specialty roasters dependent on origin-specific sourcing.
- California regulatory layering:Cal/OSHA workplace exposure limits and CDPH processing standards compound compliance costs beyond federal baselines.
- Pod substitution dynamics:Single-serve convenience formats displace traditional ground coffee household penetration in suburban markets.
Strategic Opportunities
- Biodegradable pod transition:Municipal single-use packaging restrictions in California, Oregon, and Washington create first-mover advantage for compostable material investments.
- Freeze-drying technology convergence:Premium instant coffee formulations capture office and travel consumption occasions previously lost to out-of-home channels.
- USDA organic certification pathways:Price premiums in retail channels reward supply chain transparency investments and origin narrative development.
Industry Challenges
- Roasting technician scarcity:Precision software operation and nitrogen infusion system maintenance require specialized training programs that outpace vocational pipeline output.
- Legacy equipment integration:Cold brew production lines demand capital reconfiguration incompatible with traditional hot-brew infrastructure amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Coffee Market |
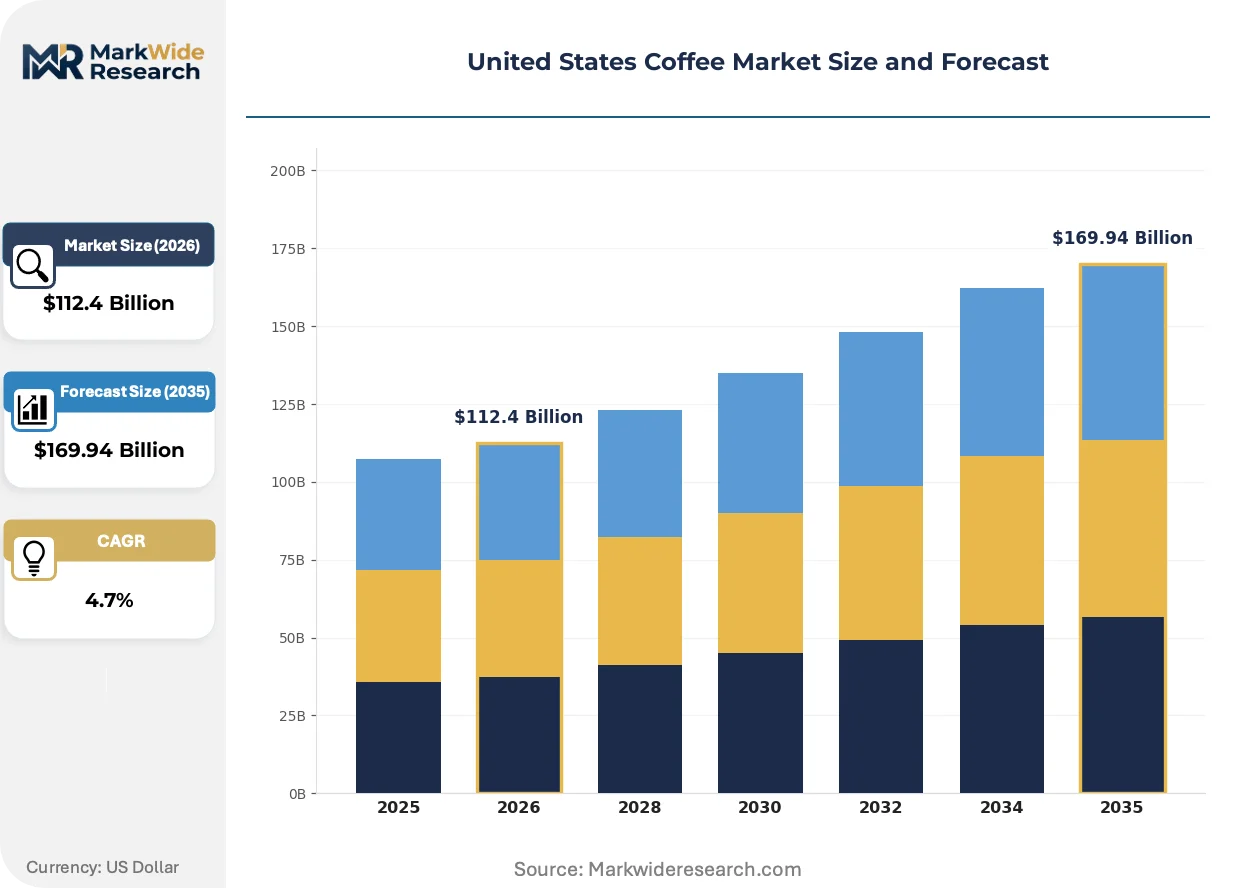
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica Beans, Robusta Beans, Instant Coffee, Ground Coffee Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Coffee Shops Consumer Type: Millennials, Baby Boomers, Professionals, Students Preparation Method: Espresso, Drip Brew, French Press, Cold Brew |
| Companies Covered | Starbucks Corporation, Keurig Dr Pepper Inc, Nestlé S.A., The J.M. Smucker Company, Dunkin’ Brands Group, Inc., JDE Peet's N.V., Caribou Coffee Company, Inc., Dutch Bros Coffee, McDonald's Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Coffee Market Strategic Shifts
Automation and sustainability mandates are compressing traditional production timelines while fragmenting distribution channels. Three distinct vectors are reconfiguring competitive positioning.
Nitrogen flushing systems for cold brew preservation are rendering obsolete conventional hot-brew concentrate methods. Third-wave coffee chains and ready-to-drink manufacturers deploy these systems at scale. The technology is rendering obsolete shelf-life limitations that previously constrained cold format geographic expansion.
California's municipal single-use packaging ordinances are accelerating biodegradable pod development timelines. Roasters must reformulate packaging specifications to maintain retail access in restricted jurisdictions. The pod segment faces the most acute compliance pressure, with manufacturers redirecting R&D spend toward compostable barrier materials.
Direct-to-subscription models are displacing traditional grocery channel dependence for premium arabica suppliers. Roasters bypass distributor markups to capture recurring revenue from home brewing enthusiasts. This shift concentrates in coastal metropolitan markets where delivery density supports unit economics.
United States Coffee Market Segmentation
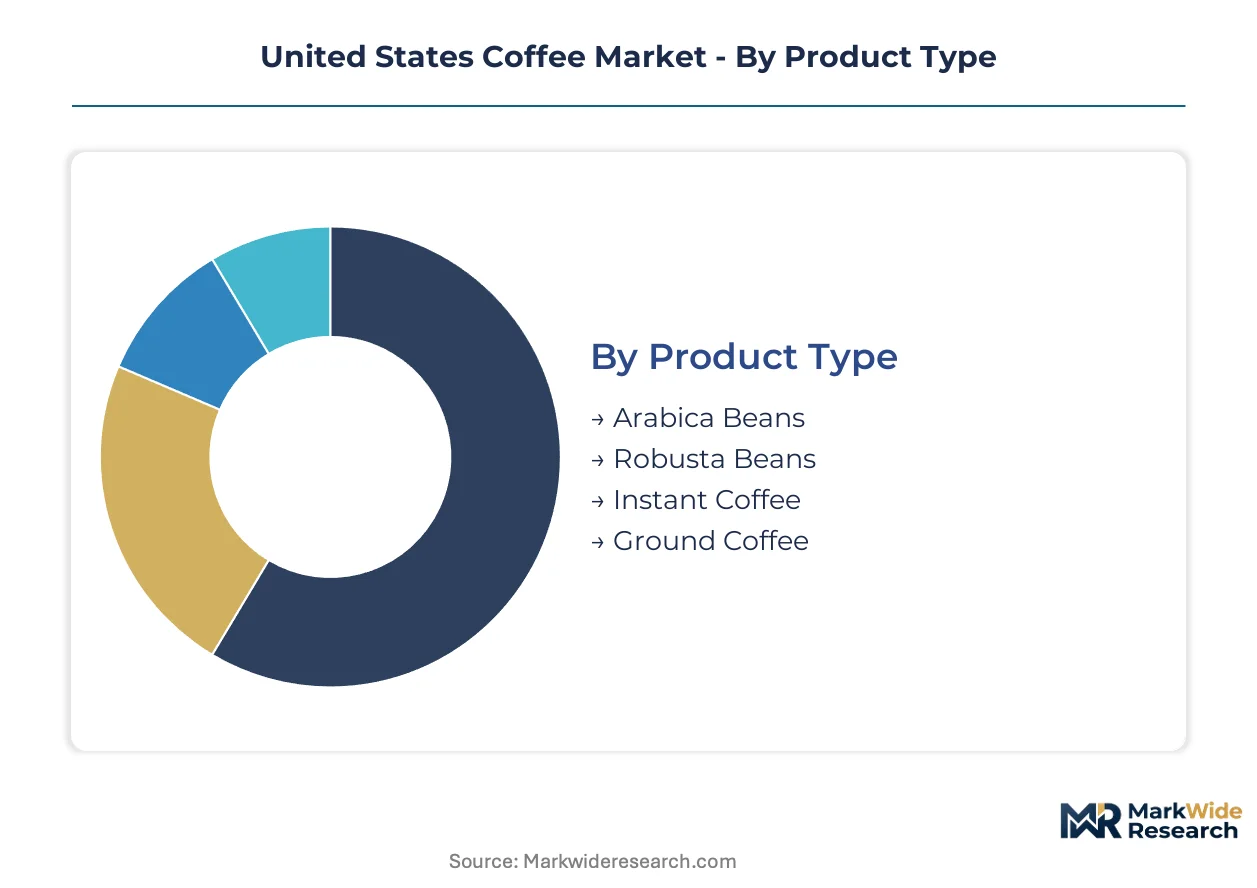
Segmentation reveals divergent margin structures across the United States coffee supply chain. Product format and preparation method drive the widest valuation spreads, while distribution channel selection determines customer acquisition economics and brand positioning latitude.
Product Type:
Mature formats anchor volume throughput while emerging categories capture premium pricing power.
- Arabica Beans:Higher-altitude cultivation yields complex acid profiles prized in specialty roasting. Demand concentrates in California's metropolitan corridors where traceability certifications and origin narratives command retail price premiums.
- Ground Coffee:Traditional household brewing format processed through roller or burr grinding to specified particle distributions. Suburban markets sustain volume leadership despite gradual displacement from pod and cold formats.
- Robusta Beans:Higher-caffeine, lower-acid species dominant in instant formulations and espresso blends.
- Instant Coffee:Freeze-dried or spray-dried extracts targeting convenience-oriented consumption occasions.
Ground Coffee retains volume leadership; Cold Brew preparation methods hold the steepest expansion curve.
Distribution Channel:
Channel selection stratifies by customer journey complexity and purchase frequency.
- Specialty Stores:Curated single-origin selections with staff-assisted education on processing methods and roast profiles. Urban millennial demand drives premium adoption and direct-trade sourcing investments.
- Online Retailers:Subscription models bypass distributor markups to capture recurring revenue from home brewing enthusiasts. Delivery density in coastal metropolitan markets supports unit economics for arabica suppliers.
- Supermarkets:Mass-market ground and pod formats with high-velocity replenishment cycles.
- Coffee Shops:Out-of-home consumption venues integrating roasting, brewing, and retail experience.
Supermarkets retain volume leadership; Online Retailers hold the steepest expansion curve.
Consumer Type:
Demographic cohorts exhibit divergent format preferences and price elasticity profiles.
- Millennials:Digital-native cohort prioritizing sustainability credentials and experiential consumption. Cold Brew and single-origin arabica adoption concentrates in this segment across California's metropolitan corridors.
- Professionals:Time-constrained workforce driving single-serve pod and premium instant demand for office and travel occasions.
- Baby Boomers:Established household brewing habits favoring traditional ground coffee formats.
- Students:Price-sensitive segment gravitating toward value-tier instant and private-label offerings.
Baby Boomers retain volume leadership; Millennials hold the steepest expansion curve.
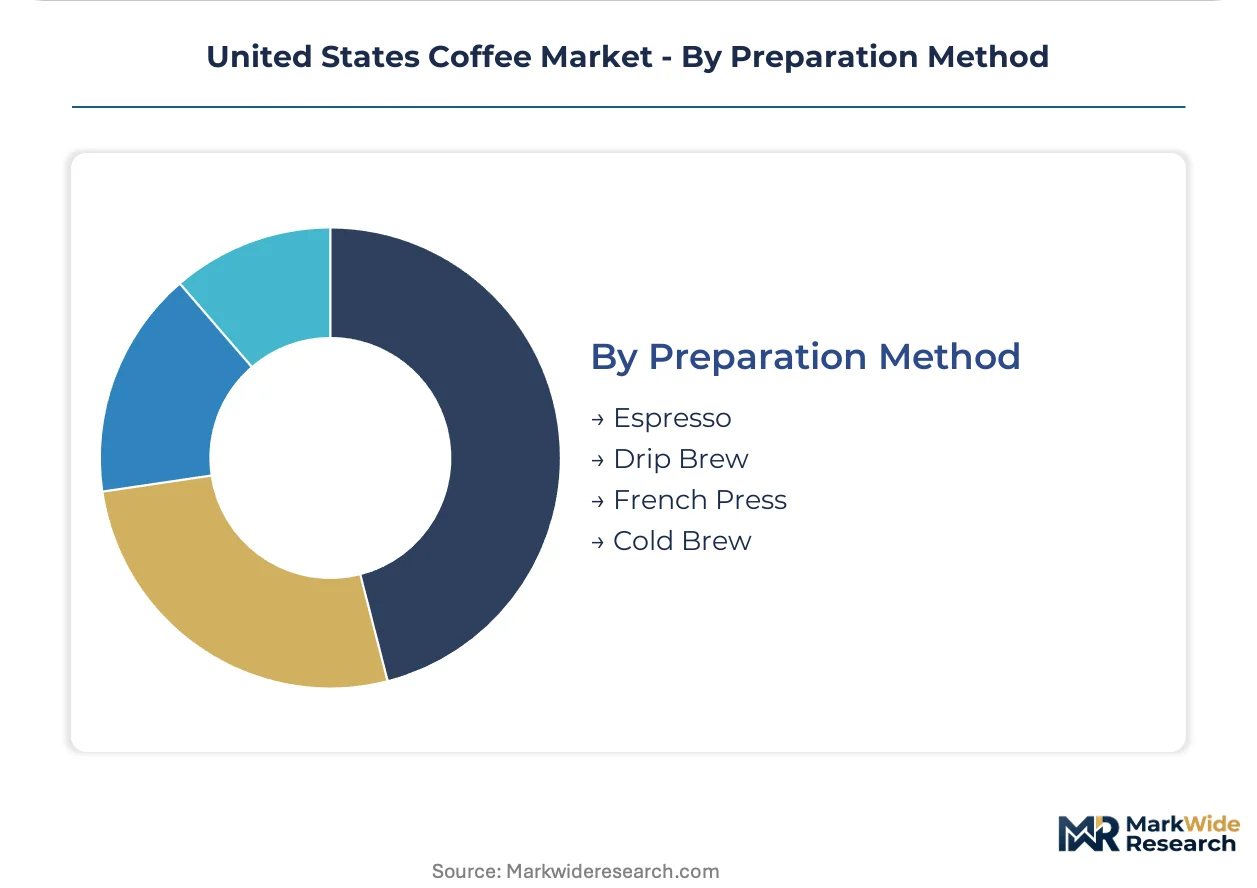
Preparation Method:
Technology and format innovation are compressing production cycles while fragmenting equipment requirements.
- Cold Brew:Extended steeping in ambient or refrigerated water produces lower-acidity concentrates. Ready-to-drink products capture younger consumer preference shifts in convenience retail channels.
- Espresso:High-pressure extraction at 9 bars and 90-96°C yielding concentrated shots. Specialty coffee shops deploy precision equipment to sustain quality consistency at scale.
- Drip Brew:Gravity-fed hot water filtration through paper or metal mesh. Traditional household penetration faces gradual displacement from pod systems.
- French Press:Immersion brewing with metal mesh filtration preserving aromatic oils.
Drip Brew retains volume leadership; Cold Brew holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial professionals and specialty coffee enthusiasts concentrate in coastal metropolitan corridors, driving premium arabica demand and cold brew adoption across distinct state-level regulatory environments.
California
Urban centers from Los Angeles to San Francisco anchor specialty channel expansion, with traceability certifications commanding retail premiums. Cal/OSHA workplace exposure limits and CDPH processing standards compound compliance costs beyond federal FDA baselines. The Los Angeles-Long Beach metro cluster hosts the highest density of third-wave roasting operations deploying nitrogen infusion systems.
Texas
Dallas-Fort Worth and Houston metropolitan areas sustain volume growth through corporate foodservice contracts and suburban household penetration. State environmental regulations under the Texas Commission on Environmental Quality govern roasting facility emissions. Austin's technology corridor incubates direct-to-subscription arabica suppliers leveraging delivery density for unit economics.
New York
Manhattan and Brooklyn specialty shops drive single-origin adoption among finance and media professionals. New York State Department of Agriculture and Markets enforces additional processing facility inspections beyond FDA FSMA requirements. The Hudson Valley roasting cluster supplies traceable beans to metropolitan retail channels.
Washington
Seattle's heritage roasting culture sustains premium market development alongside Portland spillover demand. The Washington State Department of Agriculture administers organic certification compliance pathways. Puget Sound metropolitan roasting networks integrate precision software for quality consistency at scale.
Florida
Miami-Dade and Orlando metropolitan corridors expand cold brew ready-to-drink distribution through convenience retail channels. Florida Department of Agriculture and Consumer Services regulates packaged coffee labeling requirements. The Tampa Bay industrial roasting zone supplies ground coffee formats to southeastern household markets.
United States Coffee Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated structure. The United States coffee market exhibits tiered consolidation, with captive roasting networks and proprietary brewing systems anchoring the upper tier while regional specialists occupy niche positioning. Three archetypes dominate: vertically integrated roaster-retailers, single-serve platform licensors, and premium instant formulators. Competitive moves concentrate on biodegradable packaging transitions and direct-to-subscription channel capture.
Within the integrated roaster-retailer archetype, Starbucks Corporation and Dutch Bros Coffee exemplify channel control through captive production networks. Keurig Dr Pepper Inc occupies the platform-licensor position, anchoring single-serve pod economics through proprietary brewing system deployment. Nestlé S.A. represents the premium instant tier, with freeze-drying infrastructure supporting office and travel consumption occasions.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Keurig Dr Pepper Inc |
| Nestlé S.A. |
| The J.M. Smucker Company |
| Dunkin' Brands Group, Inc. |
| JDE Peet's N.V. |
| Caribou Coffee Company, Inc. |
| Dutch Bros Coffee |
| McDonald's Corporation |
| Others |
Value Chain & Pricing Dynamics
Brazilian arabica harvest volatility concentrates margin capture among specialty roasters with multi-origin sourcing contracts. Premium single-origin lots command three-tier pricing structure across premium, standard, and economy levels based on traceability depth and cupping scores.
Pricing Analysis
Cost-plus contracts indexed to ICE arabica futures dominate green coffee procurement for mid-scale roasters. Price differentiation rests on certification tier—USDA organic and Rainforest Alliance command retail premiums—and volume scale with annual offtake commitments. Pricing pressure stems from Brazilian weather-induced spot volatility squeezing contract spreads. Private-label buyers exhibit highest price sensitivity; direct-trade specialty roasters show lowest.
Supply Chain Analysis
Green coffee feedstock draws from Brazil, Colombia, and Vietnam with harvest cycles staggered across hemispheres. Roasting networks depend on nitrogen gas supply, compostable packaging films, and precision roasting software licenses. Tariff exposure on Brazilian imports creates margin vulnerability for unhedged buyers. Distribution runs through captive retail networks, foodservice distributors, and direct-to-subscription platforms with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States coffee market functions as a defensive-moat arena where captive roasting networks and proprietary brewing systems erect switching-cost barriers against displacement.
For Market Incumbents: Insulate margin pools by deepening backward integration into origin-specific sourcing partnerships and accelerating biodegradable pod certification to preempt municipal packaging bans. Cold brew nitrogen infrastructure and precision roasting software operation create technician scarcity that reinforces competitive position. For New Entrants and Emerging Players: Pursue white-space capture in direct-to-subscription arabica channels where delivery density in coastal metropolitan markets supports unit economics. Freeze-dried premium instant formulations targeting office and travel occasions offer the most penetrable entry vector with lower capital intensity than roasting infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated roaster-retailers with captive production networks and established traceability narratives that sustain pricing power across demand cycles. Watch biodegradable packaging mandate enforcement trajectories in California, Oregon, and Washington as inflection signals for compostable material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Pod Transition | Compostable barrier material investments secure retail access under California municipal packaging ordinances. |
| Direct-to-Subscription Launch | Recurring revenue capture from home brewing enthusiasts bypasses traditional distributor markups. |
| Freeze-Drying Technology Deployment | Premium instant formulations capture office and travel consumption occasions from out-of-home channels. |
| Multi-Origin Sourcing Contracts | ICE futures-indexed procurement hedges Brazilian weather volatility for specialty roasting operations. |
| Nitrogen Infusion System Scale-Up | Cold brew preservation infrastructure extends shelf-life limits for geographic expansion beyond coastal markets. |
Study Parameters
The analysis maps arabica sourcing tiers, roasting equipment categories, and distribution channel economics, each validated through primary interviews with green coffee traders, roasting facility operators, and specialty retail buyers. Secondary sources include USDA organic certification databases, FDA FSMA inspection records, and customs import manifests. Bottom-up volume triangulation across preparation methods and top-down value reconciliation against retail channel audits anchored the market sizing.
Assumptions held fixed include FDA enforcement intensity on food safety modernization and municipal packaging restriction trajectories in West Coast jurisdictions. Segmentation modeling spanned product format, preparation method, distribution channel, and consumer demographic cohort. CAGRs derived from trend-line extrapolation of cold brew adoption curves and pod substitution rates, calibrated against arabica futures price elasticity and specialty channel expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and Brazilian real exchange rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and technology adoption S-curves. Cross-checking against Nielsen retail audit data and ICE futures volume reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Portable Espresso Machines Market
Coffee
Coffee Pods Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Italy Coffee Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Latin America Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Out-Of-Home Coffee Market
Coffee
Global Coffee Shop Market
Coffee
Coffee Grinder Market
Coffee
Decaffeinated Coffee Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Cold Brew Coffee Pots Market
Coffee
Espresso Tamper Market
Coffee
Germany Coffee Market
Coffee
Coffee Extracts Market