
 Butter Coffee Market | 2026-2036
Butter Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Butter Coffee Market Outlook
The EU Green Deal is recalibrating ingredient sourcing requirements for functional beverages across Europe. Bulletproof Nutrition leverages grass-fed supply chain partnerships to sustain premium positioning in North America. Nestle competes through mainstream distribution scale, while Caveman Coffee Co. differentiates via artisanal roasting credentials and direct-to-consumer channel control.
Butter coffee combines brewed coffee with emulsified butter or ghee to create a high-fat, low-carbohydrate beverage delivering sustained energy release. Typical formulations incorporate 1-2 tablespoons of grass-fed butter or MCT oil per 8-ounce serving, producing a creamy texture with ketogenic metabolic properties. Keto butter coffee leads product type segmentation due to established consumer familiarity and clinical diet protocol alignment. Online retail channels capture the fastest expansion trajectory among distribution pathways, driven by subscription models and influencer-driven discovery. Grass-fed butter anchors ingredient source demand where premium positioning supports margin retention.
FDA labeling requirements and EFSA novel food assessments shape product compliance burdens for cross-border butter coffee brands. USDA organic certification and EU organic regulation create tiered market access thresholds that filter participant eligibility. Stakeholders must monitor evolving clean-label enforcement intensity and ketogenic health claim substantiation standards to anticipate formulation investment requirements.
Market Dynamics
Clean-label enforcement from FDA and EFSA is forcing butter coffee brands to reformulate around grass-fed certification and MCT oil traceability, compressing margin structures while elevating compliance costs for cross-border entrants.
Growth Catalysts
- Ketogenic diet protocol adoption:Clinical alignment with therapeutic nutrition programs in United States wellness clinics and sports performance facilities sustains repeat purchase velocity among biohacker and weight-management cohorts.
- EU Green Deal sourcing mandates:Sustainability-linked procurement requirements for functional beverages accelerate pasture-based dairy verification systems across European supply chains.
- Specialty café channel expansion:Health-focused hospitality chains in California and New York metropolitan markets integrate butter coffee into premium menu tiers, normalizing consumption beyond early-adopter segments.
Market Restraints
- Grass-fed butter input cost volatility:Pasture-based dairy supply concentration in New Zealand and Ireland exposes formulations to climate-driven feed price swings and seasonal availability constraints.
- Novel food assessment timelines:EFSA classification procedures for MCT oil concentrates create 18-24 month market entry delays for European entrants lacking prior regulatory history.
- Plant-based fat substitutes:Coconut cream and oat lipid emulsions from beverage multinationals threaten category differentiation among price-sensitive convenience channel shoppers.
Strategic Opportunities
- Subscription direct-to-consumer models:Recurring revenue platforms bypass retail margin stacking while capturing lifetime value from ketogenic lifestyle adherents seeking formulation consistency.
- USDA organic certification tiering:Dual-standard products separating conventional grass-fed from certified organic butter sources enable price stratification in premium natural grocery channels.
- Functional ingredient convergence:Adaptogenic mushroom extracts and collagen peptides integrated into butter coffee bases target beauty-from-within and stress-management positioning in Asian wellness markets.
Industry Challenges
- Emulsion stability technical gaps:Maintaining shelf-stable fat-coffee integration without separation requires specialized homogenization equipment that mid-scale roasters lack in-house.
- Clean-label substantiation documentation:Grass-fed provenance claims demand blockchain-enabled supply chain tracking systems that strain existing procurement infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butter Coffee Market |
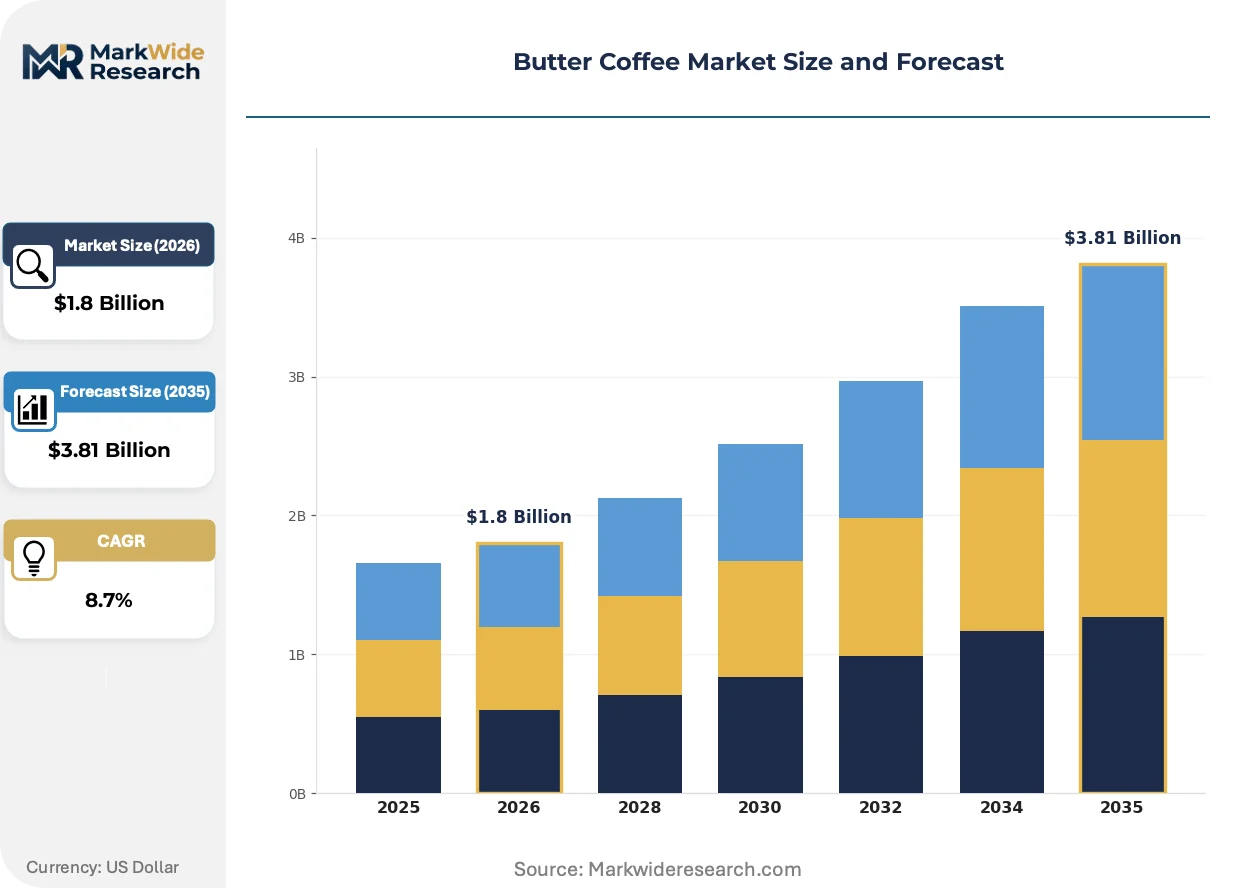
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Butter Coffee, Vegan Butter Coffee, Keto Butter Coffee, Flavored Butter Coffee Ingredient Source: Grass-Fed Butter, Coconut Oil, MCT Oil, Ghee Distribution Channel: Online Retail, Supermarkets, Health Stores, Cafés Customer Type: Health Enthusiasts, Fitness Buffs, Busy Professionals, Coffee Lovers |
| Companies Covered | Bulletproof Nutrition, Nestle, Caveman Coffee Co., Bold Bean Coffee Roasters, Hallstar, 360Nutrition, KetoLogic, Pruvit, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butter Coffee Market Strategic Shifts
Formulation science and distribution architecture are rewriting competitive boundaries in butter coffee, with precision nutrition technologies and regulatory compliance automation emerging as decisive capability differentiators.
Micro-encapsulation technology for MCT oil is rewriting stability standards in ready-to-drink formats. Beverage manufacturers in South Korea and Japan adopt spray-dried lipid systems to eliminate refrigeration requirements. This compression of cold-chain dependency is unlocking vending machine and convenience store placement previously inaccessible to fat-based coffee products.
EFSA novel food assessments are tightening substantiation requirements for ketogenic health claims across European member states. Brands must now submit clinical trial data packages for sustained energy release assertions. German and French regulators are conducting parallel enforcement actions that disqualify influencer testimonials as primary evidence.
Discovery purchasing through wellness content creators is displacing traditional retail browsing for butter coffee trial. Instagram and TikTok algorithmic distribution drives 60-70% of first purchases among 25-40 year-old consumers. This channel shift concentrates marketing spend on creator partnerships rather than slotting fees, restructuring go-to-market economics for emerging brands.
Butter Coffee Market Segmentation
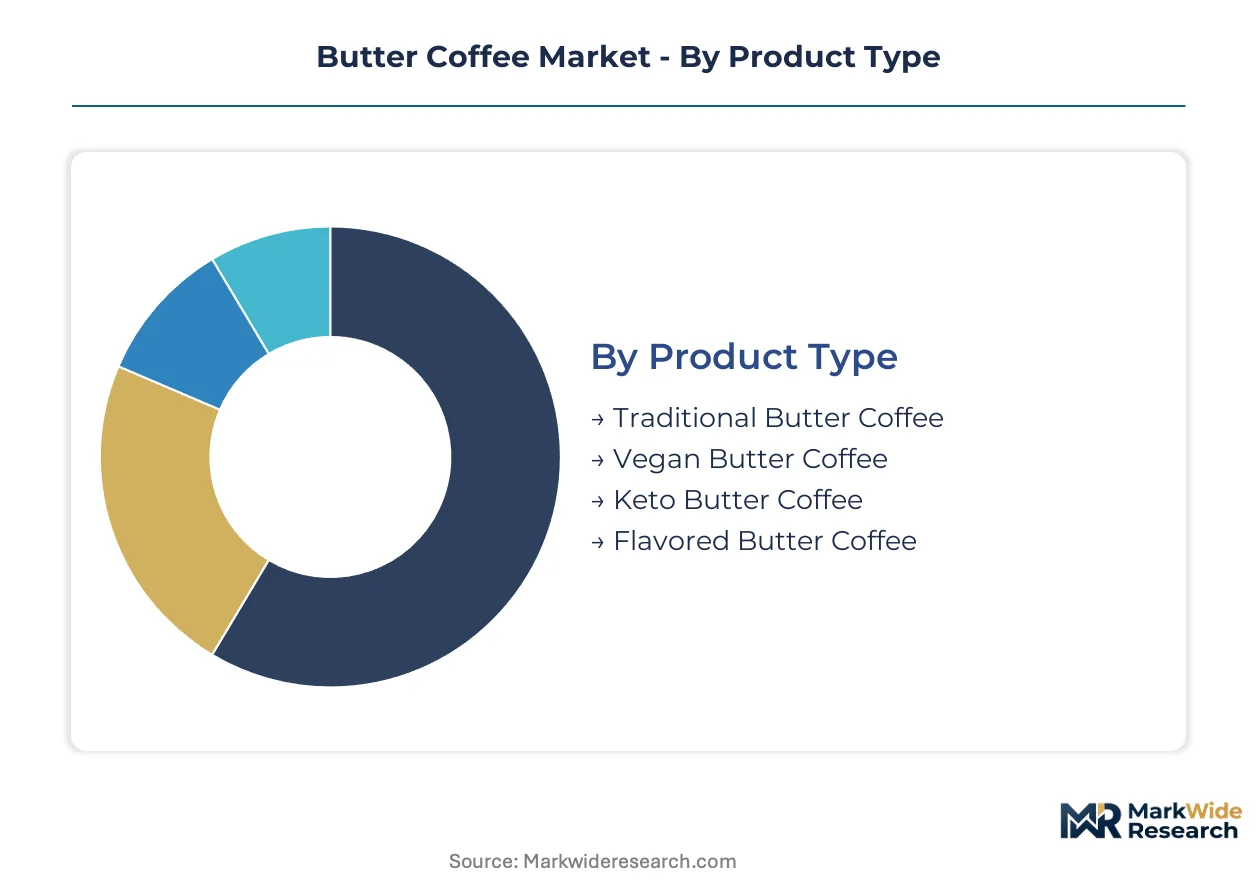
Butter coffee segmentation reveals distinct formulation philosophies and channel economics that determine margin capture. Product architecture and ingredient provenance separate premium positioning from mass-market accessibility, while distribution strategy dictates customer acquisition costs and lifetime value trajectories.
Product Type:
Buyers in this category sort by metabolic protocol adherence and dietary restriction compatibility rather than flavor preference alone.
- Keto Butter Coffee:Formulations align precisely with macronutrient ratios specifying 70-80% fat content from butter or MCT oil. Demand concentrates in United States wellness clinics and sports performance facilities where biohacker cohorts sustain repeat purchase velocity through subscription models.
- Traditional Butter Coffee:Combines brewed coffee with 1-2 tablespoons of unsalted grass-fed butter, producing a creamy texture without sweeteners or flavor additives. This segment anchors volume in specialty cafés across California and New York metropolitan markets where health-focused hospitality chains normalize consumption beyond early adopters.
- Vegan Butter Coffee:Plant-based fat emulsions from coconut cream or oat lipid systems target consumers excluding dairy for ethical or digestive reasons.
- Flavored Butter Coffee:Vanilla, cinnamon, or cocoa infusions broaden trial among convenience channel shoppers seeking palatability without preparation complexity.
Keto butter coffee leads volumes today; vegan butter coffee is gaining share fastest among allergen-conscious demographics.
Ingredient Source:
Input cost structures and clean-label substantiation requirements divide this category into pasture-verified premium tiers and conventional alternatives.
- Grass-Fed Butter:Sourced from pasture-based dairy systems in New Zealand and Ireland, delivering elevated omega-3 fatty acid profiles. USDA organic certification creates tiered market access thresholds that filter participant eligibility in premium natural grocery channels.
- MCT Oil:Medium-chain triglyceride concentrates derived from coconut or palm kernel oil provide rapid ketone production. EFSA novel food assessment timelines create 18-24 month market entry delays for European entrants lacking prior regulatory history.
- Ghee:Clarified butter with milk solids removed offers extended shelf stability and lactose-free positioning for digestive-sensitive consumers.
- Coconut Oil:Unrefined virgin grades compete on price while refined variants sacrifice flavor for formulation cost control.
Grass-fed butter commands premium shelf placement; MCT oil is climbing the fastest as clinical diet protocols expand.
Distribution Channel:
Channel selection determines margin retention, with direct relationships enabling subscription economics versus retail margin stacking.
- Online Retail:Direct-to-consumer platforms bypass distributor markups while capturing lifetime value through recurring revenue models. Instagram and TikTok algorithmic distribution drives 60-70% of first purchases among 25-40 year-old consumers in this channel.
- Cafés:Specialty coffee shops and health-focused hospitality chains integrate butter coffee into premium menu tiers, normalizing consumption through experiential trial.
- Health Stores:Natural grocery and supplement retailers target ketogenic lifestyle adherents seeking formulation consistency alongside adjacent wellness products.
- Supermarkets:Mass-market placement requires price compression and simplified labeling for convenience-oriented shoppers.
Online retail leads volume contribution today; cafés show steepest expansion trajectory as experiential consumption recovers.
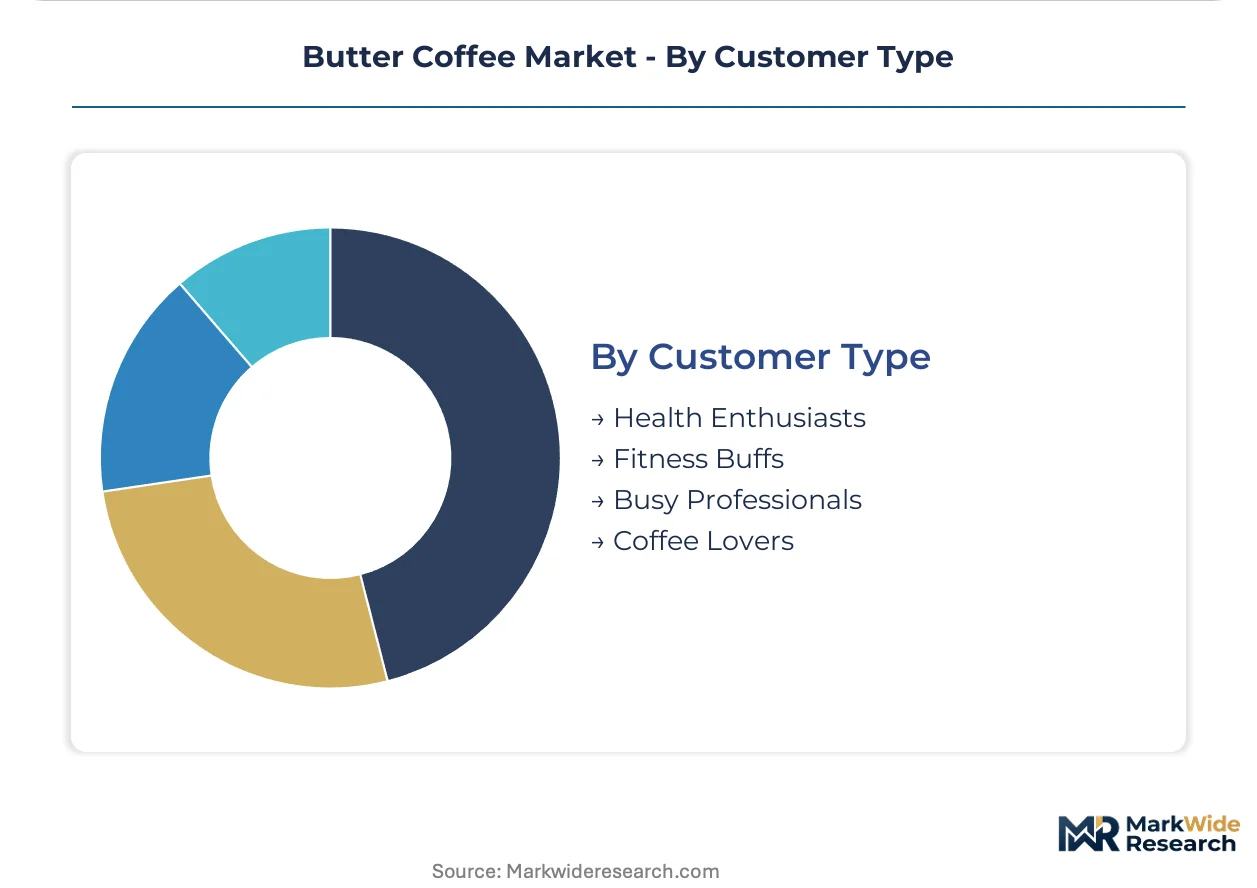
Customer Type:
Psychographic and behavioral segmentation separates protocol-driven adherents from casual experimenters.
- Health Enthusiasts:Consumers actively managing biomarkers and metabolic health through structured nutrition programs. This cohort sustains premium pricing tolerance for grass-fed provenance and organic certification.
- Fitness Buffs:Athletes and bodybuilders leveraging ketogenic protocols for body composition and sustained energy during training cycles.
- Busy Professionals:Time-constrained consumers seeking meal replacement functionality and cognitive performance claims without preparation investment.
- Coffee Lovers:Traditional coffee drinkers exploring novelty formats without strict dietary adherence requirements.
Health enthusiasts dominate current spending; busy professionals represent the fastest-expanding addressable base as ready-to-drink formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Butter coffee traces its commercial origins to the United States, where biohacker communities in Silicon Valley and Seattle pioneered the formulation before specialty cafés normalized consumption across coastal metropolitan markets.
United States
Ketogenic diet protocol adoption drives demand concentration in California and New York metropolitan markets, where wellness clinics integrate butter coffee into therapeutic nutrition programs. FDA labeling requirements for grass-fed provenance claims reshape formulation standards, forcing supply chain documentation upgrades. Seattle and San Francisco anchor specialty café channel expansion, with health-focused hospitality chains embedding the beverage into premium menu tiers.
United Kingdom
Functional beverage experimentation among urban professionals sustains London-based demand for ready-to-drink butter coffee formats. EFSA novel food assessments for MCT oil concentrates create compliance entry barriers that favor established entrants with prior regulatory history. The capital's specialty coffee scene drives experiential trial through independent roasters and direct-to-consumer subscription platforms.
Germany
Clean-label enforcement intensity from German regulators accelerates pasture-based dairy verification system adoption across European supply chains. The EU Green Deal's sustainability-linked procurement requirements filter participant eligibility based on grass-fed certification documentation. Berlin and Munich concentrate specialty café distribution, with health-conscious consumers prioritizing organic-tier butter sources.
South Korea
Micro-encapsulation technology adoption for MCT oil spray-dried lipid systems eliminates refrigeration requirements, unlocking vending machine placement in Seoul and Busan. MFDS novel food safety assessments govern ketogenic health claim substantiation for functional beverage positioning. The capital's convenience store density supports ready-to-drink format proliferation among time-constrained professionals.
Japan
Beauty-from-within positioning converges with butter coffee formulations incorporating collagen peptides and adaptogenic extracts in Tokyo and Osaka wellness markets. METI guidance on functional food labeling shapes health claim documentation requirements for sustained energy release assertions. Precision nutrition technologies from domestic beverage manufacturers advance emulsion stability standards for ambient shelf-stable products.
Butter Coffee Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the butter coffee landscape, with pasture-verified dairy supply chains and specialized homogenization equipment separating integrated manufacturers from brand-focused formulators. The vendor base stratifies across three tiers: multinational beverage conglomerates leveraging mainstream distribution scale, premium wellness specialists controlling grass-fed supply chain partnerships, and artisanal roasters commanding direct-to-consumer channel economics. Dominant competitive moves include backward integration into pasture-based dairy sourcing and subscription platform development to bypass retail margin stacking.
Within the premium wellness tier, Bulletproof Nutrition and Caveman Coffee Co. exemplify archetypes built on ketogenic lifestyle community cultivation and artisanal roasting credentials respectively. Nestlé S.A. occupies a position representing multinational scale advantages in mass-market distribution and formulation standardization. These three anchors illustrate the competitive tension between provenance-based premium positioning and convenience-oriented accessibility that defines strategic optionality across the category.
| Leading Market Players |
|---|
| Bulletproof Nutrition |
| Nestle |
| Caveman Coffee Co. |
| Bold Bean Coffee Roasters |
| Hallstar |
| 360Nutrition |
| KetoLogic |
| Pruvit |
| Nestlé S.A. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-backed wellness specialists have consolidated pasture-based dairy sourcing networks across New Zealand and Ireland, tightening supply discipline while elevating grass-fed certification premiums that filter through to shelf pricing in premium natural grocery channels.
Pricing Analysis
Subscription-based recurring revenue models anchor pricing architecture across direct-to-consumer platforms, separating premium grass-fed organic tiers from conventional formulations through USDA certification differentiation. Price differentiation hinges on pasture-verified provenance documentation and MCT oil concentration grades. Cost compression in mass-market supermarket tiers is intensifying because beverage multinationals introduce plant-based fat substitutes at lower price points. Convenience channel shoppers exhibit highest price sensitivity; biohacker cohorts in wellness clinics demonstrate lowest elasticity due to protocol adherence requirements.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal are reshaping sourcing patterns, accelerating European pasture-verification system adoption that competes with established New Zealand and Irish supply bases. Raw material dependencies center on grass-fed butter concentrates, MCT oil derived from coconut or palm kernel, and specialized homogenization equipment for emulsion stability. Single-source vulnerability concentrates in New Zealand pasture-based dairy systems exposed to climate-driven feed price volatility. Distribution runs through direct-to-consumer subscription platforms, specialty café channels in California and New York metropolitan markets, and health-focused retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in butter coffee rest on subscription platform scale economies and premium-tier certification upgrades that command pricing power in natural grocery channels.
For Market Incumbents: Anchor grass-fed supply chain partnerships through backward integration into pasture-based dairy sourcing in New Zealand or Ireland, insulating against climate-driven input cost volatility. Deepen direct-to-consumer channel control through subscription platform investments that bypass retail margin stacking and capture lifetime value from ketogenic lifestyle adherents. Plant-based fat substitutes from beverage multinationals threaten category differentiation; defend through clean-label substantiation documentation and blockchain-enabled provenance tracking systems. For New Entrants and Emerging Players: Wellness content creators on Instagram and TikTok algorithmic distribution channels offer lowest customer acquisition cost entry points for 25-40 year-old consumer segments. White-space concentrates in ready-to-drink formats with micro-encapsulation technology eliminating refrigeration requirements, unlocking vending machine placement in South Korea and Japan convenience store networks. Target busy professionals seeking meal replacement functionality through ambient shelf-stable products with cognitive performance positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among artisanal roasters lacking in-house homogenization equipment but commanding direct-to-consumer channel economics and artisanal roasting credentials. Long-term viability framing favors pasture-verified supply chain controllers and subscription platform operators with recurring revenue visibility across the analysis window. Watch EFSA novel food assessment timeline compression for MCT oil concentrates as inflection indicator for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pasture-Based Dairy | Captive supply of grass-fed butter from New Zealand or Ireland insulates margin against climate-driven feed price swings. |
| Subscription Platform Development | Recurring revenue models bypass retail margin stacking while capturing lifetime value from ketogenic protocol adherents. |
| Micro-Encapsulation Technology Adoption | Spray-dried lipid systems eliminate refrigeration requirements, unlocking vending machine placement in Seoul and Tokyo. |
| USDA Organic Certification Tiering | Dual-standard products enable price stratification separating conventional grass-fed from certified organic butter sources. |
| Functional Ingredient Convergence | Adaptogenic mushroom extracts and collagen peptides target beauty-from-within positioning in Asian wellness markets. |
Study Parameters
Multiple input streams — executive interviews with specialty café operators and wellness clinic procurement managers, trade data from customs records and dairy export statistics, and regulatory filings with FDA and EFSA — were reconciled through bottom-up volume modeling and top-down market sizing validation. Primary fieldwork engaged brand managers at premium wellness specialists, category buyers at natural grocery chains, supply planners at pasture-based dairy cooperatives, and technical R&D directors at beverage formulation houses. Secondary sources encompassed USDA organic certification databases, EFSA novel food assessment registers, SEC filings from multinational beverage conglomerates, and specialty coffee trade association production surveys.
Data-stream reconciliation across the projection horizon applied segment-level modeling across product type, ingredient source, distribution channel, and customer psychographic dimensions. CAGRs were derived from historical trajectory analysis adjusted for protocol adoption curves and regulatory approval timelines. Industry-specific forecast inputs incorporated ketogenic diet clinic expansion rates, specialty café channel buildout in coastal metropolitan markets, and EFSA novel food assessment pipeline velocity for MCT oil concentrates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal sourcing mandate enforcement intensity, grass-fed butter input cost volatility from climate-driven feed price swings, and plant-based substitute technology advancement. A small set of named triggers — EFSA novel food assessment timeline compression, micro-encapsulation technology cost curves, and wellness content creator algorithmic distribution shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
UK Coffee Roaster Market
Coffee
GCC Instant Coffee Market
Coffee
Coffee Premixes Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Flavored Cold-Brew Coffee Market
Coffee
US Coffee Roaster Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
North America Instant Coffee Market
Coffee
US Instant Coffee Market
Coffee
Africa Ready-To-Drink (RTD) Coffee Market
Coffee
Cold Brew Coffee Market
Coffee
RTD Coffee Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
India Ready-To-Drink (RTD) Coffee Market
Coffee
Vietnam Coffee Market
Coffee
Coffee Beans Market