
 Latin America Coffee Market | 2026-2036
Latin America Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Coffee Market Insights
EU Deforestation Regulation is repositioning export compliance costs for Latin American coffee producers, forcing upstream traceability investments across Brazilian and Colombian supply chains. Fazendas Pinhal leverages integrated estate milling to sustain margin control from cherry to export grade. Cenfrocafe anchors cooperative bargaining power across Peru's northern highlands, while Buencafe competes on soluble coffee scale from its Colombian base.
Latin America coffee comprises Coffea arabica and Coffea canephora (Robusta) species cultivated between 1,000 and 2,000 meters elevation, processed through washed, natural, or honey methods to yield green beans for roasting. The crop serves as a raw input for beverage manufacturing, retail brewing, and foodservice extraction across consumer and commercial channels. Arabica dominates value contribution across specialty and premium tiers, while instant processing commands volume throughput through industrial channels. Wet-processed lots concentrate margin pools in Colombia and Central America's high-altitude micro-climates, whereas dry-processed Brazilian naturals occupy commodity blending and mass-market roast applications.
ANVISA in Brazil and INVIMA in Colombia enforce pesticide residue limits and processing hygiene standards that shape export eligibility and domestic retail access. EUDR traceability mandates and USDA organic certification requirements filter which producers can supply premium European and North American buyers. Stakeholders must monitor how evolving deforestation-linked trade rules reshape origin documentation burdens and farm-gate compliance investments across the region.
Market Dynamics
EUDR traceability mandates are forcing upstream compliance investments across Brazilian and Colombian supply chains, reshaping farm-gate economics and export eligibility thresholds for specialty and commodity lots alike.
Growth Catalysts
- Specialty café expansion:Premium chains across São Paulo and Mexico City drive demand for traceable Arabica micro-lots, lifting value capture for wet-processed origins.
- EU Deforestation Regulation:Mandatory geolocation documentation for EU-bound shipments is accelerating digital farm mapping and blockchain verification adoption.
- Altitude-differentiated processing:Colombia's Zona Cafetera and Peru's northern highlands concentrate high-margin washed coffee production through cooperative infrastructure.
Market Restraints
- Input cost volatility:Fertilizer and labor costs in Brazil's Cerrado and Minas Gerais regions swing with currency fluctuations and global commodity cycles.
- Supply concentration risk:Brazil's dominance in global Arabica and Robusta output creates systemic exposure to frost and drought events in Paraná and São Paulo states.
- Regulatory friction:ANVISA pesticide residue limits and INVIMA processing hygiene standards impose divergent compliance burdens for exporters serving multiple destination markets.
Strategic Opportunities
- Underpenetrated Andean corridors:Ecuador and Bolivia's emerging high-altitude zones offer untapped acreage for specialty-grade expansion with lower land competition.
- Regulatory tailwind:USDA organic certification and Fairtrade premiums command shelf-space access in North American retail channels, rewarding early compliance investment.
- Technology convergence:Satellite-based yield monitoring combined with mobile payment platforms is integrating smallholder cooperatives into formal traceability systems.
Industry Challenges
- Agronomic skill gaps:Soil microbiome management and climate-adaptive varietal selection require technical extension capacity that outpaces current cooperative staffing.
- Certification timeline compression:EUDR's December 2024 implementation deadline forced rapid geolocation documentation without standardized interoperability protocols.
- Legacy wet mill infrastructure:Water-intensive processing equipment in Central America's volcanic highlands faces effluent discharge scrutiny under tightening watershed regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Coffee Market |
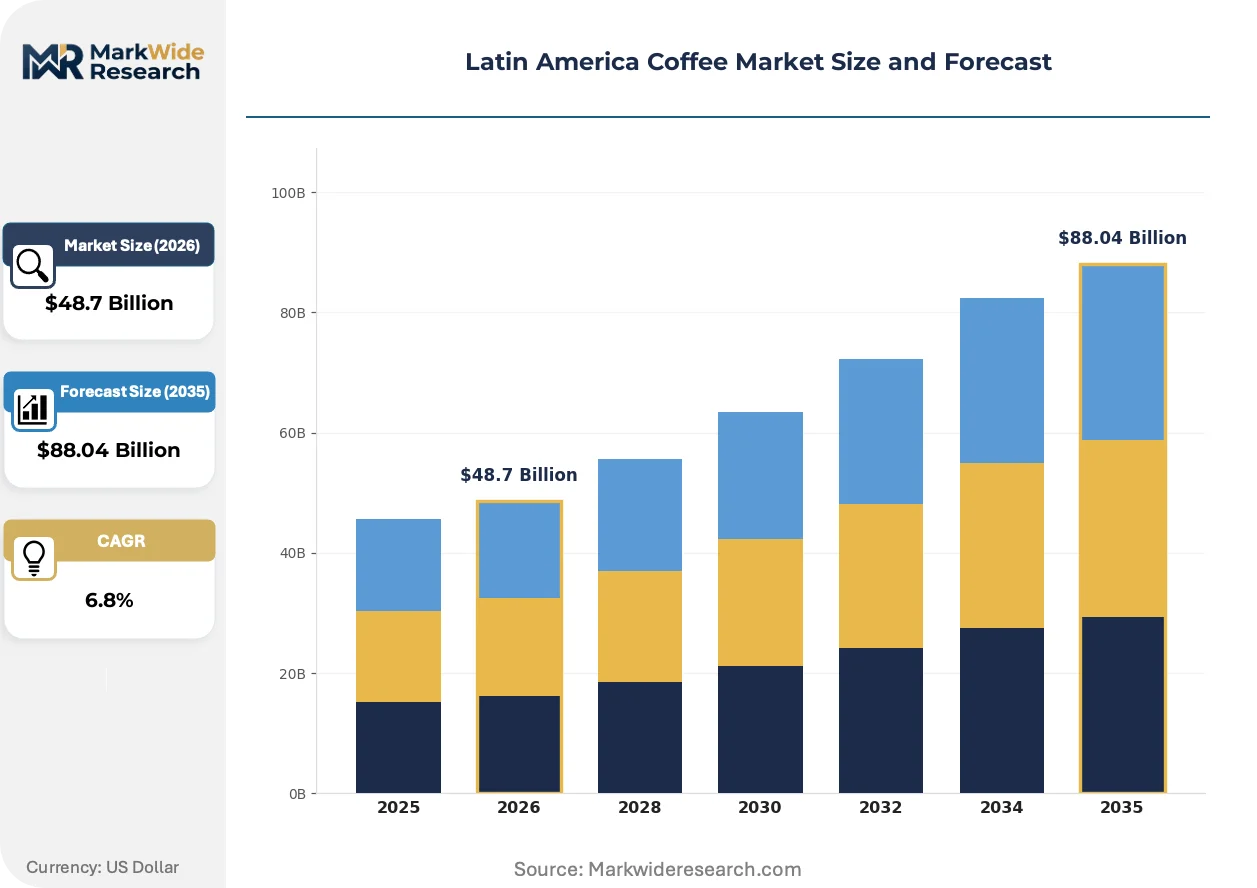
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Specialty, Instant End User: Retail Consumers, Cafés, Restaurants, Foodservice Distribution Channel: Supermarkets, Online Stores, Specialty Shops, Wholesalers Processing Method: Wet Process, Dry Process, Semi-Dry Process, Others |
| Companies Covered | Gento Coffee Roasters, Fazendas Pinhal, Buencafe, Cenfrocafe, Cafe Jesus Martin, Grupo Veloso, JACU COFFEE, Cenicafe, Coperaco Coffee, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Coffee Market Trends and Innovations
Digital traceability infrastructure and climate-adaptive agronomy are converging to reshape how Latin American coffee moves from farm gate to export terminal, compressing information asymmetries between producers and buyers.
Blockchain-enabled provenance tracking is integrating with cooperative management systems across Colombia and Peru, allowing estate and smallholder lots to carry immutable harvest-to-export records. Specialty roasters in North American and European markets are adopting these verification layers to satisfy EUDR and consumer transparency demands. The technology is compressing the premium gap between certified estate coffees and documented cooperative lots by equalizing information access.
EU Deforestation Regulation mandates are requiring geolocation polygons for every production plot supplying European buyers, forcing Brazilian fazendas and Colombian fincas to deploy GPS mapping and satellite monitoring. This regulatory friction is filtering out non-compliant smallholders from premium supply chains while accelerating consolidation around integrated estate operations with in-house compliance capacity. Colombian exporters serving EU markets are responding by embedding third-party verification into cooperative technical assistance programs.
Direct trade relationships are displacing traditional spot-market procurement for specialty-tier coffees, with roasters establishing multi-year contracts with specific farms or cooperatives. This channel shift concentrates volume commitments among relationship-driven buyers and reduces price volatility exposure for producers with documented quality consistency. The pattern is most visible in Colombia's Nariño and Huila departments, where micro-lot separation and cupping score transparency command fixed-price premiums above commodity differentials.
Latin America Coffee Market Segmentation
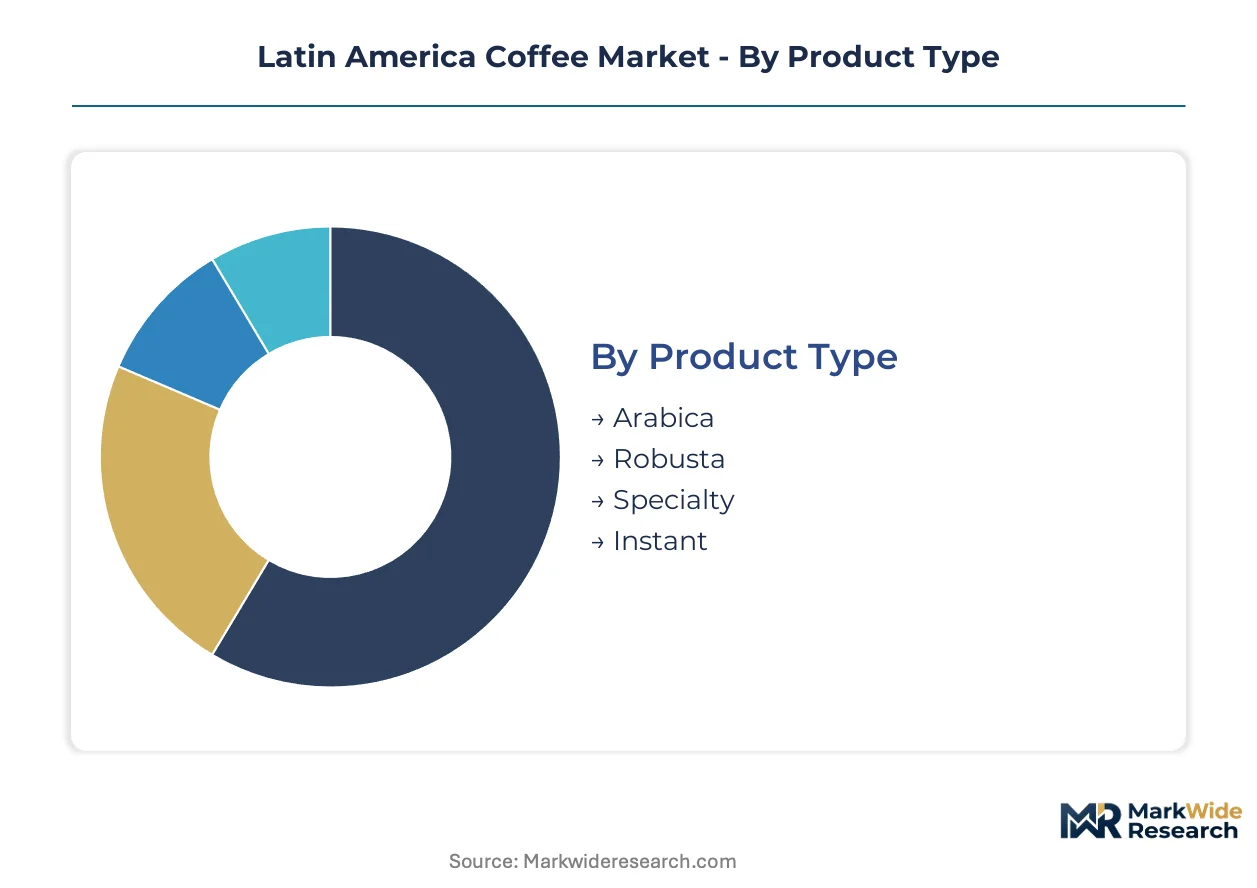
Segmentation in Latin American coffee reveals how capital deployment, regulatory exposure, and channel access concentrate margin capture across distinct production tiers. Producers and traders must align portfolio positioning with the specific compliance burdens and price formation mechanisms governing each category.
Product Type:
Capital intensity varies sharply across species and processing tiers, with wet-milled specialty lots demanding upstream infrastructure that commodity naturals bypass entirely.
- Arabica:High-altitude cultivation between 1,000 and 2,000 meters in Colombia's Zona Cafetera and Brazil's Minas Gerais delivers mild acidity and complex aromatics prized by specialty roasters. São Paulo café chains and Mexico City premium outlets concentrate demand for traceable micro-lots, though EUDR geolocation mandates now require GPS polygon documentation for EU-bound shipments.
- Robusta:Hardy Coffea canephora thrives at lower elevations with higher caffeine content and fuller body suited for espresso blends and soluble extraction. Brazil's Espírito Santo and Rondônia regions dominate regional output, with industrial processors in Campinas driving volume throughput for instant manufacturing.
- Specialty:Micro-lots scoring 80+ on SCAA cupping protocols command fixed-price premiums through direct trade relationships, concentrating margin pools in Colombia's Nariño and Huila departments where cooperative infrastructure enables lot separation.
- Instant:Spray-dried and freeze-dried soluble coffee from Colombian and Brazilian base material serves mass-market beverage manufacturing, with Buencafe's Manizales facility anchoring regional scale.
Arabica absorbs the bulk of installed capacity across Latin American origins; Specialty is expanding most quickly as traceability premiums reshape farm-gate economics.
End User:
Customer type determines packaging format, certification requirements, and price elasticity, with foodservice procurement operating on fundamentally different contract structures than retail shelf placement.
- Retail Consumers:Supermarket and online purchasers of whole bean and ground coffee drive demand for USDA organic and Fairtrade-certified SKUs, with North American retail channels rewarding early compliance investment with shelf-space access.
- Cafés:Premium chains across São Paulo and Mexico City source traceable Arabica micro-lots through multi-year direct trade contracts, displacing traditional spot-market procurement for specialty-tier volumes.
- Restaurants:Mid-tier foodservice operators prioritize consistent blending profiles and soluble options for back-of-house efficiency, with Brazilian naturals dominating commodity roast applications.
- Foodservice:Industrial extraction and vending channels command volume throughput through robusta-heavy blends and instant coffee concentrate, with ANVISA and INVIMA hygiene standards shaping export eligibility.
Retail Consumers anchor volume absorption through supermarket and online channels; Cafés are climbing the fastest as premium chain expansion accelerates specialty Arabica procurement.
Distribution Channel:
Channel selection dictates margin retention, with integrated estate operations capturing value that cooperative-dependent smallholders cede to intermediary layers.
- Supermarkets:Mass retail placement in Brazil's GPA and Mexico's Chedraui networks requires scale certification and promotional slotting fees, favoring established exporters with compliance documentation.
- Online Stores:Direct-to-consumer subscription models and marketplace platforms enable micro-lot access for North American and European specialty buyers, compressing information asymmetries through blockchain-enabled provenance tracking.
- Specialty Shops:Curated retail in Bogotá's Zona G and Lima's Miraflores district concentrates demand for single-origin offerings with cupping score transparency and harvest lot documentation.
- Wholesalers:Traditional export houses and trading companies aggregate volumes for commodity blending and industrial processing, with Santos and Buenaventura port infrastructure shaping logistics economics.
Wholesalers retain the deepest volume footprint; Online Stores are gaining share fastest as digital traceability infrastructure enables direct producer-buyer relationships.
Processing Method:
Water access, energy costs, and effluent regulations differentiate processing economics across Latin America's varied topography and watershed governance.
- Wet Process:Fully washed coffee with mucilage removal through fermentation and washing delivers clean cup profiles prized in specialty markets. Colombia's Zona Cafetera and Peru's northern highlands concentrate this capital-intensive infrastructure, though tightening watershed regulations in Central America's volcanic highlands now scrutinize water discharge.
- Dry Process:Natural sun-drying of whole cherry without water immersion produces fruit-forward, heavier-bodied profiles dominant in Brazil's Cerrado and Minas Gerais, where abundant sunlight and flat terrain enable mechanical harvesting and patio drying at scale.
- Semi-Dry Process:Honey and pulped natural methods remove skin while retaining partial mucilage, splitting water usage and cup characteristics between washed and natural extremes, with Costa Rica's Central Valley pioneering mechanical demucilaging to reduce fermentation water.
- Others:Experimental anaerobic fermentation, carbonic maceration, and thermal shock protocols occupy niche specialty tiers, with Colombian innovators in Quindío and Risaralda testing controlled-environment processing for distinct flavor differentiation.
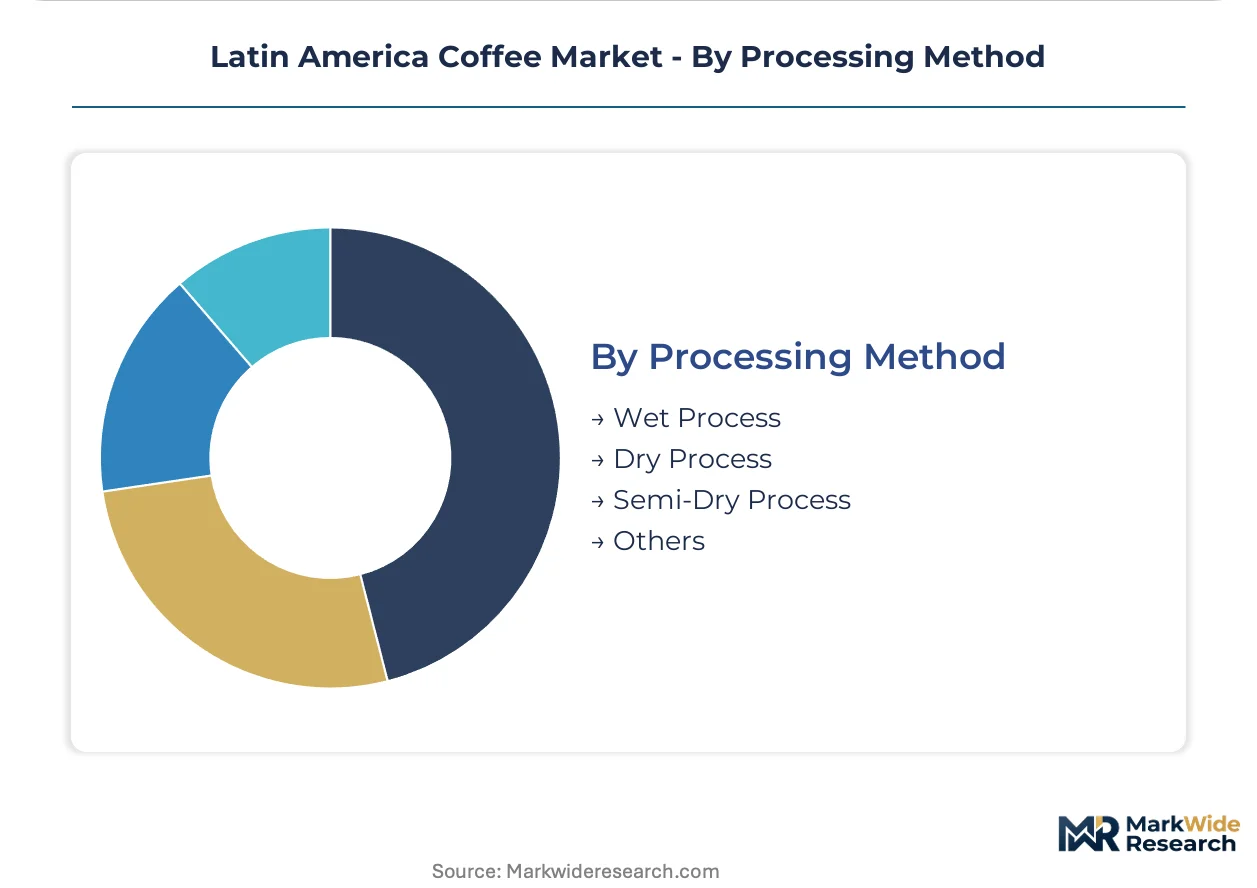
Dry Process commands the greatest installed capacity across Brazilian origins; Wet Process is expanding most quickly as altitude-differentiated micro-lots capture specialty premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium café chains in São Paulo and Mexico City concentrate demand for traceable Arabica micro-lots, while EUDR compliance investments reshape farm-gate economics across Brazilian and Colombian supply chains.
Brazil
São Paulo's specialty roasting clusters and Rio de Janeiro's premium foodservice channels drive demand for high-grade naturals and pulped naturals. ANVISA enforces pesticide residue limits that filter export eligibility for European and North American buyers. Minas Gerais and Espírito Santo concentrate mechanized harvesting and estate-scale processing infrastructure.
Colombia
Bogotá's Zona G specialty retailers and Medellín's third-wave café expansion anchor domestic premium consumption. INVIMA processing hygiene standards shape export documentation burdens for cooperative and estate operations alike. The Zona Cafetera spanning Caldas, Quindío, and Risaralda concentrates wet-milled micro-lot production with cooperative technical assistance backing traceability compliance.
Mexico
Mexico City Metro's premium chain proliferation and Guadalajara's emerging specialty roasting sector pull traceable Arabica from Chiapas and Oaxaca highlands. The Secretariat of Agriculture and Rural Development (SADER) supports organic certification programs that unlock USDA-compliant export channels. Veracruz and Puebla states concentrate altitude-differentiated production with cooperative infrastructure enabling lot separation.
Peru
Lima's Miraflores specialty retail district and Arequipa's emerging café culture concentrate domestic premium demand for high-altitude washed coffees. The National Coffee Board (JNC) coordinates cooperative technical assistance that supports EU organic and Fairtrade certification compliance. Cajamarca and Amazonas departments in the northern highlands anchor Cenfrocafe's cooperative bargaining power and micro-lot export capacity.
Costa Rica
San José's specialty roasting clusters and Central Valley café chains drive demand for honey-processed and experimental fermentation lots. The National Coffee Institute (ICAFE) regulates processing effluent standards that shape wet mill infrastructure investment. Tarrazú and West Valley regions concentrate smallholder cooperative production with mechanical demucilaging reducing water usage.
Latin America Coffee Market Competitive Landscape
Brazilian estate operations anchor one tier; Colombian cooperative specialists and Peruvian highland aggregators hold differentiated positions in traceable micro-lot channels. Market structure fragments across integrated fazendas with in-house milling capacity, cooperative federations pooling smallholder volumes, and soluble-focused industrial processors competing on throughput scale. Three archetypes dominate: estate operators controlling cherry-to-export verticality, cooperative alliances aggregating certified smallholder output, and industrial-scale instant manufacturers. Competitive moves concentrate on EUDR compliance infrastructure deployment and direct trade relationship cultivation with North American and European specialty roasters.
Within the estate-operator tier, Fazendas Pinhal exemplifies integrated production with captive milling capacity. Among cooperative specialists, Cenfrocafe occupies a position aggregating Peruvian highland smallholder output for premium export channels. At the industrial-scale end, Buencafe anchors soluble coffee manufacturing from its Colombian base. These three represent distinct strategic archetypes: vertical control, cooperative aggregation, and mass-market processing scale.
| Leading Market Players |
|---|
| Gento Coffee Roasters |
| Fazendas Pinhal |
| Buencafe |
| Cenfrocafe |
| Cafe Jesus Martin |
| Grupo Veloso |
| JACU COFFEE |
| Cenicafe |
| Coperaco Coffee |
| Others |
Pricing and Supply Chain Analysis
Fertilizer and labor costs in Brazil's Cerrado and Minas Gerais regions swing with currency fluctuations and global commodity cycles, transmitting upstream volatility through wet-processed micro-lots to specialty roasters and dry-processed naturals to mass-market blenders. This input-cost architecture stratifies pricing power across estate operators with captive milling capacity and cooperative-dependent smallholders exposed to intermediary margin capture.
Pricing Analysis
Short lead-time premiums for traceable micro-lots command fixed-price differentials above commodity spot markets, while spot inventory discounts concentrate among undifferentiated Brazilian naturals sold through Santos export houses. Three-tier pricing structure across specialty, premium, and commodity levels separates EUDR-compliant documented lots from conventional export grades. Pricing pressure stems from EUDR geolocation compliance investments compressing farm-gate margins. Specialty roasters in North American channels exhibit lowest price sensitivity; foodservice operators sourcing soluble concentrates show highest elasticity.
Supply Chain Analysis
Seasonal labor availability in Colombia's Zona Cafetera and Peru's northern highlands constrains harvest throughput during peak cherry maturation windows. Supply concentrates in Brazil, Colombia, and Peru, with Brazilian estates anchoring volume output and Andean cooperatives controlling specialty-grade micro-lot flows. The chain draws from agrochemical inputs, fermentation infrastructure, and ocean freight capacity. Single-source vulnerability runs through Brazil's dominance in global Arabica output exposed to frost events. Distribution runs through integrated estate direct trade, cooperative export aggregation, and multinational trading house spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EUDR traceability capacity bottlenecks prop specialty-grade pricing by filtering non-compliant smallholders from premium European channels, concentrating volume among estates and certified cooperatives with documented geolocation infrastructure.
For Market Incumbents: Extend backward integration into captive wet-milling capacity to sustain margin control from cherry to export grade. Consolidate around EUDR-compliant estate operations in Minas Gerais and Zona Cafetera to defend against cooperative-led micro-lot competition. Prioritize blockchain-enabled provenance tracking as a channel-control lever for direct trade relationships with North American specialty roasters. For New Entrants and Emerging Players: Begin with underpenetrated high-altitude corridors in Ecuador and Bolivia's emerging specialty zones where land competition remains below Colombian and Peruvian levels. Target USDA organic certification pathways for North American retail shelf-space access. Deploy mobile payment platforms integrated with satellite yield monitoring as a go-to-market angle for cooperative technical assistance partnerships. For Investors and Strategic Acquirers: EUDR implementation deadline compliance rates across Peruvian and Colombian cooperatives are the leading indicator that traceability-capable aggregation assets will command acquisition premiums. Long-term viability over the next decade rests on climate-adaptive varietal portfolios and watershed-resilient processing infrastructure. Target acquisition archetype: vertically integrated mid-cap estates with in-house milling and established direct trade roaster relationships. Watch satellite-based farm polygon completion rates as the inflection signal for supply-chain consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Compliance Infrastructure Deployment | Geolocation polygon documentation unlocks European premium channel access for Colombian and Brazilian estates. |
| Direct Trade Relationship Cultivation | Multi-year fixed-price contracts with North American roasters reduce price volatility exposure for Nariño micro-lot producers. |
| Cooperative Technical Assistance Expansion | Cenfrocafe-style aggregation models extend traceability capacity to Peruvian smallholders without estate-scale capital. |
| Climate-Adaptive Varietal R&D Investment | Cenicafe's breeding programs address frost and drought exposure threatening Brazil's Paraná and São Paulo output concentration. |
| Soluble Manufacturing Scale-Up | Buencafe's freeze-dried capacity anchors industrial-channel volume throughput from Colombian base material. |
Research Methodology
Trade statistics from Brazil's Ministry of Economy, Colombia's National Administrative Department of Statistics, and Peru's National Institute of Statistics and Informatics formed the secondary backbone for volume and value estimation across the analysis window. Primary interviews with cooperative technical directors, estate operations managers, export house procurement leads, and specialty roaster green buyers combined with secondary validation through customs records and agricultural ministry filings. Bottom-up and top-down triangulation anchored segmentation outputs.
Bottom-up modeling built country-level production estimates from department-level yield data and harvested area surveys, while top-down cross-checks validated against aggregate export volumes reported through ICO and national customs databases. Segmentation dimensions spanned species, processing method, end-user channel, and altitude-differentiated quality tier. CAGRs derived from trend extrapolation of historical trade flows adjusted for EUDR implementation effects. Forecast inputs included cooperative infrastructure investment pipelines and estate expansion announcements in Minas Gerais and Espírito Santo.
Underlying measurement precision varies by segment; wet-processed specialty micro-lots with documented cupping scores carry tighter precision than undifferentiated commodity naturals sold through spot markets. Forecasts reflect assumptions around EUDR compliance adoption curves and climate event frequency. Material deviation in frost severity across Brazil's southern states or watershed regulation tightening in Central America's volcanic highlands warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Beans Market
Coffee
United Arab Emirates Coffee Roaster Market
Coffee
Encapsulated Caffeine Market
Coffee
Italy Coffee Market
Coffee
Organic Coffee Market
Coffee
Thailand Coffee and Tea Capsules Market
Coffee
Reusable Coffee Cup Market
Coffee
Coffee Brewers Market
Coffee
Asia-Pacific Ready to Drink (RTD) Coffee Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Robusta Coffee Beans Market
Coffee
High Protein Coffee Market
Coffee
Roast to Order Coffee Market
Coffee
Coffee Syrup Market
Coffee
GCC Instant Coffee Market
Coffee
Global Nespresso Capsules Market