
 Smart Coffee Maker Market | 2026-2036
Smart Coffee Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Coffee Maker Market Analytics
CE marking under the EU Low Voltage Directive is collapsing the field of import-ready smart coffee equipment, forcing smaller overseas manufacturers to retest entire product lines. De'Longhi Group leverages its Italian manufacturing base to sustain dual certification for North American and European voltage standards. JURA Elektroapparate AG anchors premium positioning through proprietary brewing algorithms and Swiss engineering credentials. Koninklijke Philips N.V. competes on kitchen ecosystem integration, extending its connected appliance platform into automated morning routines.
A smart coffee maker combines embedded microcontrollers, wireless communication modules, and precision heating elements to enable remote activation, brew customization, and maintenance alerts through smartphone or voice interfaces; typical units operate at 120-240V with PID temperature control maintaining ±1°C accuracy for optimal extraction. Wi-Fi Enabled models dominate residential volume due to whole-home integration with existing smart hubs, while Voice-Activated configurations represent the fastest-expanding feature tier as natural language processing improves in multilingual kitchens. The Office end-user segment commands higher per-unit pricing through enterprise fleet management software and centralized bean-to-cup servicing contracts.
FCC Part 15 governs radio frequency emissions for Wi-Fi and Bluetooth modules in US-market units, while the EU Radio Equipment Directive mandates harmonized spectrum use and interoperability testing across member states. REACH compliance restricts certain plastics and electronic component chemistries in European-bound products, adding material substitution costs for manufacturers. Stakeholders must monitor evolving cybersecurity labeling requirements as connected kitchen appliances face escalating scrutiny over data privacy and botnet vulnerability exposure.
Market Dynamics
The EU Ecodesign Directive is compressing the field of import-ready smart coffee equipment by forcing wholesale retesting of voltage and thermal efficiency standards, privileging manufacturers with existing European certification infrastructure.
Growth Catalysts
- Hospitality fleet digitization:Boutique hotel chains are expanding procurement of connected brewing equipment with remote diagnostics capabilities to reduce in-room service calls.
- REACH material compliance:Restrictions on certain plastics and electronic component chemistries in European-bound products are accelerating substitution toward certified supply chains.
- Voice interface adoption:Natural language processing improvements in multilingual kitchens are pulling demand toward voice-activated configurations as the fastest-expanding feature tier.
Market Restraints
- Dual certification burden:Smaller overseas manufacturers face retesting entire product lines for CE marking under the EU Low Voltage Directive, raising fixed cost barriers to European market entry.
- Precision component concentration:PID temperature control modules maintaining ±1°C accuracy rely on specialized sensor suppliers concentrated in East Asian manufacturing clusters.
- Cybersecurity exposure:Connected kitchen appliances face escalating scrutiny over data privacy and botnet vulnerability exposure, with emerging labeling requirements threatening non-compliant inventory.
Strategic Opportunities
- Enterprise fleet software:The Office end-user segment offers higher per-unit pricing through centralized bean-to-cup servicing contracts and remote maintenance platforms.
- IoT ecosystem convergence:Whole-home integration with existing smart hubs creates white space for Wi-Fi enabled models to anchor automated morning routines.
- Swiss engineering positioning:Proprietary brewing algorithms and precision manufacturing credentials enable premium pricing in quality-sensitive segments.
Industry Challenges
- Radio frequency harmonization:FCC Part 15 emissions standards for US-market units diverge from EU Radio Equipment Directive interoperability testing, forcing parallel certification tracks.
- Embedded systems integration:Combining microcontrollers, wireless modules, and heating elements across 120-240V operating ranges requires specialized firmware talent scarce outside established appliance hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Coffee Maker Market |
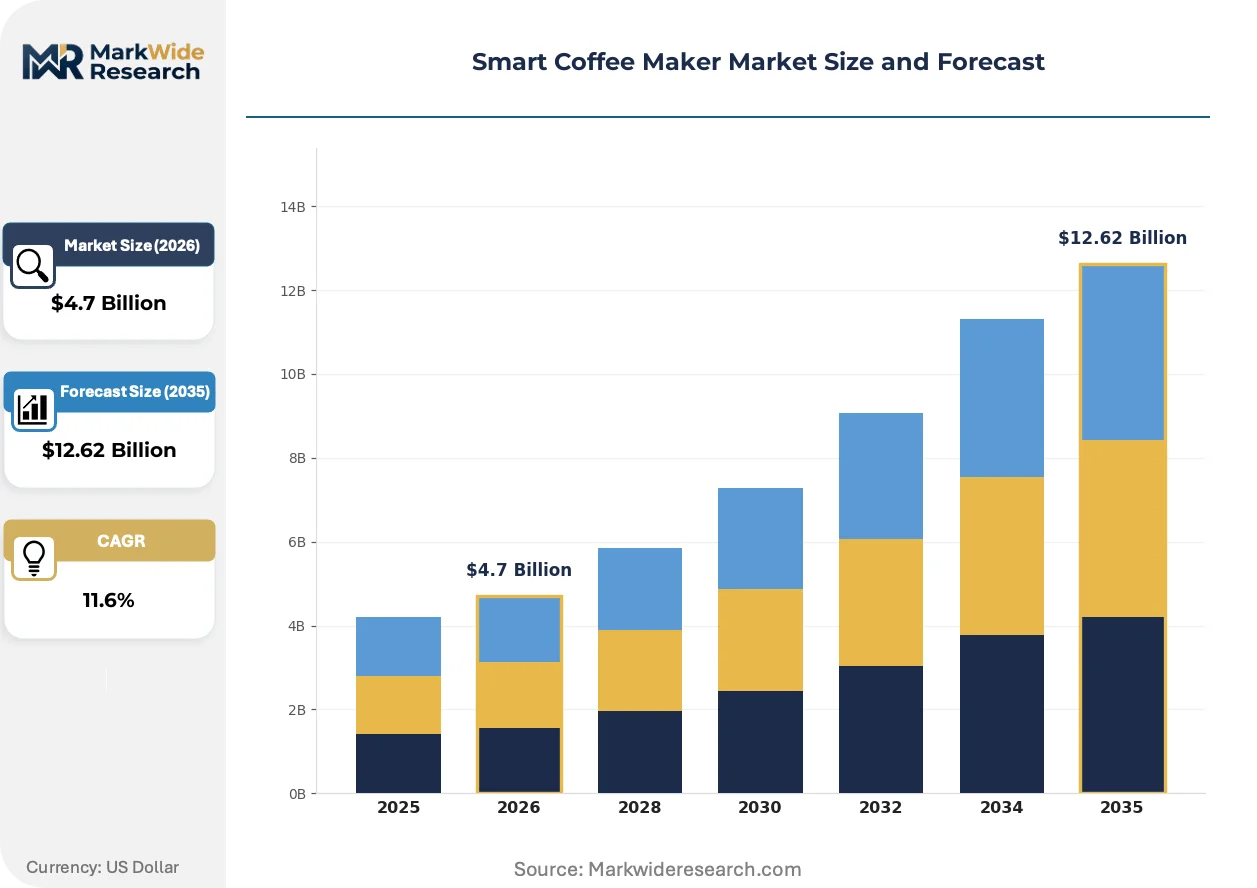
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Enabled, Bluetooth Connected, App-Controlled, Voice-Activated Feature: Auto Brew, Programmable Timer, Self-Cleaning, Custom Brew Strength End User: Home Users, Offices, Cafés, Restaurants Installation: Countertop, Built-in, Portable, Integrated |
| Companies Covered | Nestlé, De'Longhi Group, Hamilton Beach Brands, JURA Elektroapparate AG, Koninklijke Philips N.V., Keurig Green Mountain, Behmor, Inc., Breville Group, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Coffee Maker Market Evolving Landscape
Wireless communication hardware is compressing form factors and power budgets across residential and commercial product lines, enabling new placement configurations and installation economics.
Precision heating element technology is miniaturizing. Ceramic and thin-film resistor arrays now deliver PID-controlled thermal profiles in footprint-constrained countertop units. Boutique hospitality operators are adopting these compact systems for in-room installations where space premiums dominate. The technology is miniaturizing equipment depth requirements, allowing penetration of European galley kitchens and Japanese micro-apartments previously inaccessible to full-featured systems.
EU cybersecurity labeling requirements for connected appliances are tightening disclosure obligations. Manufacturers must document data handling practices and vulnerability patching protocols before market authorization. Premium residential segments in Germany and Scandinavia are responding fastest, with procurement specifications now requiring third-party security attestations alongside energy efficiency ratings.
Enterprise buyers are consolidating vendor relationships around integrated service platforms. Hotel chains and office foodservice operators are replacing transactional equipment purchases with multi-year contracts bundling hardware, consumables, and predictive maintenance. This pattern is most visible in German commercial foodservice, where operators prioritize IoT-enabled equipment with remote diagnostics to minimize downtime penalties in high-traffic locations.
Smart Coffee Maker Market Segmentation
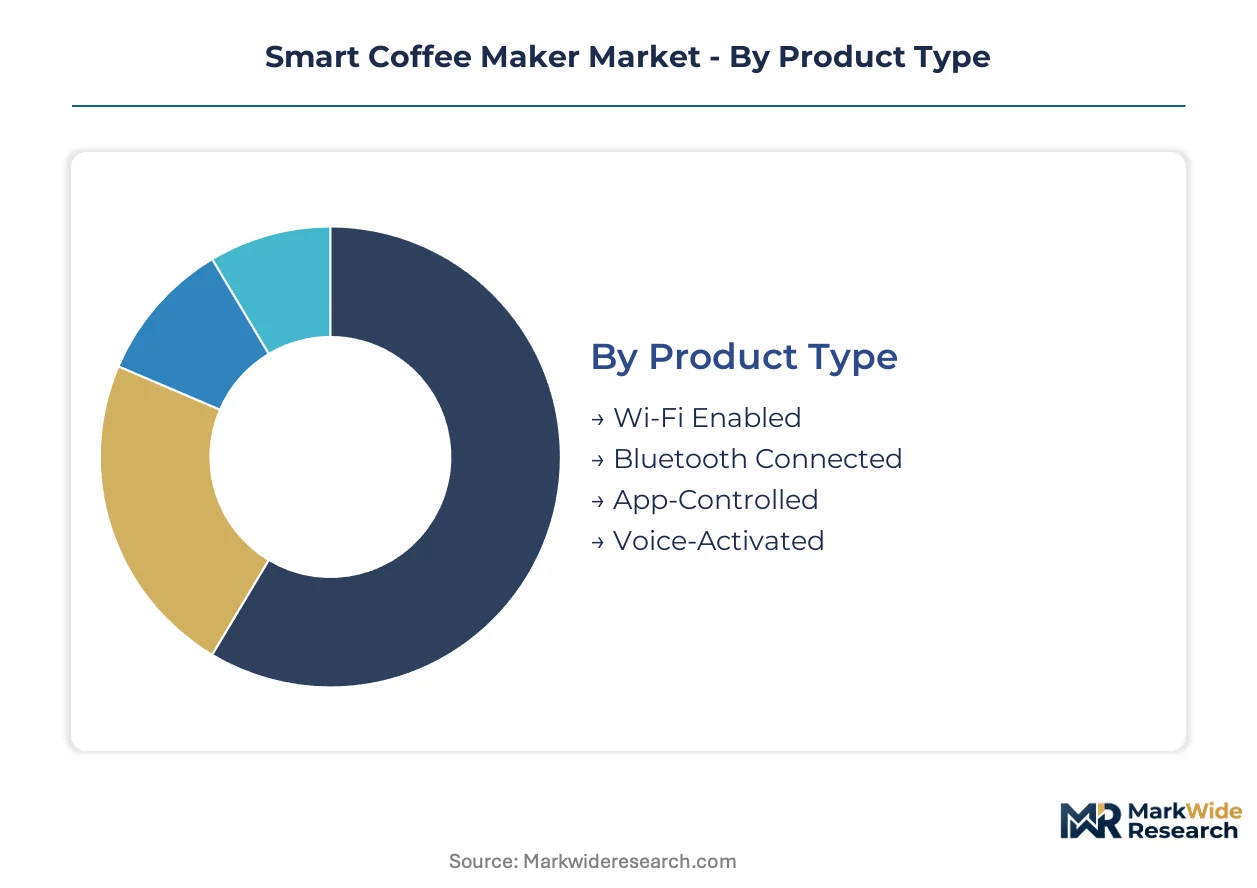
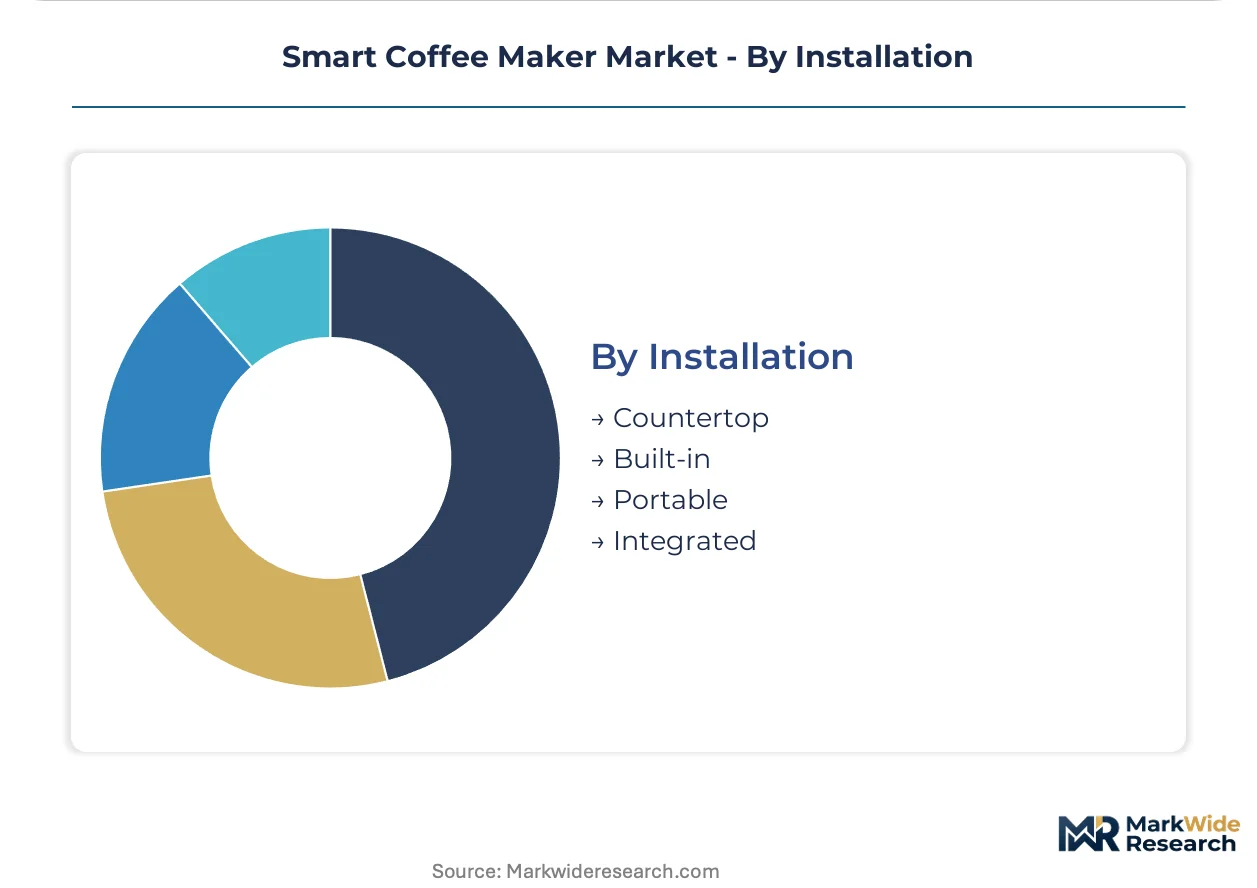
Segmentation in the Smart Coffee Maker Market reveals how connectivity interfaces, automation features, and installation constraints reshape procurement economics across residential and commercial environments. Margin pools concentrate where precision heating converges with enterprise fleet management capabilities.
Product Type:
Margin pools sit heaviest where wireless modules enable recurring software revenue and predictive maintenance contracts.
- Wi-Fi Enabled:Units integrate with whole-home automation hubs through 2.4GHz/5GHz protocols, supporting remote activation and firmware updates. Demand concentrates in German residential markets where consumers prioritize interoperability with existing IoT ecosystems and energy monitoring dashboards.
- Voice-Activated:Natural language processing modules enable hands-free brewing through Alexa, Google Assistant, or Siri integration. Scandinavian markets are rotating fastest toward this configuration as multilingual voice recognition accuracy improves in compact kitchen environments.
- Bluetooth Connected:Short-range pairing suits countertop units in space-constrained installations without router dependency.
- App-Controlled:Dedicated smartphone interfaces deliver granular brew customization through proprietary software layers.
Wi-Fi Enabled holds installed capacity. Voice-Activated is rotating up the share rankings.
Feature:
Cost tier stratification runs deepest where automation reduces manual intervention and consumable waste.
- Auto Brew:Sensors detect carafe presence and water level to trigger brewing sequences without user input. German boutique hotels are specifying this capability to reduce in-room service calls and standardize guest experience across properties.
- Self-Cleaning:Automated descaling cycles and flush routines minimize calcium buildup in hard-water regions. Mediterranean markets with high mineral content municipal supplies are prioritizing this feature to extend equipment lifespan.
- Programmable Timer:Clock-based scheduling aligns brewing with occupancy patterns in office environments.
- Custom Brew Strength:Variable extraction parameters adjust grind contact time and water temperature for individual preference profiles.
Auto Brew commands premium pricing in commercial specifications. Self-Cleaning is climbing the fastest in residential replacement cycles.
End User:
Application-specific requirements fragment procurement standards across consumption contexts.
- Offices:Enterprise fleet management software enables centralized bean-to-cup servicing, remote diagnostics, and usage-based consumable replenishment. German commercial foodservice operators prioritize IoT-enabled equipment with predictive maintenance to minimize downtime penalties in high-traffic locations.
- Home Users:Residential purchasers prioritize countertop form factors, voice integration, and energy efficiency labeling under EU Ecodesign Directive standards. Scandinavian markets require third-party cybersecurity attestations alongside efficiency ratings.
- Cafés:High-throughput environments demand commercial-grade heating elements and multi-user app access.
- Restaurants:Front-of-house and back-of-house installations require divergent capacity specifications and aesthetic constraints.
Offices concentrate annual contract value. Home Users dominate unit volume.
Installation:
Physical integration constraints determine supply chain configuration and service economics.
- Countertop:Freestanding units with 120-240V flexibility and minimal plumbing requirements suit rental properties and temporary installations. Japanese micro-apartments and European galley kitchens are adopting compact ceramic heating arrays that reduce equipment depth requirements.
- Built-in:Cabinet-integrated systems require coordinated kitchen design and dedicated electrical circuits. German residential renovation markets specify these configurations to maximize usable counter space in premium developments.
- Portable:Battery-powered or vehicle-adapted units target mobile foodservice and recreational vehicle applications.
- Integrated:Whole-kitchen ecosystem modules bundle coffee brewing with refrigeration, water filtration, and waste management in luxury residential specifications.
Countertop holds distribution density. Built-in is gaining share fastest in renovation-driven markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's role as the primary distribution hub for connected kitchen appliances entering European markets, with dedicated cold-chain and electronics handling facilities supporting just-in-time replenishment for commercial foodservice operators.
Germany
Boutique hotel chains and commercial foodservice operators drive procurement of IoT-enabled brewing equipment with remote diagnostics capabilities. The EU Ecodesign Directive tightens minimum energy performance standards for networked kitchen appliances, forcing retesting of voltage and thermal efficiency specifications. Manufacturing concentration clusters in North Rhine-Westphalia, where industrial automation suppliers serve precision heating element producers.
United States
Enterprise office foodservice contracts and residential smart home integration fuel demand for Wi-Fi enabled and voice-activated configurations. FCC Part 15 governs radio frequency emissions for Wi-Fi and Bluetooth modules, requiring emissions testing distinct from European protocols. Seattle's technology corridor anchors firmware development talent for embedded microcontroller integration across 120-240V operating ranges.
Japan
Micro-apartment living and space-constrained urban kitchens accelerate adoption of compact ceramic heating arrays with reduced equipment depth. METI efficiency standards and JIS certification requirements shape product development timelines for domestic market entry. Osaka's precision manufacturing belt concentrates suppliers of PID temperature control modules maintaining extraction accuracy.
Switzerland
Premium residential segments prioritize proprietary brewing algorithms and engineering credentials in quality-sensitive procurement decisions. Swissmedic and federal cybersecurity frameworks influence disclosure obligations for connected appliance data handling practices. The Zurich-Geneva corridor hosts precision engineering firms supplying specialized sensor components for temperature control systems.
United Kingdom
Post-renovation residential markets specify built-in cabinet-integrated systems to maximize usable counter space in premium developments. UKCA marking requirements and divergent radio equipment standards from EU protocols create parallel certification obligations for importers. London's design and specification community influences procurement patterns across Northern European markets.
Smart Coffee Maker Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and embedded systems integration capabilities. The vendor base stratifies into three tiers: multinational appliance conglomerates with dual-continent certification capacity, mid-scale specialists leveraging regional manufacturing proximity, and component-integrated assemblers dependent on outsourced firmware. Dominant competitive moves include vertical integration into precision heating element supply and strategic partnerships with smart home platform operators.
Within the premium engineering tier, JURA Elektroapparate AG and De'Longhi Group exemplify positioning through manufacturing base advantages and dual certification capacity for North American and European voltage standards. Koninklijke Philips N.V. occupies a position emphasizing kitchen ecosystem integration and connected appliance platform extension. These three entities represent distinct archetypes: Swiss precision engineering credentials, Italian manufacturing-based certification flexibility, and Dutch ecosystem convergence strategy.
| Leading Market Players |
|---|
| Nestlé |
| De'Longhi Group |
| Hamilton Beach Brands |
| JURA Elektroapparate AG |
| Koninklijke Philips N.V. |
| Keurig Green Mountain |
| Behmor, Inc. |
| Breville Group |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for PID temperature control modules concentrate purchasing leverage among German and Japanese appliance assemblers, compressing margin capture for smaller competitors while amplifying volume-discount power for consolidated hospitality procurement consortia.
Pricing Analysis
Volume-discount tiering structures dominate enterprise fleet contracts, with three-tier pricing separating premium Swiss-engineered units with proprietary brewing algorithms from standard CE-certified European models and economy-tier Asian imports. Price differentiation rests on certification grade and after-sales service bundling, as German commercial operators prioritize IoT-enabled predictive maintenance packages. Cost compression in the economy tier intensifies because REACH compliance mandates accelerate material substitution expenses. Boutique hotel chains exhibit lowest price sensitivity, while independent café operators face acute margin pressure.
Supply Chain Analysis
China and Taiwan anchor microcontroller and wireless module fabrication, while Switzerland and Germany concentrate precision sensor production for PID temperature control systems. Raw material dependencies span ceramic heating substrates, rare-earth magnets for pump motors, and certified food-grade plastics. Single-source vulnerability concentrates in East Asian semiconductor packaging facilities. Distribution runs through Hamburg's container terminals for European markets and Seattle-Tacoma for North American enterprise channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boutique hotel chain consolidation into three dominant procurement consortia is shifting buyer power toward centralized fleet-management vendors, fragmenting price-setting autonomy for equipment suppliers.
For Market Incumbents: Compound certification infrastructure advantages by accelerating dual CE-FCC testing capacity ahead of smaller competitors facing EU Ecodesign Directive retesting burdens. Prioritize backward integration into ceramic heating element supply to defend margin position against substitute technologies from compact resistor array specialists. Channel control through exclusive service contracts with German commercial foodservice operators remains critical. For New Entrants and Emerging Players: Predictive maintenance software gaps in mid-market office segments present white-space entry points where incumbents under-serve price-conscious buyers. Scandinavian residential markets with cybersecurity attestation requirements offer the most penetrable geography due to fragmented local supplier presence. A direct-to-facility sales model bypassing traditional distribution layers enables competitive service bundling. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because enterprise fleet contracts are displacing transactional equipment sales with multi-year hardware-software-consumable bundles. Acquisition targets should display captive firmware development capabilities and existing smart home platform integrations. Watch for EU cybersecurity labeling mandate enforcement as the inflection signal indicating regulatory-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Platform Integration | Philips' ecosystem convergence strategy demonstrates how kitchen appliance anchoring captures automated morning routine spend. |
| Predictive Maintenance Software Launch | German foodservice operators prioritize IoT-enabled remote diagnostics to minimize downtime penalties in high-traffic locations. |
| Ceramic Heating Technology Licensing | Compact resistor arrays enable penetration of Japanese micro-apartments previously inaccessible to full-featured systems. |
| Dual Certification Infrastructure Expansion | De'Longhi's Italian manufacturing base sustains parallel CE-FCC testing capacity that smaller overseas competitors cannot replicate. |
| Enterprise Fleet Management Partnership | Centralized bean-to-cup servicing contracts command higher annual contract value than transactional residential sales. |
Research Methodology
A standing panel of connected appliance product managers, commercial foodservice procurement directors, smart home platform engineers, and precision heating element suppliers provided ongoing calibration throughout the study. Primary interviews with hospitality fleet operators and embedded systems firmware developers combined with secondary validation against FCC equipment authorization databases, EU Ecodesign Directive compliance registries, and customs trade records. Bottom-up unit shipment estimates triangulated against top-down value projections across connectivity interface, automation feature, and installation configuration segments.
Consistency checks validated volume and value outputs against external benchmarks from appliance industry associations and semiconductor shipment disclosures. The analytical framework modeled product type, end-user application, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth rate synthesis incorporating hospitality digitization spending patterns and voice interface adoption curves. Forecast inputs included EU cybersecurity labeling implementation timelines and REACH material restriction phase-in schedules.
Forecasts assume regulatory continuity in EU Ecodesign and REACH regimes, US FCC Part 15 emissions standards, and Japanese METI efficiency frameworks; material policy shifts would require re-modeling. Supply chain disruption from semiconductor packaging concentration, tariff exposure on Chinese wireless modules, or abrupt cybersecurity attestation mandates could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
United States Coffee Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Espresso Tamper Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Brazil Ready-To-Drink (RTD) Coffee Market
Coffee
Germany Coffee Market
Coffee
Coffee Decoction Maker Market
Coffee
United States Ready-To-Drink (RTD) Coffee Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Ground Coffee Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Espresso Powder Market
Coffee
Cafix Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Green Coffee Bean Extract Market
Coffee
United Arab Emirates Coffee Roaster Market