
 China Coffee Market | 2026-2036
China Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
China Coffee Market Analysis
Specialty-grade espresso automation is fragmenting traditional café operations across China's tier-one cities. Luckin Coffee Inc. leverages its proprietary app-based ordering infrastructure to dominate urban delivery corridors. Starbucks Corporation anchors its position through reserve roastery concepts in Shanghai and Beijing. Manner Coffee competes via compact kiosk formats that minimize real estate overhead while sustaining high throughput volumes.
Coffee comprises roasted seeds of Coffea arabica and Coffea canephora, processed through wet or dry methods to achieve specified moisture content below 12% and green bean defect thresholds; its primary commercial purpose is extraction into beverages delivering standardized caffeine doses for alertness and social consumption. Instant coffee occupies the largest volume share among product types, though premium whole bean segments capture disproportionate margin pools through specialty roasting and direct-trade sourcing narratives. Online retail channels now lead growth velocity, as live-stream commerce and subscription models reshape how individual consumers replenish household coffee inventories.
SAMR enforces national food safety standards for roasted coffee and pre-packaged beverages, while NMPA oversees health claims and additive permissions that constrain functional coffee product development. GB standards for contaminant limits and labeling requirements directly shape import clearance protocols and domestic manufacturing compliance costs. Stakeholders must monitor how evolving dual carbon goals and packaging waste regulations will alter roasting energy profiles and single-serve format viability across China's provincial markets.
Market Dynamics
Specialty espresso automation is fragmenting traditional café operations across China's tier-one cities, compressing labor costs while accelerating throughput. NMPA food safety protocols and evolving GB standards for packaged beverages simultaneously reshape product formulation requirements and import clearance protocols.
Growth Catalysts
- Urban White-Collar Demand:China's tier-one cities host concentrated professional populations driving premium café consumption. Shanghai, Beijing, and Shenzhen anchor this demand through dense commercial districts and mature delivery infrastructure.
- GB Standards Modernization:Updated national standards for roasted coffee and pre-packaged beverages clarify compliance pathways. SAMR enforcement creates predictable regulatory terrain for domestic and imported products alike.
- Live-Stream Commerce:Digital retail channels accelerate household coffee replenishment cycles. Subscription models and influencer-driven discovery reshape how consumers encounter specialty roasting narratives.
Market Restraints
- Green Bean Import Dependency:China sources the majority of raw coffee from Vietnam, Brazil, and Colombia. Currency volatility and port congestion create input cost instability for domestic roasters.
- Dual Carbon Energy Costs:National decarbonization targets elevate roasting facility energy expenditures. MEE provincial enforcement varies, complicating multi-site operational planning.
- Functional Ingredient Restrictions:NMPA health claim limitations constrain adaptogen and nootropic coffee development. Additive approval timelines extend new product introduction cycles.
Strategic Opportunities
- Lower-Tier City Penetration:Chengdu, Hangzhou, and Wuhan exhibit rising café density but lag Shanghai's per-capita consumption. Real estate costs in these markets enable profitable kiosk-format expansion.
- Packaging Waste Regulation Tailwinds:Evolving provincial rules on single-use materials favor reusable cup programs and bulk bean retail. Early compliance builds brand differentiation ahead of mandatory thresholds.
- Automation-Convenience Convergence:Compact robotic espresso systems integrate with existing convenience store networks. This channel hybrid extends specialty access beyond standalone café real estate constraints.
Industry Challenges
- Q-Grader Talent Scarcity:Specialty roasting expansion outpaces certified green coffee grading capacity. Training pipelines lag market growth, creating quality control bottlenecks.
- Cross-Provincial Compliance Complexity:SAMR national standards interface with local food safety bureaus differently across municipalities. Multi-province operators face fragmented inspection protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Coffee Market |
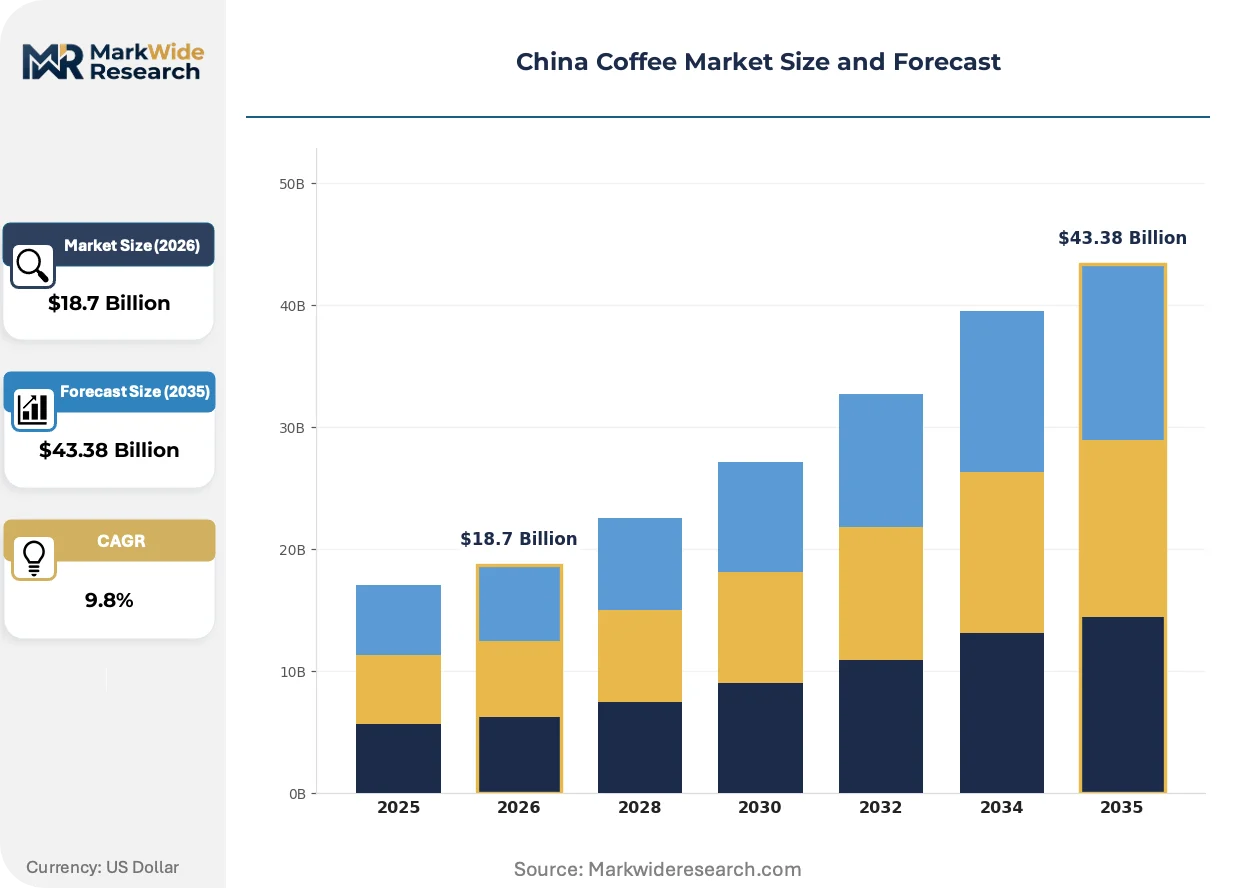
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Bean, Ground Coffee, Instant Coffee, Coffee Pods Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Coffee Shops Customer Type: Individual Consumers, Offices, Restaurants, Hotels Price Tier: Premium, Mid-Range, Economy, Discount |
| Companies Covered | Luckin Coffee Inc., Starbucks Corporation, Cotti Coffee, Nestle SA, TH International Limited, Pacific Coffee, Manner Coffee, Hainan Lisun Investment Co., Ltd., Luigi Lavazza SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Coffee Market Emerging Trajectories
Automation, regulatory tightening, and channel fragmentation are actively restructuring how coffee reaches Chinese consumers. These forces compress traditional operational models while opening new entry points for technology-enabled competitors.
Robotic espresso systems are hybridizing front-of-house labor models in high-throughput urban locations. Luckin Coffee deploys these units in delivery-optimized kitchens, reducing barista headcount while maintaining beverage consistency. The technology is compressing the viable scale threshold for automated café concepts below traditional format economics.
SAMR's evolving GB standards for contaminant limits and labeling requirements are tightening import clearance protocols. Roasted coffee shipments face enhanced laboratory testing at designated ports, extending customs dwell times. Premium whole bean importers are responding by pre-certifying supplier facilities and shifting volume through bonded warehouse zones.
White-collar procurement of office coffee is migrating from institutional foodservice contracts to direct-to-employer subscription platforms. Corporate procurement teams now negotiate directly with specialty roasters, disintermediating traditional vending operators. This pattern concentrates most visibly in Shanghai and Beijing technology sector headquarters.
China Coffee Market Segmentation

China's coffee market fragments across four distinct dimensions that determine how producers capture value and where capital deploys most efficiently. Product format dictates margin structure, while channel selection governs geographic reach and customer acquisition cost. Understanding these segment boundaries clarifies where automation investments and regulatory compliance burdens concentrate.
Product Type:
Mature formats dominate volume, though emerging segments reshape profitability expectations.
- Whole Bean:Unroasted or freshly roasted seeds packaged for home grinding, prized for aroma preservation and brewing ritual. Demand concentrates in Shanghai and Beijing among affluent households with manual brewing equipment; specialty roasting narratives and direct-trade sourcing justify price premiums. Whole Bean handles the majority of throughput; Coffee Pods are expanding most quickly on share.
- Ground Coffee:Pre-milled roasted coffee packaged in nitrogen-flushed bags, optimized for convenience without equipment investment. Offices in Shenzhen's technology corridor drive bulk procurement; freshness dating and origin labeling differentiate premium offerings from commodity alternatives.
- Instant Coffee:Spray-dried or freeze-dried soluble powder, the historical volume leader in China's market. Three-in-one formulations retain dominance in lower-tier cities where speed trumps sensory complexity.
- Coffee Pods:Single-serve aluminum or compostable capsules compatible with proprietary brewing systems. Live-stream commerce channels accelerate household adoption; NMPA food contact material standards constrain import formulations.
Instant Coffee retains the largest installed base; Coffee Pods exhibit the steepest expansion trajectory among product formats.
Distribution Channel:
Cost-to-serve varies dramatically by channel, determining which price tiers each can profitably carry.
- Supermarkets:Mass-market retail with established cold chain infrastructure for whole bean preservation. Carrefour and RT-Mart outlets in tier-one cities allocate premium shelf space to specialty roasting brands.
- Specialty Stores:Curated retail environments emphasizing origin storytelling and equipment cross-selling. Shanghai's former French Concession hosts the densest concentration of independent bean retailers.
- Online Retail:Digital-first fulfillment via Tmall, JD.com, and Douyin live-stream commerce. Subscription models reduce customer acquisition costs for repeat-purchase categories; SAMR e-commerce labeling requirements extend compliance obligations to platform sellers.
- Coffee Shops:Immediate-consumption venues with attached retail bean sales. Luckin's app-based ordering infrastructure and Starbucks' reserve roastery concepts anchor this channel in Beijing and Shenzhen.
Online Retail captures the fastest volume growth; Coffee Shops maintain the highest margin per transaction.
Customer Type:
Application context determines format preference and procurement authority structure.
- Individual Consumers:Household purchasers making discretionary replenishment decisions. Young professionals in tier-one cities drive specialty whole bean adoption through social media discovery.
- Offices:Corporate procurement of pantry and meeting room coffee. Direct-to-employer subscription platforms disintermediate traditional vending operators in Shanghai technology headquarters.
- Restaurants:Foodservice operations requiring consistent extraction for post-meal service. Mid-range dining chains in Chengdu specify blend profiles that balance cost with perceived quality.
- Hotels:Hospitality venues sourcing in-room and lobby service coffee. International chains in Beijing enforce sustainability certifications that constrain supplier selection.
Individual Consumers generate the broadest revenue base; Offices are climbing the fastest on procurement value.
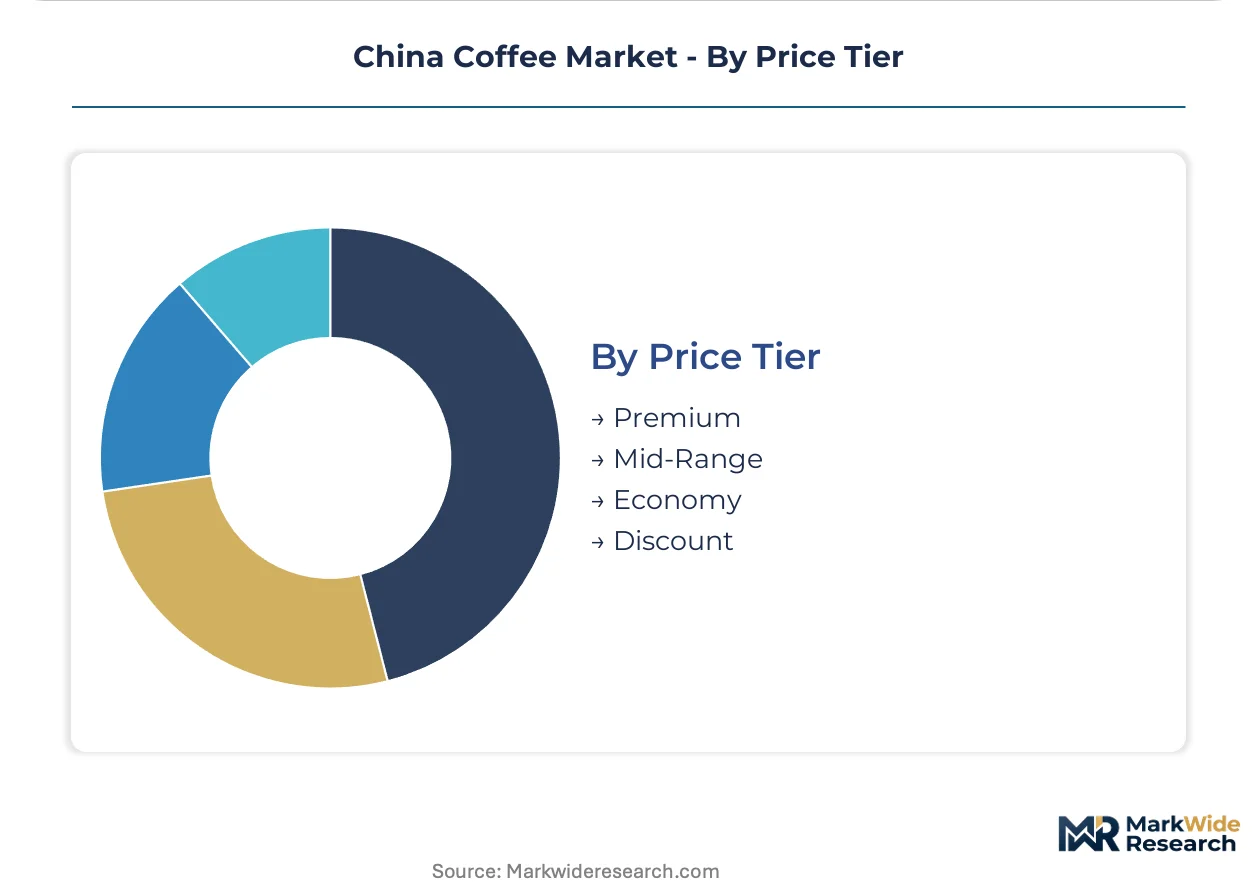
Price Tier:
Margin structure stratifies across four levels that correspond to supply chain control depth.
- Premium:Single-origin or micro-lot offerings with traceable provenance and Q-Grader certification. Direct-trade sourcing and small-batch roasting justify 3-5x commodity pricing; demand concentrates in Shanghai's specialty café corridor.
- Mid-Range:Blended commercial grades with consistent cup profiles and branded packaging. Domestic roasters in Hangzhou and Wuhan compete on freshness dating and regional identity.
- Economy:Standard commercial blends optimized for cost efficiency in high-volume channels. Supermarket private labels and institutional foodservice contracts dominate this tier.
- Discount:Commodity-grade instant coffee and bulk roasted products with minimal origin differentiation. Price-sensitive consumers in lower-tier cities sustain volume despite thin margins.
Economy tier handles the majority of unit volume; Premium tier is gaining share fastest among price segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban white-collar professionals in Shanghai, Beijing, and Shenzhen drive the majority of premium café consumption, with delivery infrastructure density and commercial district concentration determining where specialty chains expand first.
Yangtze River Delta
Shanghai anchors China's highest per-capita coffee consumption, with former French Concession specialty roasters and automated kiosk networks competing for commuter traffic. SAMR's GB standards for pre-packaged beverages tighten fastest in this jurisdiction. The Pudong-Lujiazui financial corridor sustains corporate subscription volumes that outpace national averages.
Pearl River Delta
Shenzhen's technology sector headquarters generate office coffee procurement shifting from vending contracts to direct roaster relationships. MEE provincial enforcement of dual carbon goals elevates roasting facility energy costs unevenly across Guangdong municipalities. Dongguan manufacturing clusters supply automated espresso equipment to café chains nationwide.
Beijing-Tianjin-Hebei
State-owned enterprise and government office procurement sustains mid-range instant coffee volumes despite specialty growth in Chaoyang and Haidian districts. NMPA health claim limitations constrain functional coffee development more stringently here than in southern provinces. Tongzhou sub-center construction is redistributing commercial café density eastward from traditional CBDs.
Sichuan-Chongqing
Chengdu's rising café density lags Shanghai's per-capita consumption but offers lower real estate costs for kiosk-format expansion. Local food safety bureaus apply SAMR national standards with inspection protocols that vary from coastal municipalities. Chongqing's mountainous geography complicates delivery corridor optimization for app-based ordering infrastructure.
Shandong Peninsula
Qingdao and Jinan exhibit growing whole bean adoption among affluent households with manual brewing equipment. Provincial packaging waste regulations are evolving ahead of national mandatory thresholds, favoring reusable cup programs. Weihai port infrastructure supports green bean import logistics for regional roasters sourcing from Vietnam and Brazil.
China Coffee Market Vendor Landscape
Channel-controlling players compete with product-specialist players across China's coffee market, creating a tiered structure where app-based delivery networks, reserve roastery concepts, and compact kiosk formats each occupy defensible positions. The competitive field separates into three strategic archetypes: technology-enabled volume operators, experiential premium anchors, and real-estate-efficient specialists. Dominant competitive moves include proprietary infrastructure investment and format miniaturization for lower-tier city penetration.
Within the technology-enabled volume tier, Luckin Coffee Inc. exemplifies channel control through app-based ordering infrastructure, while Starbucks Corporation anchors experiential positioning through reserve roastery investments in Shanghai and Beijing. Manner Coffee occupies the real-estate-efficient specialist position with compact kiosk formats that minimize overhead while sustaining throughput. These three players collectively represent the competitive vectors reshaping how coffee reaches Chinese consumers.
| Leading Market Players |
|---|
| Luckin Coffee Inc. |
| Starbucks Corporation |
| Cotti Coffee |
| Nestle SA |
| TH International Limited |
| Pacific Coffee |
| Manner Coffee |
| Hainan Lisun Investment Co., Ltd. |
| Luigi Lavazza SpA |
| Others |
Supply Flow & Price Mechanics
Vietnamese Robusta and Brazilian Arabica green bean procurement anchors margin distribution across China's roasting tiers, with import cost volatility compressing mid-range blender profitability while specialty single-origin premiums widen. Roasters in Shanghai and Beijing absorb currency fluctuation through long-term offtake structures, whereas smaller Hangzhou and Wuhan operators face spot market exposure that erodes working capital buffers.
Pricing Analysis
Cost-plus contracts indexed to the International Coffee Organization composite price dominate green bean procurement, with Vietnamese and Brazilian origin differentials adjusting quarterly. Three-tier pricing structure across premium, standard, and economy levels separates Q-Grader-certified micro-lots from commercial blends and commodity instant formulations. Pricing pressure stems from MEE dual carbon enforcement elevating roasting energy costs, particularly in Guangdong province. Economy-tier instant coffee buyers exhibit highest price sensitivity, while Shanghai specialty consumers tolerate 3-5x premiums for traceable provenance narratives.
Supply Chain Analysis
Green coffee feedstock draws from Vietnam, Brazil, and Colombia, with Weihai and Shanghai ports handling the majority of import volume. Roasted bean distribution, soluble powder processing, and capsule formulation rest on these upstream origins, while domestic roasting capacity clusters in Yangtze River Delta and Pearl River Delta manufacturing zones. Single-source vulnerability concentrates in Vietnamese Robusta dependency for instant coffee production. Distribution runs through bonded warehouse zones for pre-certified premium importers, direct-to-roaster container shipments for volume buyers, and e-commerce fulfillment centers for subscription retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's coffee market represents an early-cycle expansion story, with live-stream commerce and automated kiosk formats accelerating penetration beyond tier-one city saturation points. Corporate subscription platforms and lower-tier city real estate economics provide twin tailwinds for sustained adoption velocity.
For Market Incumbents: Entrench app-based ordering infrastructure against emerging kiosk-format competitors by expanding proprietary delivery corridor density in Chengdu and Wuhan. Lock in multi-year green bean offtake agreements with Vietnamese and Brazilian suppliers to insulate margin position from currency volatility. Vertical integration into automated espresso equipment manufacturing, leveraging Dongguan component supply clusters, reduces per-unit hardware costs for franchise expansion. For New Entrants and Emerging Players: Establish a beachhead in office coffee subscription platforms serving Beijing and Shanghai technology sector headquarters, where direct-to-employer procurement displaces traditional vending contracts. Target Sichuan-Chongqing corridor kiosk deployment, exploiting lower commercial real estate costs against saturated Shanghai and Beijing markets. Lead with reusable cup program compliance ahead of Shandong packaging waste regulations to build brand differentiation before mandatory thresholds propagate nationally. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated espresso equipment manufacturing, enabling asset-light franchise scaling for regional chain acquisitions. The 5-10 year viability window favors roasters with certified Q-Grader pipelines and bonded warehouse import infrastructure over pure retail format plays. Monitor NMPA additive approval timelines as inflection indicator for functional coffee product development runway.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary App Infrastructure Expansion | Luckin's delivery-optimized kitchen network demonstrates channel control defensibility against kiosk competitors. |
| Q-Grader Certification Pipeline Investment | Specialty roasting quality bottlenecks constrain expansion; certified talent scarcity creates acquisition premiums. |
| Bonded Warehouse Import Positioning | Pre-certified supplier facilities reduce SAMR customs dwell times for premium whole bean shipments. |
| Reusable Cup Program Pre-Compliance | Shandong packaging waste regulations favor early movers before national mandatory thresholds. |
| Automated Espresso Equipment Integration | Compact robotic systems compress viable scale thresholds below traditional café format economics. |
Methodological Framework
A spread of perspectives from green coffee importers, roasting facility operators, specialty café chain executives, and SAMR regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through NMPA food safety filings, customs import records, and GB standards documentation. Bottom-up volume modeling across product formats and price tiers triangulated against top-down market sizing from trade association disclosures and provincial bureau statistics.
Demand-supply-balance framing anchored the forecast framework, with consumption growth projections tested against green bean import capacity and roasting facility expansion plans across the analysis window. Segmentation dimensions modeled include product format, distribution channel, customer type, and price tier, with regional adoption patterns and regulatory enforcement intensity as cross-cutting variables. CAGRs derived from historical volume trajectories adjusted for channel shift acceleration and automation adoption curves.
Stress conditions across Vietnamese dong volatility, MEE provincial enforcement variance, and NMPA additive approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding live-stream commerce penetration and kiosk-format economics. Cross-checking against International Coffee Organization trade flow data and provincial bureau retail audit statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
United Kingdom Ready-To-Drink (RTD) Coffee Market
Coffee
Espresso Tamper Market
Coffee
UK Coffee Roaster Market
Coffee
Freeze Dried Coffee Market
Coffee
Reusable Coffee Cup Market
Coffee
US Instant Coffee Market
Coffee
Smart Coffee Maker Market
Coffee
North America Coffee Market
Coffee
Espresso Coffee Market
Coffee
Coffee Bottle Market
Coffee
Take Out Coffee Market
Coffee
Middle East Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
Coffee Roaster Market
Coffee
US Coffee Roaster Market
Coffee
Asia-Pacific Coffee Franchise Market