
 Organic Coffee Market | 2026-2036
Organic Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Coffee Market Intelligence
Ethiopia's highland cooperative expansion is rewriting upstream supply dynamics for premium arabica. Starbucks Corporation leverages vertical integration from farm-gate to retail, sustaining traceability premiums across its Reserve program. Nestlé S.A. anchors mass-market penetration through Nespresso's organic capsule lines, while Equal Exchange Co-op differentiates through cooperative ownership structures that control farmer-equity terms.
Organic coffee denotes arabica or robusta beans cultivated without synthetic pesticides, herbicides, or genetically modified organisms, with certification requiring three-year soil transition periods and annual third-party audits; the resulting product serves both sensory-driven consumers and buyers seeking chemical-residue compliance. Whole beans occupy the highest margin pool within product type, as grinding-at-home trends sustain premium pricing, while cold brew represents the fastest-growing format driven by ready-to-drink convenience demand. Online retail channels now capture the most dynamic growth within distribution, though supermarkets still dominate volume throughput for household customer types.
The USDA's National Organic Program and the EU Organic Regulation set the dominant certification frameworks governing cross-border trade, with the EU Deforestation Regulation adding geolocation traceability requirements that reshape exporter compliance costs. The FAO's Codex Alimentarius provides harmonized residue thresholds that facilitate bilateral recognition agreements. Stakeholders must monitor how fragmentation between national organic standards affects market access, particularly where mutual recognition remains incomplete.
Market Dynamics
The EU Deforestation Regulation's geolocation traceability mandates are restructuring exporter compliance architectures and reshaping procurement relationships between origin-country cooperatives and European importers.
Growth Catalysts
- EU Green Deal supply chain mandates:Deforestation-free certification requirements are accelerating third-party audit demand across East African and Latin American origin zones, tightening importer due diligence protocols.
- Specialty café channel expansion:Premium roasteries in Germany, the Netherlands, and Denmark are anchoring volume growth through direct-trade relationships that bypass conventional commodity exchanges.
- Soil microbiome regeneration protocols:Advances in compost tea inoculation and shade-tree polyculture are shortening effective transition periods for conventional-to-organic conversion at highland elevations.
Market Restraints
- Three-year soil transition lock-in:USDA National Organic Program and EU Organic Regulation mandate identical 36-month chemical-free periods before certification eligibility, freezing supply expansion timelines.
- Arabica concentration in Ethiopian highlands:Premium grade dependency on Yirgacheffe and Sidamo cooperative zones creates origination risk from localized climate volatility or political disruption.
- Robusta substitution pressure:Conventional Vietnamese and Indonesian robusta supplies undercut organic arabica pricing in instant coffee and commercial roast segments.
Strategic Opportunities
- Underpenetrated Nordic retail:Sweden and Norway maintain below-EU-average organic coffee household penetration despite high per-capita consumption, presenting white-space for specialty format entry.
- Cold brew ready-to-drink formats:Nitrogen-infused and shelf-stable concentrate packaging is opening convenience-store and foodservice channels previously inaccessible to whole-bean specialists.
- EU Organic Regulation harmonization:Mutual recognition expansion with third-country equivalency agreements is reducing duplicative certification costs for exporters in Peru and Colombia.
Industry Challenges
- Agronomist certification backlog:Accredited organic inspector scarcity in East Africa and Central America is extending audit scheduling delays beyond 18 months for new cooperative applicants.
- Legacy roasting equipment retrofit costs:Conventional drum roasters require separate organic-dedicated lines to prevent cross-contamination, demanding capital outlays that strain mid-scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Coffee Market |
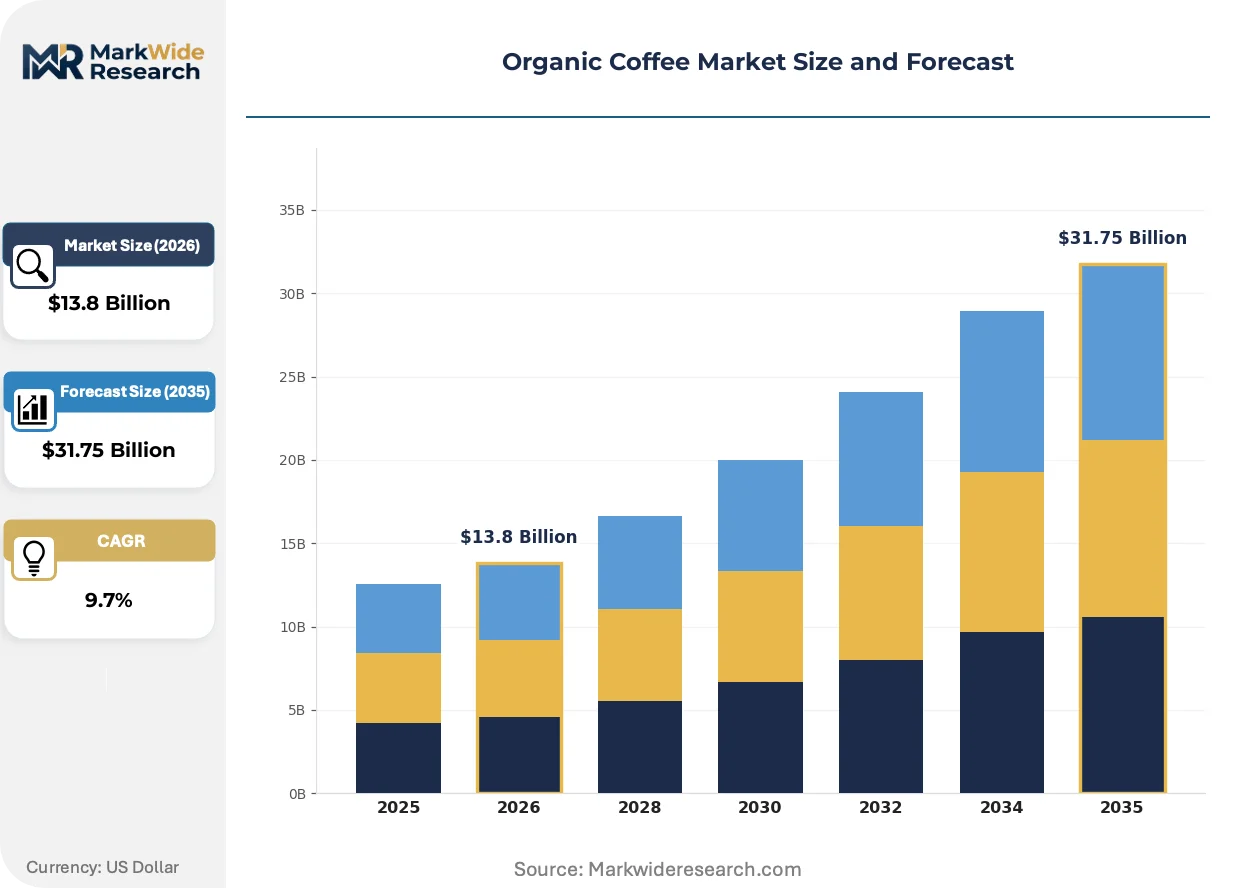
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $31.75 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Beans, Ground Coffee, Instant Coffee, Cold Brew Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Cafés Customer Type: Households, Offices, Coffee Shops, Restaurants Grade: Arabica, Robusta, Blends, Others |
| Companies Covered | Starbucks Corporation, Nestlé S.A., Keurig Dr Pepper Inc., Allegro Coffee Company, Luigi Lavazza S.p.A., Counter Culture Coffee, Jim’s Organic Coffee, The J.M. Smucker Company, Equal Exchange Co-op, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Coffee Market Strategic Shifts & Innovations
Processing technology and regulatory architecture are converging to compress supply chain opacity, while consumption patterns fragment across preparation formats and channel preferences.
Blockchain-enabled lot tracking is hybridizing with traditional cooperative bookkeeping systems to create immutable farm-to-port documentation. German and Swiss importers are deploying these hybrid systems fastest, driven by EU Deforestation Regulation documentation burdens. The resulting transparency infrastructure is compressing price discovery timelines and enabling real-time premium adjustments based on cupping scores and social compliance metrics.
EU Deforestation Regulation geolocation requirements are mandating polygon mapping of all production plots above 0.5 hectares for import eligibility. This policy is forcing exporters to invest in GPS-enabled farm boundary surveys and satellite monitoring subscriptions. Ethiopian and Colombian cooperatives face the steepest compliance cost curves, with many consolidating through secondary cooperatives to share traceability infrastructure investments.
Subscription-based direct-to-home roasting is displacing supermarket bulk purchasing among urban millennials in Germany and the Netherlands. These buyers prioritize freshness dating and origin storytelling over price minimization, channeling volume toward micro-roasters with weekly delivery cadences. Copenhagen and Berlin represent the densest adoption clusters, with household penetration rates substantially exceeding southern European cities.
Organic Coffee Market Segmentation
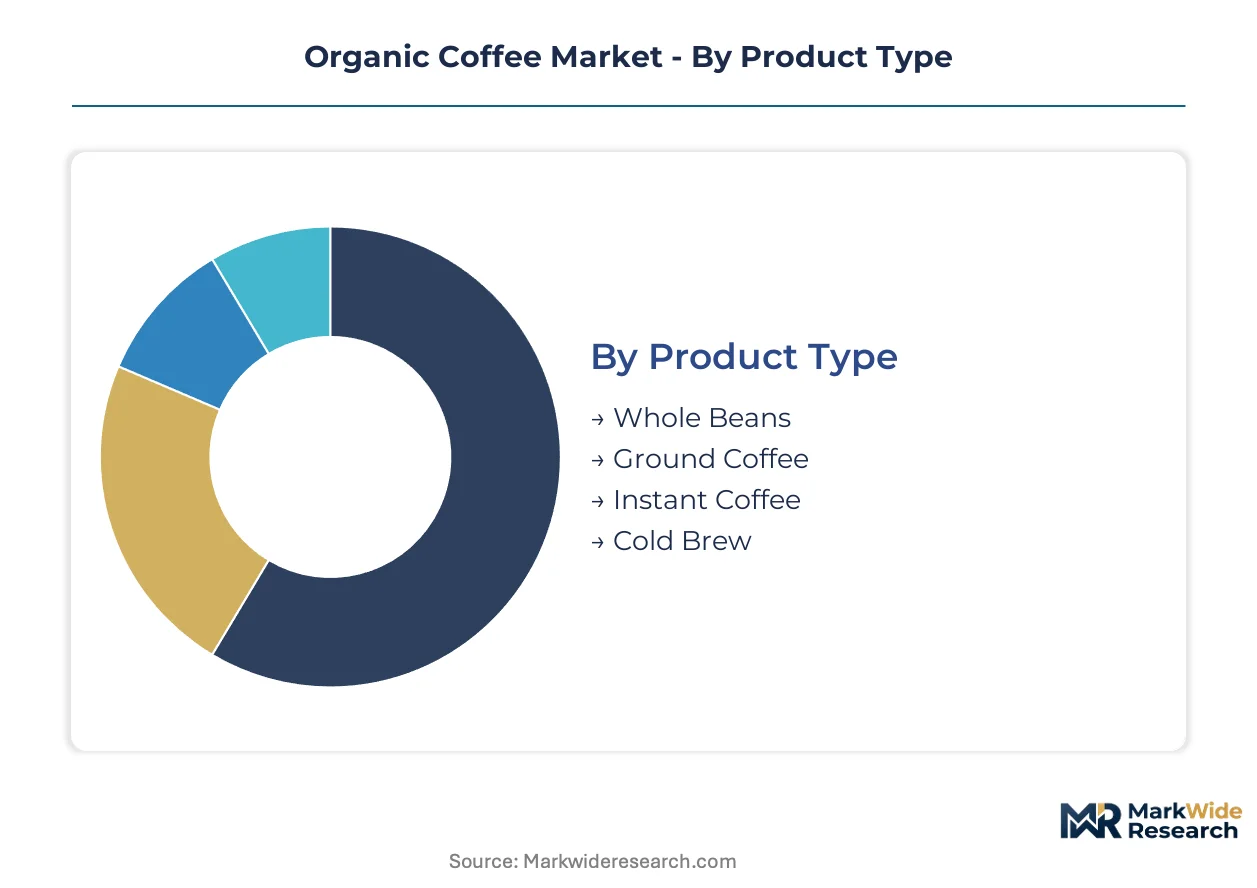
Organic coffee segmentation reveals how certification premiums flow through distinct product formats and procurement channels. Understanding these divides exposes where margin pools concentrate and where volume expansion faces structural barriers.
Product Type:
Inventory velocity varies dramatically across formats, with ready-to-drink cold brew turning weekly while whole beans sit for months in climate-controlled storage.
- Whole Beans:Unprocessed arabica or robusta cherries dried and hulled to green bean state, retaining volatile aromatic compounds until grinding. German and Dutch households sustain the deepest demand concentration, driven by freshness-obsessed consumers operating home burr grinders. The three-year organic transition lock-in constrains supply elasticity for this highest-margin format.
- Cold Brew:Extended steeping in ambient or chilled water produces low-acidity concentrate, packaged in nitrogen-flushed cans or bag-in-box formats for foodservice. Copenhagen and Berlin cafés are deploying this format fastest, bypassing traditional espresso equipment capital requirements. Ready-to-drink convenience is opening convenience-store channels previously closed to organic specialists.
- Ground Coffee:Pre-milled beans packaged in nitrogen-flushed valve bags, sacrificing aromatic longevity for preparation speed.
- Instant Coffee:Spray-dried or freeze-dried soluble granules, dominated by Nestlé's organic capsule lines in European mass retail.
Whole Beans anchors the volume base while Cold Brew gains share at the steepest rate.
Distribution Channel:
Channel economics stratify sharply, with direct-to-consumer subscription models capturing triple the margin of supermarket slotting-fee arrangements.
- Online Retail:Direct-to-home roasting subscriptions and marketplace fulfillment, displacing bulk purchasing among urban millennials. Weekly delivery cadences from Berlin and Amsterdam micro-roasters sustain premium pricing through freshness dating and origin storytelling. The EU Deforestation Regulation's documentation burdens favor digital-native traceability platforms.
- Specialty Stores:Premium roasteries with in-house cupping labs and direct-trade relationships, bypassing commodity exchanges. Copenhagen and Stockholm clusters concentrate the highest per-capita household penetration in this channel.
- Supermarkets:Mass-market volume throughput for household customer types, dominated by private-label organic lines in German and Austrian retail chains.
- Cafés:Out-of-home consumption venues from independent espresso bars to Reserve-format flagship locations.
Supermarkets still move the heaviest tonnage while Online Retail expands most quickly.
Customer Type:
Procurement sophistication diverges, with coffee shops negotiating direct-trade contracts while offices default to distributor-managed pantry services.
- Coffee Shops:Specialty cafés and premium roasteries anchoring the fastest-growing buyer segment, particularly in Germany, the Netherlands, and Denmark. These operators prioritize traceability documentation and cupping-score transparency over price minimization.
- Households:Individual consumers purchasing for home preparation, split between grinder-owning enthusiasts and convenience-oriented pod users.
- Offices:Workplace pantry services and hospitality suites, typically procured through foodservice distributors with limited origin visibility.
- Restaurants:Fine-dining and casual dining operators, where organic certification supports menu storytelling but volume remains thin.
Households provide the revenue foundation while Coffee Shops climb the fastest.
Grade:
Botanical variety determines altitude requirements, processing protocols, and ultimately the certification cost structure borne by origin cooperatives.
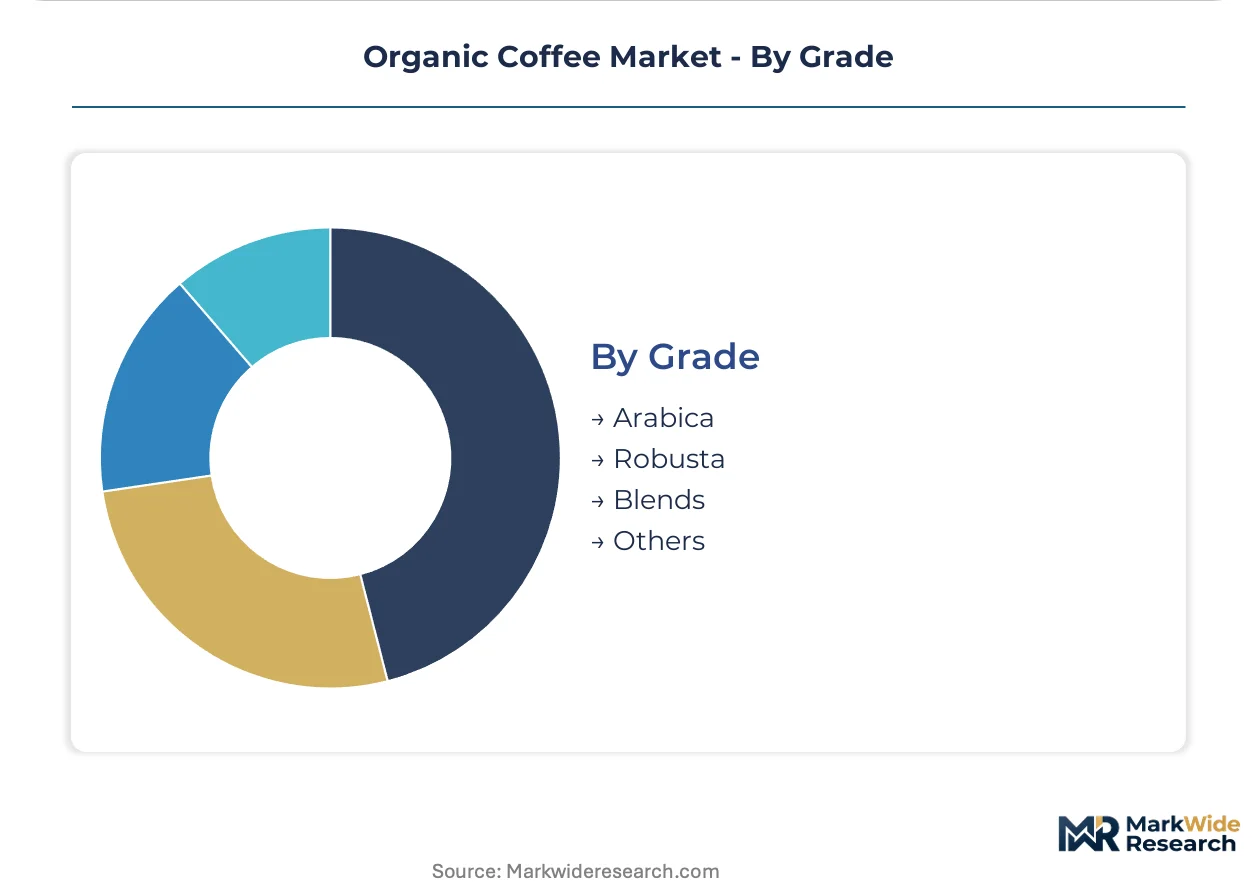
- Arabica:Coffea arabica cultivated above 1,200 meters in Ethiopian highlands and Colombian Andes, requiring shade-tree polyculture for organic compliance. Yirgacheffe and Sidamo cooperative zones face steepest EU Deforestation Regulation geolocation compliance costs.
- Robusta:Coffea canephora with higher caffeine content and disease resistance, concentrated in Vietnamese and Indonesian lowlands where organic transition remains sparse.
- Blends:Formulated combinations balancing arabica aromatics with robusta body, common in espresso roasting.
- Others:Liberica and excelsa varieties, negligible commercial presence in certified organic channels.
Arabica commands the premium tier while Blends sustain mainstream volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container terminals anchor northern Europe's organic coffee import throughput, handling the densest concentration of certified green bean arrivals from East African and Latin American origins. This maritime infrastructure underwrites Germany's role as the continent's distribution hub for premium arabica.
Germany
Specialty café density in Berlin and Hamburg sustains the deepest per-capita organic coffee consumption in Europe. The EU Organic Regulation harmonizes certification requirements across federal states, reducing duplicative audit burdens for importers. Bavaria's micro-roaster clusters in Munich are pioneering subscription-based direct-to-home models that bypass conventional retail.
Netherlands
Amsterdam's port infrastructure and specialty coffee culture combine to drive premium arabica import volumes. The EU Deforestation Regulation's geolocation mandates are accelerating digital traceability platform adoption among Dutch trading houses. Rotterdam's cold brew concentrate facilities are expanding nitrogen-flush canning capacity for convenience-store distribution.
United States
Seattle's roasting heritage and third-wave café proliferation anchor West Coast demand for certified organic whole beans. The USDA National Organic Program maintains strict three-year transition requirements that constrain supply elasticity. Brooklyn's micro-roaster ecosystem is displacing supermarket bulk purchasing through weekly subscription cadences.
Ethiopia
Yirgacheffe and Sidamo cooperative zones concentrate premium arabica origination for European and North American buyers. The country's agricultural regulator is coordinating with EU authorities on mutual recognition equivalency for organic certification. Addis Ababa's export consolidation facilities are investing in GPS-enabled farm boundary surveys to meet deforestation-free documentation requirements.
Colombia
Andean highland cooperatives in Huila and Nariño supply shade-grown arabica to German and Dutch direct-trade roasters. The national coffee federation is negotiating third-country equivalency agreements with EU authorities to reduce certification costs. Bogotá's specialty roasting clusters are developing cold brew concentrate capacity for regional foodservice channels.
Organic Coffee Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The organic coffee market exhibits tiered concentration, with multinational beverage platforms controlling mass retail channels while cooperative-owned roasters anchor specialty segments. Three archetypes dominate: vertically integrated café-retail hybrids, cooperative-equity trading houses, and capsule-format mass marketers. Competitive moves center on backward integration into origin-country cooperative partnerships and cold brew format capacity expansion.
Among publicly traded beverage platforms, Starbucks Corporation and Nestlé S.A. occupy positions that exemplify divergent strategic vectors—one toward experiential retail integration, the other toward mass-market capsule penetration. Equal Exchange Co-op represents the cooperative-equity archetype, embedding farmer ownership into trading structures. These three anchors illustrate how certification premiums flow through distinct governance models rather than converging on uniform competitive logic.
| Leading Market Players |
|---|
| Starbucks Corporation |
| Nestlé S.A. |
| Keurig Dr Pepper Inc. |
| Allegro Coffee Company |
| Luigi Lavazza S.p.A. |
| Counter Culture Coffee |
| Jim's Organic Coffee |
| The J.M. Smucker Company |
| Equal Exchange Co-op |
| Others |
Cost & Logistics Intelligence
Overcapacity in Vietnamese conventional robusta processing is compressing organic arabica premiums across European spot markets, forcing Ethiopian and Colombian cooperatives to absorb certification audit costs while German importers extend payment terms to preserve working capital.
Pricing Analysis
Three-tier pricing structure across Reserve-grade micro-lots, certified organic commodity lots, and conventional arabica separates cupping-score premiums from baseline organic certification markups. Price differentiation rests on EU Deforestation Regulation geolocation compliance costs and direct-trade relationship depth. Cost compression in instant coffee and commercial roast segments is intensifying because Vietnamese robusta undercuts organic arabica input costs. Household grinder-owners show least price sensitivity while foodservice distributors purchasing through pantry services exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from Hamburg and Rotterdam importers are straining Addis Ababa export consolidation facilities, forcing Ethiopian cooperatives to seek supply-chain finance facilities from regional development banks. Geographic supply concentration draws from Ethiopia, Colombia, and Vietnam. Raw material dependencies rest on shade-tree polyculture establishment, compost tea inoculation inputs, and nitrogen-flush packaging materials. Single-source vulnerability concentrates in Yirgacheffe and Sidamo cooperative zones where localized climate volatility threatens origination. Distribution runs through Port of Hamburg container terminals anchoring northern European throughput.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic coffee is approaching a platform-economics inflection where blockchain-enabled traceability infrastructure and subscription-based direct-to-home roasting interoperate to displace conventional commodity exchange price discovery.
For Market Incumbents: Entrench backward integration into Ethiopian highland cooperatives and Colombian Andean growing zones to secure deforestation-free certification pipelines before EU Deforestation Regulation enforcement tightens. Acquire GPS-enabled farm boundary survey capabilities and satellite monitoring subscriptions to compress compliance cost curves. Channel control through Reserve-format flagship locations protects margin pools against cold brew format entrants.
For New Entrants and Emerging Players: Swedish and Norwegian retail underpenetration relative to German consumption intensity presents white-space for specialty format entry with subscription-based direct-to-home roasting. Copenhagen and Berlin adoption clusters demonstrate millennial willingness to prioritize freshness dating over price minimization. Nitrogen-infused cold brew concentrate packaging opens convenience-store channels previously inaccessible to whole-bean specialists.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among micro-roasters operating weekly delivery cadences with digital-native traceability platforms. Long-term viability across the projection horizon favors acquisition targets with established EU Organic Regulation certification and existing cooperative equity structures. Monitor mutual recognition equivalency negotiations between EU authorities and third-country regulators as inflection indicator for certification cost compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origin Cooperatives | Captures deforestation-free certification premiums before EU Deforestation Regulation enforcement tightens compliance costs. |
| Cold Brew Format Capacity Expansion | Opens convenience-store and foodservice channels in Copenhagen and Berlin through nitrogen-flush canning infrastructure. |
| Blockchain Traceability Platform Deployment | Compresses price discovery timelines for German and Swiss importers facing EU geolocation documentation burdens. |
| Subscription-Based Direct-to-Home Launch | Displaces supermarket bulk purchasing among urban millennials prioritizing freshness dating over price minimization. |
| EU Organic Regulation Equivalency Investment | Reduces duplicative certification costs for Peruvian and Colombian exporters through mutual recognition expansion. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with specialty café procurement managers, cooperative export directors, German and Dutch trading house operators, and EU regulatory affairs specialists. Secondary validation drew from USDA National Organic Program filings, EU Organic Regulation implementation guidance, customs and trade data through Port of Hamburg and Rotterdam terminals, and cooperative audit documentation. Bottom-up volume modeling across product formats triangulated against top-down market sizing from certification body registries.
Calibration against historical organic certification growth patterns and cold brew format adoption curves anchored the analytical framework across the analysis window. Segmentation dimensions modeled included product type, distribution channel, customer type, and grade tier alongside geographic regulatory cluster differentiation. CAGRs were derived from trend extrapolation moderated by transition period constraints and compliance cost trajectory assumptions. Forecast inputs incorporated EU Deforestation Regulation implementation pace and subscription service penetration saturation curves.
Practitioners should monitor mutual recognition equivalency negotiations, agronomist certification backlog resolution, and cold brew format shelf-stable packaging innovation for early signals of trajectory revision. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and consumer willingness-to-pay elasticity. Macroeconomic contraction, regulatory delay, or technological substitution in alternative beverage categories would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Global Nespresso Capsules Market
Coffee
Reusable Coffee Cup Market
Coffee
Coffee Premixes Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Oceania Coffee Market
Coffee
Green Coffee Extract Market
Coffee
Coffee Roaster Machine Market
Coffee
Italy Coffee Market
Coffee
Specialty Coffee Market
Coffee
Global Coffee Shop Market
Coffee
Global Portable Coffee Makers Market
Coffee
Robusta Coffee Beans Market
Coffee
Coffee Pods and Capsules Market
Coffee
Encapsulated Caffeine Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
Canned Coffee Market