
 India Coffee Roaster Market | 2026-2036
India Coffee Roaster Market Size, Share, and Industry Trends Forecast 2026-2036
India Coffee Roaster Market Insights
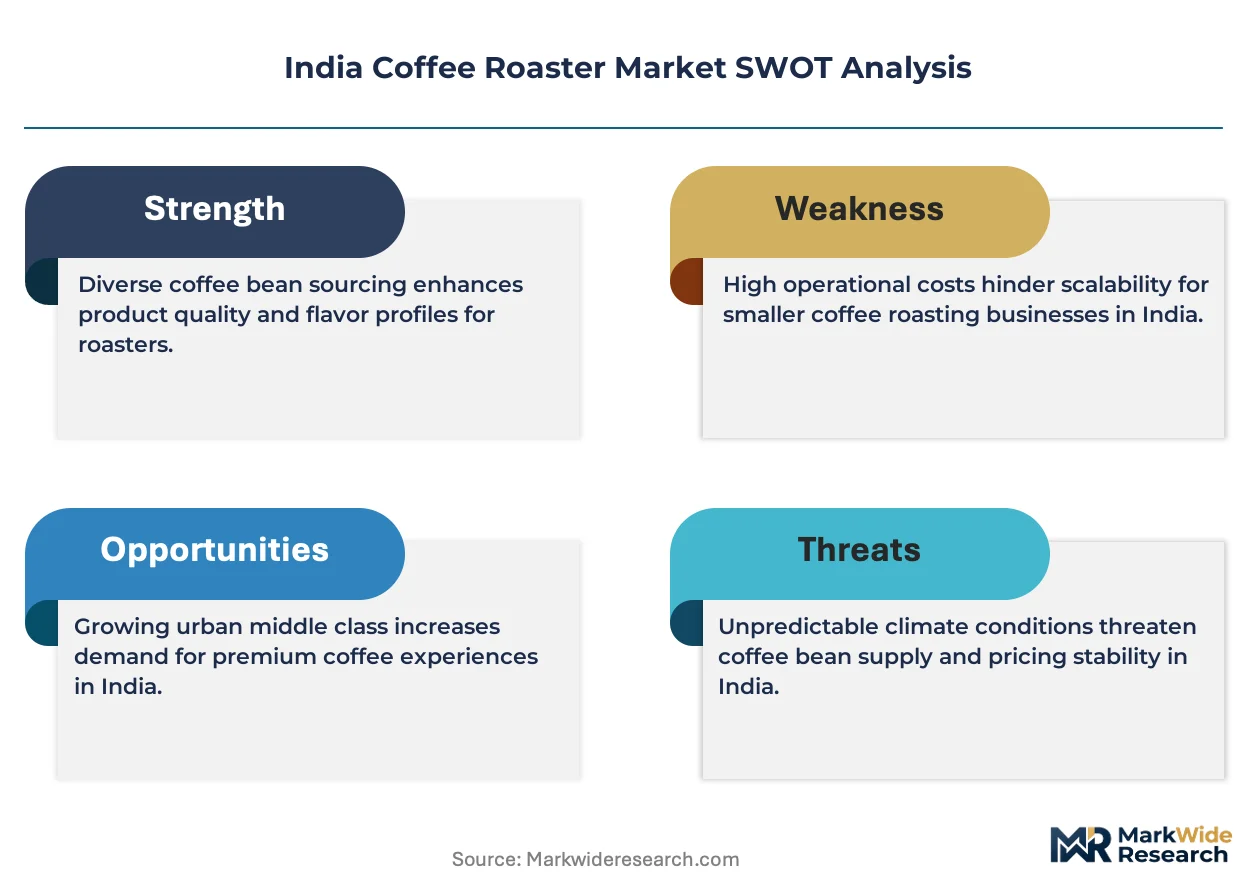
The capital-intensity divergence between artisan micro-roasters and scaled commercial operators is collapsing as mid-tier players adopt semi-automated drum systems. Blue Tokai Coffee Roasters leverages vertical integration from farm gate to café shelf, controlling quality consistency across its roasting network. Araku sustains premium positioning through single-origin specialization in the Eastern Ghats. KC Roasters anchors its presence in Maharashtra through equipment-leasing models that lower entry barriers for independent cafés.
A coffee roaster is a thermal processing machine that heats green coffee beans to temperatures between 180°C and 230°C, triggering Maillard reactions that develop volatile aromatic compounds and reduce moisture content from roughly 12% to 1-2%. Its primary commercial purpose is to transform raw agricultural commodity into shelf-stable, flavor-differentiated product for beverage preparation. Drum roasting technology dominates the installed base due to superior heat transfer control and batch traceability, while air roasting systems are gaining traction among specialty shops seeking brighter acidity profiles. The commercial roasters segment carries the largest revenue pool, though home roasters are expanding fastest among affluent urban consumers in tier-one cities. Specialty coffee applications command the widest margin spreads, particularly when tied to organic certification and direct-trade sourcing narratives.
BIS mandates electrical safety certification for commercial roasting equipment, while FSSAI guidelines govern hygiene standards in roasting facilities handling food-grade commodities. State-level pollution control boards in Karnataka and Tamil Nadu are tightening emissions norms for roasting operations in dense urban zones. Stakeholders must monitor how evolving BIS energy-efficiency standards and municipal air-quality enforcement reshape equipment replacement cycles and facility siting decisions.
Market Dynamics
Drum roasting automation is compressing the cost gap between artisan micro-roasters and scaled commercial operators, forcing mid-tier players to retool or exit as BIS electrical safety standards raise compliance thresholds.
Growth Catalysts
- PLI scheme incentives:The government's production-linked incentive scheme for food processing machinery subsidizes domestic roasting equipment manufacturing, lowering capital costs for café chains expanding in-house capacity.
- Specialty café proliferation:Bengaluru and Mumbai roasters are installing 15-30 kg batch drum systems to control origin narratives and margin capture from bean to cup.
- FSSAI hygiene mandates:Stricter facility certification requirements are accelerating replacement of legacy roasting infrastructure with stainless-steel, food-grade compliant systems.
Market Restraints
- Green bean price volatility:Arabica futures on international commodity exchanges expose roasters to input cost swings that compress roasting margins and deter capacity expansion.
- Equipment import dependence:High-capacity automated drum roasters from European and Turkish manufacturers face extended lead times and currency exposure, constraining rapid scaling.
- Karnataka and Tamil Nadu emissions enforcement:State pollution control boards are capping particulate discharge from roasting operations in dense urban zones, limiting facility siting options.
Strategic Opportunities
- Tier-two city underpenetration:Hyderabad, Pune, and Ahmedabad lack specialty roasting infrastructure relative to their consumption growth, creating first-mover positioning for equipment-leasing models.
- Direct-trade certification convergence:Organic and fair-trade sourcing narratives command retail premiums when paired with transparent roasting provenance, opening margin expansion for compliant operators.
- IoT-enabled predictive maintenance:Sensor-integrated drum roasters that monitor bean temperature curves and drum thermal efficiency are enabling outcome-based service contracts with café chains.
Industry Challenges
- Roastmaster talent scarcity:Skilled operators capable of profiling single-origin batches across variable moisture content and density are concentrated in South Indian coffee belt states, constraining geographic expansion.
- BIS certification timelines:Electrical safety testing and energy-efficiency validation for imported roasting equipment creates 4-6 month deployment delays that disrupt café opening schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Coffee Roaster Market |
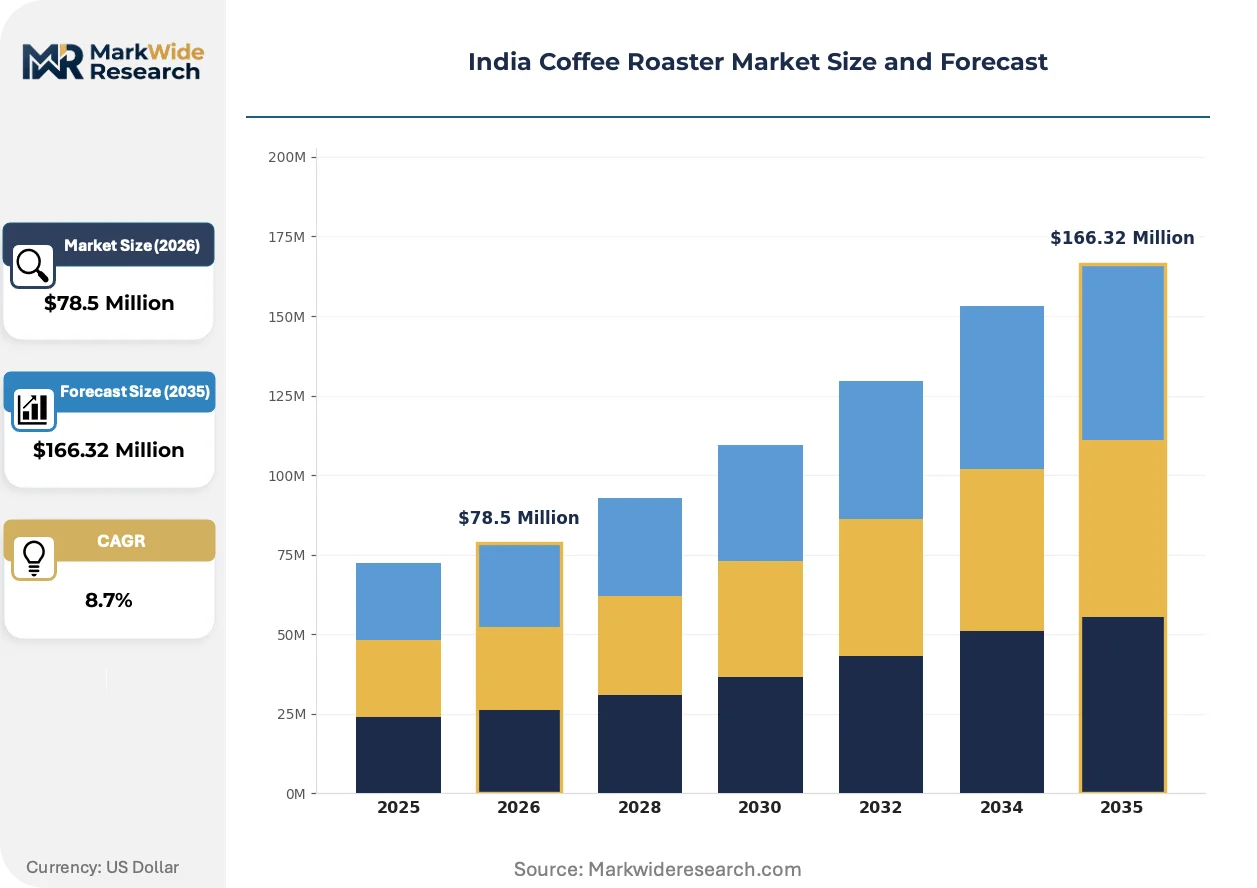
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $166.32 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Roasters, Home Roasters, Sample Roasters, Shop Roasters Technology: Air Roasting, Drum Roasting, Hybrid Roasting, Electric Roasting End User: Cafés, Restaurants, Specialty Shops, Retail Chains Application: Retail Coffee, Bulk Coffee, Specialty Coffee, Organic Coffee |
| Companies Covered | Blue Tokai Coffee Roasters, Araku, Bloom Coffee Roasters, KC Roasters, Subko Specialty Coffee Roasters, Cohoma Coffee Company, Maverick & Farmer Coffee, Country Bean Coffee, Levista Coffee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Coffee Roaster Market Trends and Innovations
Automation and data capture are redefining roasting economics, with sensor integration and regulatory pressure compressing the viable equipment range toward semi-automated mid-capacity systems.
Fluid-bed air roasting technology is miniaturizing from industrial-scale installations to 5-10 kg shop-floor units suitable for specialty cafés seeking brighter acidity profiles and faster batch turnaround. Mumbai and Delhi micro-roasters are piloting these systems for single-origin showcase roasts. The technology is miniaturizing capital requirements for flavor-differentiated positioning, enabling smaller operators to compete on cup quality without drum roasting infrastructure.
BIS energy-efficiency standards for commercial food processing equipment are tightening thermal performance thresholds for electric and gas-fired roasting systems. The regulations are accelerating replacement cycles for pre-2020 drum roasters in Karnataka and Tamil Nadu facilities. Medium-capacity operators in Bengaluru are retrofitting heat-recovery systems to comply ahead of enforcement deadlines.
Café chains are consolidating roasting procurement under centralized commissary models rather than maintaining dispersed site-level equipment. This pattern concentrates volume with regional roasting hubs and displaces independent micro-roasters from B2B supply relationships. The shift is most visible in Maharashtra, where Mumbai-based chains are building captive roasting capacity to serve multiple outlet locations.
India Coffee Roaster Market Segmentation
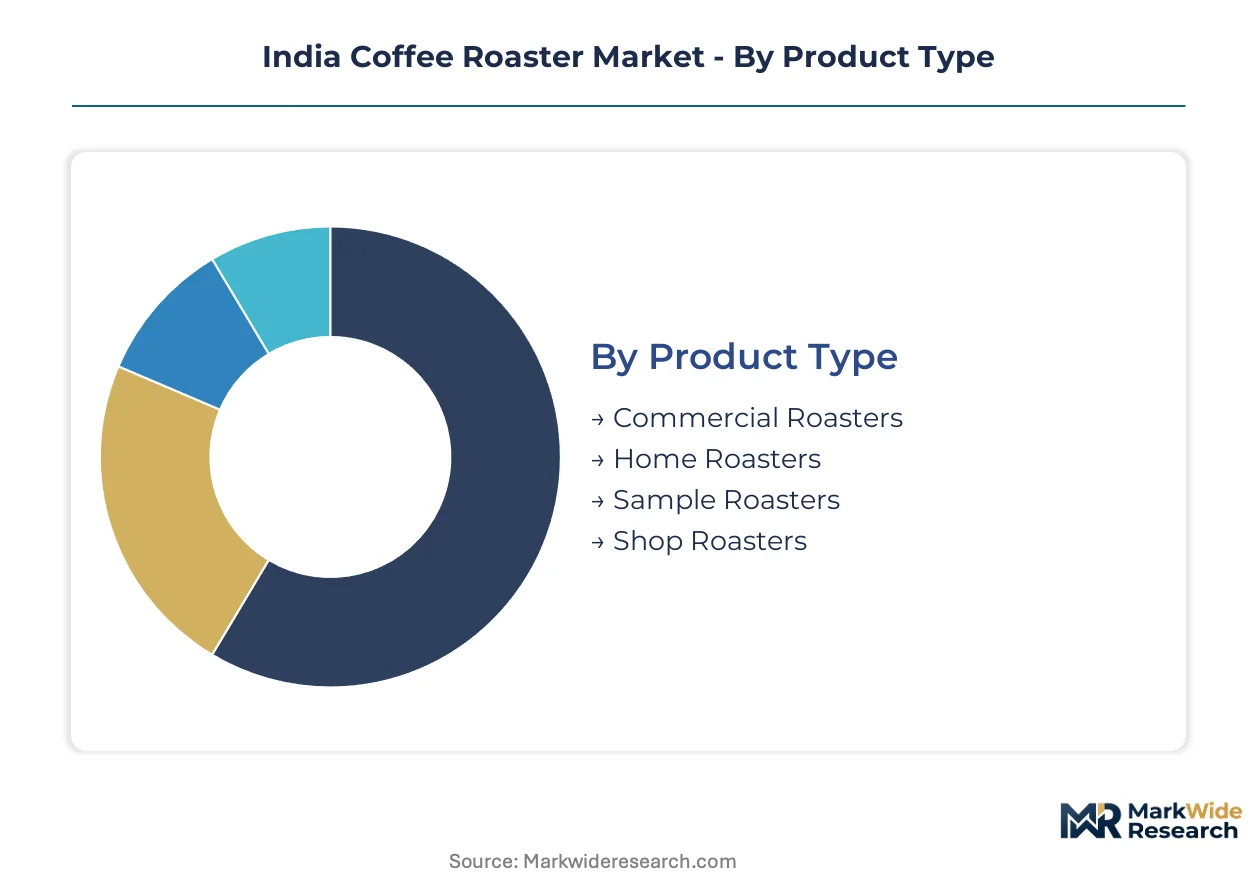
Equipment configuration and end-use concentration determine margin capture in India's coffee roasting landscape. Segmentation reveals how drum roasting automation and specialty café proliferation are reallocating revenue pools across technology tiers and customer categories.
Product Type:
Margin pools concentrate in commercial-scale systems serving café chains, while home roasting equipment climbs fastest among affluent urban consumers.
- Commercial Roasters:Batch-capacity systems ranging from 15 kg to 120 kg dominate revenue capture. Maharashtra and Karnataka café chains deploy these for centralized commissary roasting serving multiple outlet locations, with FSSAI hygiene mandates accelerating stainless-steel equipment replacement.
- Home Roasters:Electric countertop units with 100-500 gram capacity target tier-one city enthusiasts seeking origin control. Bengaluru and Mumbai households drive demand through direct-trade subscription models that bundle green bean supply with roasting hardware.
- Sample Roasters:1-5 kg laboratory-grade systems enable cupping and profile development for green bean procurement decisions.
- Shop Roasters:5-15 kg shop-floor units balance visibility and throughput for independent cafés in Hyderabad and Pune.
Commercial Roasters holds installed capacity. Home Roasters is rotating up the share rankings.
Technology:
Cost tier stratification separates legacy drum systems from emerging air roasting alternatives targeting acidity differentiation.
- Drum Roasting:Indirect heat transfer through rotating steel drums delivers precise temperature curve control and batch traceability. Karnataka and Tamil Nadu facilities favor these systems for arabica-robusta blending operations, though BIS energy-efficiency standards are accelerating pre-2020 equipment replacement cycles.
- Air Roasting:Fluid-bed systems suspend beans in hot air streams for faster heat transfer and brighter cup profiles. Mumbai micro-roasters pilot 5-10 kg units for single-origin showcase batches that command retail premiums through acidity differentiation.
- Hybrid Roasting:Combined drum-air configurations optimize for both development time and flavor clarity in medium-scale operations.
- Electric Roasting:Grid-powered systems address municipal emissions enforcement in dense Bengaluru and Chennai urban zones where gas-fired equipment faces particulate discharge caps.
Drum Roasting anchors the installed base. Air Roasting is gaining share fastest among specialty operators.
End User:
Application intensity varies sharply, with cafés deploying in-house roasting for margin capture while retail chains consolidate under captive commissary models.
- Cafés:Independent and chain coffee shops represent the densest equipment deployment. Mumbai and Bengaluru operators install 15-30 kg drum systems to control origin narratives and capture value from bean to cup, displacing third-party roasted supply relationships.
- Restaurants:Food-service operations adopt compact shop roasters for menu differentiation and guest experience theater.
- Specialty Shops:Single-origin focused retailers in the Eastern Ghats and Coorg regions emphasize transparent roasting provenance.
- Retail Chains:Grocery and convenience formats source through centralized roasting hubs rather than maintaining dispersed site-level capacity.
Cafés command the deepest equipment penetration. Specialty Shops are climbing the fastest as direct-trade certification expands.
Application:
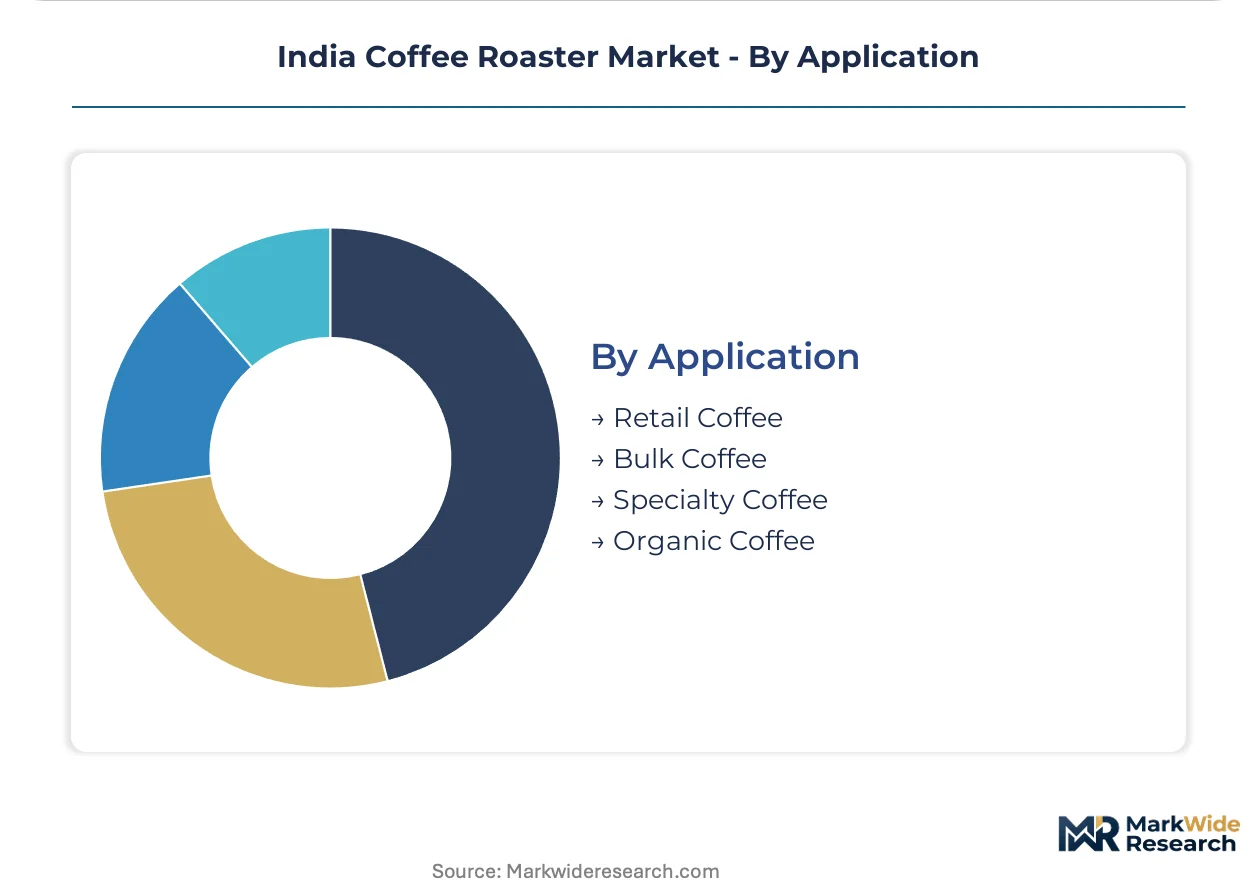
Customer type stratification separates commodity-volume bulk roasting from premium-capture specialty and organic positioning.
- Specialty Coffee:Single-origin and micro-lot roasting commands the widest margin spreads when paired with transparent sourcing narratives. Araku and Coorg region operators leverage this tier for farm-gate-to-café-shelf vertical control.
- Retail Coffee:Packaged whole-bean and ground products for grocery and e-commerce channels concentrate volume in Maharashtra and Karnataka processing clusters.
- Bulk Coffee:Institutional and food-service roasting prioritizes throughput over profile differentiation for hotel and airline supply contracts.
- Organic Coffee:Certified organic roasting requires segregated processing lines and documentation systems that add compliance cost but unlock export and premium domestic positioning.
Retail Coffee holds volume leadership. Specialty Coffee is rotating up the share rankings through café chain expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states, with Karnataka and Tamil Nadu buyers absorbing premium equipment costs while Maharashtra and Gujarat operators remain highly price-sensitive to green bean volatility.
Karnataka
Bengaluru café chains drive drum roasting automation adoption as origin-control narratives justify 15-30 kg batch investments. BIS electrical safety certification timelines compress deployment schedules for imported European equipment. Chikmagalur and Coorg arabica-robusta processing clusters anchor roasting infrastructure concentration in the Western Ghats.
Maharashtra
Mumbai specialty cafés expand in-house capacity through equipment-leasing models that lower capital barriers for independent operators. FSSAI hygiene mandates accelerate stainless-steel replacement of legacy roasting infrastructure. Pune and Nashik emerging as secondary roasting hubs serving western India distribution networks.
Tamil Nadu
Chennai roasters face tightening state pollution control board emissions caps on particulate discharge from gas-fired equipment. PLI scheme subsidies for food processing machinery reduce domestic equipment procurement costs. Nilgiri district single-origin specialists leverage transparent provenance for premium positioning in domestic and export channels.
Telangana
Hyderabad exhibits significant underpenetration relative to consumption growth, creating first-mover opportunities for mid-capacity roasting installations. State industrial policy incentives for food processing clusters reduce facility siting costs in peripheral zones. Secunderabad café operators pilot fluid-bed air roasting systems for acidity-differentiated specialty batches.
Gujarat
Ahmedabad and Surat food-service operators adopt compact shop roasters for menu differentiation amid limited specialty coffee infrastructure. DGFT import facilitation for processing machinery shortens equipment lead times versus other western states. Vadodara institutional roasting concentrates on bulk hotel and airline supply contracts with throughput prioritization over profile development.
India Coffee Roaster Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical control over farm-gate sourcing and café retail commanding premium positioning. The structure fragments across equipment-leasing intermediaries, single-origin purists, and scaled commissary operators. Three archetypes dominate: backward-integrated farm-to-café chains, equipment-financing enablers for independent cafés, and specialty purists anchored to specific terroirs. Competitive moves concentrate on captive roasting capacity expansion and direct-trade certification convergence for margin capture.
Within the integrated farm-to-café tier, Blue Tokai Coffee Roasters and Araku exemplify contrasting geographic strategies—one scaling across multiple Indian cities, the other anchored to Eastern Ghats single-origin specialization. KC Roasters occupies a distinct position in equipment-leasing models that lower entry barriers for Maharashtra independent operators. These three represent how vertical control, terroir anchoring, and financing innovation respectively define viable competitive positions.
| Leading Market Players |
|---|
| Blue Tokai Coffee Roasters |
| Araku |
| Bloom Coffee Roasters |
| KC Roasters |
| Subko Specialty Coffee Roasters |
| Cohoma Coffee Company |
| Maverick & Farmer Coffee |
| Country Bean Coffee |
| Levista Coffee |
| Others |
Pricing and Supply Chain Analysis
BIS electrical safety certification gates both equipment qualification and price tiering in India's coffee roaster market, with compliant stainless-steel systems commanding premiums over uncertified legacy units while disqualifying budget imports from commercial café procurement.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now drive lifetime value capture for drum roasting equipment vendors. Three-tier pricing structure across premium, standard, and economy levels segments buyers by automation grade and batch capacity, with FSSAI hygiene mandates compressing margins on entry-tier gas-fired systems. Cost compression in mid-capacity electric roasters is intensifying because PLI scheme subsidies for domestic manufacturing expand local supply. Independent cafés in tier-two cities exhibit highest price sensitivity, while Bengaluru and Mumbai chain operators absorb premium pricing for IoT-enabled systems.
Supply Chain Analysis
Extended lead times for European and Turkish high-capacity drum roasters stretch inventory cycles for Maharashtra and Karnataka café chains expanding captive capacity. Manufacturing concentrates in Germany, Turkey, and emerging domestic Indian assembly operations for food processing machinery. Critical component dependencies include precision temperature sensors, stainless-steel drum fabrication, and gas-electric hybrid burner systems. Single-source vulnerability for automated control modules from European suppliers creates disruption risk. Distribution runs through regional equipment-leasing intermediaries and direct manufacturer relationships with large café chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drum roasting automation and BIS energy-efficiency mandates constitute a dual inflection reshaping viable competitive positions, compressing the equipment range toward semi-automated mid-capacity systems and accelerating replacement cycles.
For Market Incumbents: Compound installed base advantages through captive roasting capacity expansion in underpenetrated Hyderabad and Pune markets, while retrofitting heat-recovery systems onto pre-2020 drum roasters ahead of Tamil Nadu and Karnataka emissions enforcement deadlines. Deepen backward integration into green bean sourcing to defend margin position against commodity price volatility.
For New Entrants and Emerging Players: Predictive maintenance service layers represent a critical gap where incumbents under-serve independent café operators. Target equipment-leasing models for tier-two city café chains lacking capital for 15-30 kg batch system acquisition. Deploy fluid-bed air roasting technology for acidity-differentiated positioning in Mumbai and Delhi specialty micro-roasting segments.
For Investors and Strategic Acquirers: BIS energy-efficiency standard tightening reshapes the acquisition landscape toward compliant equipment portfolios with retrofit service capabilities. Five-to-ten year viability favors operators with demonstrated direct-trade certification convergence and farm-gate sourcing relationships. Monitor Karnataka and Tamil Nadu pollution control board enforcement calendars as capacity utilization inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Drum Roasting Automation Deployment | Compresses cost gaps between artisan micro-roasters and scaled commercial operators in Bengaluru. |
| Heat-Recovery System Retrofit | Anticipates BIS energy-efficiency enforcement in Karnataka and Tamil Nadu urban roasting facilities. |
| Direct-Trade Certification Convergence | Unlocks retail premiums when paired with transparent roasting provenance in Eastern Ghats operations. |
| Equipment-Leasing Model Expansion | Lowers entry barriers for independent cafés in underpenetrated Hyderabad and Pune markets. |
| IoT-Enabled Predictive Maintenance Launch | Enables outcome-based service contracts with café chains monitoring bean temperature curves. |
Research Methodology
Desk research of BIS certification databases, FSSAI facility registration records, and PLI scheme beneficiary disclosures preceded structured interviews with roasting equipment plant managers, café chain procurement heads, aftermarket service technicians, and state pollution control board enforcement officers. Primary fieldwork across Karnataka, Maharashtra, and Tamil Nadu roasting clusters was cross-validated against customs import data for European and Turkish equipment, SEC filings of food processing machinery manufacturers, and café industry trade association membership directories. Bottom-up equipment installation counts were triangulated with top-down market size estimates.
Variance decomposition across product type, technology tier, end-user category, and application intensity shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating green bean price volatility assumptions and regulatory compliance cost escalations. Forecast inputs included café chain expansion pipelines, state-level emissions enforcement calendars, and PLI scheme subsidy allocation trajectories.
Material uncertainties — green bean commodity price swings, BIS certification timeline delays, and municipal air-quality enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation pace and equipment replacement cycle acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Coffee Crystal Market
Coffee
China Ready-To-Drink (RTD) Coffee Market
Coffee
South Korea Coffee Roaster Market
Coffee
Ground Coffee Market
Coffee
Global Coffee Market
Coffee
Mushroom Coffee Market
Coffee
Global Coffee Shop Market
Coffee
Global Portable Coffee Makers Market
Coffee
China Coffee Market
Coffee
Coffee Premixes Market
Coffee
Green Coffee Bean Extract Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Middle East Coffee Market
Coffee
Cold Brew Coffee Market
Coffee
Bioactive Compounds in Coffee Market