
 Gypsum Board Market | 2026-2036
Gypsum Board Market Size, Share, and Industry Trends Forecast 2026-2036
Gypsum Board Market Intelligence
The push for enhanced fire-resistant and soundproof gypsum boards is bifurcating the market between standard and specialized product tiers. Saint-Gobain leverages its extensive R&D capabilities to lead in high-performance segments. Knauf competes on manufacturing scale and a broad distribution network across multiple continents, while Georgia-Pacific specializes in the North American residential construction market. These firms navigate distinct supply chain and innovation pressures based on their strategic focus.
Gypsum board is a construction panel composed of a calcium sulfate dihydrate core, often with additives, pressed between two layers of heavy paper or fiberglass mats. It serves as a primary material for constructing interior walls and ceilings due to its workability and fire-retardant properties. The residential construction application remains the largest volume segment, though commercial projects command higher margins. Fire-resistant and moisture-resistant board product types are displacing standard boards in specified applications.
Product standards are governed by bodies like ASTM International in the United States and the CE marking framework under the EU's Construction Products Regulation. These regulations dictate minimum performance criteria for fire resistance, structural integrity, and material composition, influencing market access. Stakeholders must now decide whether to invest in manufacturing capabilities for higher-value, specialized boards or to optimize production for the high-volume standard board segment.
Market Dynamics
The convergence of stringent fire safety regulations and demand for enhanced acoustic performance in commercial buildings is the central force shaping the gypsum board market. Mandates like the EU's Construction Products Regulation are compelling a shift towards higher-specification products, creating distinct value tiers.
Growth Catalysts
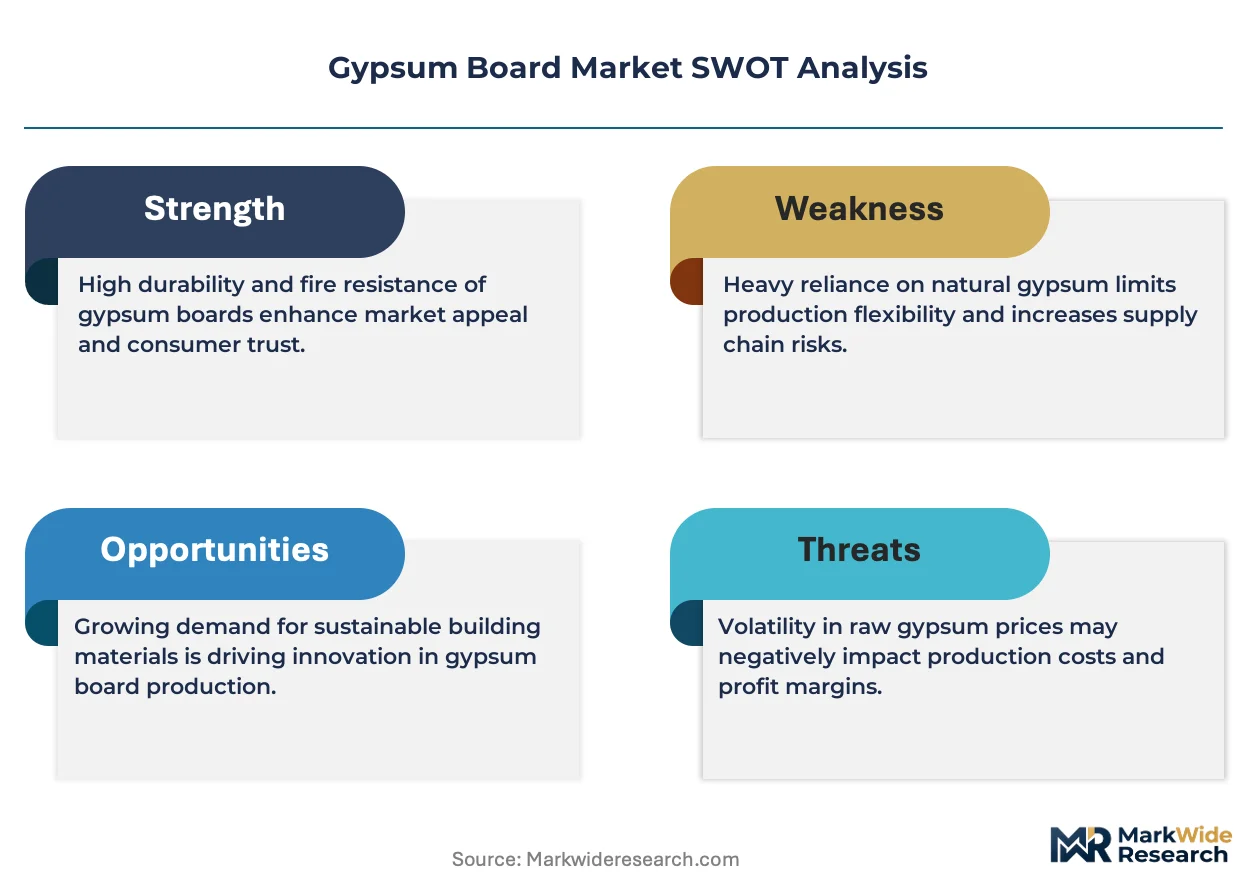
- EU Construction Products Regulation:This framework's CE marking requirements for fire resistance drive demand for certified high-performance boards across member states.
- Rapid Urbanization:High-volume residential and commercial construction in economies like India creates sustained demand for standard and specialized gypsum boards.
- Commercial Construction:New office and hospitality projects require high-performance boards for fire safety and sound insulation, boosting value segments globally.
Market Restraints
- Synthetic Gypsum Scarcity:A decline in coal power reduces the supply of flue-gas desulfurization (FGD) gypsum, a key raw material, creating cost pressures.
- Material Substitution:Magnesium oxide (MgO) boards and cement-fiber panels compete in applications requiring superior moisture or impact resistance, limiting market scope.
- Logistical Complexity:The weight and fragility of gypsum panels increase transportation costs and on-site damage risk, complicating project supply chains.
Strategic Opportunities
- Southeast Asian Markets:Construction growth in Vietnam and Indonesia offers expansion opportunities as modern building practices and codes are adopted.
- Prefabricated Construction:The move towards off-site manufacturing creates demand for specialized gypsum panels optimized for speed and ease of factory installation.
- Circular Economy Integration:Developing capabilities for recycling construction and demolition waste into new gypsum board aligns with emerging environmental regulations.
Industry Challenges
- High Capital Investment:Building or retrofitting manufacturing lines for specialized boards requires significant capital, posing a barrier for smaller producers.
- Fragmented Building Codes:Adhering to different standards like ASTM in the US and CE marking in Europe complicates product development and export.
- Installer Skill Gaps:A shortage of labor trained in advanced gypsum systems can slow the adoption of high-performance wall and ceiling assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gypsum Board Market |
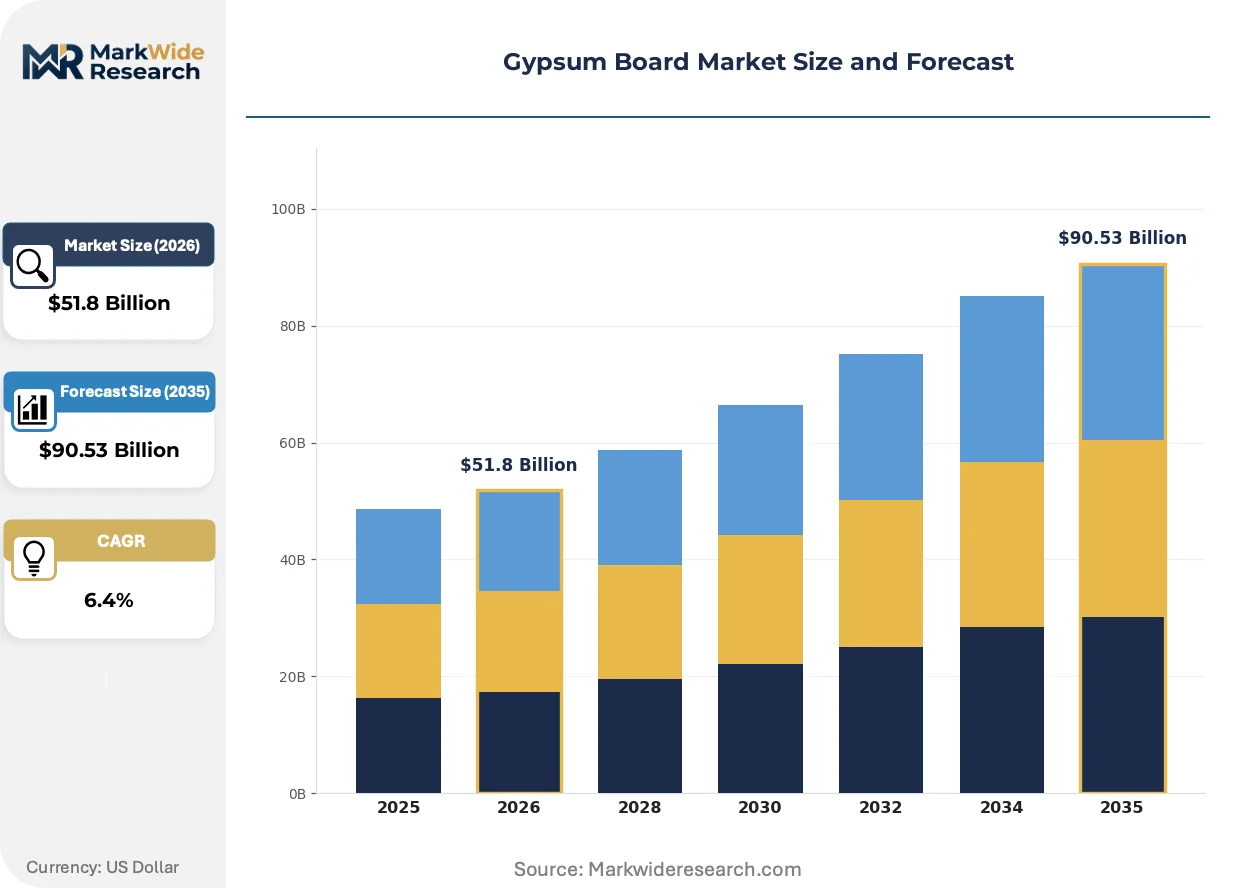
| Market Size in 2026 | $51.8 Billion |
| Market Size in 2035 | $90.53 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Gypsum Board, Moisture-Resistant Board, Fire-Resistant Board, Soundproof Board Application: Residential Construction, Commercial Construction, Industrial Applications, Renovation Projects End User: Contractors, Builders, Architects, DIY Consumers Thickness: 1/4 inch, 1/2 inch, 5/8 inch, 3/4 inch |
| Companies Covered | USG Corporation, Gold Bond, Knauf, American Gypsum Company, PABCO Gypsum, Saint-Gobain, National Gypsum, Etex Group, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gypsum Board Market Strategic Shifts & Innovations
A fundamental shift toward performance-driven specifications and sustainable building practices is reshaping product development. Manufacturers are innovating beyond standard panels to meet demands for enhanced fire safety, acoustic control, and lower environmental impact in construction.
Additives like glass fibers and vermiculite are integrated into the gypsum core to boost fire resistance and strength. Commercial construction, especially high-rise projects, is rapidly adopting these enhanced boards. This use of material science is bifurcating the market between standard boards and high-margin, specialized performance products.
The European Union's Construction Products Regulation (CPR) mandates specific fire-resistance classifications for building materials sold within the bloc. This policy forces manufacturers to provide detailed performance declarations and obtain CE marking, increasing compliance burdens. Consequently, product development is now heavily skewed towards achieving higher fire ratings to gain access to the commercial construction market.
Architectural specifications increasingly prioritize acoustic performance for occupant comfort in commercial and residential buildings. This shift elevates purchasing criteria beyond cost, driving demand for specialized sound-damping gypsum boards. This focus is most visible in North American and European urban markets for new office and multi-family construction.
Gypsum Board Market Segmentation
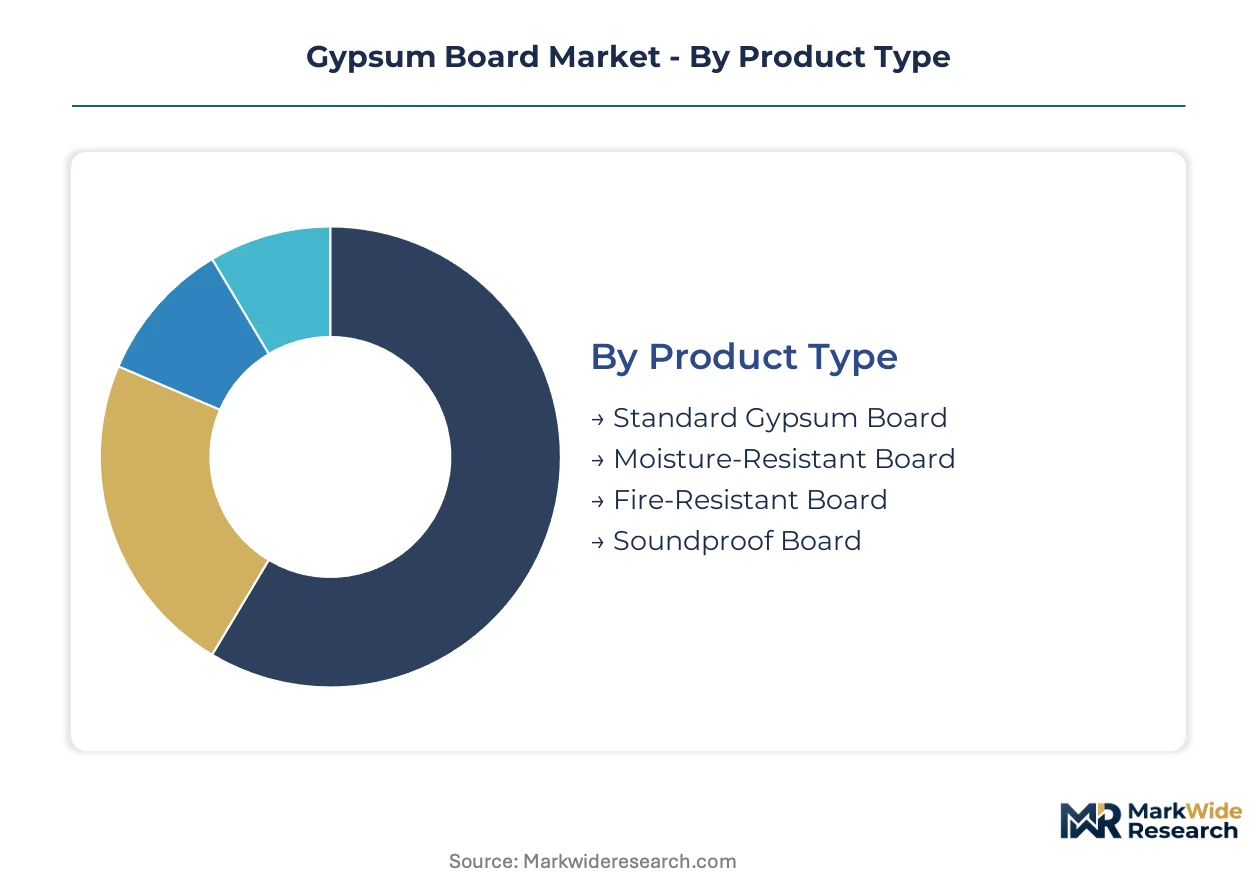
The gypsum board market's segmentation reveals distinct value propositions and demand drivers across various product forms and end-use applications. Understanding these segments is crucial for manufacturers to align production capabilities with evolving regulatory landscapes and consumer preferences.
Product Type:
The gypsum board market confronts significant substitution pressures, particularly for standard product types, as specialized alternatives gain traction across diverse construction needs.
- Fire-Resistant Board:Composed with fiberglass reinforcement and non-combustible minerals, these boards delay flame spread and maintain structural integrity during fire events. Demand concentrates in commercial high-rise projects and public buildings in Europe, driven by stringent CE marking fire safety requirements.
- Soundproof Board:Featuring a denser core or laminated layers, these panels absorb and block sound transmission, enhancing acoustic privacy and comfort. North American office spaces and multi-family residential units increasingly specify these boards to meet occupant satisfaction criteria.
- Standard Gypsum Board:This basic panel consists of a gypsum core encased in paper, serving as a foundational material for interior walls and ceilings.
- Moisture-Resistant Board:Treated with water-repellent additives, these boards resist humidity and mold growth in bathrooms and other damp environments.
Standard Gypsum Board retains volume leadership; Fire-Resistant Board holds the steepest expansion curve.
Application:
Application segments delineate distinct margin profiles, with commercial projects typically commanding higher-value board specifications compared to high-volume residential uses.
- Commercial Construction:This segment encompasses offices, retail spaces, and hospitality venues, requiring high-performance boards for fire safety and acoustic control. Demand for specialized boards is strong in rapidly urbanizing regions such as India and Southeast Asia.
- Residential Construction:This application includes single-family homes and multi-family dwellings, representing the largest volume segment for standard gypsum boards. Growth is sustained by new housing projects in fast-urbanizing economies.
- Industrial Applications:Gypsum boards find use in non-critical areas of industrial facilities, often for partitioning or non-load-bearing walls.
- Renovation Projects:These projects involve upgrading existing structures, driving demand for both standard and specialized boards to meet modern building codes.
Residential Construction represents the largest volume segment, while Commercial Construction demonstrates the most significant value growth.
End User:
End-user segments reflect varied procurement scales and product preferences, ranging from large-scale professional buyers to individual consumers.
- Contractors:Professional installation firms purchase gypsum boards in bulk for diverse projects, prioritizing ease of installation and material consistency. These entities often drive demand for specific product types based on project specifications.
- Builders:Companies engaged in new construction or large-scale development procure gypsum boards directly from manufacturers or distributors. Their purchasing decisions are influenced by project timelines and cost efficiencies.
- Architects:These professionals specify particular gypsum board types based on performance criteria, influencing material selection for commercial and high-end residential projects.
- DIY Consumers:Individual homeowners purchase gypsum boards for small-scale repair or renovation tasks, often favoring readily available standard boards from retail channels.
Professional end-users like Contractors and Builders account for the bulk of consumption, with DIY Consumers contributing to specialized retail channels.
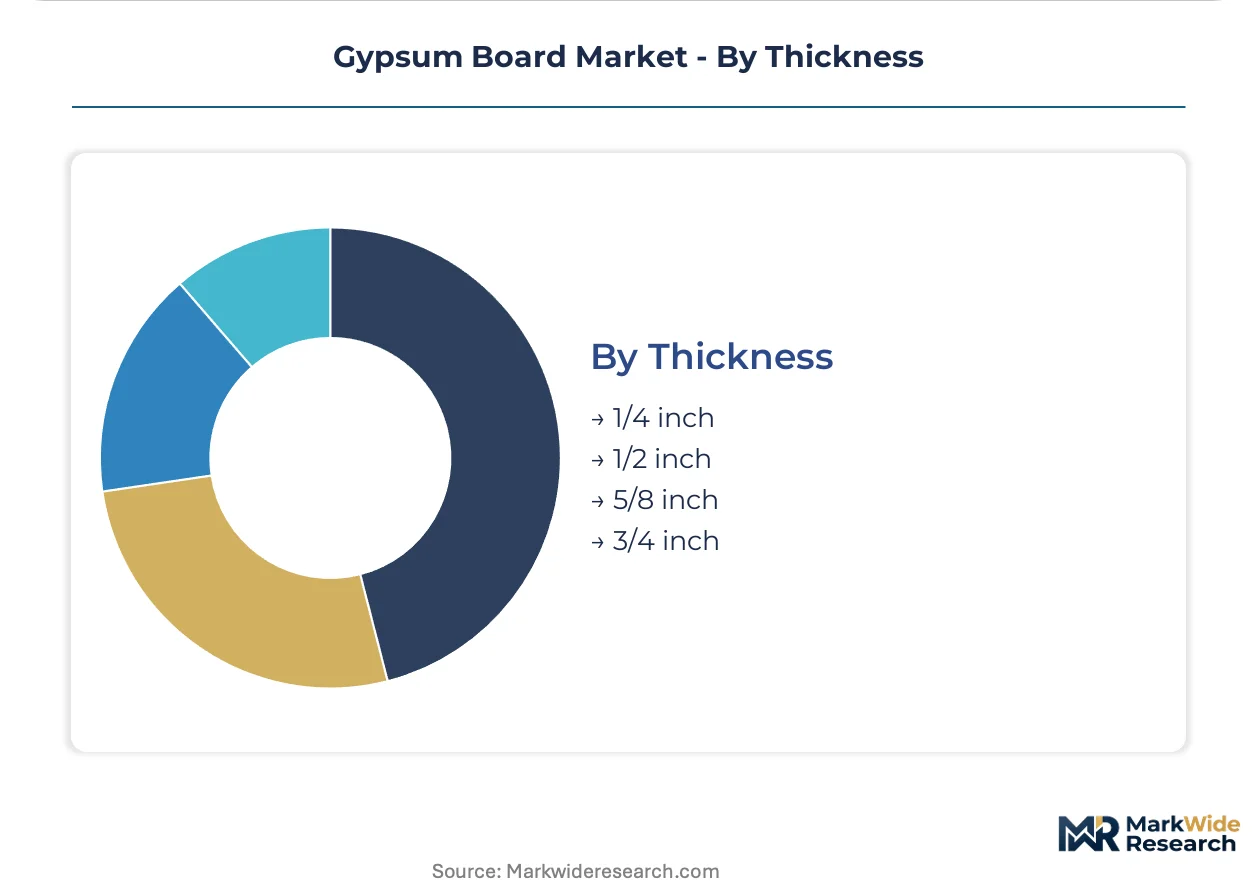
Thickness:
Board thickness directly correlates with structural performance and specific application requirements, influencing material selection across construction types.
- 1/2 inch:This common thickness is widely used for interior walls and ceilings in residential and light commercial construction due to its balance of weight, cost, and structural integrity. It offers sufficient rigidity for most standard applications.
- 5/8 inch:Often specified for enhanced fire resistance and sound attenuation, this thicker board finds application in commercial buildings and fire-rated assemblies. It provides superior performance where stricter building codes apply.
- 1/4 inch:This thinner board is typically used for curved surfaces, overlaying existing walls, or as a base for custom finishes due to its flexibility.
- 3/4 inch:Employed in specialized applications requiring maximum rigidity, impact resistance, or very high fire ratings, this thickness is less common but offers superior strength.
Mid-range thicknesses like 1/2 inch and 5/8 inch constitute the primary market volume, while 1/4 inch and 3/4 inch address niche performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global gypsum board market exhibits varied export-import dynamics, with established manufacturers often supplying specialized products to regions with nascent production capabilities. Raw material availability, particularly synthetic gypsum, influences trade flows and regional self-sufficiency. This balance shapes localized pricing structures and supply chain resilience across continents.
United States
Residential construction and commercial projects requiring fire-rated assemblies drive significant demand for gypsum boards. ASTM International standards govern product performance and safety, influencing material specifications across the country. Major manufacturers operate extensive facilities in states like Texas and Georgia, serving large-scale housing developments and commercial builds.
India
Rapid urbanization, coupled with infrastructure development and new housing projects, fuels sustained demand for gypsum boards. The PLI scheme for construction materials could incentivize domestic production and reduce reliance on imports. Construction hubs in Mumbai and Delhi drive significant volume demand for both standard and specialized boards.
Germany
Commercial building renovations and new office and hospitality projects require high-performance gypsum boards. The EU's Construction Products Regulation mandates CE marking for fire resistance, impacting product selection. Production facilities in North Rhine-Westphalia serve Central European markets, focusing on high-performance boards for enhanced safety and acoustics.
China
Extensive commercial and residential construction, particularly in urban centers, creates substantial demand for gypsum board products. GB standards dictate material composition and performance for building products, ensuring quality control. Major manufacturing clusters in the Yangtze River Delta support massive infrastructure and housing projects across the nation.
Vietnam
Modern building practices and increasing demand for fire-resistant and soundproof solutions are transforming the construction sector. Local building codes are evolving to align with international safety and performance benchmarks. Ho Chi Minh City's construction boom drives demand for imported and domestically produced specialized gypsum boards.
Gypsum Board Market Key Industry Players
Concentration sits with large, vertically integrated manufacturers dominating the global gypsum board market. The industry exhibits a tiered structure, with a few multinational corporations holding significant market share alongside numerous regional and local players. These firms often compete through capacity expansion and strategic partnerships to extend their geographic reach and product portfolios. Portfolio diversification into specialized boards, such as fire-resistant and soundproof options, also marks a key competitive move for established players.
Global manufacturers like Saint-Gobain S.A. and Knauf GmbH exemplify the scale and diversified product offerings in the gypsum board sector. Saint-Gobain represents a leader in high-performance segments, leveraging extensive research and development capabilities to meet stringent regulatory demands. Knauf occupies a position focused on manufacturing scale and broad distribution networks, ensuring wide market access across multiple continents. Georgia-Pacific LLC, a North American-based entity, anchors a significant portion of the residential construction market within its home region, adapting to local building trends. These companies collectively demonstrate varied strategic approaches to market penetration and product specialization, reflecting the market's evolving demands.
| Leading Market Players |
|---|
| USG Corporation |
| Gold Bond |
| Knauf |
| American Gypsum Company |
| PABCO Gypsum |
| Saint-Gobain |
| National Gypsum |
| Etex Group |
| Georgia-Pacific |
| Others |
Cost & Logistics Intelligence
Project-based contracts for large commercial developments lock in both supply access and price visibility for specialized gypsum boards. This structure mitigates raw material price volatility for major construction firms, ensuring consistent product availability for high-value projects.
Pricing Analysis
Contractors anchor the pricing structure for gypsum board, heavily influencing material selection based on project specifications. Pricing stratifies across performance tiers, with fire-resistant and soundproof boards commanding higher values due to specific CE marking or ASTM certifications. Pricing pressure stems from the declining availability of synthetic gypsum, increasing raw material input costs for manufacturers. DIY consumers exhibit the highest price sensitivity for standard boards, while commercial project developers prioritize performance over cost for specialized applications.
Supply Chain Analysis
Port congestion and container availability challenges impact inbound logistics costs for gypsum board raw materials, particularly for imported additives. Geographic supply of core gypsum material concentrates in countries like the United States, China, and Germany, alongside significant consumption in India. The supply chain draws from calcium sulfate dihydrate, paper or fiberglass mats, and performance-enhancing additives like glass fibers. Logistical complexity, driven by the weight and fragility of finished panels, represents a structural risk. Distribution primarily runs through direct channels to large builders and contractors, supplemented by wholesale distributors for smaller projects and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gypsum board market presents an early-cycle expansion story, buoyed by the global push for enhanced fire safety and acoustic performance in new construction.
For Market Incumbents:
Consolidate market share in high-performance segments by investing heavily in R&D for advanced fire-resistant and soundproof formulations. Expanding manufacturing capacity in fast-urbanizing regions like India and Southeast Asia can counter the threat of regional material substitution. Incumbents should leverage their extensive distribution networks and certification investments to maintain a competitive edge against emerging players.
For New Entrants and Emerging Players:
Certification fast-tracks into specific performance niches, such as specialized acoustic panels for healthcare facilities, offer a viable entry point. Target underpenetrated Southeast Asian markets, particularly Vietnam, where modern building practices are rapidly evolving. A focused go-to-market strategy emphasizing partnerships with architectural firms specializing in green building or prefabricated construction can secure early project wins.
For Investors and Strategic Acquirers:
Capital is best deployed toward specialized board manufacturers with proprietary technology in fire resistance or soundproofing, offering insulation from commodity pricing pressures. Long-term viability remains strong, driven by sustained urbanization and increasingly stringent building codes over the next decade. The signal to watch is the increasing adoption rate of industrialized construction methods, which favors specialized, factory-ready gypsum panels.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports growing construction demand and reduces import reliance in rapidly urbanizing economies. |
| R&D for Advanced Fire-Resistant Boards | Addresses evolving regulatory mandates and captures higher-margin commercial project specifications. |
| Integration of Circular Economy Practices | Aligns with sustainability goals and mitigates raw material scarcity through recycling construction waste. |
| Partnerships with Prefabricated Construction Firms | Captures demand from off-site manufacturing trends, optimizing panel installation efficiency. |
| Investment in Acoustic Performance Solutions | Responds to architectural trends prioritizing occupant comfort in commercial and multi-family buildings. |
Research Approach
The analysis maps key gypsum board product types and end-use applications, each validated through primary discussions with commercial contractors, architects, material scientists, and building code officials. Secondary data sources, including ASTM International standards, the EU Construction Products Regulation, national building codes, and construction industry reports, informed the market sizing. This approach utilized both bottom-up and top-down triangulation to ensure comprehensive market coverage and data accuracy.
Consistency checks across the analysis window validated volume and value outputs against historical trends and external benchmarks. The analytical framework modeled segmentation dimensions including product type, application, end-user, thickness, and regional regulatory frameworks. Compound annual growth rates were derived from historical data and projected future demand, incorporating key forecast inputs such as urbanization rates, construction spending, and anticipated regulatory updates.
Decision-makers should treat outputs as directional under base assumptions of stable regulatory environments and consistent raw material supply; material deviation would warrant model refresh. Forecasts reflect these assumptions, acknowledging that significant raw material price volatility or unforeseen economic downturns impacting construction could alter market trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Balustrade Market