
 North America Insulated Concrete Form (ICF) Market | 2026-2036
North America Insulated Concrete Form (ICF) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insulated Concrete Form (ICF) Market Analytics
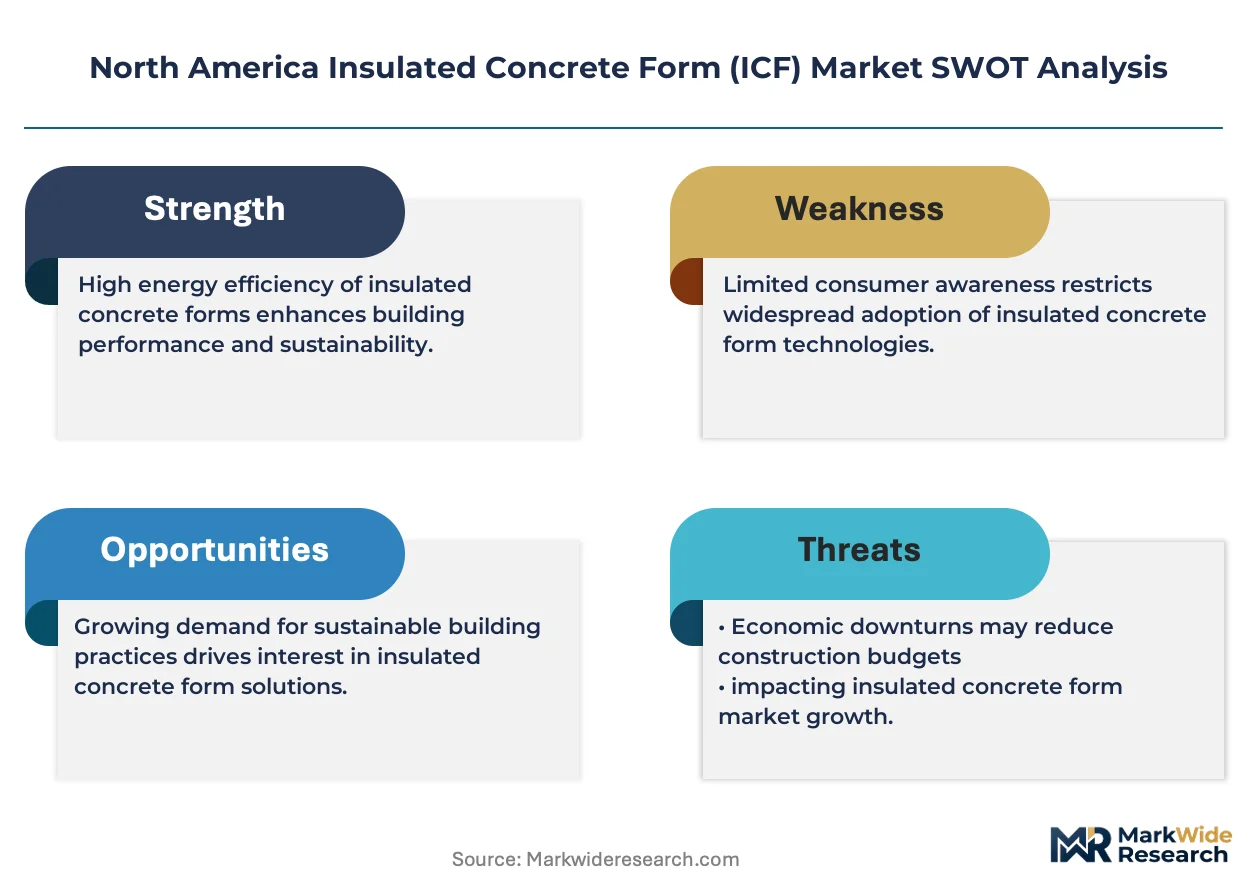
The US Department of Energy's escalating building energy codes is restructuring demand toward high-performance thermal envelopes across the region. Nudura Inc. leverages its integrated forming and insulation technology to capture specification-driven projects in the Midwest. BuildBlock Building Systems anchors its position through extensive distributor relationships and contractor training programs. Logix Insulated Concrete Forms Ltd. differentiates via its reversible panel design that reduces jobsite waste and labor cycles.
Insulated Concrete Forms are hollow, interlocking modular units made from expanded polystyrene or other rigid foam that workers stack and fill with reinforced concrete, creating monolithic walls with thermal resistance values exceeding R-22. The assembly serves as permanent formwork, insulation, and air barrier for below-grade and above-grade construction. Standard ICF dominates volume shipments across the region, while Specialty ICF commands premium positioning in acoustic-sensitive and blast-resistant applications. Residential Builders represent the deepest demand pool, though Commercial Contractors are expanding share as fire-rated and multi-story ICF assemblies gain code acceptance.
The US Environmental Protection Agency and Canada's National Research Council jointly influence product certification pathways through energy performance benchmarking and material safety standards. The International Energy Conservation Code adoption across US states creates uneven but progressive demand pull for thermal envelope upgrades. Stakeholders must monitor code divergence between Canadian provinces and US states to anticipate specification shifts and inventory positioning requirements.
Market Dynamics
The US Department of Energy's escalating R-value mandates are compressing specification cycles for thermal envelope assemblies across residential and commercial construction. Builders in hurricane-prone coastal corridors now treat ICF as default resilient infrastructure rather than premium upgrade.
Growth Catalysts
- International Energy Conservation Code adoption:US states are progressively mandating higher thermal resistance standards that ICF assemblies exceed without additional insulation layers.
- Coastal storm resilience requirements:Florida and Texas building codes now prioritize monolithic concrete wall systems for wind-load resistance in designated catastrophe zones.
- Multi-story commercial construction:Fire-rated ICF assemblies are gaining acceptance for mid-rise hotels and senior housing where traditional wood framing faces height restrictions.
Market Restraints
- Expanded polystyrene feedstock volatility:Petrochemical price swings compress margin predictability for form manufacturers dependent on resin supply chains.
- Specialized contractor scarcity:ICF installation requires trained crews familiar with concrete pumping and alignment systems, creating bottleneck risk in peak construction seasons.
- Light-gauge steel framing substitution:Cold-formed steel systems compete for mid-rise commercial projects with faster erection cycles and lower upfront material costs.
Strategic Opportunities
- Canadian provincial energy retrofit programs:Ontario and British Columbia incentive structures for deep energy retrofits create demand pull for ICF foundation systems in existing housing stock.
- Acoustic-rated specialty forms:Hospitals and recording studios in urban cores are specifying high-density ICF variants for sound transmission class ratings above STC 60.
- Direct-to-builder digital specification tools:Configurator platforms that automate thermal performance calculations are shortening the architect-to-contractor decision chain.
Industry Challenges
- Concrete pumping coordination complexity:Project schedules face disruption when ready-mix delivery windows conflict with ICF bracing and placement sequences.
- Code inspector familiarity gaps:Local authorities in jurisdictions with limited ICF exposure impose redundant testing requirements that extend permitting timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insulated Concrete Form (ICF) Market |
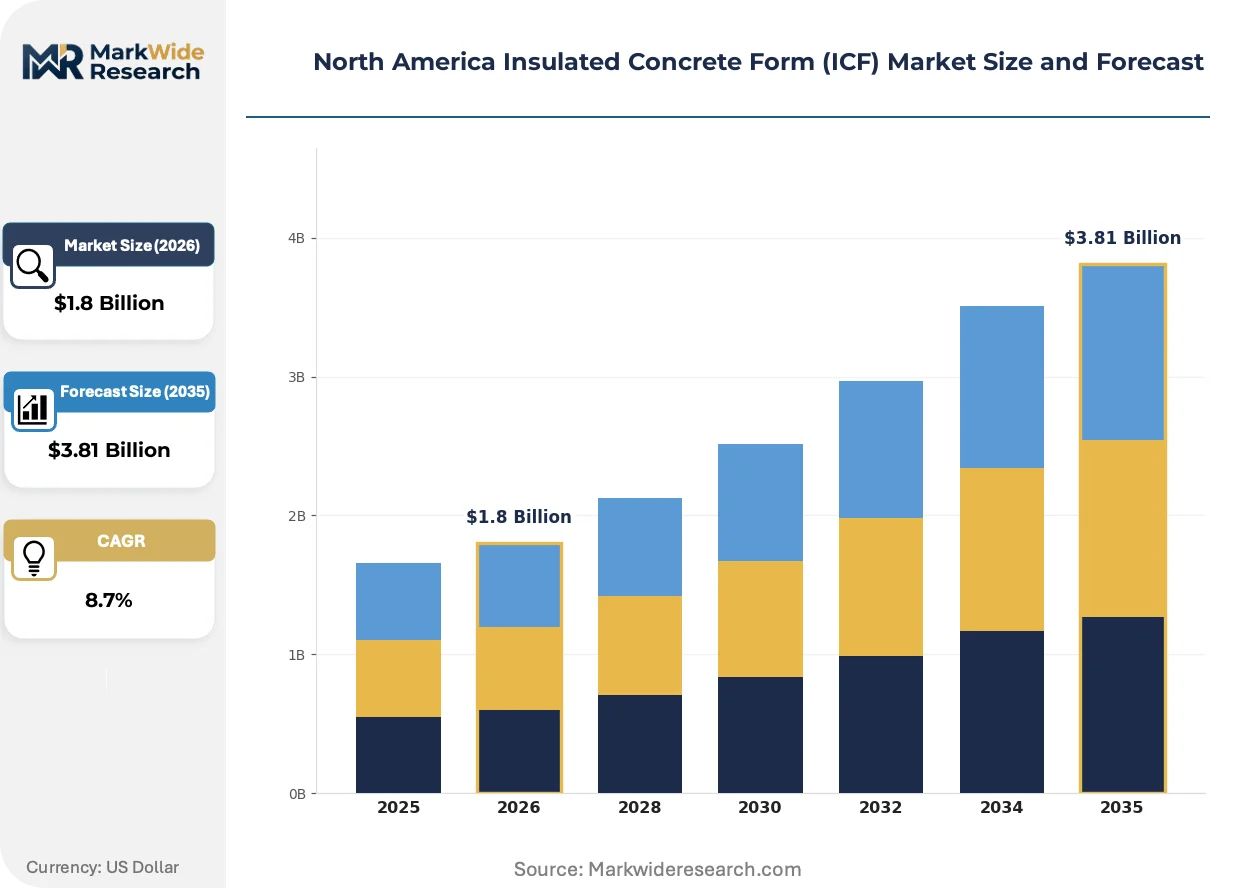
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard ICF, Specialty ICF, Reinforced ICF, Flexible ICF End User: Residential Builders, Commercial Contractors, Developer Groups, DIY Homeowners Application: Basements, Walls, Foundations, Roof Systems Distribution Channel: Direct Sales, Retail Distribution, Online Platforms, Wholesalers |
| Companies Covered | Nudura Inc., BuildBlock Building Systems, Logix Insulated Concrete Forms Ltd., Quad-Lock Building Systems, Superform Products Limited, Airlite Plastics Company, Amvic Inc., Fox Blocks, IntegraSpec, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insulated Concrete Form (ICF) Market Evolving Landscape
Material convergence and digital specification tools are compressing traditional design-bid-build cycles for envelope assemblies. The competitive frontier is shifting from product performance to installation speed and waste reduction.
Reversible panel ICF systems are unifying formwork and insulation functions in a single stackable unit that eliminates bracing teardown. Residential contractors in Texas and Florida are specifying these systems for slab-on-grade foundations to halve crew-day requirements. This unifying architecture is compressing the labor cost gap between ICF and conventional framed construction.
The US Department of Energy's building energy codes are mandating continuous insulation layers that eliminate thermal bridging in above-grade walls. Commercial developers in California are redesigning envelope specifications to meet Title 24 requirements without exterior rigid board additions. The multi-family residential segment is responding fastest by embedding ICF into standard design templates.
Builder procurement patterns are consolidating around distributors who bundle ICF with engineered lumber and weather barrier systems. Regional lumberyards in the Midwest are displacing traditional concrete specialty suppliers by offering contractor training and takeoff software. This channel consolidation is most visible in Ohio and Michigan where integrated material packages now dominate mid-scale residential bidding.
North America Insulated Concrete Form (ICF) Market Segmentation
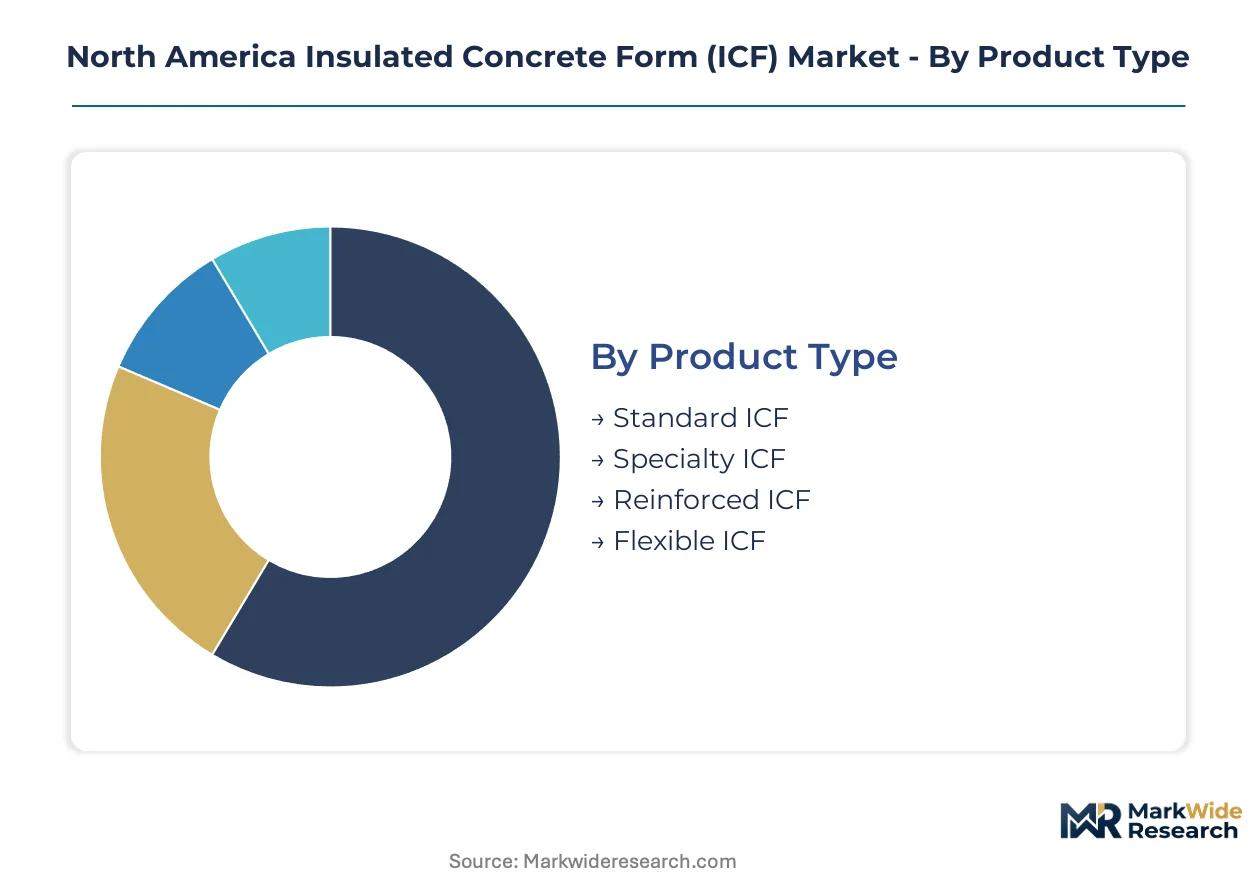
ICF procurement decisions hinge on thermal performance thresholds, installation speed, and code compliance requirements. Builders segment demand across product tiers, end-user sophistication, and application complexity to match envelope specifications with project economics.
Product Type:
Cost tier determines specification access for residential versus commercial buyers.
- Standard ICF:Expanded polystyrene panels with interlocking plastic webs form the baseline specification for single-family foundations and above-grade walls. Demand concentrates in Texas and Florida where builders prioritize wind-load resilience over premium thermal ratings. The International Energy Conservation Code adoption across US states reinforces specification for R-value compliance without additional insulation layers.
- Specialty ICF:High-density foam formulations and acoustic-rated cores serve hospitals, recording studios, and blast-resistant structures. California developers specify these variants for Title 24 energy compliance in multi-family mid-rise construction. Sound transmission class ratings above STC 60 command premium positioning in urban cores where noise mitigation drives code approvals.
- Reinforced ICF:Pre-engineered steel or fiber-composite webbing enhances structural capacity for multi-story commercial assemblies.
- Flexible ICF:Radius-capable forms accommodate curved architectural elements and custom residential designs.
Volume sits with Standard ICF; growth tilts toward Specialty ICF.
End User:
Customer sophistication separates specification-driven procurement from price-sensitive purchasing.
- Residential Builders:Production homebuilders in hurricane-prone coastal corridors now treat ICF as default resilient infrastructure. Crew-day economics dominate procurement as reversible panel systems compress labor cost gaps with conventional framing.
- Commercial Contractors:Fire-rated ICF assemblies gain acceptance for mid-rise hotels and senior housing where wood framing faces height restrictions. The US Department of Energy's escalating R-value mandates accelerate specification for thermal envelope upgrades in multi-story construction.
- Developer Groups:Institutional investors prioritize whole-building lifecycle costs over upfront material premiums.
- DIY Homeowners:Small-scale buyers depend on distributor training programs and digital configuration tools for foundation retrofits.
Residential Builders anchor current volume; Commercial Contractors are climbing the fastest.
Application:
Installation complexity and concrete coordination requirements segment demand by project phase.
- Basements:Below-grade walls demand moisture-resistant foam formulations and drainage integration. Ontario and British Columbia retrofit programs drive replacement demand in existing housing stock.
- Walls:Above-grade assemblies face continuous insulation mandates that eliminate thermal bridging. California Title 24 compliance accelerates specification without exterior rigid board additions.
- Foundations:Slab-on-grade systems in Texas and Florida halve crew-day requirements with reversible panel designs.
- Roof Systems:Insulated concrete roof decks remain niche due to structural load coordination and specialized contractor scarcity.
Walls dominate current installations; basements show steepest expansion trajectory.
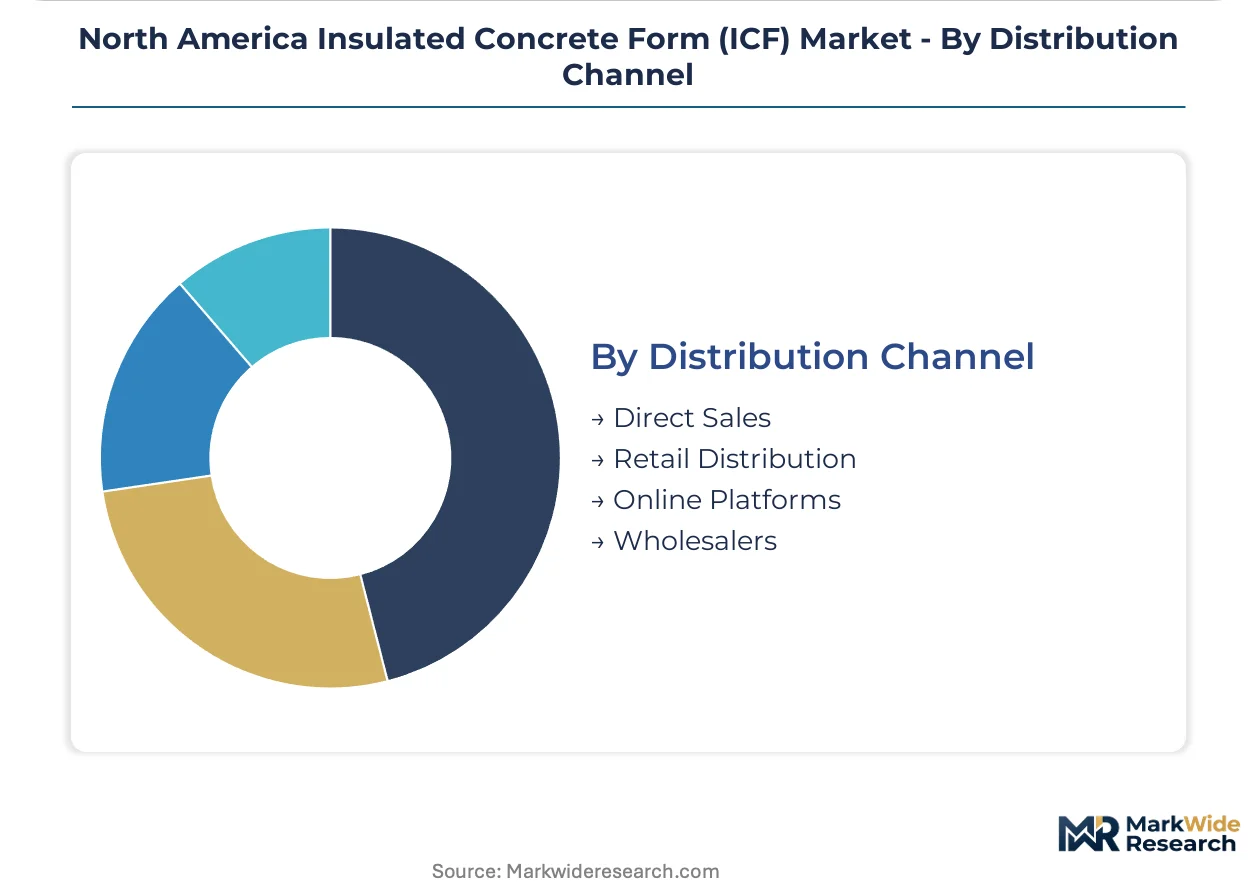
Distribution Channel:
Channel consolidation around bundled material packages is restructuring procurement access.
- Direct Sales:Manufacturers bypass intermediaries for large commercial projects requiring engineered takeoffs and technical support.
- Retail Distribution:Regional lumberyards in Ohio and Michigan displace concrete specialty suppliers by bundling ICF with engineered lumber and weather barrier systems.
- Online Platforms:Digital configurators automate thermal performance calculations for DIY homeowners and small contractors.
- Wholesalers:Traditional concrete supply houses retain share in markets with limited lumberyard ICF training capacity.
Retail Distribution captures the deepest volume; Online Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston-Galveston corridor anchors North American ICF demand as Gulf Coast builders retrofit storm-resilient foundations and above-grade walls ahead of hurricane seasons. This concentration radiates across state energy codes and provincial retrofit programs.
United States
Florida and Texas building codes now mandate monolithic concrete wall systems for wind-load resistance in designated catastrophe zones. The US Department of Energy's escalating R-value requirements through the International Energy Conservation Code accelerate specification for thermal envelope upgrades. The Dallas-Fort Worth metroplex sees production homebuilders embedding ICF into standard design templates for slab-on-grade foundations.
Canada
Ontario and British Columbia incentive structures for deep energy retrofits create demand pull for ICF foundation systems in existing housing stock. Health Canada's National Research Council jointly influences product certification pathways through material safety standards. The Greater Toronto Area anchors retrofit activity as provincial programs target below-grade thermal bridging reduction.
Mexico
Industrial corridor construction in Nuevo León and the Bajío Region drives specification for fire-rated assemblies in mid-rise manufacturing facilities. The country's national construction regulator advances energy efficiency benchmarking that elevates thermal envelope standards. Monterrey-based developers prioritize resilient concrete systems for seismic and thermal performance in expanding industrial parks.
North America Insulated Concrete Form (ICF) Market Competitive Landscape
The competitive structure tilts toward specification-driven specialists with integrated forming technology. Regional lumberyards displace traditional concrete specialty suppliers by bundling ICF with engineered lumber and weather barrier systems. Three archetypes dominate: integrated technology providers, distributor-network builders, and reversible-panel innovators. Capacity expansion and contractor training programs constitute the dominant competitive moves as players race to address specialized crew scarcity.
Within the integrated technology tier, Nudura Inc. and BuildBlock Building Systems occupy positions shaped by specification access and distribution depth. Logix Insulated Concrete Forms Ltd. anchors the reversible-panel innovation vector. These three exemplify how product architecture and channel configuration separate premium positioning from commodity volume play.
| Leading Market Players |
|---|
| Nudura Inc. |
| BuildBlock Building Systems |
| Logix Insulated Concrete Forms Ltd. |
| Quad-Lock Building Systems |
| Superform Products Limited |
| Airlite Plastics Company |
| Amvic Inc. |
| Fox Blocks |
| IntegraSpec |
| Others |
Value Network & Pricing Analysis
Expanded polystyrene resin feedstock volatility cascades through ICF manufacturing tiers, compressing margin predictability for form producers tethered to Gulf Coast petrochemical supply chains while forcing project-based pricing adjustments onto commercial contractors in Texas and Florida.
Pricing Analysis
Thermal performance outcomes anchor value-based pricing for ICF assemblies, with R-value compliance thresholds separating premium specialty forms from standard expanded polystyrene panels. Price differentiation rests on certification grade for wind-load resistance and acoustic transmission ratings, with California Title 24 compliance commanding substantial premiums over baseline IECC specifications. Cost compression in standard ICF tiers is intensifying because lumberyard distributors bundle formwork with engineered lumber packages at compressed margins. Production homebuilders in hurricane corridors exhibit highest price sensitivity, while hospital developers specifying STC 60+ acoustic assemblies demonstrate minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements from commercial contractors in Florida and Texas mandate multi-supplier qualification for expanded polystyrene resin, compelling manufacturers to maintain relationships with both domestic Gulf Coast producers and Canadian petrochemical suppliers. Geographic supply concentration centers on the United States, Canada, and Mexico for resin feedstock, with steel webbing components drawing from Midwest fabrication clusters. Raw material dependencies encompass styrene monomer, plasticizer additives, and galvanized steel ties. Single-source vulnerability persists for specialized high-density foam formulations used in blast-resistant applications. Distribution runs through regional lumberyards displacing traditional concrete specialty houses across Ohio, Michigan, and the Dallas-Fort Worth metroplex.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ICF market functions as a cost-of-compliance arena where the International Energy Conservation Code adoption across US states erects a certification barrier that filters out commodity formwork suppliers unable to document continuous insulation performance.
For Market Incumbents: Extend contractor training infrastructure into secondary markets where code inspector familiarity gaps create permitting bottlenecks for rival products. Deepen backward integration into expanded polystyrene resin production to insulate margin structures from petrochemical price swings. Capacity addition in Ontario and British Columbia captures provincial retrofit program incentives before regional lumberyards consolidate distribution access. For New Entrants and Emerging Players: The US Department of Energy's escalating R-value mandates in Texas and Florida open a window for specification-driven entrants with reversible panel designs that halve crew-day requirements. Target acoustic-rated specialty forms for urban hospital and recording studio verticals where STC 60+ ratings command premium positioning with limited incumbent competition. Pursue direct-to-builder digital specification tools that automate thermal performance calculations and compress architect-to-contractor decision cycles. For Investors and Strategic Acquirers: Distributor consolidation across Midwest lumberyards is the leading indicator that channel control is shifting from concrete specialty suppliers to integrated material bundlers. The five-to-ten-year viability window favors acquisition of reversible-panel technology specialists with established contractor training programs rather than commodity formwork producers. Watch for Ontario and British Columbia provincial program expansion as the signal for retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Contractor Training Program Expansion | Builds installation capacity in jurisdictions with inspector familiarity gaps and accelerates permitting timelines. |
| Backward Integration into Resin Production | Captures margin compression from Gulf Coast petrochemical volatility and secures supply continuity. |
| Digital Specification Platform Launch | Automates thermal performance calculations for Title 24 and IECC compliance, shortening design-bid-build cycles. |
| Acoustic-Rated Product Line Extension | Penetrates hospital and recording studio verticals where STC 60+ ratings command premium positioning. |
| Regional Lumberyard Partnership Deepening | Secures bundled distribution access in Ohio, Michigan, and Texas where integrated material packages dominate bidding. |
Research Methodology
Independent corroboration across ICF manufacturer sales executives, regional lumberyard procurement managers, and commercial contractor project directors underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with building code officials in Florida, Texas, and California alongside concrete pumping specialists and structural engineers specifying multi-story assemblies. Secondary validation drew from International Energy Conservation Code adoption tracking, US Department of Energy building energy code documentation, and provincial retrofit program filings in Ontario and British Columbia. Bottom-up shipment data from formwork producers was triangulated against top-down construction permit analysis for monolithic concrete wall systems.
Rate-of-change decomposition across the projection horizon separates volume expansion from value capture dynamics in the North America ICF market. The analytical framework models product type segmentation across standard, specialty, reinforced, and flexible form variants alongside end-user sophistication tiers and application complexity dimensions. CAGRs were derived from regression analysis of historical permitting data against code adoption timelines and energy efficiency mandate trajectories. Forecast inputs incorporated contractor crew availability indices and expanded polystyrene resin price series from Gulf Coast petrochemical benchmarks.
The model assumes a particular technology adoption path; alternative pathways for reversible panel systems achieving mainstream specification in single-family production housing would alter the outlook for labor cost parity with conventional framing. Forecasts reflect assumptions regarding continued International Energy Conservation Code progression and sustained provincial incentive structures in Canada. Deviation in petrochemical feedstock pricing or concrete pumping labor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Gutter and Downspout Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
Central & South America Iron Casting Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Vietnam Ceramic Tiles Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market