
 Concrete Floating Floors System Market | 2026-2036
Concrete Floating Floors System Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Floating Floors System Market Analysis
Specialist distributor networks across Europe is reconfiguring as manufacturers bypass traditional intermediaries to serve acoustic engineering consultancies directly. Kinetics Noise Control, Inc. leverages its vibration isolation expertise to anchor premium specification channels. GERB Schwingungsisolierungen GmbH & Co. dominates precision-engineered spring isolator supply for broadcast infrastructure. Mason Industries Inc. extends its elastomeric bearing portfolio into floating floor assemblies for healthcare and laboratory verticals.
A concrete floating floor system comprises a structural slab mechanically decoupled from the building frame via resilient bearings or spring isolators, achieving impact sound reduction ratings exceeding 25 dB in critical frequency bands. Precast systems lead specification volumes in commercial retrofit projects where speed of installation governs contractor selection, while modular technology segments are capturing specification share in multi-unit residential towers where repetitive floor plates reward factory-controlled tolerances. Sustainable technology formulations incorporating recycled aggregate binders are emerging as margin pools as green building certification thresholds harden across Northern Europe.
CE marking under the EU Construction Products Regulation governs structural bearing performance declarations for European projects, while the EPA's noise pollution guidelines influence federal facility specifications in the United States. Germany's KBA and regional building control offices enforce DIN-standard acoustic testing protocols that filter non-compliant suppliers from public cinema and concert venue tenders. Stakeholders must monitor evolving carbon-accounting rules for cementitious content as these threaten to recast material cost structures and supplier qualification criteria.
Market Dynamics
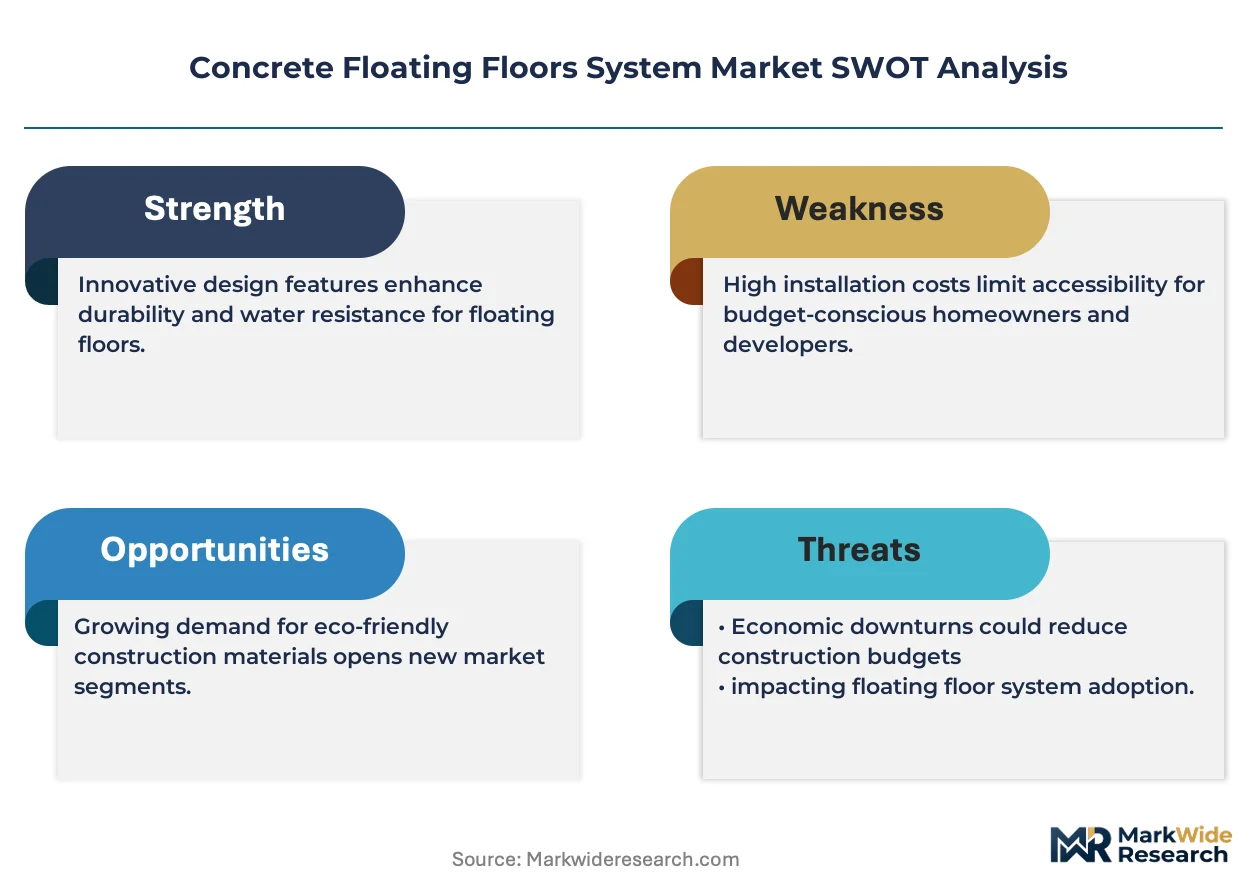
Acoustic decoupling requirements in urban media infrastructure are forcing specification upgrades across cinema, broadcast, and residential retrofit segments. Germany's DIN-standard enforcement and the United Kingdom's building safety regulations are compressing contractor qualification timelines.
Growth Catalysts
- Broadcast infrastructure expansion:Cinema and studio construction in Germany and the United Kingdom demands impact sound reduction exceeding 25 dB. CE marking under the EU Construction Products Regulation mandates resilient bearing performance declarations.
- Energy code tightening:Germany's updated building energy codes accelerate insulated floating floor specifications in multi-unit residential towers. Thermal bridging penalties drive decoupled slab adoption.
- Urban retrofit density:Media district revitalization in Manchester, Berlin, and Los Angeles concentrates demand for rapid-install precast systems where speed governs contractor selection.
Market Restraints
- Cementitious input volatility:Carbon-accounting rules for cement content threaten to recast material cost structures. Suppliers face margin compression from embodied carbon tracking requirements.
- Spring isolator supply concentration:Precision-engineered component manufacturing clusters in Central Europe. Geographic concentration creates vulnerability for broadcast infrastructure timelines.
- Site-cast labor dependency:Traditional poured-in-place systems require skilled acoustic installation crews. Labor scarcity in Germany and the United Kingdom extends project durations.
Strategic Opportunities
- Modular residential penetration:Factory-controlled tolerance systems capture specification share in repetitive floor plate towers. United States multi-family construction rewards standardized assemblies.
- Healthcare vertical expansion:Elastomeric bearing adaptations for laboratory and hospital isolation create margin pools. Vibration-sensitive equipment rooms demand specialized decoupling.
- Recycled aggregate binders:Green building certification thresholds in Northern Europe favor sustainable formulations. LEED and BREEAM point systems incentivize low-carbon cementitious alternatives.
Industry Challenges
- Acoustic engineering talent scarcity:Vibration isolation design expertise concentrates among aging specialist consultancies. Knowledge transfer gaps threaten quality assurance in complex broadcast installations.
- Multi-certification burden:Projects require simultaneous CE marking, DIN-standard testing, and EPA noise guideline compliance. Documentation timelines extend bidding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Floating Floors System Market |
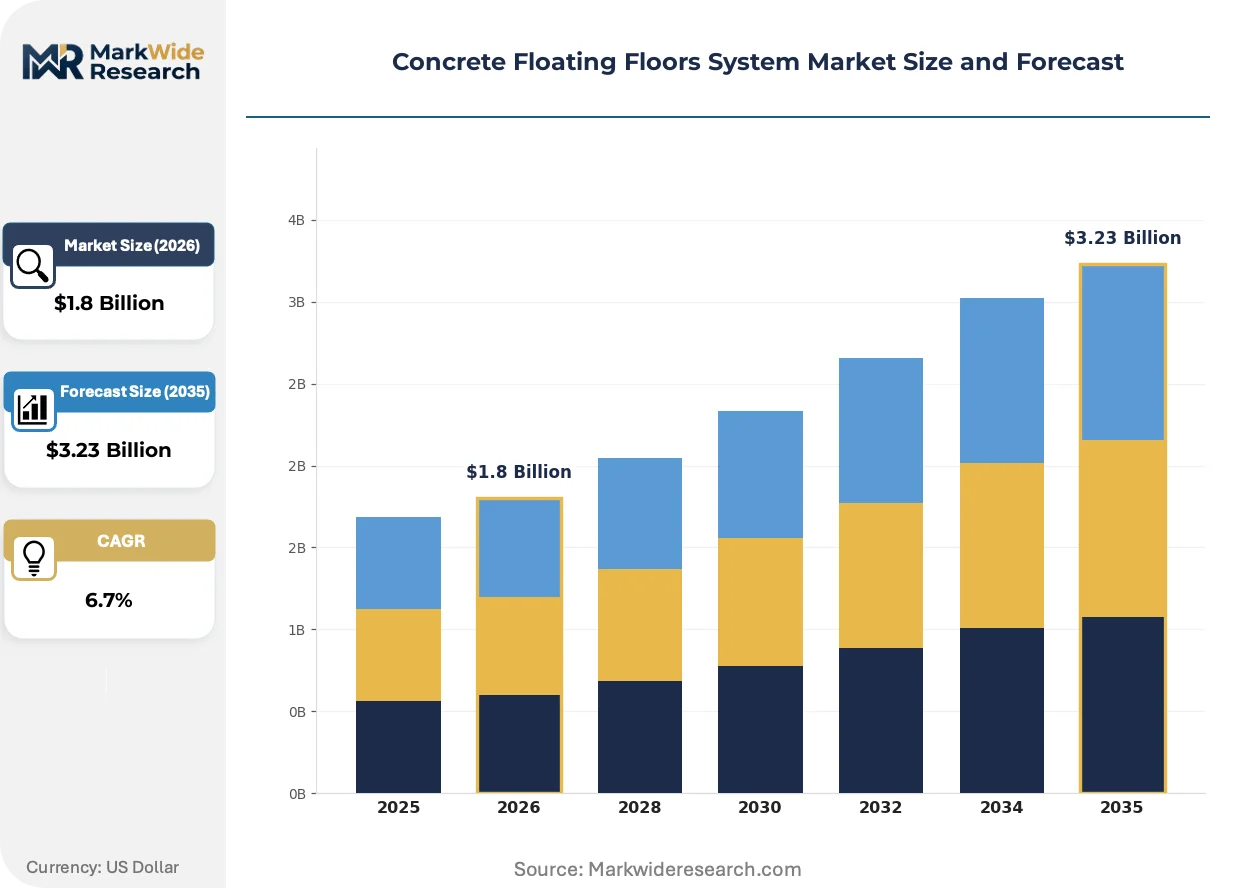
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precast, Insulated, Reinforced, Lightweight Application: Residential, Commercial, Industrial, Institutional Technology: 3D Printing, Traditional, Sustainable, Modular End User: Builders, Architects, Contractors, Homeowners |
| Companies Covered | Farrat Isolevel Ltd., Geoplast S.p.A, Swegon Group AB, Embelton Ltd., GERB Schwingungsisolierungen GmbH & Co., Kinetics Noise Control, Inc., Mason Industries Inc., Total Vibration Solutions Limited, Merlin Integrated Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Floating Floors System Market Emerging Trajectories
Specification authority is migrating from general contractors to acoustic engineering consultancies. Material science advances and regulatory carbon tracking are compressing traditional installation methods.
Precast concrete floating floor technology is migrating from commercial retrofit dominance into multi-unit residential specification. Factory-cured panels with integrated resilient bearings reduce site labor by eliminating field-cast curing periods. Developers in Berlin and Manchester are adopting these systems where construction speed determines project financing viability.
REACH and the EU Green Deal are tightening embodied carbon disclosure requirements for cementitious construction products. Suppliers must now document cradle-to-gate emissions for CE marking compliance. German public cinema tenders already filter submissions based on verified environmental product declarations.
Acoustic engineering consultancies are displacing traditional distributor networks as the primary specification gatekeeper. Manufacturers now bypass intermediaries to serve design firms directly with performance guarantees. This channel compression is most visible in United Kingdom broadcast studio projects where KBA and regional building control offices enforce strict isolation testing protocols.
Concrete Floating Floors System Market Segmentation
Segmentation in concrete floating floors reveals how specification authority, installation speed, and acoustic performance requirements reshape procurement patterns across construction verticals. Distinct product categories serve divergent project timelines, while application splits expose where decoupling standards tighten fastest.
Product Type:
Precast systems compress installation cycles from weeks to days, while site-cast alternatives extend timelines but offer geometric flexibility for complex footprints.
- Precast:Factory-cured panels with integrated resilient bearings eliminate field curing periods entirely. Demand concentrates in Manchester and Berlin media districts where construction speed determines project financing viability and retrofit windows are narrow.
- Insulated:Thermal-decoupled assemblies combine acoustic bearings with rigid insulation boards to address energy code bridging penalties. Germany's updated building energy codes are accelerating specifications in multi-unit residential towers where thermal performance and impact sound reduction must coexist.
- Reinforced:Steel-reinforced slabs tolerate heavier point loads for broadcast infrastructure and concert venues. Specification volumes track cinema construction permits in Germany and the United Kingdom.
- Lightweight:Reduced-density formulations using expanded clay or recycled aggregates lower structural dead loads for existing building retrofits. Manchester and Los Angeles urban media districts favor these where floor loading capacity is constrained.
Precast dominates installed base in commercial retrofit. Insulated is where expansion concentrates as energy code tightening accelerates across Northern Europe.
Application:
Cost tier stratification separates premium acoustic specifications from commodity thermal decoupling, with institutional projects commanding performance guarantees that residential developers rarely require.
- Commercial:Cinema, broadcast studio, and office fit-outs demand impact sound reduction exceeding 25 dB with documented test certificates. Germany's KBA and United Kingdom building control offices enforce DIN-standard protocols that filter non-compliant suppliers from public tenders.
- Residential:Multi-unit towers reward repetitive floor plates where modular technology segments capture specification share. Factory-controlled tolerances reduce acoustic variation between units, critical for developer warranty exposure.
- Industrial:Vibration-sensitive manufacturing and laboratory environments require precision-engineered spring isolator systems. Supply concentrates with Central European specialists serving pharmaceutical and semiconductor cleanroom construction.
- Institutional:Healthcare and education projects combine acoustic isolation with infection control and durability requirements. Mason Industries extends elastomeric bearing portfolios into hospital isolation rooms where equipment vibration threatens diagnostic accuracy.
Commercial commands premium pricing tiers. Residential is climbing the fastest as urban density intensifies and retrofit activity expands.
Technology:
Volume concentration favors established methods, while emerging fabrication approaches target margin pools in certification-driven segments.
- Traditional:Poured-in-place systems with field-installed resilient bearings remain default for irregular geometries. Labor scarcity in Germany and the United Kingdom extends project durations and compresses contractor margins.
- Modular:Factory-assembled floor cassettes with pre-integrated bearings slash site labor and accelerate tower construction. United States multi-family construction rewards standardized assemblies where repetitive floor plates dominate.
- Sustainable:Recycled aggregate binders and low-carbon cementitious formulations target LEED and BREEAM point systems. Northern European green building certification thresholds harden fastest, creating margin pools for verified environmental product declarations.
- 3D Printing:Additive manufacturing of complex bearing geometries and topology-optimized slab sections remains pre-commercial. Early trials focus on bespoke broadcast studio installations where acoustic performance justifies prototyping costs.
Traditional methods retain volume leadership. Modular is where specification share shifts most rapidly as developer timelines compress.
End User:
Customer type determines whether procurement flows through distributor networks or direct manufacturer relationships, with specification authority migrating toward acoustic engineering consultancies.
- Builders:Volume purchasers of precast and modular systems for multi-unit residential towers. Procurement patterns favor standardized assemblies with performance guarantees that reduce site risk.
- Architects:Specification gatekeepers in broadcast and cinema projects who mandate acoustic test certificates and CE marking compliance. Channel compression is most visible as manufacturers bypass intermediaries to serve design firms directly.
- Contractors:Installation speed governs selection in commercial retrofit where liquidated damages clauses penalize schedule overruns. Precast systems reduce crew size and eliminate curing-period weather risk.
- Homeowners:Niche demand for basement home theater and music room isolation. Specification relies on acoustic engineering consultancies rather than general contractor recommendations.
Builders move the highest volume. Architects is where margin expansion concentrates as specification authority centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA anchors the regulatory framework for acoustic isolation standards across European cinema and broadcast construction. CE marking under the EU Construction Products Regulation governs structural bearing performance declarations. Regional demand concentrates in urban media districts undergoing intensive retrofit activity.
Germany
Cinema construction permits and broadcast studio expansion in Berlin and Munich drive specification volumes for impact sound reduction exceeding 25 dB. DIN-standard acoustic testing protocols enforced by the KBA and regional building control offices filter non-compliant suppliers from public tenders. The Berlin-Brandenburg media cluster concentrates demand for rapid-install precast systems where narrow retrofit windows govern contractor selection.
United Kingdom
Building safety regulations compress contractor qualification timelines while Manchester and London media districts revitalize with acoustic decoupling upgrades. United Kingdom building control offices enforce strict isolation testing protocols that elevate specification authority toward acoustic engineering consultancies. The Manchester urban core favors lightweight floating floor formulations where existing building floor loading capacity constrains design options.
United States
EPA noise pollution guidelines influence federal facility specifications while Los Angeles media district revitalization concentrates demand for precast systems. Multi-family residential construction rewards modular technology segments with repetitive floor plates that reduce acoustic variation between units. The Los Angeles urban core sees liquidated damages clauses penalizing schedule overruns, accelerating precast adoption.
France
Public cinema infrastructure investment and broadcast facility modernization in Paris and Lyon intensify demand for precision-engineered isolation systems. ANSM and CNIL oversight of technical standards intersects with CE marking requirements for construction products entering French tenders. The Île-de-France media cluster exhibits procurement patterns favoring standardized assemblies with performance guarantees that reduce site risk exposure.
Italy
Historic building retrofit constraints in Milan and Rome favor lightweight floating floor systems with reduced structural dead loads. Geoplast S.p.A anchors domestic supply chains serving commercial and institutional verticals where geometric flexibility competes with installation speed. The Lombardy construction cluster demonstrates specification migration toward factory-controlled tolerance systems in multi-unit residential towers.
Concrete Floating Floors System Market Vendor Landscape
Vibration isolation specialists and construction materials conglomerates split the market between premium engineered components and volume precast supply. The vendor base concentrates among Central European precision manufacturers and North American acoustic engineering houses. Three archetypes dominate: spring isolator precision engineers, elastomeric bearing system integrators, and modular precast fabricators. Capacity expansion into recycled aggregate formulations and direct-to-consultancy channel compression represent the dominant competitive moves reshaping procurement relationships.
Among Germany-based precision engineers, GERB Schwingungsisolierungen GmbH & Co. occupies a position exemplifying the spring isolator archetype for broadcast infrastructure. Kinetics Noise Control, Inc. and Mason Industries Inc. anchor the North American tier, representing the elastomeric bearing system integration model. Farrat Isolevel Ltd. sits within the United Kingdom specialist cluster where acoustic engineering consultancies displace traditional distributor networks as specification gatekeepers.
| Leading Market Players |
|---|
| Farrat Isolevel Ltd. |
| Geoplast S.p.A |
| Swegon Group AB |
| Embelton Ltd. |
| GERB Schwingungsisolierungen GmbH & Co. |
| Kinetics Noise Control, Inc. |
| Mason Industries Inc. |
| Total Vibration Solutions Limited |
| Merlin Integrated Solutions, Inc. |
| Others |
Supply Flow & Price Mechanics
Carbon-accounting disclosure mandates for cementitious content function as a dual regulatory chokepoint that widens pricing spreads between verified low-carbon systems and commodity alternatives while forcing supply chain reconfiguration toward Northern European aggregate suppliers with environmental product declaration capabilities.
Pricing Analysis
Configured-to-order pricing for precision-engineered spring isolator systems commands substantial premiums over standard elastomeric bearing assemblies. Three-tier pricing structure across premium, standard, and economy levels segments the market: premium tiers attach to DIN-standard certified installations for German cinema infrastructure, standard tiers serve United Kingdom residential retrofit, and economy tiers address volume precast for United States multi-family towers. Pricing pressure stems from embodied carbon tracking requirements that compress margins on high-cement formulations. Residential developers exhibit highest price sensitivity, while broadcast studio architects prioritize performance guarantees over unit cost.
Supply Chain Analysis
Upstream feedstock for resilient bearings draws from specialized steel spring manufacturing in Germany, synthetic elastomer compounding in the United States, and recycled aggregate processing in the United Kingdom. Cement and precast concrete fabrication concentrates in Germany, the United Kingdom, and Italy. Single-source vulnerability clusters around precision-engineered spring isolator supply from Central European specialists. Distribution runs through acoustic engineering consultancies that displace traditional distributor networks as specification gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. DIN-standard certification and CE marking compliance create switching costs that lock specification authority with established suppliers.
For Market Incumbents: Pre-empt margin erosion from carbon-accounting rules by accelerating backward integration into recycled aggregate supply chains and securing environmental product declaration capabilities before green building certification thresholds harden further. Capacity addition in Manchester and Berlin media districts captures retrofit density concentration. Certification investment in low-carbon cementitious formulations defends position against emerging sustainable technology entrants.
For New Entrants and Emerging Players: Mid-market commercial buildings in France and Italy represent the most penetrable entry point where ANSM oversight intersects with less stringent acoustic testing protocols than German KBA enforcement. Healthcare vertical expansion into hospital isolation rooms offers secondary white-space with vibration-sensitive equipment room demand. Direct-to-consultancy channel compression bypasses entrenched distributor relationships that incumbents dominate.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-engineered component specialists with captive acoustic engineering talent. Long-term viability hinges on carbon-accounting rule evolution rather than cyclical construction demand. Acquisition target archetype: mid-cap spring isolator manufacturers with DIN-standard testing infrastructure. The signal to watch is German public tender filtration rates based on verified environmental product declarations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Aggregate Supply | Environmental product declaration capabilities secure German public cinema tender eligibility under tightening EU Green Deal thresholds. |
| Direct-to-Consultancy Channel Compression | Bypassing distributor networks captures specification authority as acoustic engineering consultancies displace traditional intermediaries. |
| Modular Technology Segment Expansion | Factory-controlled tolerance systems reduce acoustic variation between units in United States multi-family towers. |
| Healthcare Vertical Penetration | Hospital isolation room specifications create margin pools where equipment vibration threatens diagnostic accuracy. |
| Low-Carbon Cementitious Formulation R&D | LEED and BREEAM point systems incentivize sustainable technology segments in Northern Europe. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with acoustic engineering consultants, precast concrete fabricators, broadcast studio construction managers, and building control office inspectors. Secondary validation drew from CE marking compliance databases, DIN-standard acoustic test certificates, German KBA tender documentation, EPA noise pollution guidelines, and EU Construction Products Regulation filings. Bottom-up project pipeline analysis across Berlin, Manchester, and Los Angeles media districts triangulated with top-down construction permit data.
Calibration against historical specification volumes and acoustic performance testing records anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application vertical, technology tier, and end-user procurement channel. CAGRs derived from regression analysis of cinema construction permits, broadcast infrastructure investment cycles, and multi-unit residential tower completions. Industry-specific forecast inputs incorporated energy code tightening trajectories and carbon-accounting rule implementation timelines.
Practitioners should monitor German KBA tender filtration criteria and United Kingdom building safety regulation amendments for early signals of specification authority migration. Forecasts reflect assumptions regarding retrofit window availability in urban media districts and labor scarcity persistence in acoustic installation crews. Quarterly review of CE marking compliance rates and environmental product declaration verification volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Masonry Sealers Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
EPS Sandwich Panels Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Asia-Pacific Particle Board Market