
 GCC Concrete Blocks Market | 2026-2036
GCC Concrete Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Concrete Blocks Market Foresight
Buyer concentration among Saudi giga-project developers is rebalancing procurement volumes toward bundled, long-term supply agreements. ACICO Group leverages its integrated manufacturing footprint across Kuwait and Saudi Arabia to secure these multi-year contracts. Al Jazeera Factory For Construction Materials anchors its position through specialized hollow block production tailored to high-rise specifications. ESPAC competes on rapid fulfillment capabilities for infrastructure timelines.
Concrete blocks are masonry units manufactured from Portland cement, aggregates, and water, formed through vibration compaction or autoclaved curing to achieve compressive strengths ranging from 7 to 35 MPa depending on grade and intended structural duty. Hollow blocks containing 25-50% void ratio dominate residential and commercial vertical construction due to their thermal insulation properties and reduced dead load. Solid blocks command premium positioning in load-bearing applications and foundation systems where higher compressive strength is mandatory. Paving blocks represent the fastest-growing product category as municipalities across the GCC expand permeable surface mandates for stormwater management in new districts.
Gulf Standardization Organization (GSO) conformity requirements and Saudi Building Code enforcement by the Saudi Standards, Metrology and Quality Organization (SASO) are elevating minimum block density and dimensional tolerance thresholds. The UAE's updated Fire and Life Safety Code issued by the Ministry of Interior is accelerating demand for fire-rated concrete block assemblies in high-occupancy buildings. Stakeholders must monitor evolving green building rating adoption across Abu Dhabi, Dubai, and Riyadh where embodied carbon thresholds for construction materials are gaining regulatory traction.
Market Dynamics
Saudi giga-project developers are consolidating procurement into multi-year bundled supply agreements, compressing vendor margins while privileging manufacturers with cross-border production footprints and SASO-certified thermal performance testing capabilities.
Growth Catalysts
- NEOM and Qiddiya Infrastructure:Saudi Arabia's giga-developments are generating concentrated demand for fire-rated hollow block assemblies across residential, hospitality, and industrial zones.
- SASO Thermal Compliance:Enforcement of updated Saudi Building Code minimum density thresholds is disqualifying low-grade imports and elevating domestic premium block specifications.
- Permeable Surface Mandates:Municipal stormwater regulations across Dubai, Abu Dhabi, and Riyadh are accelerating specification of interlocking concrete paving blocks in new district developments.
Market Restraints
- Cement Price Volatility:Clinker input costs fluctuate with regional fuel subsidy adjustments and carbon border considerations affecting GCC production economics.
- Kuwait-Saudi Supply Concentration:Integrated manufacturers with cross-border kiln operations control bulk procurement channels, limiting new entrant access to giga-project tenders.
- Autoclaved Aerated Concrete Substitution:Lightweight AAC panels are displacing hollow blocks in select high-rise curtain wall applications where weight reduction is prioritized.
Strategic Opportunities
- Oman Construction Corridor:Duqm Special Economic Zone and Salalah port expansion projects remain underpenetrated by Saudi and UAE block suppliers with established SASO certification.
- Embodied Carbon Tracking:Abu Dhabi's Pearl Rating System and Dubai's Al Sa'fat are mandating lifecycle carbon disclosure for walling materials, creating first-mover advantage for EPD-certified block producers.
- 3D-Printed Block Molds:Convergence of additive manufacturing with traditional vibration compaction is enabling rapid customization of specialized block geometries for complex architectural facades.
Industry Challenges
- Fire-Rating Certification Timelines:UAE Ministry of Interior testing protocols for multi-hour fire-rated block assemblies extend product approval cycles by 8-14 months.
- Kiln Retrofit Capex:Conversion to natural gas firing for SASO emissions compliance requires substantial capital deployment at aging facilities in eastern Saudi Arabia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Concrete Blocks Market |
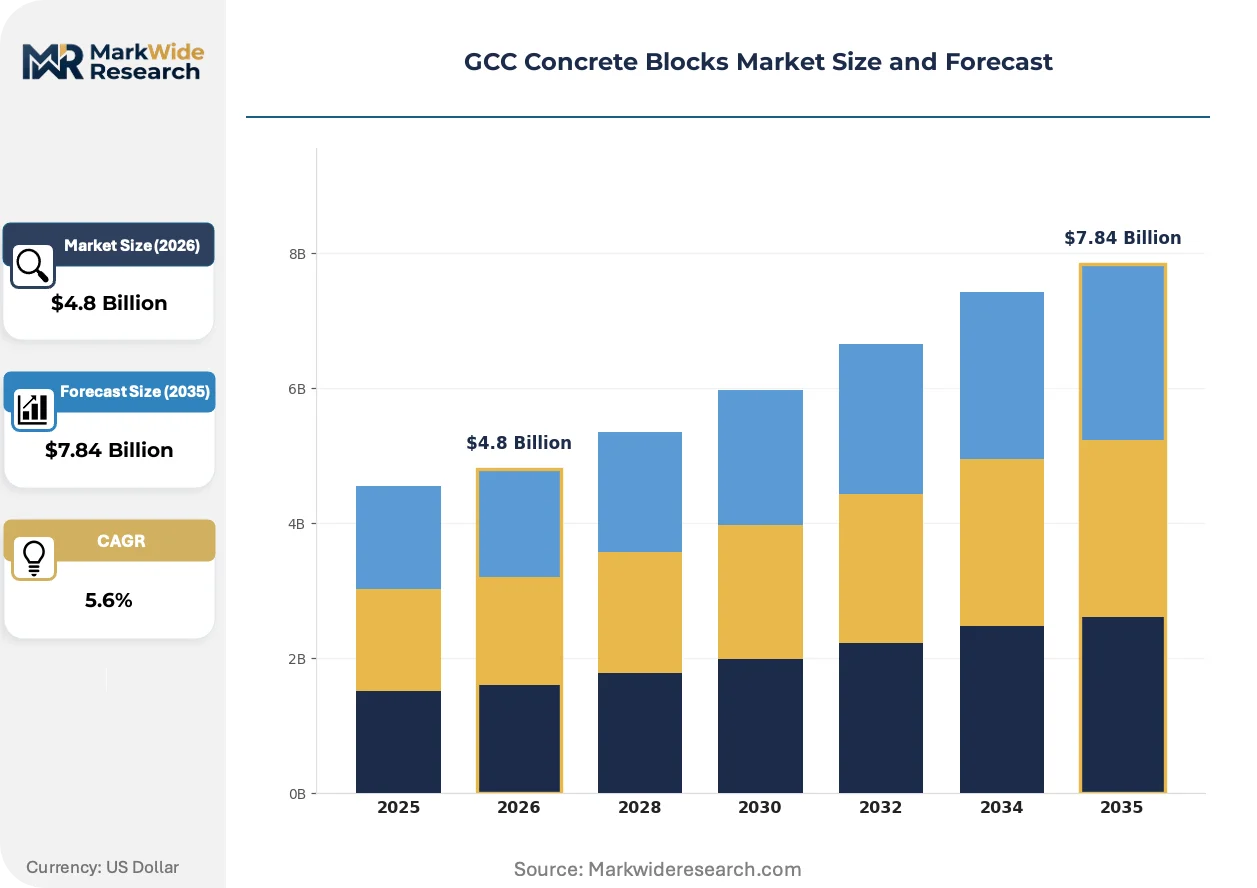
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Blocks, Hollow Blocks, Solid Blocks, Paving Blocks Material: Cement, Fly Ash, Gravel, Recycled Aggregates End User: Residential Construction, Commercial Buildings, Roads, Landscaping Application: Structural, Non-Structural, Interior, Load-Bearing |
| Companies Covered | ACICO Group, Al Jazeera Factory For Construction Materials, ESPAC, Bucomac Industries, MJK Group, Raknor LLC, Aamal Cement Industries, Khonaini International Company, Saudi ReadyMix, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Concrete Blocks Market Shifts & Advancements
Manufacturing automation and regulatory carbon tracking are compressing traditional specification cycles while elevating performance-certified block categories across the Gulf construction corridor.
Geopolymer cement formulations are unifying supplementary cementitious material sourcing with regional industrial waste streams. NEOM contractors are specifying these blends for foundation and below-grade applications where sulfate resistance is mandatory. This unification is collapsing the traditional separation between waste management contracts and construction material procurement.
SASO's 2024 enforcement of Gulf Standardization Organization dimensional tolerance standards is eliminating sub-2mm deviation block imports from non-GCC sources. Saudi project engineers are now rejecting shipments lacking GSO conformity marks at port of entry. High-rise commercial towers in Riyadh and Jeddah are experiencing specification delays as suppliers retool pressing equipment.
Developer-led consolidation of material procurement is compressing distributor margins across the Saudi construction corridor. ACICO and Al Jazeera Factory are securing direct supply relationships with giga-project procurement offices, bypassing traditional merchant distributors. This disintermediation is most visible in the Red Sea coastal developments where logistics integration favors manufacturer-direct delivery models.
GCC Concrete Blocks Market Segmentation
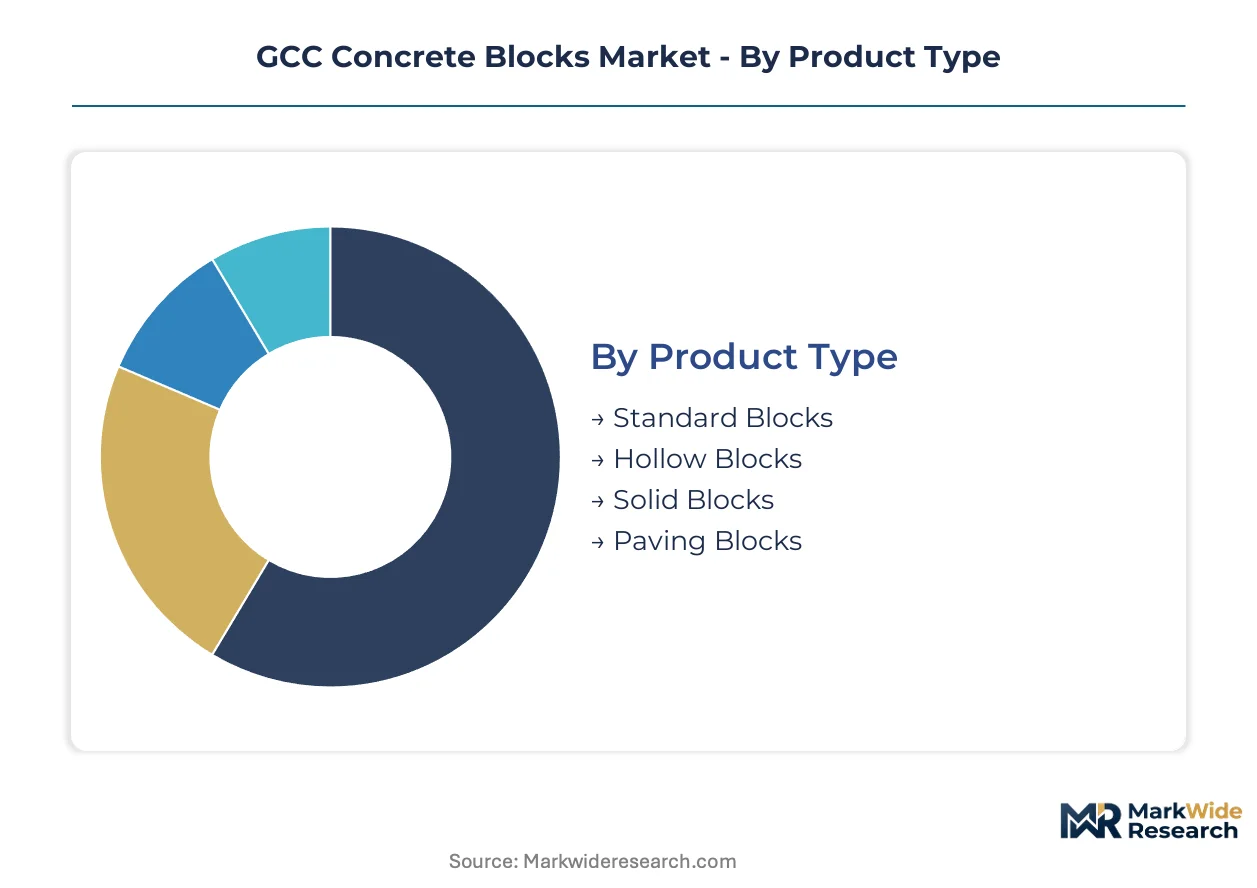
Segmentation in the GCC concrete blocks market tracks how regulatory pressure and project scale reshape procurement patterns. Specification divergence between giga-developments and standard construction creates distinct volume clusters across product categories.
Product Type:
Standardization dominates high-volume infrastructure, while customized geometries capture premium architectural specifications.
- Hollow Blocks:These units contain 25-50% void ratios engineered for thermal insulation and dead-load reduction. Saudi giga-developments at NEOM and Qiddiya are specifying fire-rated hollow block assemblies for residential and hospitality verticals under tightened SASO thermal compliance mandates.
- Paving Blocks:Interlocking permeable units designed for stormwater infiltration and surface drainage. Municipal mandates across Dubai, Abu Dhabi, and Riyadh are accelerating specification of these units in new district developments, making this category expand most quickly among all product types.
- Standard Blocks:General-purpose masonry units for non-specialized walling applications with baseline compressive strength ratings.
- Solid Blocks:Dense units for load-bearing foundations and structural walls where higher compressive strength is mandatory.
Most installed capacity flows through hollow block production lines. Expansion is steepest in paving blocks.
Material:
Input cost volatility and embodied carbon tracking are rebalancing mix ratios toward industrial byproduct substitution.
- Cement:Portland cement remains the primary binder, though clinker input costs fluctuate with regional fuel subsidy adjustments affecting GCC production economics.
- Fly Ash:Pulverized fuel ash from thermal power generation serves as a supplementary cementitious material. NEOM contractors are specifying fly ash blends for foundation applications where sulfate resistance is mandatory under geopolymer formulation trials.
- Gravel:Crushed stone aggregate providing bulk density and compressive strength to block matrices.
- Recycled Aggregates:Construction and demolition waste processed for secondary use in non-structural applications.
Cement retains the dominant share of material input value. Fly ash is gaining share fastest as waste-to-material contracts collapse traditional procurement separations.
End User:
Project scale and procurement consolidation intensity determine margin capture across customer categories.
- Residential Construction:Multi-family and single-family vertical developments across Saudi Arabia's construction corridor. Bundled long-term supply agreements with giga-project developers are compressing distributor margins while privileging manufacturers with cross-border production footprints.
- Commercial Buildings:High-rise towers, retail complexes, and office developments in Riyadh and Jeddah. UAE Ministry of Interior fire-rating protocols are extending product approval cycles for multi-hour rated block assemblies specified in high-occupancy buildings.
- Roads:Highway infrastructure, bridge approaches, and drainage structures requiring durable masonry elements.
- Landscaping:Hardscape elements, retaining walls, and aesthetic masonry for urban green spaces.
Residential construction channels the largest absolute volume. Commercial buildings show the steepest specification upgrade trajectory as codes tighten.
Application:
Structural duty requirements split manufacturing investment between high-strength curing systems and standard vibration compaction.
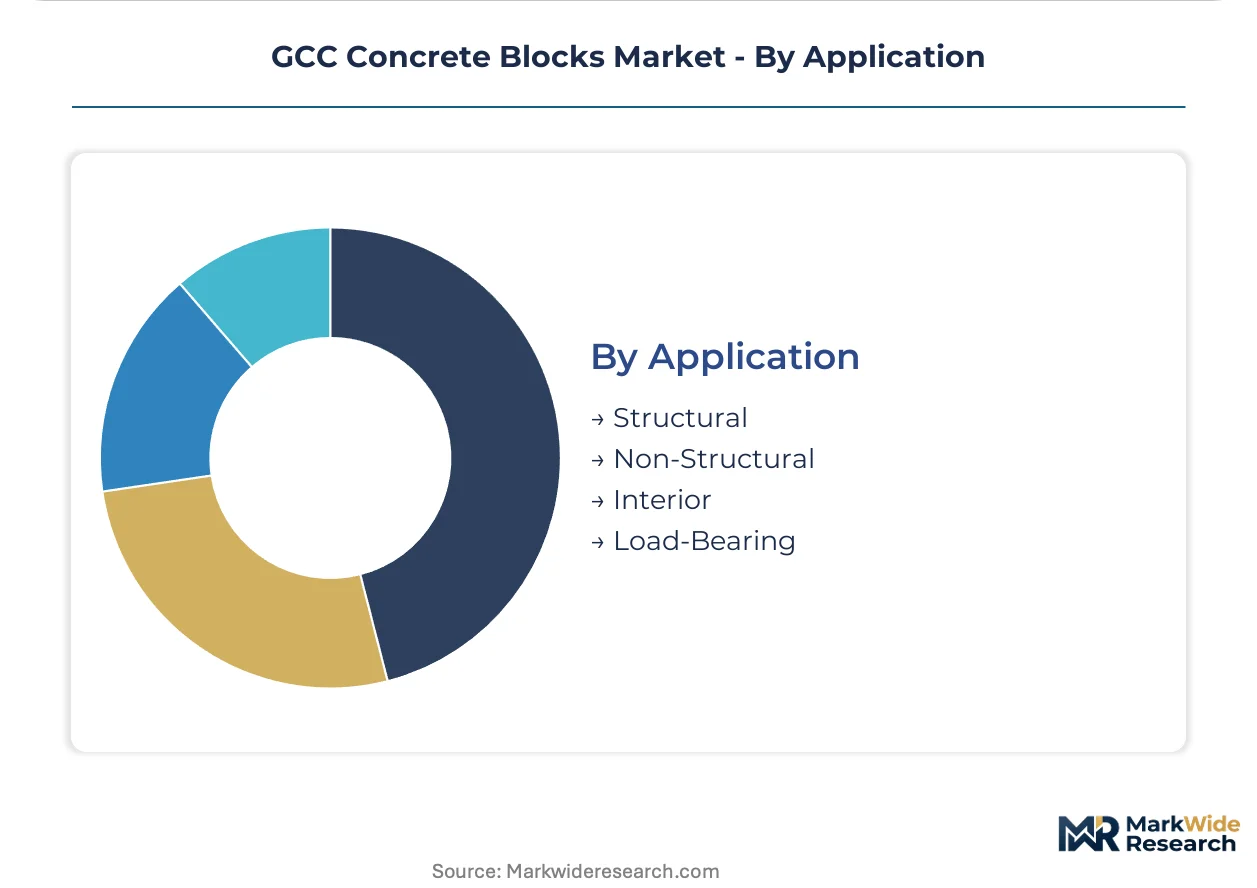
- Load-Bearing:Blocks engineered to carry structural loads above 15 MPa compressive strength, common in foundation systems and low-rise structural walls.
- Structural:General structural duty blocks for framed construction infill and partition walls with moderate strength requirements.
- Non-Structural:Architectural and screening walls without structural duty, permitting lighter density and lower cement content.
- Interior:Finish-quality blocks for exposed wall surfaces requiring tighter dimensional tolerances under GSO conformity standards.
Load-bearing applications command premium positioning. Interior specifications are climbing fastest as GSO dimensional tolerance enforcement eliminates sub-standard imports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands procurement volumes through NEOM and Qiddiya, while the UAE leverages stricter fire codes to elevate block specifications. Kuwait's cross-border manufacturers exploit geographic arbitrage. Oman remains underpenetrated by certified suppliers.
Saudi Arabia
NEOM and Qiddiya giga-developments concentrate demand for fire-rated hollow block assemblies across residential and hospitality verticals. SASO enforces updated Saudi Building Code minimum density thresholds that disqualify low-grade imports. Riyadh, Jeddah, and the Red Sea coast form the construction corridor where bundled long-term supply agreements are compressing distributor margins.
United Arab Emirates
Dubai and Abu Dhabi municipalities are expanding permeable surface mandates for stormwater management in new district developments. The UAE Ministry of Interior's updated Fire and Life Safety Code extends product approval cycles for multi-hour rated block assemblies. High-occupancy towers in Dubai Marina and Abu Dhabi's Al Reem Island are experiencing specification delays as suppliers navigate certification timelines.
Kuwait
Integrated manufacturers with cross-border kiln operations control bulk procurement channels serving Saudi giga-projects. ACICO Group leverages its manufacturing footprint across Kuwait and Saudi Arabia to secure multi-year contracts. The country's producers benefit from geographic proximity to the eastern Saudi construction corridor while maintaining SASO-certified thermal performance testing capabilities.
Oman
Duqm Special Economic Zone and Salalah port expansion projects remain underpenetrated by Saudi and UAE block suppliers with established SASO certification. The country's national standards body has not yet aligned fully with GSO dimensional tolerance requirements. Muscat and the Batinah Coast represent emerging demand clusters where local producers lack scale to serve infrastructure timelines.
Qatar
Post-World Cup infrastructure maintenance and Lusail City completion are sustaining block demand at moderated levels. The country's civil defense authority maintains strict fire-rating protocols for high-occupancy buildings that parallel UAE standards. Doha and Al Wakrah industrial zones host limited domestic block manufacturing, creating import dependence for specialized grades.
GCC Concrete Blocks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers. The vendor base fragments between integrated manufacturers with cross-border footprints and single-facility operators serving municipal infrastructure. Three archetypes dominate: scale-driven conglomerates with cement-to-block vertical control, regional specialists with SASO certification depth, and rapid-fulfillment contractors for infrastructure timelines. Competitive moves concentrate on securing direct supply relationships with giga-project procurement offices and retooling pressing equipment for GSO dimensional compliance.
Among Kuwait and Saudi Arabia-based integrated manufacturers, ACICO Group occupies a position exemplifying cross-border production scale. Al Jazeera Factory For Construction Materials represents the specialized hollow block producer archetype with high-rise specification focus. ESPAC sits within the rapid-fulfillment contractor tier serving compressed infrastructure timelines. These three anchors illustrate how geographic footprint and certification depth determine access to bundled procurement channels.
| Leading Market Players |
|---|
| ACICO Group |
| Al Jazeera Factory For Construction Materials |
| ESPAC |
| Bucomac Industries |
| MJK Group |
| Raknor LLC |
| Aamal Cement Industries |
| Khonaini International Company |
| Saudi ReadyMix |
| Others |
Supply & Pricing Matrix
Cross-border kiln integration across Kuwait and Saudi Arabia anchors both supply security and pricing leverage for block manufacturers serving giga-project procurement offices. This geographic footprint compresses logistics costs while enabling bundled long-term contract structures that lock in volume commitments.
Pricing Analysis
Capacity additions in eastern Saudi Arabia are reshaping price floors for fire-rated hollow block assemblies as domestic producers scale SASO-certified output. Three-tier pricing structure across premium certified, standard grade, and economy imports separates buyers by thermal compliance level and volume scale. Pricing pressure stems from cement clinker cost volatility tied to regional fuel subsidy adjustments. Residential giga-developments show highest price sensitivity due to bundled procurement consolidation, while commercial high-rises absorb premiums for fire-rated certification.
Supply Chain Analysis
Workforce availability constraints in Saudi Arabia's Eastern Province and Kuwait's industrial zones limit kiln expansion velocity despite demand surges. Supply concentrates in Saudi Arabia, Kuwait, and the UAE, with raw material dependencies on Portland cement clinker, fly ash from regional power generation, and crushed limestone aggregate. Single-source vulnerability runs through integrated manufacturers controlling cross-border procurement channels. Distribution runs through manufacturer-direct delivery models to giga-project sites, bypassing traditional merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder underpinned by Saudi Arabia's multi-decade giga-development pipeline and tightening building code enforcement across the GCC.
For Market Incumbents: Acquire underutilized kiln capacity in Oman's Batinah Coast to preempt entrant positioning in the underpenetrated Duqm corridor. Consolidate fly ash sourcing contracts with regional power utilities to secure supplementary cementitious material supply against geopolymer formulation competitors. SASO certification depth remains the critical defensive lever against low-grade import substitution. For New Entrants and Emerging Players: Launch via rapid-fulfillment infrastructure contracting serving compressed timelines in Oman's Salalah port expansion and Qatar's post-World Cup maintenance cycles. Target the Omani market where established SASO-certified suppliers maintain limited presence and local producers lack scale for infrastructure volumes. Position around EPD-certified block production to capture embodied carbon tracking premiums in Abu Dhabi and Dubai green building mandates. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with SASO certification depth because giga-project procurement consolidation favors scaled domestic manufacturers over fragmented import channels. Five-to-ten year viability hinges on regulatory enforcement durability rather than cyclical construction demand. Monitor SASO thermal compliance disqualification rates for low-grade imports as the inflection signal for domestic pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Fire-rated thermal testing capabilities unlock NEOM and Qiddiya bundled contract access. |
| Cross-Border Kiln Expansion | Kuwait-Saudi geographic arbitrage compresses logistics costs for Red Sea coastal deliveries. |
| Fly Ash Supply Integration | Waste-to-material contracts collapse procurement separations and anchor geopolymer blend supply. |
| Oman Market Entry | Duqm and Salalah project timelines lack certified block capacity from established GCC suppliers. |
| EPD Certification Program | Abu Dhabi Pearl Rating and Dubai Al Sa'fat mandates create first-mover carbon disclosure advantage. |
Research Methodology
Coverage spans Saudi Arabia, UAE, Kuwait, Oman, and Qatar, with primary inputs from each construction corridor. The analysis combines interviews with giga-project procurement directors, plant managers at integrated block manufacturers, and technical directors at SASO-certified testing facilities with secondary validation from Gulf Standardization Organization conformity records, SASO enforcement bulletins, and municipal stormwater regulation filings. Bottom-up volume triangulation against top-down construction spend data anchors market sizing.
Rate-of-change decomposition separates volume growth from specification upgrade pricing effects across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-use sector, and structural duty application. CAGRs derive from construction pipeline visibility, regulatory enforcement timelines, and substitution elasticity between block categories. Cement price volatility indices and clinker trade flow data inform cost-side assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt SASO enforcement acceleration or cement subsidy withdrawal scenarios. Forecasts reflect assumptions about giga-project completion sequencing and green building code adoption velocity. Material deviation in NEOM construction pacing or GCC carbon border implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
Sliding Bearing Market