
 Pipeline Installation Services Market | 2026-2036
Pipeline Installation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Installation Services Market Analytics
The shift from single-source to multi-source contracting for complex pipeline projects is broadening the competitive field for international installation contractors. Saipem S.p.A. leverages its integrated engineering and construction capabilities to anchor large-diameter subsea and onshore projects across multiple continents. TechnipFMC plc differentiates through its proprietary reel-lay and rigid pipeline technologies that reduce offshore installation timelines. McDermott International sustains a dominant fabrication and marine installation footprint in the Middle East and Asia-Pacific basins.
Pipeline installation services encompass the engineering, procurement, construction, and commissioning of conduit systems for hydrocarbon, water, and industrial fluid transport, typically involving steel pipe diameters from 4 inches to 48 inches with wall thicknesses engineered to withstand internal pressures exceeding 1,440 psi and external hydrostatic loads. Trenching and directional drilling command the largest service-type revenue pools due to their applicability across terrain-constrained onshore corridors and environmentally sensitive crossings. Subsea installation methods represent the fastest-growing installation-method category, driven by deepwater field developments in Brazil, West Africa, and the eastern Mediterranean. Mega projects absorb disproportionate planning and capital resources, though medium-scale pipelines deliver more predictable margins and faster cycle times for contractors.
The Pipeline and Hazardous Materials Safety Administration governs onshore safety standards in the United States, while the Bureau of Safety and Environmental Enforcement oversees offshore construction compliance, and the International Maritime Organization regulates vessel-based pipe-lay operations through its SOLAS and MARPOL conventions. These frameworks elevate insurance, inspection, and documentation costs, effectively filtering marginal contractors from high-stakes project bidding. Stakeholders must monitor regulatory harmonization pressures between national pipeline codes and emerging carbon-accounting standards that could reshape material selection and welding qualification protocols.
Market Dynamics
Deepwater field developments in Brazil, West Africa, and the eastern Mediterranean are compressing project timelines and forcing installation contractors to reconfigure vessel fleets and welding protocols for high-pressure, high-temperature subsea environments.
Growth Catalysts
- Offshore decommissioning mandates:The Bureau of Safety and Environmental Enforcement in the United States requires full pipeline removal at end-of-life, generating recurring installation demand for replacement infrastructure.
- Hydrogen blending infrastructure:Steel pipeline networks rated for 1,440 psi internal pressure are being retrofitted for hydrogen-natural gas mixtures across European industrial corridors.
- Arctic corridor development:Permafrost-specific trenching technologies are unlocking onshore routes through northern Canada and Russia previously deemed unconstructable.
Market Restraints
- Specialized vessel scarcity:Heavy-lift pipe-lay vessels capable of operating below 3,000 meters water depth concentrate among a handful of North Sea and Asian fleet operators.
- Alloy steel price volatility:High-grade chromium-molybdenum pipe stocks fluctuate with nickel futures, compressing fixed-bid margins for EPC contractors.
- Extended permitting cycles:The Pipeline and Hazardous Materials Safety Administration's environmental review timelines for cross-state corridors now routinely exceed 36 months.
Strategic Opportunities
- Carbon capture transport networks:The United States Inflation Reduction Act subsidizes CO2 pipeline construction, creating dedicated installation demand from ethanol plants to sequestration basins.
- Modular micro-pipeline systems:Standardized 4- to 12-inch diameter skids for remote mining and agricultural water transport bypass traditional EPC bidding cycles.
- Digital twin integration:Real-time sensor fusion during installation is absorbing quality assurance costs previously borne through post-construction hydrostatic testing.
Industry Challenges
- Subsea welding technician shortages:Saturated diving schools cannot produce hyperbaric-qualified welders fast enough to crew expanding vessel fleets.
- Legacy GIS data incompatibility:Decades-old pipeline route records in paper format obstruct robotic inspection integration and integrity management automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Installation Services Market |
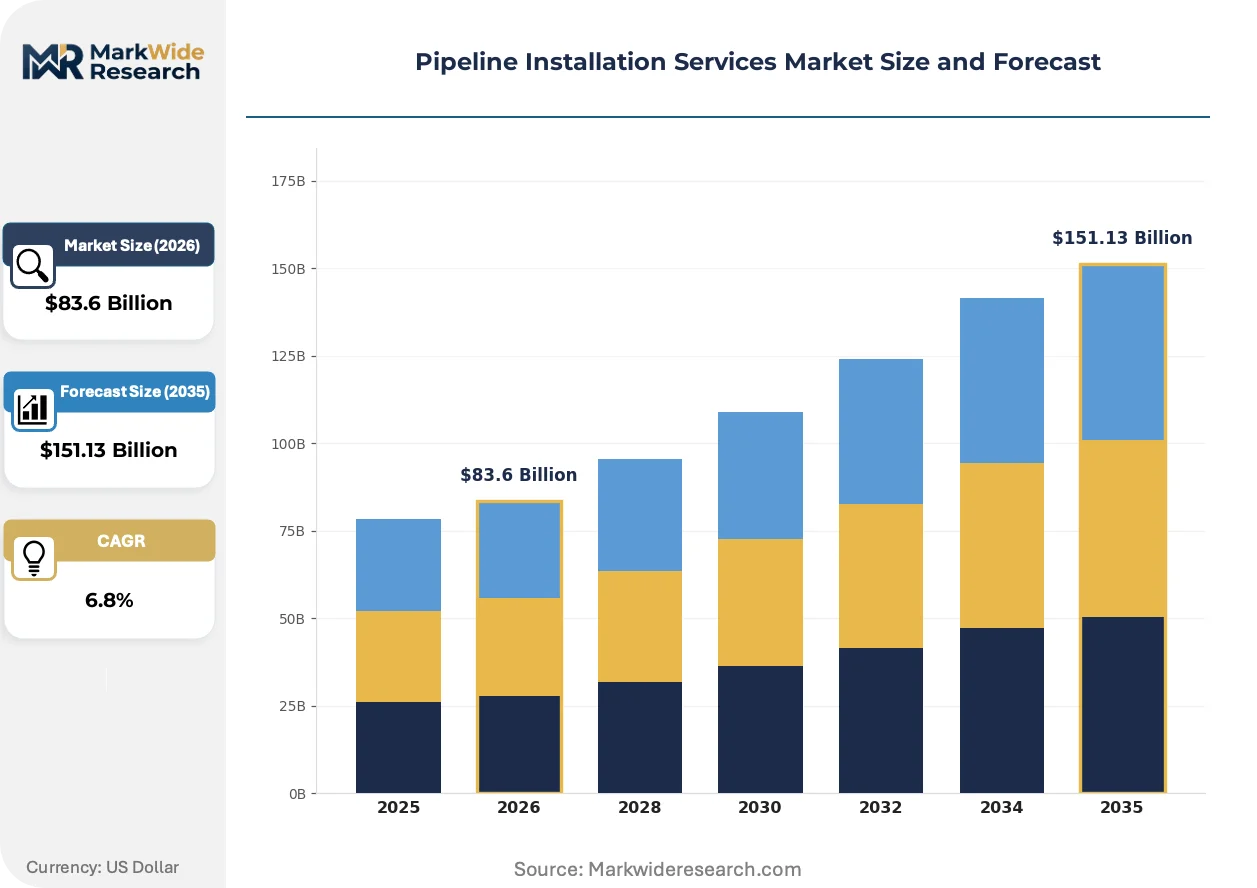
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $151.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Trenching, Directional Drilling, Open Cut, Auger Boring End User: Oil & Gas Companies, Water Utilities, Construction Firms, Industrial Plants Installation Method: Above Ground, Below Ground, Subsea, Hybrid Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Saipem S.p.A., Subsea 7 S.A., TechnipFMC plc, McDermott International, John Wood Group PLC, China Petroleum Pipeline Engineering Co., Ltd., Halliburton Company, Baker Hughes Company, Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Installation Services Market Evolving Landscape
Reel-lay vessel automation and composite material pipelines are compressing offshore construction windows while regulatory carbon-accounting requirements reshape material procurement specifications across all pressure ratings.
Composite reinforced thermoplastic pipe is absorbing installation cost premiums previously accepted for corrosion-resistant alloy steel in sour gas applications. ADNOC and Saudi Aramco are qualifying these systems for 2,000-meter water depths at accelerated schedules. The technology is absorbing market share from rigid steel in tieback applications where weight constraints dominate vessel selection.
The European Union's Carbon Border Adjustment Mechanism is forcing EPC contractors to document embodied carbon in steel pipe sourcing. Procurement departments now require mill certificates tracing blast furnace emissions through integrated steelworks in India and China. German and Dutch installation contractors are responding by qualifying electric arc furnace producers with renewable power purchase agreements.
Integrated service contracts bundling engineering, installation, and decades-long integrity management are displacing discrete construction-only bidding. National oil companies in the Middle East favor single-accountability structures that transfer operational risk to contractors. This consolidation is most visible in Abu Dhabi's long-term pipeline maintenance frameworks where Saipem and TechnipFMC now compete on lifecycle cost models rather than upfront capital expenditure.
Pipeline Installation Services Market Segmentation
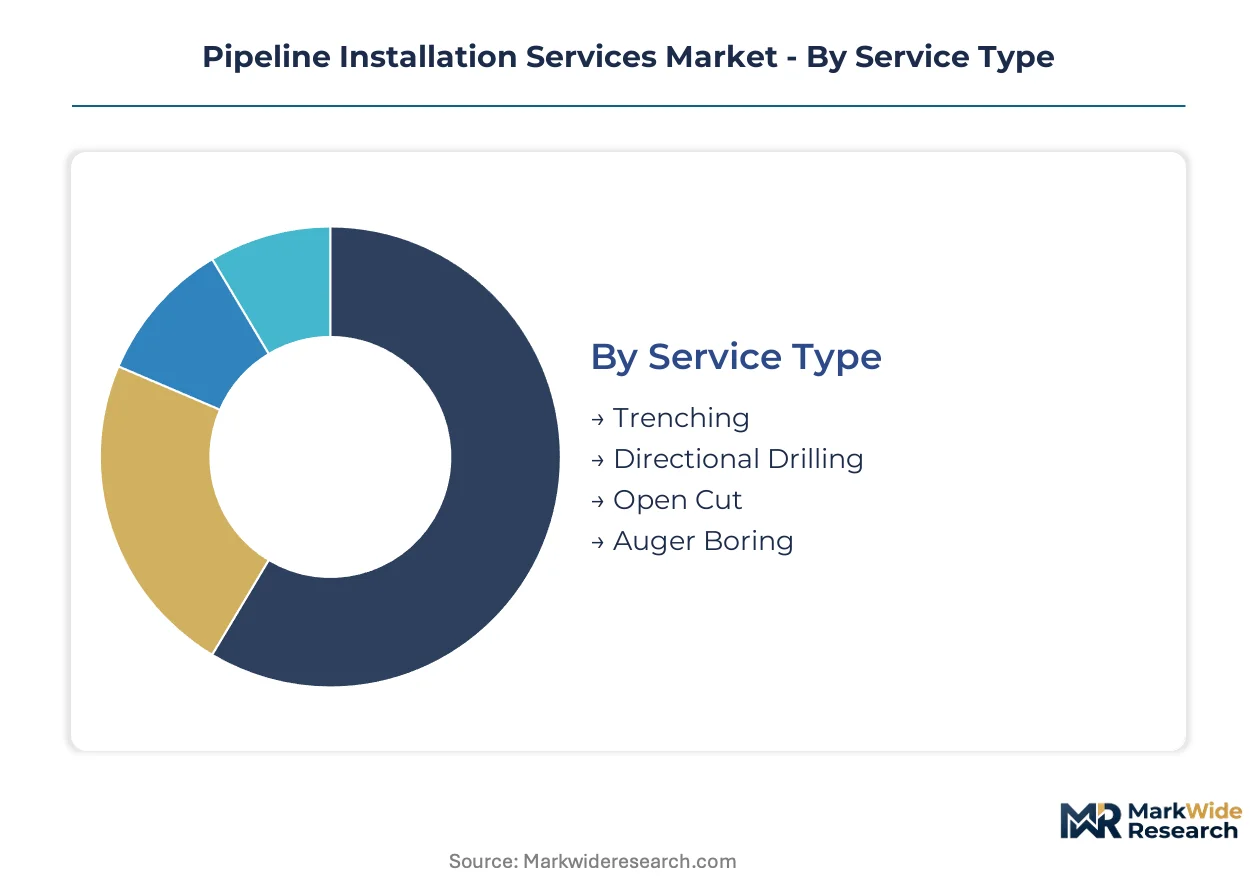
Pipeline installation contractors configure equipment fleets and crew specializations around distinct technical requirements across service types, end users, and installation environments. Segmentation reveals where capital deployment concentrates and which contract structures yield sustainable margins.
Service Type:
Standardized trenching methods compete with bespoke directional drilling solutions across terrain and regulatory constraints.
- Trenching:Conventional excavation using backhoes and trenchers for onshore corridors with minimal subsurface interference. Saudi Aramco and ADNOC deploy continuous trenching spreads across desert terrain where rock hardness permits high daily progress rates.
- Directional Drilling:Steerable horizontal drilling beneath rivers, roads, and environmentally sensitive zones without surface disruption. Demand concentrates in the United States where the Pipeline and Hazardous Materials Safety Administration mandates minimal-impact crossings under wetlands and urban infrastructure.
- Open Cut:Direct excavation through paved surfaces and shallow soil profiles for distribution networks and utility tie-ins. Water utilities in Germany and the Netherlands favor open cut for aging cast-iron replacement programs in dense urban grids.
- Auger Boring:Dry excavation through cohesive soils using rotating helical screws for short-distance utility crossings. Mining operations in Western Australia apply auger boring for dewatering pipeline installation beneath haul roads without traffic interruption.
Leading the category by volume: Trenching. Growing fastest: Directional Drilling.
End User:
Capital intensity and contract duration separate hydrocarbon infrastructure from municipal utility procurement.
- Oil & Gas Companies:Long-cycle projects with engineering-procurement-construction contracts spanning fabrication through commissioning. Brazil's Petrobras and Norway's Equinor drive subsea installation demand for pre-salt and North Sea field developments.
- Water Utilities:Municipal procurement with segmented design-bid-build structures and public funding constraints. The United States Environmental Protection Agency's lead service line replacement mandates are accelerating trenchless renewal contracts across Midwestern states.
- Construction Firms:Project-specific subcontracting for building services and site infrastructure. High-rise developers in Singapore and Dubai specify modular riser installation for chilled water and fire suppression systems.
- Industrial Plants:Process piping within refineries, chemical complexes, and power generation facilities. German chemical producers at BASF's Ludwigshafen complex require specialized alloy welding for high-temperature steam lines.
Dominating contract value: Oil & Gas Companies. Expanding most quickly: Water Utilities.
Installation Method:
Above-ground simplicity yields to subsea complexity as water depth and pressure ratings escalate.
- Above Ground:Elevated piping on supports and racks for process plants, loading terminals, and temporary construction lines. Permafrost regions in northern Canada favor above-ground installation to avoid thermal degradation of buried infrastructure.
- Below Ground:Buried pipelines with cathodic protection for long-distance transmission and distribution networks. The United States interstate natural gas system relies on below-ground installation for corridor efficiency and agricultural land preservation.
- Subsea:Submerged pipelines requiring specialized lay vessels, hyperbaric welding, and trenching for stability. West Africa's deepwater developments off Angola and Nigeria compress installation windows through reel-lay automation.
- Hybrid:Combinations of above-ground, buried, and subsea sections for complex route topography. Eastern Mediterranean gas export projects from Israel's Leviathan field traverse onshore, nearshore, and deepwater zones within single pipeline systems.
Highest capital absorption: Subsea. Steepest expansion trajectory: Hybrid.
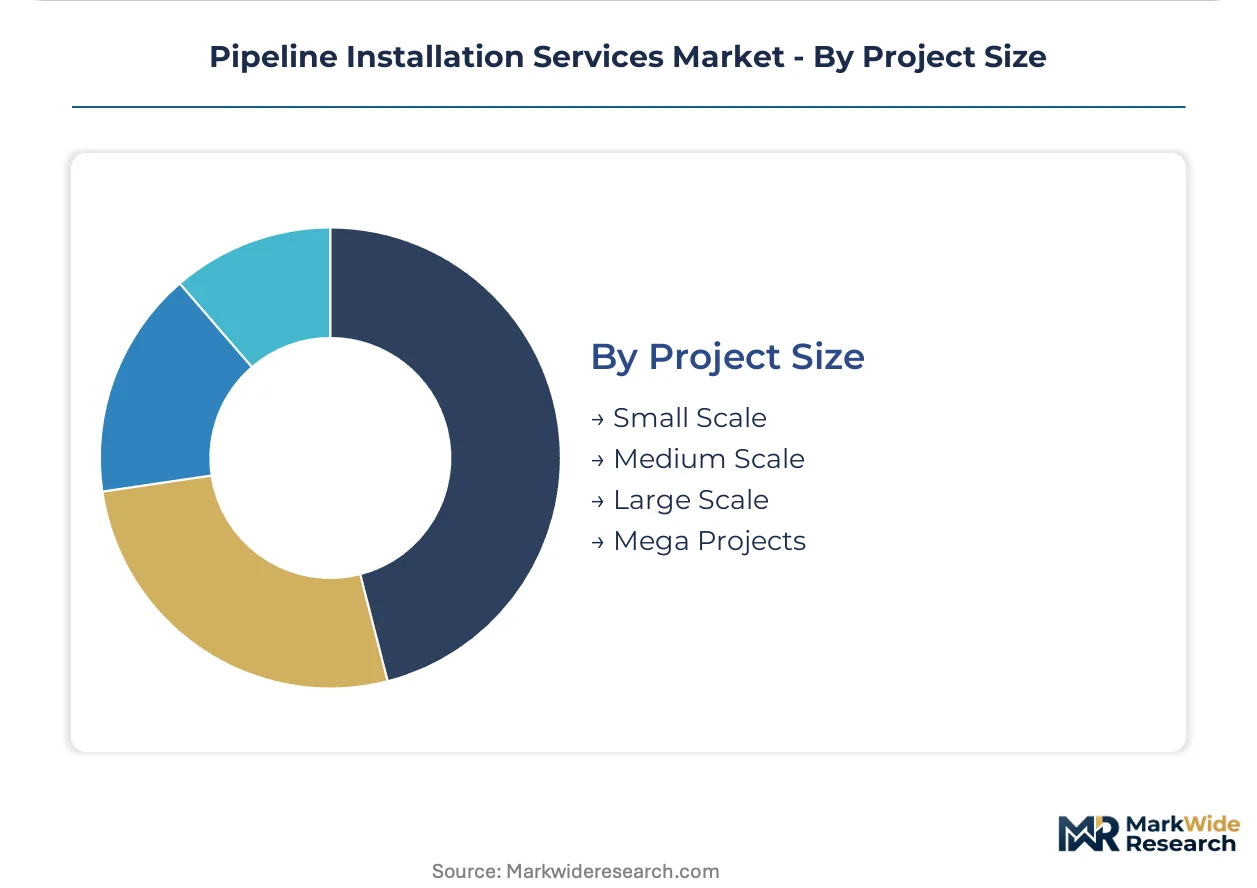
Project Size:
Margin predictability inversely correlates with project scale and stakeholder complexity.
- Small Scale:Local distribution extensions and service connections under $10 million contract value. Rural water cooperatives in Texas and Oklahoma procure small-scale installation through regional contractors with minimal bonding requirements.
- Medium Scale:Regional transmission lines and industrial park infrastructure with defined scopes and faster cycle times. Japanese steel mills at Nippon Steel's Nagoya works commission medium-scale oxygen pipeline replacement on 18-month schedules.
- Large Scale:Cross-country trunk lines and offshore field developments with multi-year execution. The East African Crude Oil Pipeline from Uganda to Tanzania exemplifies large-scale onshore installation across varied terrain and regulatory jurisdictions.
- Mega Projects:Transcontinental systems and integrated LNG export infrastructure absorbing disproportionate planning resources. QatarEnergy's North Field expansion and associated subsea pipeline networks command dedicated vessel fleets and consortium structures.
Generating most contract volume: Medium Scale. Gaining share fastest: Mega Projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mill clusters in eastern China and the Ruhr Valley anchor pipeline fabrication capacity, while hydrocarbon basins off Brazil, West Africa, and the eastern Mediterranean drive subsea installation demand.
United States
The Permian Basin and Gulf of Mexico offshore fields sustain cross-country trunk line and deepwater pipeline demand. The Pipeline and Hazardous Materials Safety Administration enforces Class Location requirements for high-pressure natural gas transmission corridors. Houston hosts the world's densest concentration of marine installation contractors and pipe-lay vessel operators.
Brazil
Pre-salt carbonate reservoirs off the Santos Basin require steel pipelines rated for 2,000-meter water depths and 1,440 psi internal pressures. The National Petroleum Agency mandates local content minimums for subsea installation contracts. The Porto do Açu industrial complex north of Rio de Janeiro concentrates pipe coating and logistics infrastructure.
Saudi Arabia
Saudi Aramco's Master Gas System expansion and Red Sea coastal development programs absorb onshore and offshore installation capacity. The Saudi Standards, Metrology and Quality Organization enforces pipeline material traceability protocols for sour service applications. The Eastern Province around Dhahran hosts integrated engineering centers and marine fabrication yards.
Norway
Equinor's North Sea and Barents Sea field developments sustain demand for rigid and flexible subsea pipelines. The Norwegian Petroleum Safety Authority governs hyperbaric welding qualifications and vessel certification standards. Stavanger and Bergen anchor specialized diving contractor clusters and subsea engineering consultancies.
United Arab Emirates
ADNOC's offshore field redevelopment and hydrogen export corridor planning generate multi-source contracting opportunities. The Abu Dhabi National Oil Company mandates integrated service contracts bundling installation with decades-long integrity management. The Das Island and Zirku Island industrial zones concentrate pipe fabrication and marine logistics infrastructure.
Pipeline Installation Services Market Competitive Landscape
Integrated service contracting dominates the current landscape, with national oil companies transferring operational risk to single-accountability EPC structures. The vendor base concentrates among full-service marine contractors with proprietary vessel fleets and regional specialists with terrain-specific trenching capabilities. Three archetypes define competitive positioning: integrated engineering-procurement-construction houses, subsea installation specialists with reel-lay automation, and onshore trenching contractors with desert or permafrost expertise. Portfolio diversification and strategic partnerships represent the dominant competitive moves, as pure-play fabricators seek bundled maintenance contracts.
Within the integrated tier, Saipem S.p.A., TechnipFMC plc, and McDermott International exemplify the full-service model spanning engineering through commissioning. These entities occupy positions defined by vessel fleet scale and geographic licensing relationships rather than discrete product lines. Their competitive differentiation rests on lifecycle cost models and single-point accountability structures favored by Middle Eastern national oil companies.
| Leading Market Players |
|---|
| Saipem S.p.A. |
| Subsea 7 S.A. |
| TechnipFMC plc |
| McDermott International |
| John Wood Group PLC |
| China Petroleum Pipeline Engineering Co., Ltd. |
| Halliburton Company |
| Baker Hughes Company |
| Schlumberger Limited |
| Others |
Value Network & Pricing Analysis
Alloy steel pipe stock volatility propagates through fixed-bid EPC contracts into three-tier pricing structures across premium, standard, and economy levels, with chromium-molybdenum grades commanding substantial premiums over carbon steel for sour service applications in Saudi Aramco and ADNOC corridors.
Pricing Analysis
Warranty and integrity-management bundling separate premium installation contracts from unbundled construction-only bids. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth: hyperbaric-qualified welding commands premium tiers, while conventional onshore trenching occupies economy positioning. Price differentiation hinges on vessel fleet scale and geographic licensing relationships. Cost compression in fixed-bid offshore segments is intensifying because nickel futures volatility transfers risk to contractors. Water utilities exhibit highest price sensitivity due to municipal funding constraints, while national oil companies prioritize lifecycle cost models over upfront capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with integrated steelworks in India and China for high-grade chromium-molybdenum pipe, with electric arc furnace producers in Europe and North America serving secondary sourcing roles. The supply chain draws from blast furnace emissions-intensive mills, nickel futures markets, and specialized pipe coating facilities at Porto do Açu and Das Island. Tariff exposure through the European Union's Carbon Border Adjustment Mechanism threatens cost structures for contractors sourcing from emissions-intensive integrated steelworks. Distribution runs through marine logistics hubs in Houston, Stavanger, and Singapore anchoring vessel fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
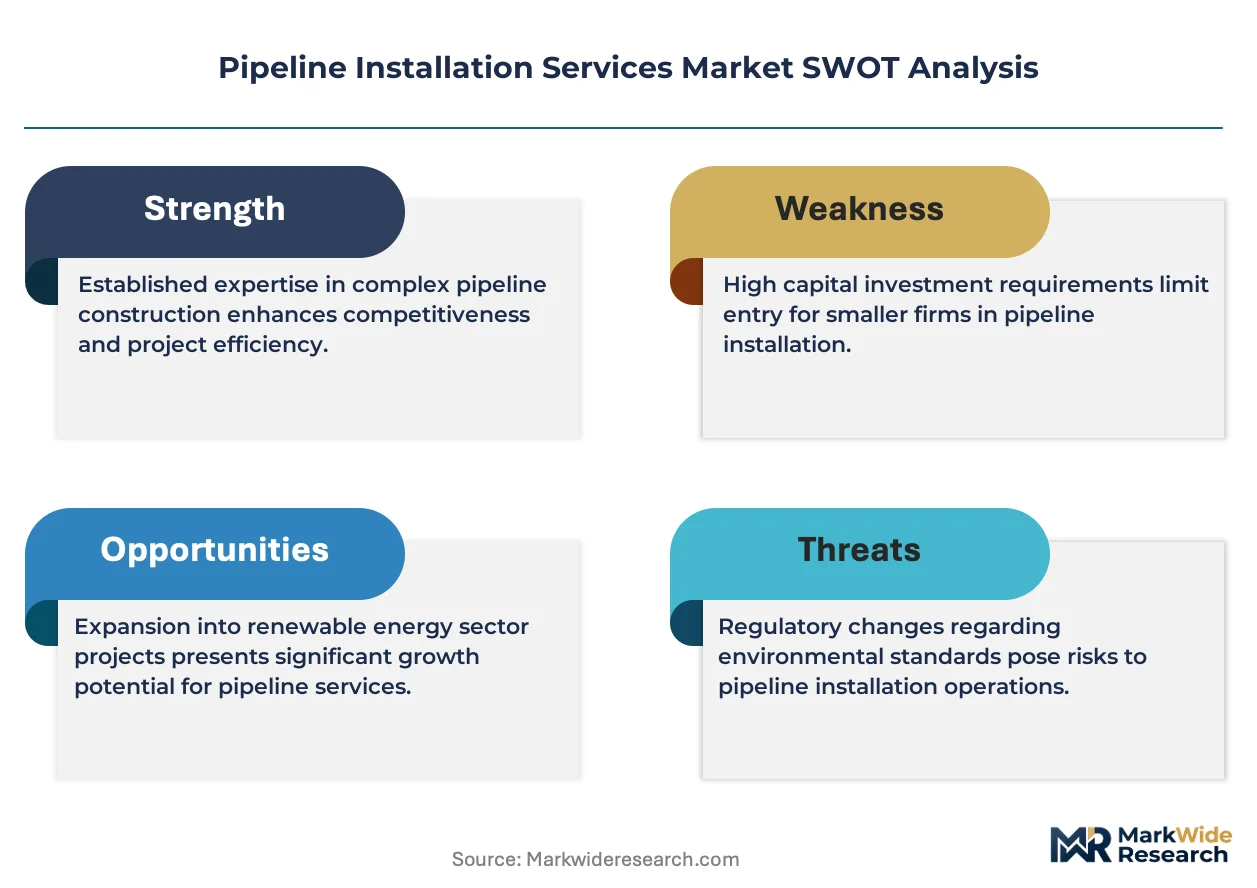
The Pipeline and Hazardous Materials Safety Administration's Class Location requirements and extended environmental review timelines erect substantial compliance moats that filter marginal contractors from high-stakes bidding, privileging incumbents with documented safety records and regulatory relationships.
For Market Incumbents: Extend integrity-management service contracts to capture decades-long operational risk transfer from Middle Eastern national oil companies, while adding hyperbaric welding training capacity to address technician shortages threatening vessel fleet utilization. Backward integration into electric arc furnace steel sourcing with renewable power purchase agreements hedges Carbon Border Adjustment Mechanism exposure.
For New Entrants and Emerging Players: The Inflation Reduction Act's CO2 pipeline construction subsidies in the United States open a window for modular micro-pipeline system specialists to bypass traditional EPC bidding cycles through standardized 4- to 12-inch diameter skid offerings. Target rural water cooperatives in Texas and Oklahoma with small-scale trenchless renewal contracts, leveraging EPA lead service line replacement mandates as a go-to-market entry point.
For Investors and Strategic Acquirers: ADNOC's accelerated qualification schedules for composite reinforced thermoplastic pipe at 2,000-meter water depths is the leading indicator that material substitution will reshape vessel selection criteria and contractor competitive positioning. Acquisition focus should center on reel-lay automation specialists and composite pipe qualification capabilities, with carbon-accounting documentation systems serving as the critical inflection signal for portfolio construction across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Reel-Lay Vessel Automation | Compresses offshore construction windows for Petrobras pre-salt developments through rigid pipeline deployment speed. |
| Composite Pipe Qualification | ADNOC and Saudi Aramco acceleration programs displace corrosion-resistant alloy steel in sour gas tieback applications. |
| Carbon Border Adjustment Compliance | Electric arc furnace producer partnerships with renewable power purchase agreements secure mill certificate traceability for European contractors. |
| Hyperbaric Welding Training Expansion | Saturated diving school output cannot crew expanding vessel fleets for West Africa and eastern Mediterranean deepwater projects. |
| Digital Twin Integration | Real-time sensor fusion during installation absorbs quality assurance costs previously borne through post-construction hydrostatic testing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving EPC contract managers, marine vessel operators, hyperbaric welding technicians, national oil company procurement officers, and pipeline integrity engineers. Secondary sources encompassed Pipeline and Hazardous Materials Safety Administration incident databases, Bureau of Safety and Environmental Enforcement decommissioning records, International Maritime Organization SOLAS conventions, and steel mill emission disclosures. Bottom-up project pipeline tracking and top-down market sizing triangulated volume estimates across the analysis window.
Data-stream reconciliation merged vessel fleet deployment schedules, alloy steel price indices, and contract award announcements into a unified analytical framework. Segmentation dimensions modeled encompassed service type, end user category, installation method, and project scale tier across the projection horizon. CAGRs derived from weighted average of historical execution rates and announced capital expenditure programs, with hydrogen blending infrastructure retrofit timelines and carbon capture transport network development serving as industry-specific demand inputs.
The model assumes a particular technology adoption path; alternative pathways for composite reinforced thermoplastic pipe at extreme water depths would alter the outlook for rigid steel demand and vessel fleet configuration. Forecasts reflect assumptions regarding regulatory harmonization between national pipeline codes and emerging carbon-accounting standards, with subsea welding technician production rates and legacy GIS data digitization progress representing material uncertainty factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Engineering Services
Asia Pacific Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Construction Engineering Services Outsourcing Market
Engineering Services
United States (US) MEP Services Market
Engineering Services
Sheet Metal Fabrication Services Market
Engineering Services
United States Engineering Services Market
Engineering Services
Seismic Services Market
Engineering Services
Bridge Inspection System Market
Engineering Services
Middle East Seismic Services Market
Engineering Services
Vacuum Excavation Service Market
Engineering Services
NDT Inspection Services Market
Engineering Services
Geotechnical Services Market
Engineering Services
North America Seismic Survey Market
Engineering Services
India Engineering, Procurement, and Construction Management (EPCM) Market
Engineering Services
Engineering Services Market
Engineering Services
Well Cementing Services Market
Engineering Services
Metal Joining Services Market