
 Silos Market | 2026-2036
Silos Market Size, Share, and Industry Trends Forecast 2026-2036
Silos Market Outlook
REACH compliance is repositioning material specifications for chemical and food-contact silo linings across Europe. AGI leverages its North American manufacturing footprint to dominate large-diameter galvanized steel grain storage. Symaga specializes in modular bolted steel designs that navigate seismic requirements in Mediterranean markets. Sukup Manufacturing Co. anchors its position through backward integration into roll-forming and aeration component production.
Silos are enclosed vertical storage vessels engineered from reinforced concrete, corrugated steel, or thermoplastic composites, typically featuring conical or flat bottoms with aeration systems to control moisture and temperature. Their primary purpose is to preserve bulk solids—grains, powders, pellets, and granules—against spoilage, contamination, and pest infestation during extended holding periods. Steel silos lead the product type category due to faster on-site assembly and lower foundation costs versus monolithic concrete, though concrete maintains share in permanent chemical storage where structural inertia and fire resistance command premium positioning. The agriculture end user segment generates the largest volume demand, while chemical applications concentrate margin pools through corrosion-resistant alloy specifications and pressure-rated designs.
The EPA regulates particulate emissions from grain handling and storage facilities under the National Emission Standards for Hazardous Air Pollutants, while OSHA enforces confined-space entry protocols for silo maintenance crews. In Europe, ECHA's REACH restrictions on hexavalent chromium coatings are accelerating shifts to epoxy-based and hot-dip galvanized steel protection systems. Stakeholders must monitor evolving carbon-border adjustments and embodied-carbon disclosure rules that will reshape sourcing decisions for steel-intensive storage infrastructure.
Market Dynamics
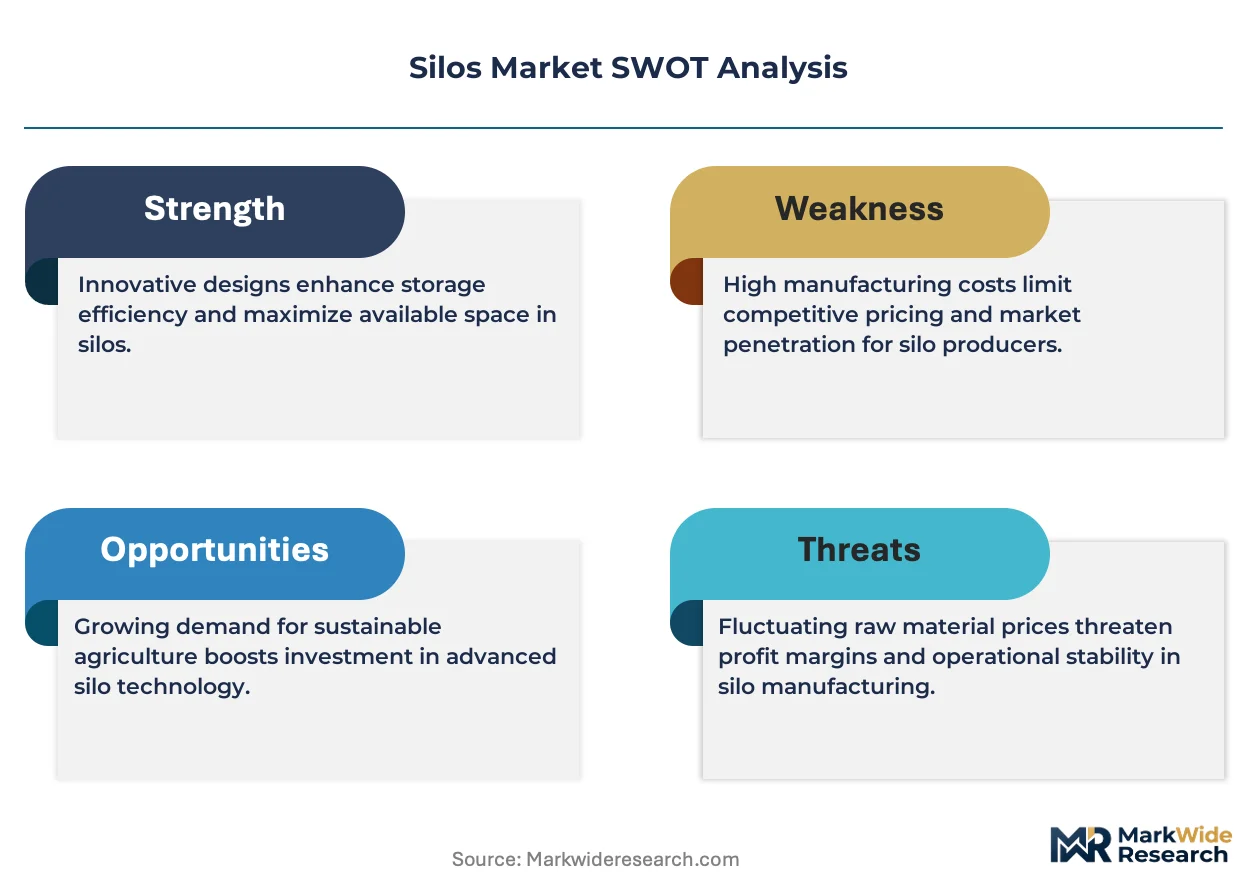
REACH compliance is forcing material substitutions across European silo manufacturing, as ECHA restrictions on hexavalent chromium coatings accelerate shifts toward epoxy-based and hot-dip galvanized protection systems. This regulatory pressure cascades through supply chains, reshaping specification standards for food-contact and chemical storage vessels.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Tightening storage infrastructure standards across member states drives replacement cycles for aging concrete silos with compliant steel alternatives.
- American Midwest Cooperative Modernization:Elevator networks are dismantling legacy concrete structures and installing large-diameter galvanized steel replacements to reduce post-harvest losses.
- Aeration System Integration:Advanced moisture and temperature control technologies embedded in new silo designs extend grain preservation periods and reduce spoilage rates.
Market Restraints
- Steel Input Cost Volatility:Fluctuations in galvanized steel sheet pricing compress margins for manufacturers without captive roll-forming capabilities.
- Foundation Engineering Complexity:Seismic requirements in Mediterranean and Pacific Rim geographies add structural engineering costs that concrete alternatives avoid.
- Confined-Space Regulatory Burden:OSHA enforcement of maintenance crew entry protocols raises operational compliance costs for facility operators.
Strategic Opportunities
- Carbon-Border Adjustment Preparedness:Early alignment with embodied-carbon disclosure rules positions suppliers favorably for EU import tariff structures taking effect.
- Modular Bolted Design Expansion:Seismic-rated bolted steel configurations address underpenetrated Mediterranean markets where welded alternatives fail certification.
- Chemical Storage Alloy Specialization:Corrosion-resistant specifications for pressure-rated designs capture margin pools in specialty chemical applications.
Industry Challenges
- Welding Certification Scarcity:Qualified pressure-vessel welders for chemical-grade silo fabrication remain concentrated in legacy manufacturing clusters.
- Legacy System Integration Friction:New aeration and monitoring technologies require retrofit protocols that extend installation timelines for existing concrete structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silos Market |
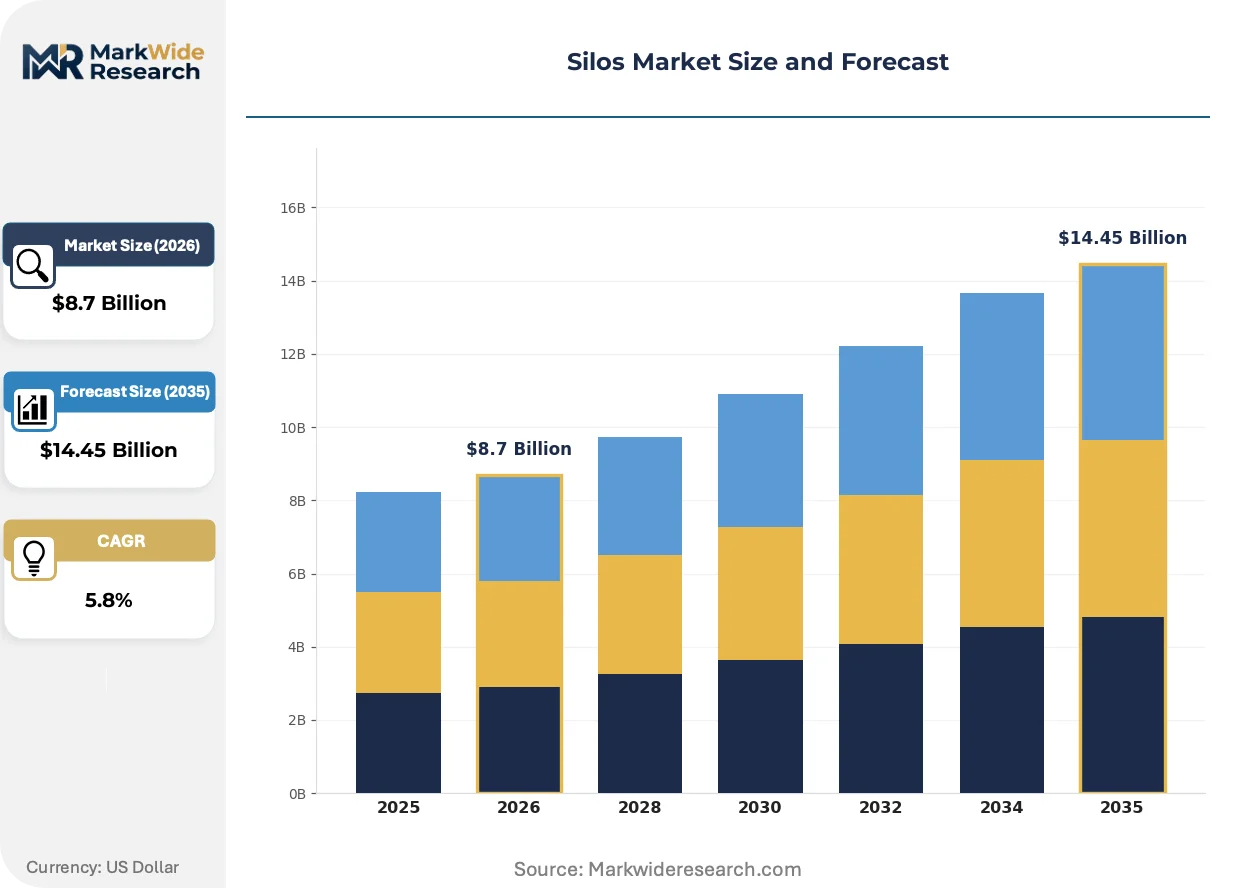
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Silos, Steel Silos, Plastic Silos, Wooden Silos End User: Agriculture, Industrial, Chemical, Food & Beverage Size: Small, Medium, Large, Extra Large Application: Storage, Transportation, Processing, Mixing |
| Companies Covered | Sukup Manufacturing Co., AGI, Symaga, Silos Córdoba, Bentall Rowlands, Sioux Steel Company, CST Industries, Prado Silos, TSC Silos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silos Market Strategic Shifts
Digital monitoring systems and material science advances are compressing installation timelines while extending asset lifecycles. The convergence of regulatory disclosure requirements and supply chain traceability is reshaping how specifications are written and enforced.
Bolted steel silo construction is modularizing on-site assembly processes, reducing foundation requirements and crane time. Commercial grain elevators in the American Midwest are adopting these configurations to minimize harvest-season installation windows. The approach is modularizing competitive positioning around speed-to-operation rather than pure material cost.
REACH restrictions on hexavalent chromium are eliminating traditional coating systems from European specification sheets. ECHA enforcement timelines are compressing supplier transition windows to epoxy-based and hot-dip galvanized alternatives. Food-contact silo linings face the steepest reformulation requirements, with German and French inspectors already rejecting non-compliant imports.
Cooperative buyers are consolidating procurement around full-service installation contracts that bundle engineering, foundation work, and after-sales monitoring. This bundling displaces the historical model of silo-only supply with separate contractor management. The shift concentrates volume with manufacturers possessing in-house aeration component production and regional service networks.
Silos Market Segmentation
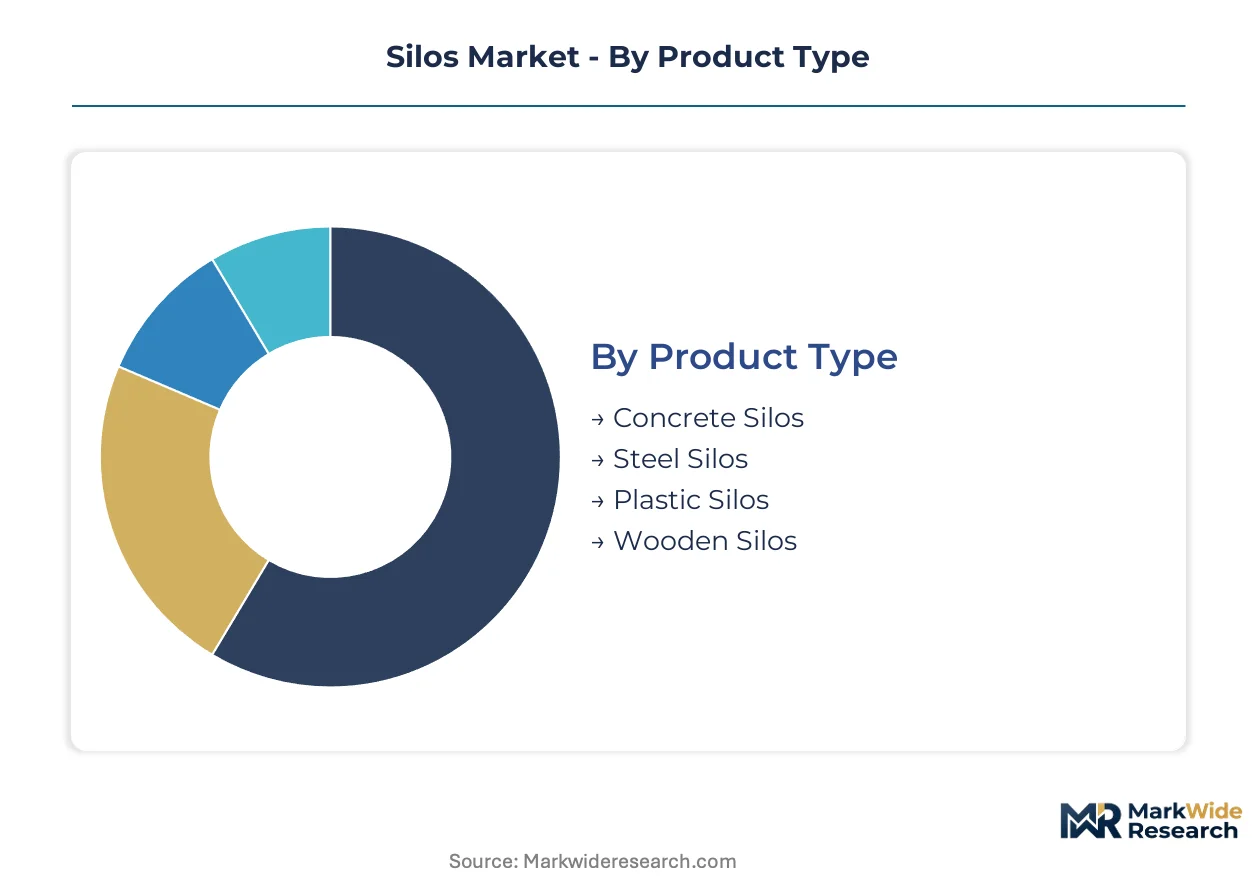
Silo procurement decisions pivot on material durability, foundation requirements, and regulatory compliance profiles. Segmentation reveals how specification choices cascade through total cost of ownership calculations and regional certification pathways.
Product Type:
Material selection determines assembly speed, seismic resilience, and coating compliance obligations under REACH and EPA frameworks.
- Concrete Silos:Monolithic reinforced structures deliver structural inertia and fire resistance for permanent chemical storage installations. Demand concentrates in EU chemical corridors where ECHA pressure-vessel standards favor mass concrete over welded alternatives for hazardous material containment.
- Steel Silos:Corrugated galvanized or epoxy-coated configurations enable faster on-site assembly with lower foundation costs. American Midwest cooperative elevator networks are dismantling legacy concrete structures to install large-diameter galvanized replacements that reduce post-harvest losses.
- Plastic Silos:Thermoplastic composite vessels serve niche food-contact and corrosive chemical applications where metal fatigue risks dominate. German and French inspectors are already rejecting non-compliant imports under tightened Farm to Fork infrastructure standards.
- Wooden Silos:Traditional timber construction persists in heritage grain preservation operations and small-scale organic farming cooperatives.
Mature deployment sits with Concrete Silos. Newer deployment is concentrated in Steel Silos.
End User:
Volume scale and margin concentration diverge sharply across buyer categories, with chemical applications commanding alloy premiums.
- Agriculture:Grain handling operations generate the largest volume demand as commercial elevators expand capacity to cut spoilage. American Midwest cooperative networks are modernizing legacy structures with aeration-integrated steel replacements.
- Chemical:Corrosion-resistant alloy specifications and pressure-rated designs capture the steepest margin pools. REACH compliance is forcing material substitutions across European manufacturing as ECHA restrictions eliminate hexavalent chromium coatings from specification sheets.
- Industrial:Bulk powder and pellet storage for cement, minerals, and construction materials drives demand for abrasion-resistant linings.
- Food & Beverage:Food-contact silo linings face the steepest reformulation requirements under EU Green Deal Farm to Fork infrastructure standards.
Volume leadership belongs to Agriculture. Margin concentration clusters in Chemical.
Size:
Foundation engineering complexity and crane rental windows scale non-linearly with diameter and height specifications.
- Large:Diameters exceeding 30 meters dominate commercial grain elevator installations where harvest-season throughput determines ROI. Mediterranean seismic requirements add structural engineering costs that welded alternatives often fail to certify.
- Extra Large:Custom-engineered mega-silos serve port terminal operations and integrated processing facilities with dedicated foundation studies.
- Medium:Mid-scale configurations balance modularity with throughput for regional cooperative networks.
- Small:Compact bolted designs address farm-level storage and specialty chemical batch operations.
Procurement is shifting toward Large capacities in export-oriented grain corridors. Small-scale deployment is expanding in organic and specialty chemical niches.
Application:
Functional use case determines aeration system integration, discharge mechanism design, and cleaning protocol requirements.
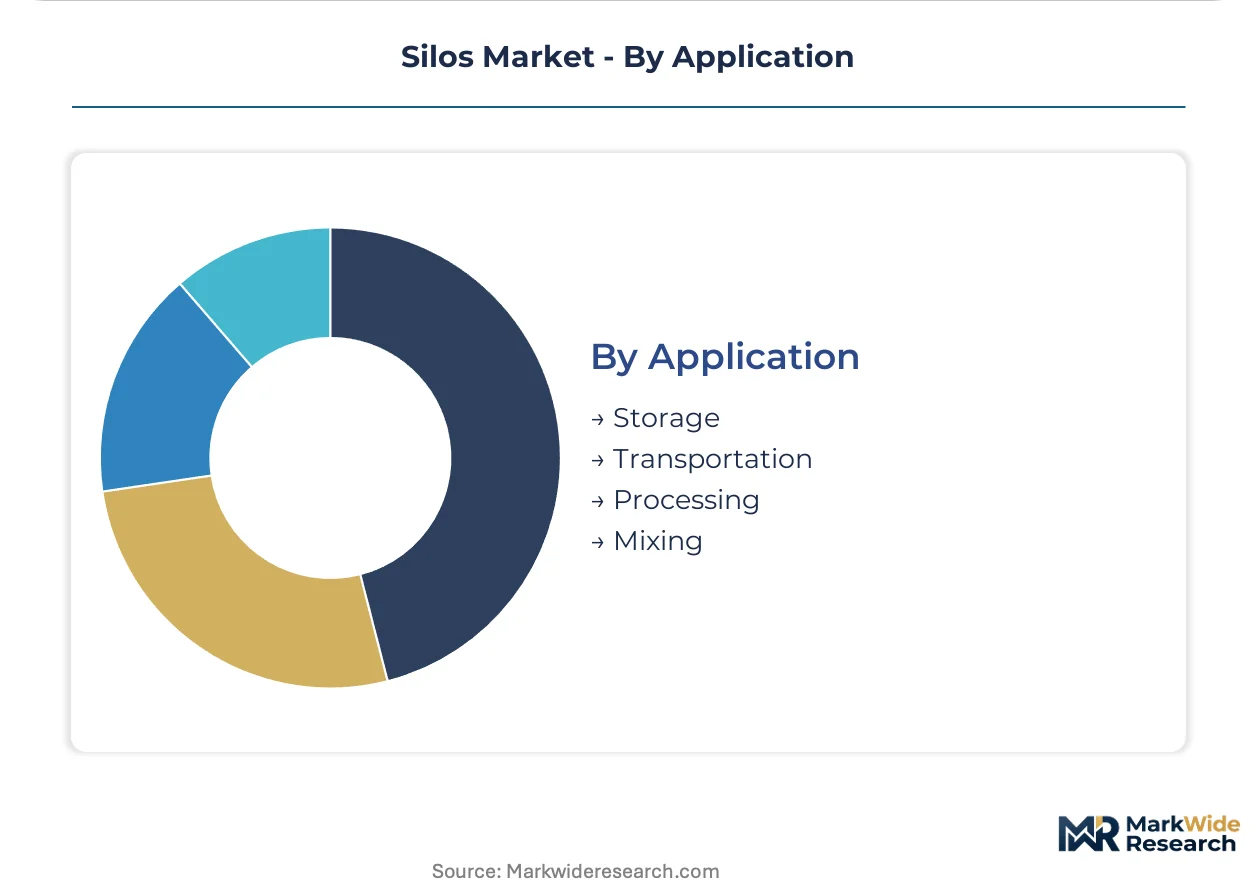
- Storage:Extended-hold preservation against spoilage, contamination, and pest infestation represents the core function. Advanced moisture and temperature control technologies embedded in new designs extend grain preservation periods.
- Processing:In-silo drying and conditioning operations require integrated heat and airflow management systems.
- Transportation:Mobile and port-side configurations prioritize rapid loading compatibility with rail and vessel systems.
- Mixing:Blending silos for feed formulation and chemical compounding demand specialized agitation and discharge geometries.
Storage dominates capital allocation. Processing is gaining share fastest as aeration technology improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
American Midwest cooperative networks anchor grain storage demand, while EU chemical corridors and Mediterranean seismic zones concentrate specialized steel fabrication requirements across distinct regulatory environments.
United States
Iowa and Illinois elevator cooperatives are dismantling legacy concrete structures to install large-diameter galvanized steel replacements. EPA National Emission Standards for Hazardous Air Pollutants regulate particulate discharge from grain handling facilities. Sioux Steel Company anchors manufacturing presence in the upper Midwest, supplying cooperative networks with aeration-integrated systems.
Germany
ECHA enforcement of REACH hexavalent chromium restrictions is eliminating traditional coating systems from specification sheets. The Farm to Fork strategy tightens storage infrastructure standards for food-contact applications. Industrial clusters along the Rhine corridor concentrate chemical-grade silo fabrication for pressure-rated hazardous material containment.
Spain
Symaga's modular bolted steel designs navigate seismic certification requirements that welded alternatives fail to meet. ECHA compliance deadlines compress supplier transition windows to epoxy-based protection systems. Andalusian agricultural cooperatives are expanding capacity to reduce post-harvest losses under tightened EU infrastructure standards.
China
Dual carbon goals and GB standards are reshaping material specifications for steel-intensive storage infrastructure. Port terminal operations in the Yangtze River Delta drive demand for custom-engineered mega-silos with dedicated foundation studies. Domestic fabricators are consolidating procurement around full-service installation contracts bundling engineering and after-sales monitoring.
Brazil
Commercial agriculture expansion in Mato Grosso and Goiás is driving grain elevator capacity additions to cut spoilage rates. ANVISA regulations govern food-contact storage vessel specifications for export-oriented operations. Regional cooperative networks are modernizing legacy infrastructure with aeration-integrated designs.
Silos Market Competitive Environment
North American producers anchor one tier; European specialists hold certification advantages in seismic-rated and chemical-grade applications. The vendor base fragments across regional fabrication clusters with distinct regulatory compliance capabilities. Three archetypes dominate: integrated manufacturers with captive roll-forming, modular bolted design specialists, and alloy fabricators serving pressure-rated chemical storage. Capacity expansion and strategic bundling of installation services represent the dominant competitive moves.
Within the integrated manufacturing tier, Sukup Manufacturing Co. exemplifies backward integration into roll-forming and aeration component production. AGI anchors large-diameter galvanized steel grain storage through its North American manufacturing footprint. Symaga occupies a position among modular bolted steel specialists addressing Mediterranean seismic requirements that welded alternatives cannot certify.
| Leading Market Players |
|---|
| Sukup Manufacturing Co. |
| AGI |
| Symaga |
| Silos Córdoba |
| Bentall Rowlands |
| Sioux Steel Company |
| CST Industries |
| Prado Silos |
| TSC Silos |
| Others |
Value Chain & Pricing Dynamics
Backward integration into roll-forming and aeration component production anchors pricing power for North American manufacturers while compressing margins for competitors sourcing externally. This captive supply structure insulates integrated players from galvanized steel sheet volatility that otherwise erodes project profitability.
Pricing Analysis
Volume leadership in agriculture generates thin margins on standard grain storage, while chemical-grade alloy specifications capture premium positioning. Pricing stratifies across corrosion-resistant pressure-rated designs, hot-dip galvanized food-contact vessels, and standard commercial configurations. Cost compression in the standard steel tier is intensifying because foundation engineering complexity and seismic certification requirements concentrate procurement with bundled full-service providers. Cooperative elevator networks in the American Midwest exhibit the highest price sensitivity, whereas EU chemical corridors prioritize REACH-compliant coating systems over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese galvanized steel sheet production that feeds global fabrication networks. Raw material procurement draws from Australian iron ore, Brazilian metallurgical coal, and South Korean hot-rolled coil. Tariff exposure on steel inputs threatens margin stability for European and North American fabricators without captive rolling capacity. Distribution runs through regional fabrication clusters with distinct regulatory compliance capabilities, concentrating final assembly near end-use markets to minimize transport costs for large-diameter vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive survival in silo manufacturing demands vertical-integration depth, with upstream control over roll-forming and downstream bundling of installation services separating viable players from margin-squeezed assemblers.
For Market Incumbents: Extend backward integration into aeration component production to defend against modular bolted specialists encroaching on harvest-season installation windows. Anchor capacity in the American Midwest where cooperative networks consolidate procurement around full-service contracts. Fortify REACH-compliant coating capabilities before ECHA enforcement eliminates hexavalent chromium alternatives from European specification sheets. For New Entrants and Emerging Players: Equipment financing partnerships with regional agricultural cooperatives unlock penetration in Mediterranean seismic zones where welded alternatives fail certification. Target modular bolted configurations for Andalusian and Spanish markets underserved by legacy concrete suppliers. Pursue white-space positioning in corrosion-resistant alloy fabrication for EU chemical corridors where pressure-rated vessel welders remain scarce. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking agricultural infrastructure exposure. Long-term viability hinges on carbon-border adjustment preparedness as EU embodied-carbon disclosure rules reshape sourcing decisions. Monitor ECHA coating compliance deadlines as an inflection indicator for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Roll-Forming | Captive steel processing insulates margins from commodity volatility in galvanized sheet markets. |
| Modular Bolted Design Certification | Seismic-rated configurations unlock Mediterranean agricultural demand that welded alternatives cannot serve. |
| REACH-Compliant Coating Transition | Epoxy-based and hot-dip galvanized systems replace hexavalent chromium before ECHA enforcement eliminates non-compliant imports. |
| Full-Service Installation Bundling | Engineering-foundation-monitoring packages displace silo-only supply and concentrate volume with integrated manufacturers. |
| Aeration Technology Integration | Embedded moisture control extends grain preservation periods and differentiates premium vessel specifications. |
Study Parameters
Independent corroboration across plant engineers at commercial grain elevators, procurement leads at agricultural cooperatives, and technical directors at steel fabrication facilities underwrites the qualitative findings. Primary fieldwork encompassed maintenance directors, OEM procurement teams, and aftermarket service heads across American Midwest, German, and Spanish markets. Secondary validation drew from EPA National Emission Standards filings, ECHA REACH restriction updates, EU Farm to Fork strategy documentation, and customs data on galvanized steel sheet trade flows. Bottom-up demand modeling triangulated against top-down capacity assessments across regional fabrication clusters.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-regulatory-shift adoption curves. Segmentation dimensions encompassed material type, end-use industry, vessel diameter tier, and regional regulatory framework. CAGRs were derived from installed base replacement cycles, cooperative elevator modernization timelines, and chemical storage capacity expansion patterns. Industry-specific forecast inputs included ECHA compliance transition deadlines and American Midwest harvest-season installation window constraints.
Caveats apply where steel input cost volatility, seismic certification requirement changes, or carbon-border adjustment implementation timing could materially shift the outlook. Deviation in REACH enforcement intensity or galvanized steel tariff structures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Sawn and Profiled Wood Products Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Garage and Overhead Doors Market