
 Spraying and Plastering Machine Market | 2026-2036
Spraying and Plastering Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Spraying and Plastering Machine Market Analysis
Multi-source procurement for spraying and plastering equipment is hardening across European construction fleets. Putzmeister Holding GmbH leverages its German manufacturing base to sustain premium positioning in large-scale plastering systems. Graco Inc. anchors North American distribution through its industrial coatings heritage, while Sika AG competes by extending chemical-material compatibility into application hardware.
Spraying and plastering machines mechanically project cementitious, gypsum-based, or polymer-modified mortars onto vertical and horizontal surfaces at pressures ranging from 20 to 80 bar, eliminating manual troweling in high-volume construction. Electric sprayers dominate residential retrofit channels where noise restrictions and indoor air quality standards limit combustion-powered alternatives, while airless sprayers capture the fastest growth in industrial protective coatings due to superior transfer efficiency and reduced overspray waste. Plastering machines concentrate margin pools in medium-capacity units serving commercial mid-rise contractors who balance mobility with daily output targets.
Germany's Energy Efficiency Act, France's RE2020 environmental regulation, and the EU Machinery Directive collectively tighten emission and safety standards for construction equipment deployed across member states. These frameworks compel manufacturers to integrate dust suppression systems and electric powertrains to maintain market access. Stakeholders must monitor how impending CE marking revisions for battery-powered construction machinery reshape product development roadmaps and certification costs.
Market Dynamics
Germany's revised Energy Efficiency Act compresses building envelope completion timelines, forcing commercial contractors across Europe to mechanize plastering workflows and retire manual troweling crews. This regulatory acceleration is concentrating equipment demand among mid-rise specialists who must maintain throughput under tighter municipal inspection schedules.
Growth Catalysts
- Energy Efficiency Act mandates:Germany's binding envelope completion deadlines push builders toward continuous-flow plastering systems that sustain 24-hour curing cycles without labor gaps.
- India affordable housing targets:Central government commitments to urban housing stock expansion concentrate fleet orders in Mumbai, Delhi, and Bangalore contractor pools.
- Polymer-modified mortar compatibility:Machine-applied polymer renders reduce cracking incidence on high-rise facades, accelerating specification by risk-averse developers.
Market Restraints
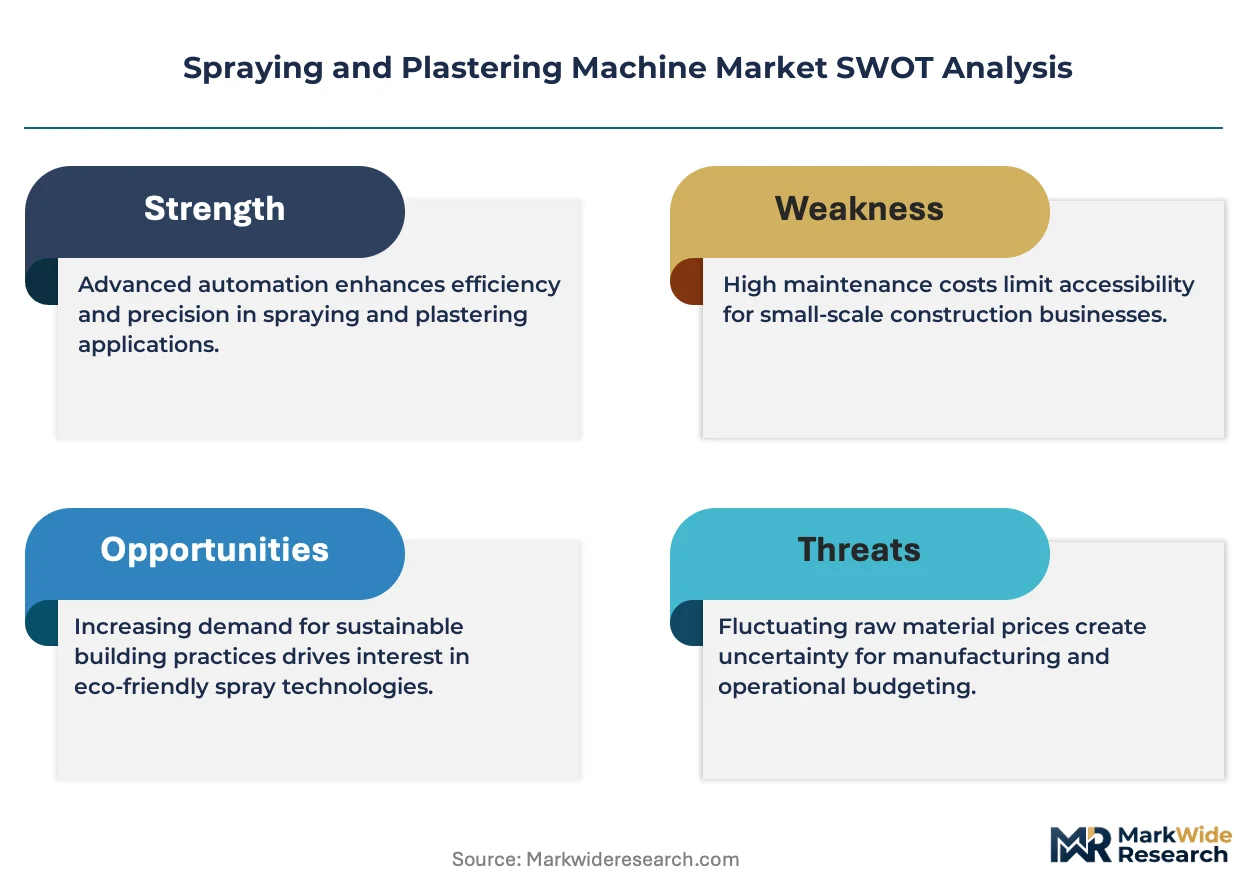
- Steel and aluminum input volatility:Hopper fabrication costs fluctuate with commodity indexes, compressing margin visibility for equipment manufacturers.
- CE marking certification friction:Battery-powered machinery faces pending electrical safety standard revisions that delay product launches.
- Manual troweling substitution threshold:Small residential renovators retain hand-finishing for projects under 500 square meters where machine mobilization costs exceed labor savings.
Strategic Opportunities
- France RE2020 carbon thresholds:Environmental performance standards for new construction create specification pull for low-cure-energy plastering systems.
- Industrial protective coatings crossover:Airless spraying technology from marine and infrastructure maintenance channels migrates into architectural finishing applications.
- Rental fleet channel expansion:Equipment-as-a-service models reduce capital barriers for mid-tier contractors in Spain and Italy.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of electric drive systems and pressure control modules requires skills absent from traditional masonry training pipelines.
- Legacy pneumatic integration:Contractors with existing compressor infrastructure face retrofit costs when transitioning to standalone electric units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spraying and Plastering Machine Market |
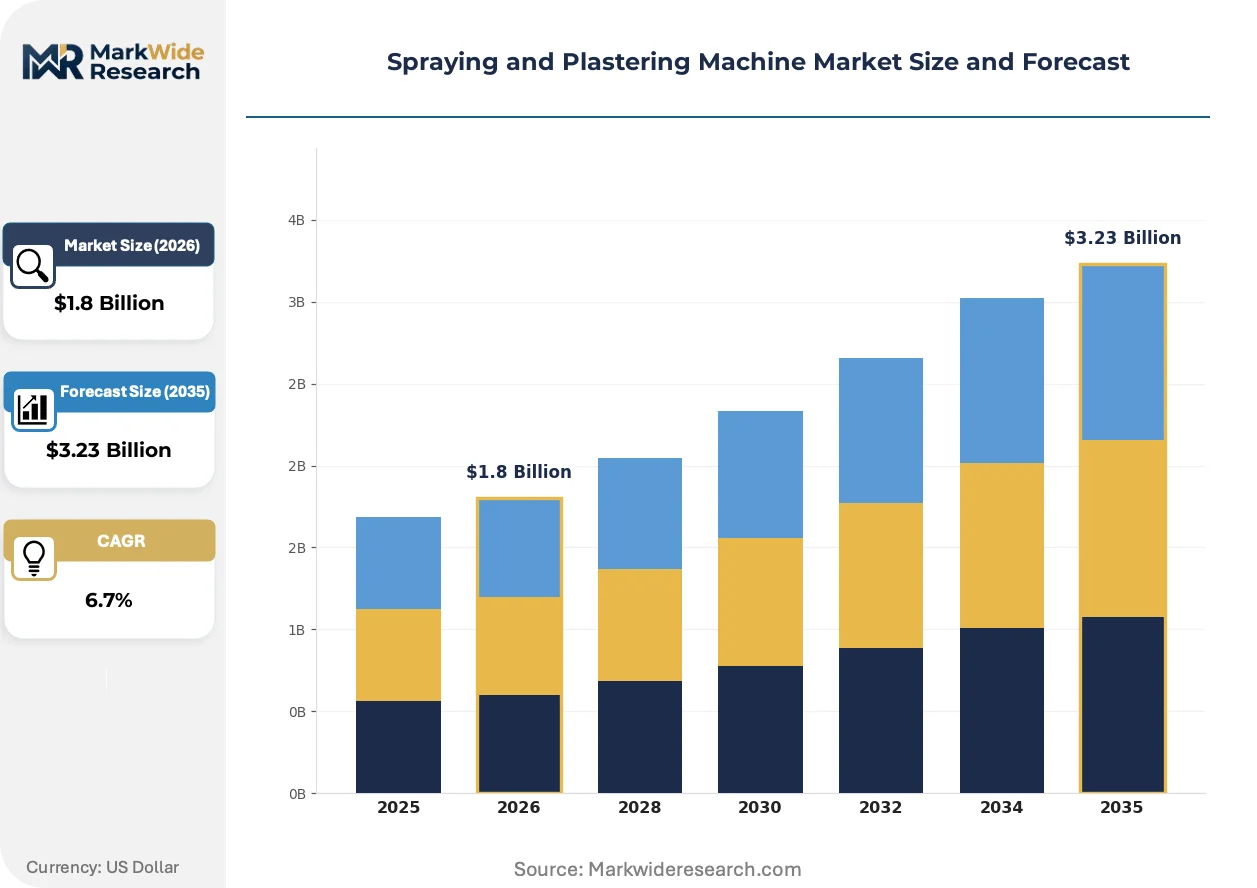
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Sprayers, Airless Sprayers, Pneumatic Sprayers, Plastering Machines Application: Residential Construction, Commercial Construction, Repair & Maintenance, Industrial Applications End User: Contractors, DIY Enthusiasts, Builders, Plastering Professionals Size: Small, Medium, Large, Portable |
| Companies Covered | Putzmeister Holding GmbH, Sika AG, Graco Inc., IMER International SpA, Schwing Stetter Group, Normet, Kappa Building Machines Pvt. Ltd, ACME Equipment Pte Ltd, Zhengzhou Sincola Machinery Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spraying and Plastering Machine Market Emerging Trajectories
Electrification and automation are compressing the skill gap between machine operation and finish quality, while regulatory carbon thresholds restructure material specifications and procurement priorities across European construction.
Battery-electric plastering systems are integrating regenerative braking and onboard power management to extend runtime between charging cycles. Commercial mid-rise contractors in Germany and the Netherlands are specifying these units for indoor air quality compliance on sealed building envelopes. The technology is integrating dust suppression and noise reduction as standard features, displacing combustion-powered alternatives from urban retrofit channels.
France's RE2020 environmental regulation mandates lifecycle carbon accounting for construction materials, compelling plastering machine manufacturers to certify compatibility with low-carbon gypsum and recycled-aggregate mortars. Industrial consequence includes reformulated pump chambers and abrasion-resistant liners. Commercial high-rise segments in Paris and Lyon are responding by pre-qualifying equipment vendors on material certification breadth.
After-sales service unbundling is fragmenting traditional distributor relationships. Contractors in India's tier-1 cities now source machines through direct manufacturer channels while procuring maintenance and spare parts through independent technical service networks. This behavioral shift is most visible in Mumbai, where fleet operators prioritize uptime guarantees over bundled warranty terms.
Spraying and Plastering Machine Market Segmentation
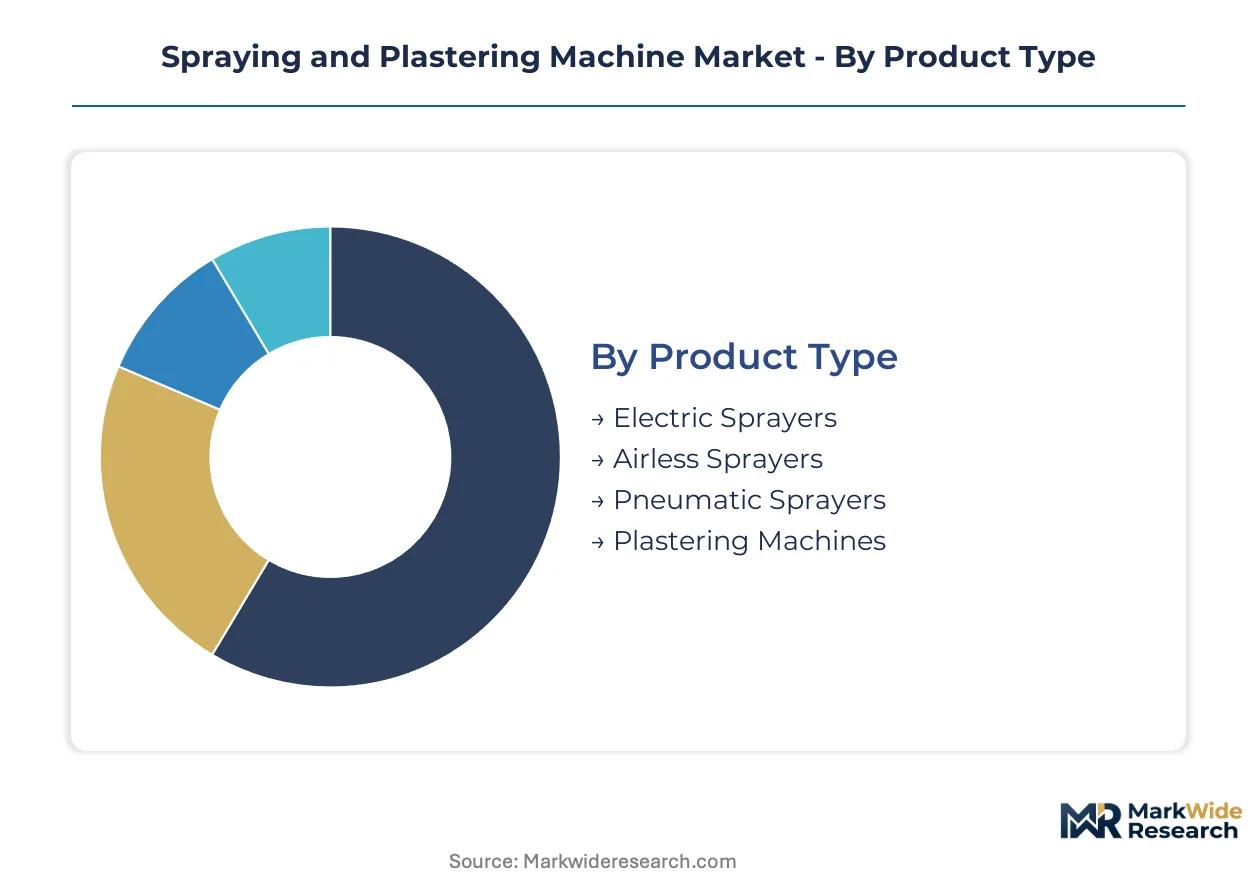
Spraying and plastering machines serve divergent workflow economics across construction verticals. Product specifications, application environments, and operator skill levels fragment procurement patterns into distinct equipment tiers with non-overlapping margin profiles.
Product Type:
Contractor fleet decisions pivot on power source availability, noise constraints, and material viscosity requirements rather than upfront capital alone.
- Electric Sprayers:Battery and corded units deliver 20-40 bar output with zero exhaust emissions. Demand clusters in German urban retrofit projects where municipal noise ordinances and indoor air quality rules restrict combustion equipment. Runtime anxiety persists on large facades without charging infrastructure.
- Airless Sprayers:Hydraulic piston pumps generate 200+ bar pressures for high-build coatings and fireproofing. Marine maintenance contractors in Rotterdam and Hamburg ports drive specification for transfer efficiency above 65% on steel substrate preparation. Material savings justify premium pricing on large surface areas.
- Pneumatic Sprayers:Compressed air atomization suits low-viscosity primers and stains. Legacy compressor fleets in Italian and Spanish contractor yards sustain residual demand despite electrification trends.
- Plastering Machines:Continuous-flow rotor-stator pumps handle cementitious and gypsum mortars up to 6mm aggregate size. Mumbai and Delhi contractors specify medium-capacity units for affordable housing envelope completion under compressed municipal inspection schedules.
Volume sits with Plastering Machines; growth tilts toward Airless Sprayers.
Application:
Project scale and finish tolerance requirements stratify equipment specifications across construction phases.
- Residential Construction:Single-family and low-rise multi-family projects favor portable electric units for interior finishing. Bangalore and Pune developers specify dust-suppressed models for sealed building envelopes under tightening municipal air quality enforcement.
- Commercial Construction:Mid-rise office and retail shells demand continuous-output plastering systems sustaining 8-12 hour shifts. German Energy Efficiency Act deadlines compress envelope completion windows, concentrating fleet investment among specialist contractors.
- Repair & Maintenance:Facade remediation and structural rehabilitation require material compatibility across aged substrates. Paris and Lyon contractors pre-qualify equipment on low-carbon gypsum certification breadth under France RE2020 lifecycle accounting rules.
- Industrial Applications:Protective coatings for chemical processing infrastructure specify explosion-proof airless configurations. Rotterdam port maintenance yards drive specification for ATEX-compliant hardware on offshore platform refurbishment.
Commercial Construction commands current fleet investment; Repair & Maintenance is climbing the fastest as building stock ages across Western Europe.
End User:
Capital access and technical sophistication divide procurement channels into divergent service models.
- Contractors:Fleet-owning specialists with dedicated maintenance capabilities source through direct manufacturer relationships. Mumbai tier-1 operators unbundle after-sales service from equipment purchase, procuring spare parts through independent technical networks.
- DIY Enthusiasts:Home improvement retailers in German and Dutch suburban markets stock compact electric sprayers for interior painting. Price sensitivity limits specification to entry-level diaphragm pumps below 150 bar.
- Builders:Project developers with in-house finishing crews specify medium-capacity plastering machines for phased construction. Equipment-as-a-service rental models reduce capital barriers for Spanish and Italian mid-tier operators.
- Plastering Professionals:Skilled tradesmen in traditional markets retain manual troweling for projects under 500 square meters where machine mobilization costs exceed labor savings on small residential renovations.
Contractors dominate installed base; Builders are expanding fleet ownership fastest as vertical integration pressures mount.
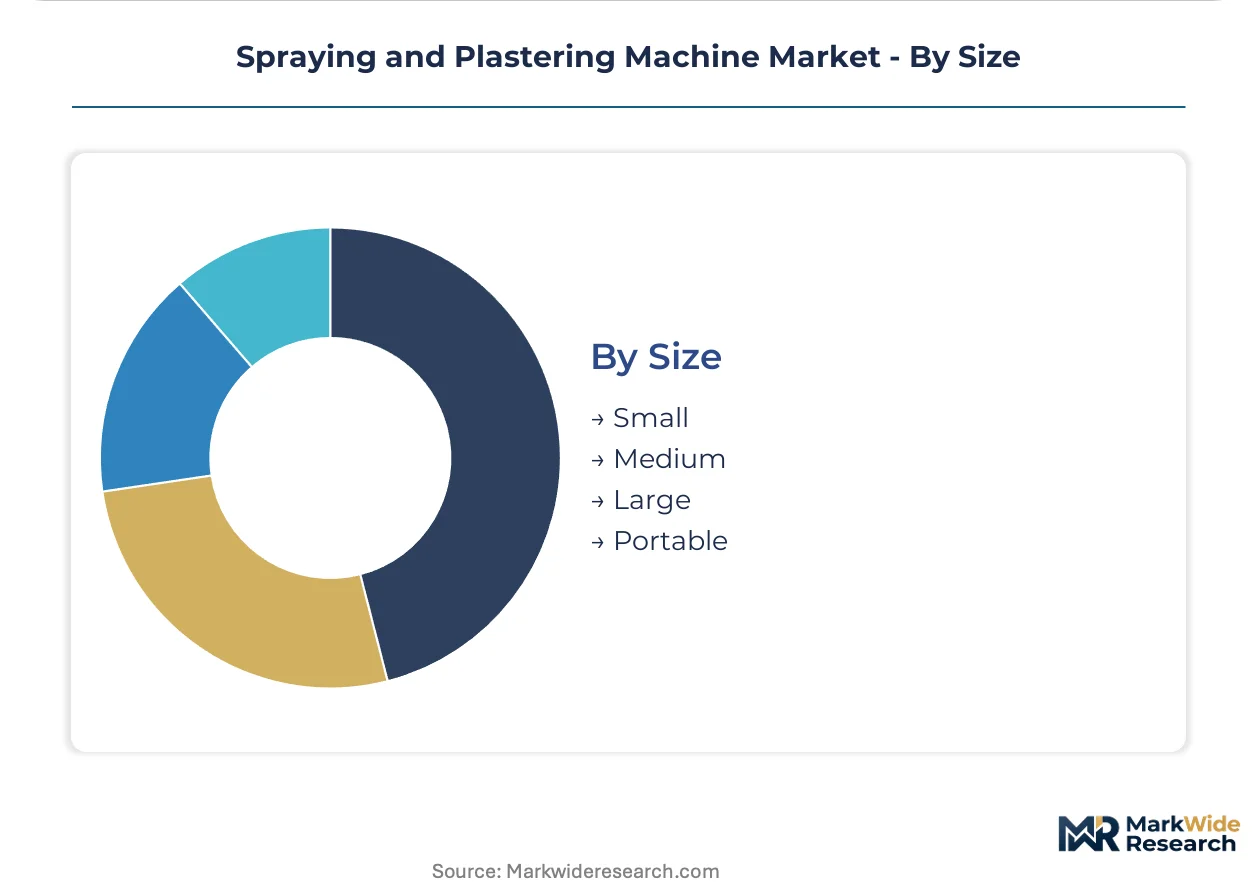
Size:
Mobility requirements and daily output targets trade off across equipment form factors.
- Small:Handheld and cart-mounted units under 25kg suit interior touch-up and detail work. DIY channels in German hardware retail stock these for residential renovation.
- Medium:Trailer-mounted plastering systems with 100-200 liter hoppers balance mobility with 15-25 square meter hourly output. Commercial mid-rise contractors in Netherlands and Belgium specify these for envelope completion under compressed schedules.
- Large:Truck-mounted continuous mixing and pumping systems serve high-rise shell construction. Indian affordable housing projects in Delhi NCR deploy these for 500+ unit phased developments.
- Portable:Compact battery-electric units with rapid-charge capability address urban retrofit constraints. German contractors specify these for sealed building envelope work where combustion equipment faces municipal restrictions.
Medium units capture margin concentration; Portable configurations are gaining share fastest on electrification and rental channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in Germany, India, the United States, France, and the Netherlands, where regulatory deadlines and infrastructure investment compress adoption timelines for mechanized plastering systems.
Germany
The Energy Efficiency Act mandates accelerated building envelope completion, forcing commercial contractors to retire manual troweling crews in favor of continuous-flow plastering systems. CE marking requirements under the EU Machinery Directive compel manufacturers to integrate dust suppression and electric powertrains. Berlin and Munich contractor pools lead fleet conversion, with mid-rise specialists investing in medium-capacity units to sustain 24-hour curing cycles.
India
Central government affordable housing targets concentrate demand in Mumbai, Delhi, and Bangalore, where tier-1 contractors expand mechanized fleets to meet compressed municipal inspection schedules. The PLI scheme for construction equipment manufacturing reduces import dependency for critical components. Delhi-NCR phased developments deploy truck-mounted continuous mixing systems for 500+ unit projects.
United States
OSHA silica exposure standards tighten permissible dust levels on commercial construction sites, accelerating specification of dust-suppressed electric sprayers for interior finishing. EPA regional air quality enforcement in California and New York Metro limits combustion equipment deployment on sealed building envelopes. Los Angeles and New York contractor fleets prioritize portable battery-electric configurations for urban retrofit compliance.
France
RE2020 environmental regulation mandates lifecycle carbon accounting for construction materials, compelling equipment manufacturers to certify compatibility with low-carbon gypsum and recycled-aggregate mortars. ANSM and CNIL oversight extends to workplace safety data collection on automated systems. Paris and Lyon commercial high-rise segments pre-qualify vendors on material certification breadth.
Netherlands
Municipal noise ordinances in Amsterdam and Rotterdam restrict combustion-powered equipment from residential retrofit channels, concentrating demand for battery-electric plastering systems with regenerative braking. The Dutch Building Decree accelerates energy performance deadlines for existing stock renovation. Rotterdam port maintenance yards drive airless sprayer specification for marine protective coatings crossover into architectural applications.
Spraying and Plastering Machine Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from application hardware into material certification and after-sales service unbundling. The vendor base clusters around three archetypes: German-engineered premium systems specialists, North American industrial coatings heritage players, and Asian fabricators serving volume-tier contractor fleets. Competitive positioning hardens through strategic partnerships with mortar formulators and rental fleet channel expansion. Technology licensing agreements for battery-electric powertrains and dust suppression modules accelerate product development cycles.
Within the premium systems tier, Putzmeister Holding GmbH and Sika AG occupy positions that exemplify divergent strategic paths. Putzmeister anchors German manufacturing heritage in large-scale plastering systems for commercial mid-rise and high-rise envelope completion. Sika AG represents material-hardware convergence, extending chemical compatibility expertise into application equipment specification. Graco Inc. sits within the industrial coatings crossover archetype, leveraging airless spraying heritage from marine and infrastructure maintenance into architectural finishing channels.
| Leading Market Players |
|---|
| Putzmeister Holding GmbH |
| Sika AG |
| Graco Inc. |
| IMER International SpA |
| Schwing Stetter Group |
| Normet |
| Kappa Building Machines Pvt. Ltd |
| ACME Equipment Pte Ltd |
| Zhengzhou Sincola Machinery Co., Ltd |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between CE-marked electric systems and unbranded pneumatic units manifests in pricing spreads exceeding 40 percent and supply chain fragmentation across German-engineered component clusters and Asian fabrication hubs. Premium tiers anchor in Stuttgart and Munich manufacturing bases where dust suppression modules and regenerative braking systems command material premiums, while economy tiers source rotor-stator pumps and hopper assemblies from Zhengzhou and Pune supplier networks.
Pricing Analysis
Volume concentration in medium-capacity plastering machines compresses margins to single-digit territory, while airless sprayers for marine protective coatings sustain premium positioning through transfer efficiency guarantees above 65 percent. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered continuous-flow systems from Italian pneumatic legacy units and Chinese battery-electric entrants. Cost compression in steel and aluminum hopper fabrication is intensifying because commodity index volatility erodes manufacturer visibility. Small residential renovators exhibit highest price sensitivity, deferring mechanization for projects under 500 square meters where mobilization costs exceed labor arbitrage.
Supply Chain Analysis
Single-source vulnerability sits with German-manufactured pressure control modules and Dutch-designed regenerative braking systems for battery-electric configurations. Component sourcing draws from China for rotor-stator pump housings, India for electric drive assemblies, and Germany for precision pressure sensors. Tariff exposure on steel and aluminum inputs threatens margin stability for hopper fabricators serving European contractor fleets. Distribution runs through direct manufacturer channels for tier-1 contractors in Mumbai and Delhi, while independent technical service networks handle aftermarket spare parts procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics technician scarcity constrains service capacity expansion, propping pricing power for manufacturers with captive maintenance networks and certified training pipelines.
For Market Incumbents: Extend aftermarket service bundling to offset hardware margin compression from Chinese battery-electric entrants. Acquire independent technical service networks in India's tier-1 cities to defend uptime guarantee positioning against Sika AG's material-hardware convergence strategy. Prioritize CE marking pre-certification for pending electrical safety standard revisions to lock out delayed competitors. For New Entrants and Emerging Players: The 25-35 percent price gap between premium German-engineered systems and economy pneumatic units opens white-space targeting for mid-tier contractors in Spain and Italy. Equipment-as-a-service rental models reduce capital barriers for builders with in-house finishing crews. Pursue material certification partnerships with low-carbon gypsum formulators to qualify under France's RE2020 lifecycle accounting rules. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by industrial coatings heritage players seeking architectural finishing crossover. Five-to-ten year viability favors manufacturers with integrated dust suppression and electric powertrain capabilities. Watch for CE marking revision finalization as inflection indicator for product launch velocity and certification cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Control Modules | Captive supply of German-engineered sensors defends margin against commodity volatility. |
| Material Certification Partnership | Low-carbon gypsum compatibility unlocks Paris and Lyon commercial high-rise pre-qualification. |
| Rental Fleet Channel Expansion | Equipment-as-a-service models penetrate Spanish and Italian mid-tier contractor capital constraints. |
| Mechatronics Training Pipeline Investment | Certified technician scarcity creates defensive moat for aftermarket service revenue capture. |
| Battery-Electric Powertrain Licensing | Technology agreements accelerate product development cycles for municipal noise ordinance compliance. |
Methodological Framework
Independent corroboration across equipment procurement directors at German commercial contractors, maintenance heads at Mumbai tier-1 fleets, and regulatory affairs leads at mortar formulation companies underwrites the qualitative findings. Secondary validation incorporated EU Machinery Directive documentation, BIS construction equipment standards, and customs records for rotor-stator pump imports. Bottom-up triangulation across product type, application vertical, and end-user capital access segments converged with top-down macroeconomic anchoring.
Comparable-period anchoring linked projection horizons to historical adoption curves for mechanized plastering systems in Germany's Energy Efficiency Act implementation phase. Segmentation dimensions modeled encompass power source architecture, project scale tier, and regional regulatory cluster intensity. CAGRs were derived from elasticity-adjusted penetration rates across the analysis window, incorporating steel and aluminum input cost trajectories and municipal inspection schedule compression in Indian tier-1 cities.
Inputs from primary contractor interviews and secondary regulatory filings were available through the study window; gaps in real-time fleet utilization telemetry introduce uncertainty bands around medium-capacity unit demand projections. Deviation in CE marking revision timing or battery-electric safety standard finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Die Casting Machinery Market
Construction Equipment and Machinery
Injection Molding Machine Market