
 India Faucet Market | 2026-2036
India Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
India Faucet Market Foresight
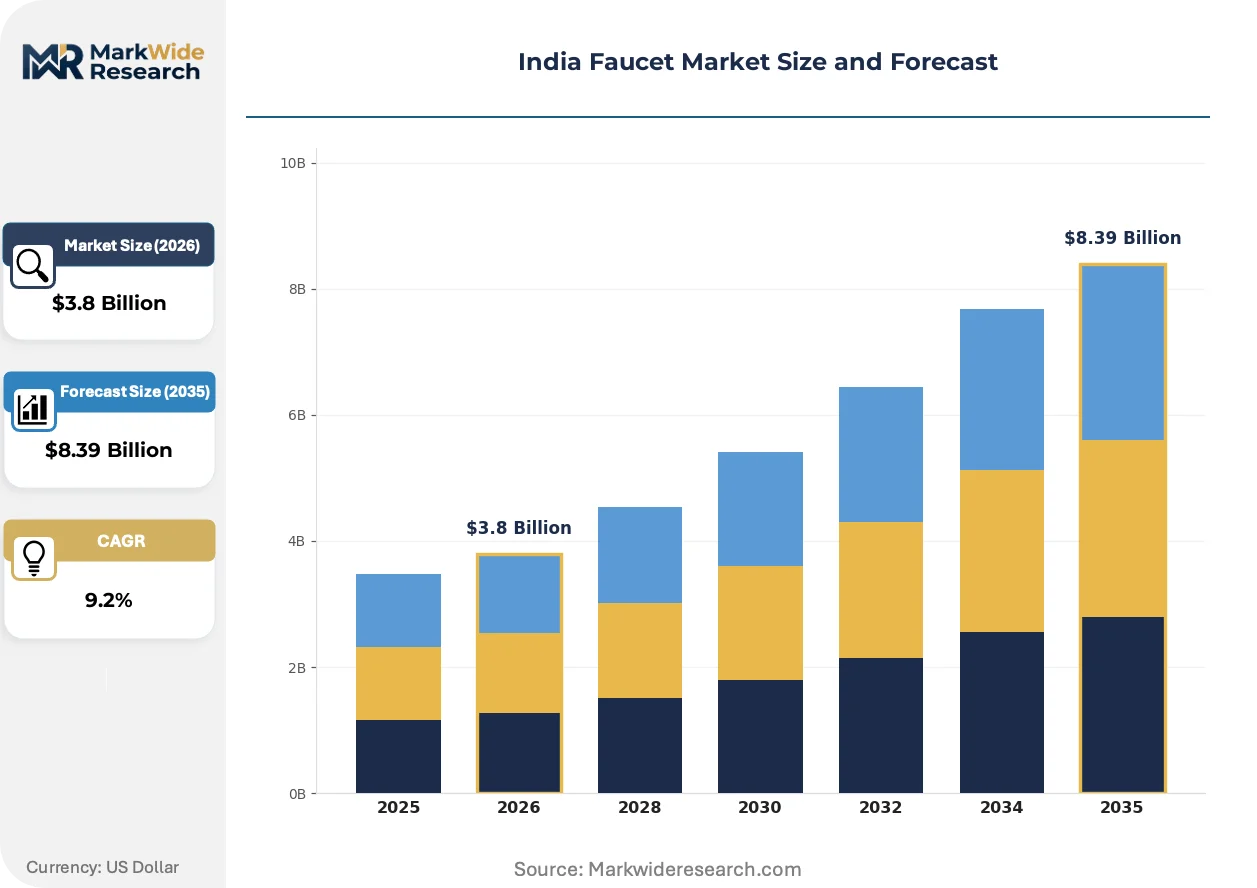
Gujarat's manufacturing corridor is rewriting supply dynamics for India's faucet industry. Jaquar sustains dominance through integrated brass casting operations in Gujarat and Kerala. Hindware leverages its distribution depth across 500-plus Indian towns to anchor mass-market penetration. Kohler competes in the premium segment through specialized design studios in Mumbai and Delhi.
A faucet is a valve-controlled plumbing fixture that regulates water discharge through ceramic disc or cartridge mechanisms, typically constructed from brass alloys with chrome or PVD surface finishing for corrosion resistance. It serves to control flow rate, temperature mixing, and water conservation in residential and commercial installations. Brass material commands the widest installed base due to machinability and durability, while stainless steel gains traction in coastal markets where salinity accelerates corrosion. Bathroom faucets generate the deepest margin pools as consumers prioritize aesthetic differentiation and sensor-based automation, whereas kitchen pull-out configurations represent the fastest-growing installation type among urban apartment developments.
BIS mandates IS 8931 standards for water efficiency and lead leaching limits, compelling manufacturers to reformulate brass compositions and upgrade testing protocols. CDSCO oversight intersects where antimicrobial surface claims require clinical validation, while state-level Jal Jeevan Mission implementations in Maharashtra and Tamil Nadu shape bulk procurement specifications for rural household connections. Stakeholders must monitor evolving state plumbing codes and BIS amendment cycles to anticipate compliance cost shifts.
Market Dynamics
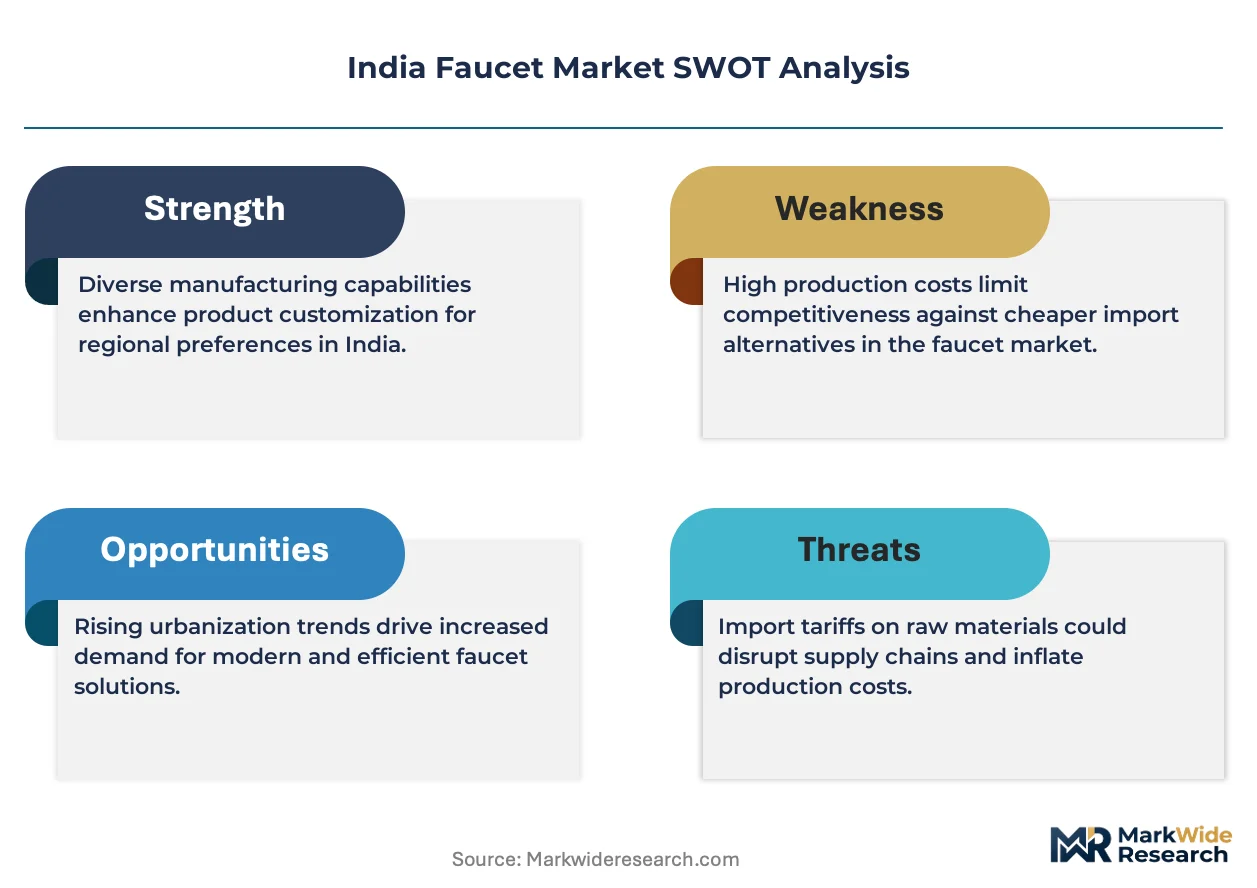
BIS certification mandates for water efficiency and lead content are compressing product development cycles while redrawing competitive boundaries across India's faucet landscape. Manufacturers must now absorb compliance costs or surrender market position to certified rivals.
Growth Catalysts
- Urban housing stock expansion:Apartment construction in Mumbai and Delhi is accelerating fixture replacement cycles. Developers specify sensor-equipped brass fittings to differentiate premium inventory.
- Jal Jeevan Mission procurement:Rural household connection targets in Maharashtra and Tamil Nadu are creating bulk demand for certified faucets. State agencies mandate BIS-compliant products for subsidy eligibility.
- Stainless steel corrosion resistance:Coastal salinity in Gujarat and Kerala is driving material substitution away from standard brass alloys. Marine-grade 304 stainless fixtures command durable installed bases.
Market Restraints
- Brass alloy input volatility:Copper and zinc price swings squeeze margin structures for casting-dependent producers. Smaller fabricators lack hedging capacity against London Metal Exchange fluctuations.
- Gujarat foundry concentration:Over half of domestic brass casting capacity clusters in the manufacturing corridor. Single-state disruption risks cascade through national supply networks.
- IS 8931 testing bottlenecks:BIS laboratory capacity constraints extend certification timelines to 12-16 weeks. Product launch delays favor incumbents with established approval pipelines.
Strategic Opportunities
- Tier-2 bathroom renovation:Pune and Hyderabad homeowners are upgrading from utilitarian to design-forward fittings. Aesthetic differentiation commands 40-60% price premiums over basic models.
- Sensor-automation convergence:Infrared proximity detection married to ceramic disc valves is penetrating commercial washroom specifications. Hospitality and healthcare verticals prioritize touchless hygiene protocols.
- E-commerce direct distribution:Platform logistics are disintermediating traditional plumbing merchant networks. Urban consumers research specifications online before requesting installation quotes.
Industry Challenges
- PVD coating technician scarcity:Physical vapor deposition surface finishing requires specialized vacuum chamber operation skills. Training pipelines lag equipment installation across Kerala and Tamil Nadu facilities.
- Lead-free alloy reformulation:BIS leaching limits below 5 micrograms per liter force brass composition changes. Metallurgical R&D cycles must validate machinability without sacrificing corrosion resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Faucet Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Faucets, Bathroom Faucets, Shower Faucets, Bathtub Faucets Material: Brass, Stainless Steel, Plastic, Chrome Installation Type: Wall-Mounted, Deck-Mounted, Freestanding, Pull-Out End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | CERA, Grohe, Jaquar, American Standard, Delta Faucet, Hindware, Roca, Parryware, Kohler, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Faucet Market Shifts & Advancements
Sensor-actuated flow control and antimicrobial surface treatments are redefining product specifications across residential and commercial installation channels. Manufacturers must now integrate electronics with traditional valve mechanics.
Thermostatic mixing cartridges with wax-element temperature regulation are rendering obsolete manual two-handle configurations in premium bathroom renovations. Mumbai and Delhi developers specify these for luxury apartment completions. The technology compresses price competition by tying margin to precision engineering rather than commodity brass casting.
BIS amendment cycles for IS 8931 are tightening water efficiency testing protocols and lead content thresholds. Foundries must recalibrate alloy compositions and invest in spectrometry verification equipment. Maharashtra-based manufacturers face the steepest compliance curves as state plumbing codes anticipate federal standard alignment.
Builder procurement is consolidating around certified vendor lists with pre-approved BIS documentation. Traditional plumbing merchants lose specification influence to direct manufacturer relationships with construction firms. Bangalore's high-rise residential sector exhibits the most concentrated buyer power, with single developers sourcing thousands of units annually.
India Faucet Market Segmentation
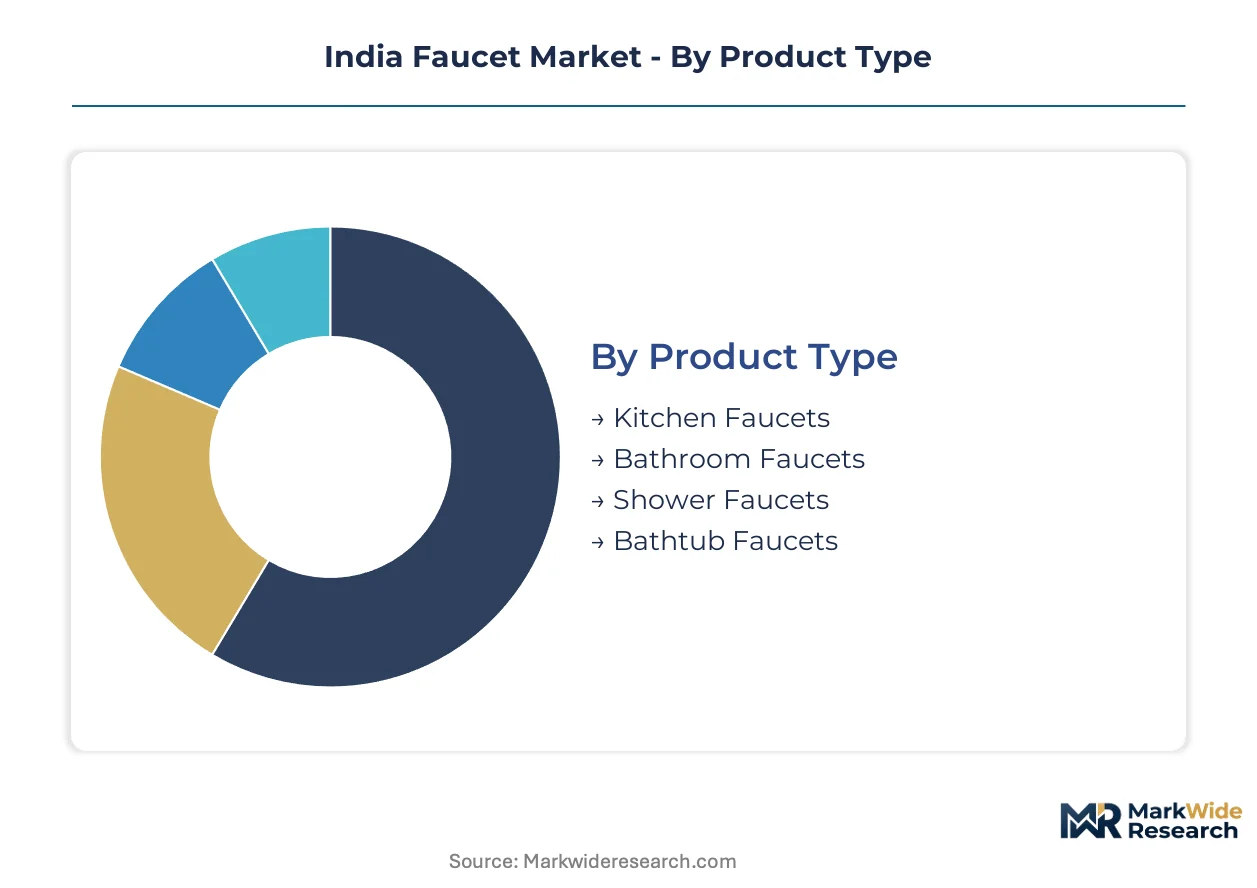
India's faucet market segments reflect divergent engineering requirements across residential construction, commercial hospitality, and industrial process applications. Each dimension—product type, material composition, installation mechanics, and end-use vertical—carries distinct margin profiles and certification burdens under BIS oversight.
Product Type:
Kitchen and bathroom applications anchor the use-case spectrum, with divergent priorities around water conservation versus aesthetic differentiation.
- Kitchen Faucets:Pull-out spray configurations with ceramic disc cartridges dominate urban apartment specifications. Mumbai developers specify these for compact counter layouts where flexible reach reduces sink redundancy.
- Bathroom Faucets:Single-lever thermostatic mixers command the deepest margin pools as Pune and Hyderabad homeowners prioritize design-forward finishes. Sensor-actuated variants are penetrating premium commercial washrooms.
- Shower Faucets:Pressure-balancing valves with wax-element temperature regulation serve high-rise installations where supply fluctuations threaten scald risk.
- Bathtub Faucets:Floor-mounted freestanding spouts with hand-shower diverters concentrate in luxury Delhi residential completions.
Established volume favors bathroom fittings; emerging adoption favors kitchen pull-out configurations.
Material:
Cost tier stratification separates casting-dependent producers from fabrication specialists, with coastal corrosion driving substitution patterns.
- Brass:Copper-zinc alloys with lead content below BIS-mandated thresholds remain the installed base majority. Gujarat foundries supply machined blanks to nationwide fixture assemblers.
- Stainless Steel:Marine-grade 304 and 316 compositions displace standard brass in Kerala and Gujarat coastal markets where salinity accelerates pitting corrosion.
- Plastic:ABS and polypropylene bodies serve Jal Jeevan Mission rural connections where cost minimization overrides durability expectations.
- Chrome:Electroplated surface layers over brass substrates provide the standard aesthetic finish across mass-market distribution channels.
Brass casting retains volume dominance; stainless steel exhibits the steepest expansion trajectory in corrosion-prone geographies.
Installation Type:
Application mechanics determine supply chain configuration, with wall-mounted specifications requiring embedded rough-in plumbing coordination.
- Wall-Mounted:Concealed valve bodies with exposed trim plates dominate Indian residential bathrooms where floor space constraints favor recessed installations.
- Deck-Mounted:Countertop penetration with integrated escutcheons serves kitchen islands and vanity configurations across Bangalore apartment stock.
- Freestanding:Floor-flange mounting with rigid supply risers concentrates in premium bathtub filler applications.
- Pull-Out:Retractable hose mechanisms with spray head docking represent the fastest-climbing kitchen specification among urban developers.
Wall-mounted fixtures retain specification frequency; pull-out mechanics gain share fastest in compact urban kitchens.
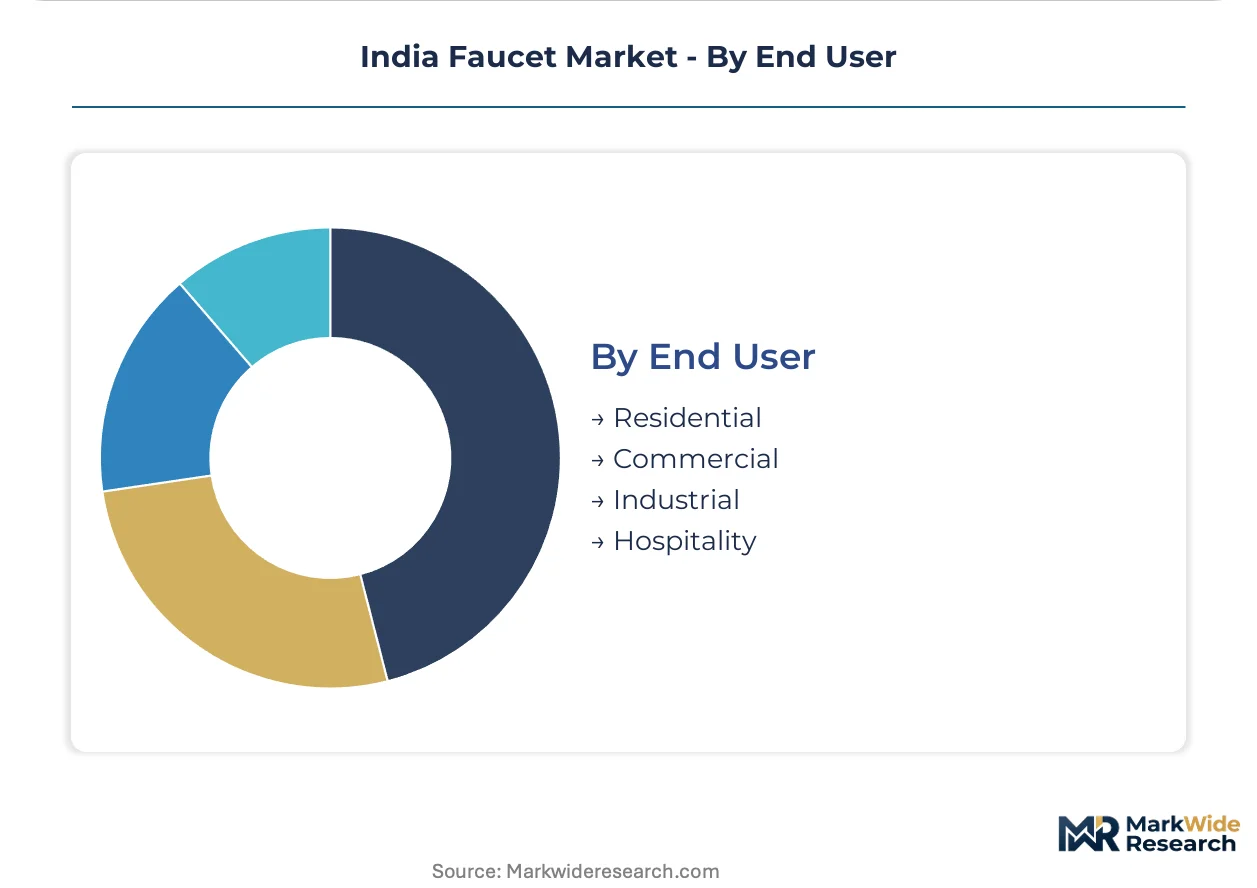
End User:
Customer type dictates procurement channel and certification stringency, with hospitality verticals imposing the most rigorous antimicrobial surface protocols.
- Residential:Individual homeowner purchases through plumbing merchants and e-commerce platforms generate fragmented demand across Maharashtra and Tamil Nadu renovation cycles.
- Commercial:Office building specifications prioritize sensor-actuated touchless protocols to reduce maintenance liability and water consumption.
- Industrial:Process water applications in manufacturing facilities require heavy-duty brass or stainless steel constructions with high-cycle durability ratings.
- Hospitality:Hotel and healthcare procurement mandates BIS certification plus CDSCO-validated antimicrobial claims for infection control compliance.
Residential channels aggregate the greatest unit volume; hospitality specifications command the strictest performance validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat consume faucets differently from Karnataka and Tamil Nadu. Western states prioritize brass casting supply chains and export-oriented production, while southern markets emphasize coastal corrosion resistance and sensor-automation adoption. This geographic divergence shapes procurement specifications and manufacturing investment patterns across the analysis window.
Maharashtra
Mumbai's high-rise residential construction drives specification for thermostatic mixing cartridges and concealed wall-mounted fixtures. State plumbing codes anticipate alignment with BIS IS 8931 amendments, accelerating compliance investments among Pune-based manufacturers. Jal Jeevan Mission rural household connection targets in Marathwada and Vidarbha generate bulk procurement demand for certified plastic-body faucets.
Gujarat
Surat and Ahmedabad anchor India's brass casting corridor, supplying machined blanks to nationwide fixture assemblers. BIS laboratory capacity constraints extend certification timelines, favoring incumbents with established approval pipelines. The manufacturing concentration creates single-state disruption risk that cascades through national supply networks during foundry shutdowns.
Karnataka
Bangalore apartment developers consolidate procurement around certified vendor lists with pre-approved BIS documentation, stripping traditional plumbing merchants of specification influence. State agencies mandate BIS-compliant products for Jal Jeevan Mission subsidy eligibility in rural districts. Coastal salinity in Mangalore accelerates stainless steel substitution away from standard brass alloys.
Tamil Nadu
Chennai's hospitality and healthcare procurement mandates BIS certification plus CDSCO-validated antimicrobial surface claims for infection control compliance. PVD coating technician scarcity constrains surface finishing capacity expansion across Kerala-bordering facilities. Rural household connection programs in delta districts shape bulk faucet specifications for cost-minimized ABS and polypropylene bodies.
Delhi-NCR
Luxury residential completions in Gurugram and Noida specify floor-mounted freestanding bathtub spouts with hand-shower diverters. E-commerce platform logistics disintermediate traditional plumbing merchant networks as urban consumers research specifications online. The National Capital Region exhibits concentrated buyer power with single developers sourcing thousands of units annually.
India Faucet Market Competitive Landscape
Capability concentration sits with integrated foundry operators; scale advantage sits with distribution-heavy mass-market penetrators. The market structures around three tiers: brass-casting specialists with captive alloy supply, merchant-assemblers sourcing machined blanks from Gujarat, and premium design studios importing European cartridge technology. Dominant competitive moves include backward integration into brass foundry operations and direct-to-developer procurement relationships that bypass traditional plumbing supply channels.
Among domestic integrated manufacturers, Jaquar and Hindware occupy distinct archetype positions. Jaquar exemplifies the foundry-integrated specialist with captive brass casting capacity in Gujarat and Kerala. Hindware represents the distribution-scale model, leveraging merchant network depth across hundreds of Indian towns. Kohler sits within the premium-tier import-reliant segment, competing through specialized design studios in Mumbai and Delhi rather than domestic manufacturing scale.
| Leading Market Players |
|---|
| CERA |
| Grohe |
| Jaquar |
| American Standard |
| Delta Faucet |
| Hindware |
| Roca |
| Parryware |
| Kohler |
| Others |
Supply & Pricing Matrix
Undercapacity across Gujarat foundries is tightening brass blank availability and compressing margin structures for non-integrated assemblers. BIS certification bottlenecks extend lead times to 12-16 weeks, forcing manufacturers to absorb compliance costs or surrender positioning to certified rivals with established approval pipelines.
Pricing Analysis
Project-based procurement dominates builder specifications, with Mumbai and Delhi developers negotiating volume discounts on thermostatic and sensor-equipped fittings. Price differentiation rests on BIS certification tier and ceramic cartridge origin, with European-sourced valve mechanisms commanding 40-60% premiums over domestic alternatives. Cost compression in mass-market brass fixtures is intensifying because copper and zinc volatility squeezes casting-dependent producers without hedging capacity. Jal Jeevan Mission rural procurement exhibits highest price sensitivity, while luxury residential buyers prioritize design-forward finishes over unit economics.
Supply Chain Analysis
Extended payment terms from Surat and Ahmedabad foundries are straining working capital for merchant-assemblers sourcing machined blanks. Geographic supply concentration centers on Gujarat brass casting, Kerala machining clusters, and Tamil Nadu surface finishing facilities. Raw material dependencies draw from London Metal Exchange copper-zinc contracts, marine-grade 304 stainless feedstock, and vacuum chamber PVD coating consumables. Single-state disruption risk cascades through national networks during foundry shutdowns. Distribution runs through direct manufacturer-developer relationships that disintermediate traditional plumbing merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's faucet market represents a high-growth disruption as BIS water efficiency mandates and lead-content thresholds force alloy reformulation across the installed base. Sensor-automation convergence with ceramic disc mechanics is compressing replacement cycles and redrawing competitive boundaries.
For Market Incumbents: Harden foundry-integrated positioning through captive brass casting capacity expansion in Gujarat and Kerala. Accelerate BIS certification pipeline investments to exploit 12-16 week laboratory bottlenecks that delay rival product launches. Defend against stainless steel substitution in coastal markets by validating marine-grade alloy machinability without sacrificing corrosion resistance.
For New Entrants and Emerging Players: Tier-2 bathroom renovation in Pune and Hyderabad offers penetrable white-space where aesthetic differentiation commands substantial premiums over utilitarian fittings. Target Jal Jeevan Mission rural procurement through cost-minimized ABS and polypropylene body configurations that prioritize subsidy eligibility over durability. Establish e-commerce direct distribution to disintermediate traditional plumbing merchant networks before incumbents consolidate platform logistics.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated foundry operators with captive alloy supply and established BIS approval pipelines. Five-to-ten year viability favors brass-casting specialists over merchant-assemblers exposed to input volatility and certification delays. Monitor PVD coating technician training pipeline expansion across Kerala and Tamil Nadu as inflection indicator for surface finishing capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Foundry Operations | Captive casting capacity insulates margin structures from London Metal Exchange copper-zinc volatility. |
| BIS Certification Pipeline Investment | Pre-approved documentation accelerates product launches amid 12-16 week laboratory bottlenecks. |
| Sensor-Automation Product Line Expansion | Infrared proximity detection penetrates hospitality and healthcare verticals prioritizing touchless hygiene protocols. |
| E-Commerce Direct Distribution Buildout | Platform logistics capture urban consumer research-to-purchase journeys before traditional merchant intervention. |
| Marine-Grade Stainless Steel Alloy Development | 304 and 316 compositions displace standard brass in Kerala and Gujarat coastal markets with salinity corrosion. |
Research Methodology
A spread of perspectives from brass foundry operators, ceramic cartridge suppliers, BIS laboratory technicians, Mumbai developer procurement heads, and Kerala plumbing merchant networks converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through BIS amendment documentation, state Jal Jeevan Mission procurement circulars, and customs records tracking copper-zinc alloy imports. Bottom-up unit economics triangulated against top-down construction completion data across Maharashtra, Gujarat, Karnataka, and Tamil Nadu.
Demand-supply balance modeling tracked housing stock expansion, rural household connection targets, and foundry capacity utilization across the projection horizon. Segmentation dimensions included product type, material composition, installation mechanics, and end-use vertical with geographic regulatory cluster overlays. CAGRs derived from weighted average of historical replacement cycles and policy-driven procurement inflections. Forecast inputs incorporated BIS IS 8931 amendment timing and state plumbing code alignment trajectories.
Practitioners should monitor copper-zinc price volatility, BIS laboratory capacity expansion, and state-level Jal Jeevan Mission target revisions for early signals. Forecasts reflect documented assumptions on alloy reformulation timelines and certification pipeline throughput. Macroeconomic construction slowdown, regulatory standard acceleration, or sensor-automation technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market