
 Japan Heavy Construction Equipment Rental Market | 2026-2036
Japan Heavy Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Heavy Construction Equipment Rental Market Insights
Maintenance-inclusive rental packages is pivoting how Japanese contractors procure heavy equipment, bunduring uptime guarantees with hourly usage models. Kanamoto leverages its nationwide depot network to offer same-day service commitments across prefectures. Hitachi Construction Machinery anchors premium positioning through integrated telematics that track fuel efficiency and fault codes. Komatsu differentiates via its KOMTRAX platform, extending remote diagnostics as a standard lease feature rather than an upsell.
Japan heavy construction equipment rental encompasses the temporary provision of earthmoving, lifting, and material-handling machinery with operating weights exceeding ten metric tons, typically governed by Japan's Construction Machinery and Vehicle Safety Regulations mandating annual third-party inspections. Excavators dominate rental fleet composition due to versatility across demolition, foundation, and utility trenching applications. Infrastructure developers represent the fastest-growing end-user category as public works budgets prioritize seismic retrofitting and flood-resilient transport corridors. Short-term rental commands margin concentration during disaster recovery windows and Olympic-legacy venue conversions, while long-term leasing absorbs predictable demand from metropolitan subway extensions.
METI's energy-efficiency benchmarks for construction machinery, alongside JIS standards for emission compliance and OSHA-aligned operator certification protocols administered by the Ministry of Health, Labour and Welfare, collectively elevate fleet renewal thresholds and bar grey-market imports. Stakeholders must monitor how Japan's carbon neutrality roadmap for 2050 translates into diesel-equipment phase-out timelines and electrified replacement schedules.
Market Dynamics
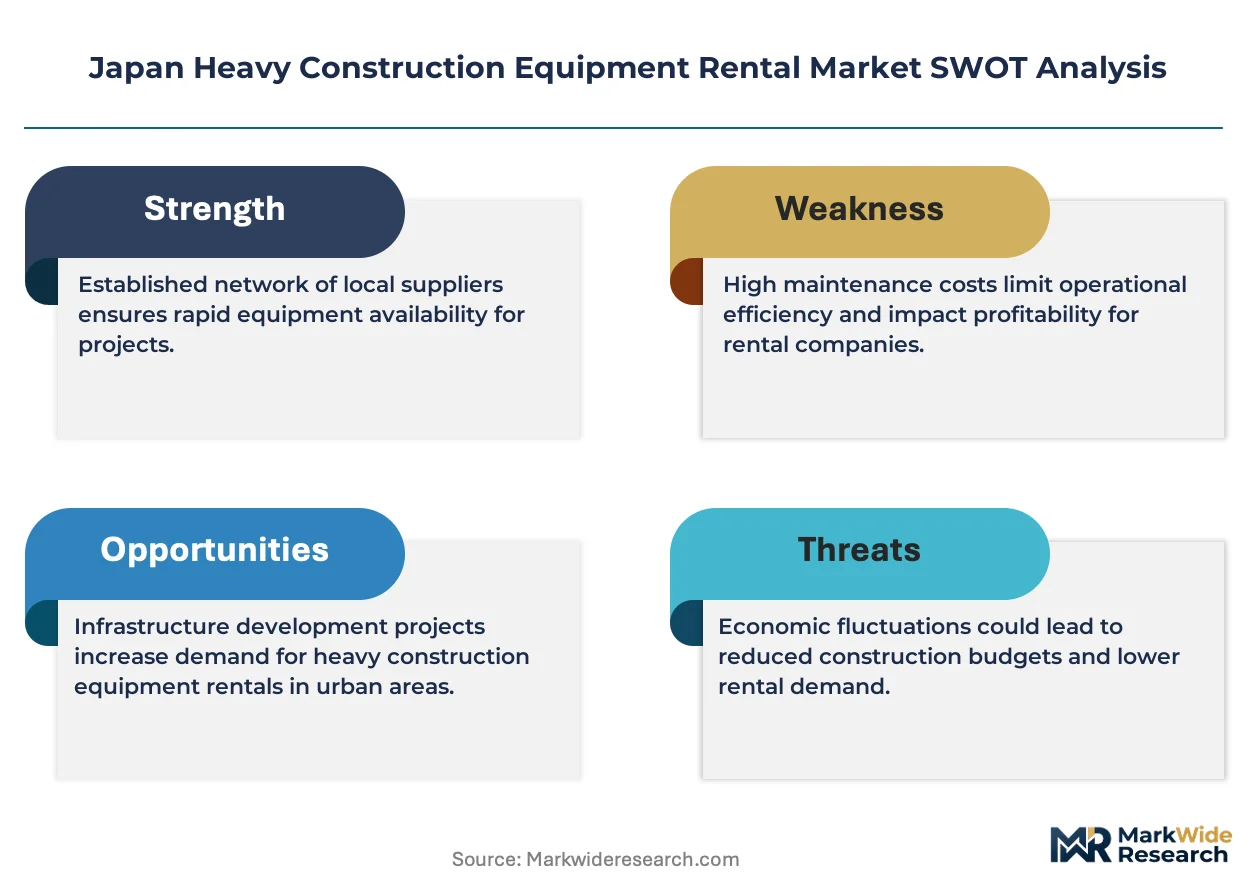
Japan's amended Construction Recycling Act is compressing equipment replacement cycles while METI's energy-efficiency benchmarks force fleet operators toward electrified assets. This dual regulatory pressure is restructuring rental economics across Honshu infrastructure corridors.
Growth Catalysts
- Seismic retrofitting mandates:Japan's Building Standards Act revisions are accelerating public works budgets for earthquake-resistant transport corridors. Infrastructure developers are expanding excavator and crane utilization across metropolitan subway extensions.
- Telematics integration:Remote diagnostics platforms are embedding uptime guarantees into standard lease terms. Equipment lessors are bundling fuel-efficiency tracking with hourly usage models.
- Disaster recovery windows:Short-term rental demand concentrates during typhoon rehabilitation periods. Fleet operators capture margin premiums through rapid-deployment service commitments.
Market Restraints
- Diesel-equipment phase-out uncertainty:Japan's 2050 carbon neutrality roadmap lacks concrete construction machinery timelines. Rental operators face stranded-asset risk on high-horsepower fleet segments.
- Grey-market import barriers:JIS emission compliance standards and Ministry of Health, Labour and Welfare operator certification protocols block low-cost foreign equipment. Fleet renewal costs concentrate with domestic OEMs.
- Skilled operator scarcity:OSHA-aligned certification requirements create bottlenecks for crane and excavator deployment. Project timelines extend during labor shortage periods.
Strategic Opportunities
- Electrified compact equipment:Battery-powered excavators below twenty metric tons are penetrating urban renewal sites. Tokyo's density restrictions favor zero-emission machinery for confined foundation work.
- Maintenance-inclusive contracts:Uptime-guarantee pricing is displacing traditional dry-hire arrangements. Contractors in Osaka and Nagoya are adopting total-cost-of-ownership models.
- Flood-resilient infrastructure:River embankment reinforcement projects are sustaining long-term leasing demand. Prefectural governments are prioritizing climate-adaptive transport corridors.
Industry Challenges
- Third-party inspection bottlenecks:Japan's Construction Machinery and Vehicle Safety Regulations mandate annual certification. Depot networks face scheduling congestion during peak construction seasons.
- Legacy fleet integration:Telematics retrofitting of pre-2020 assets creates compatibility friction. Rental operators balance connectivity investment against residual value compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Heavy Construction Equipment Rental Market |
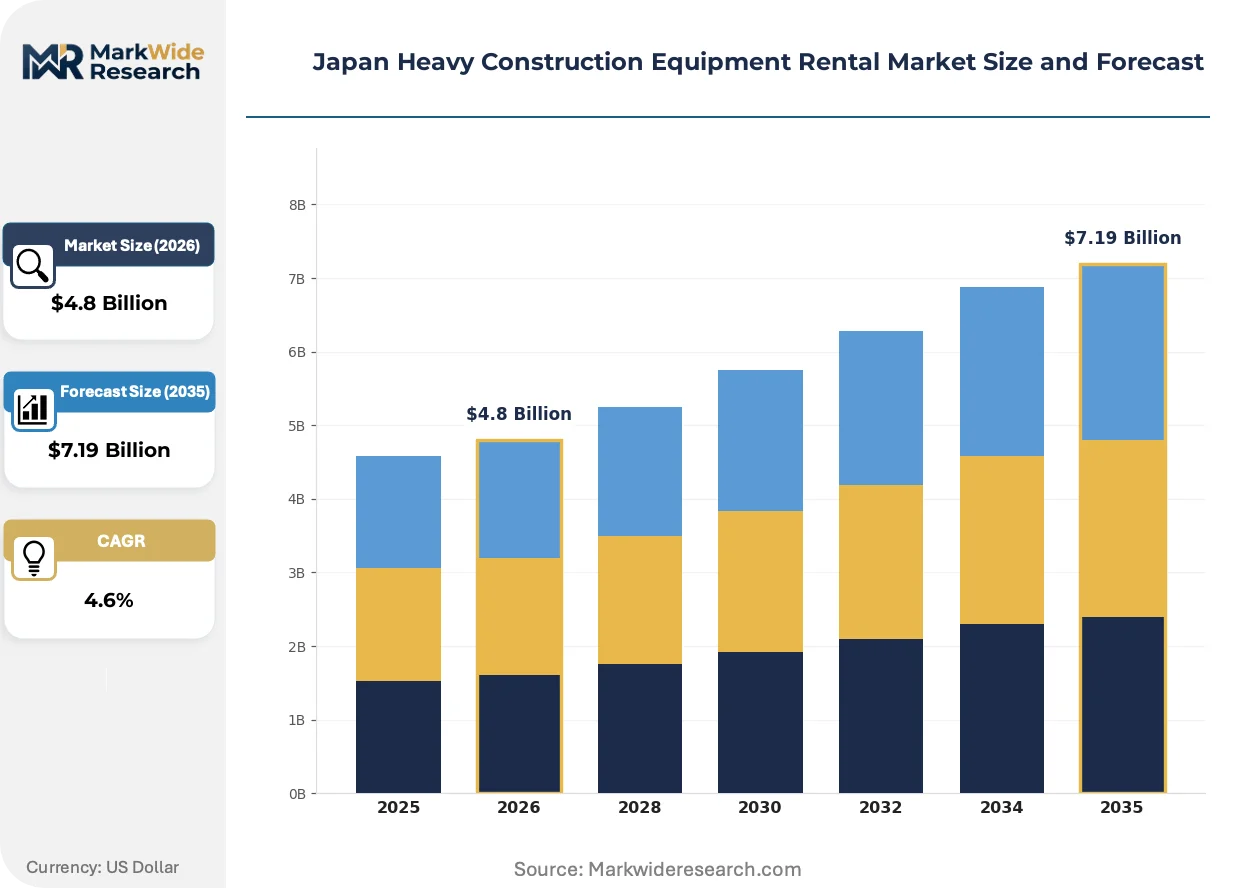
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders End User: Construction Firms, Infrastructure Developers, Mining Companies, Government Contractors Service Type: Short-Term Rental, Long-Term Rental, Leasing, Maintenance Services Deployment Mode: On-Site, Off-Site, Mobile Services, Remote Operations |
| Companies Covered | Nikken Corporation, Rent Corporation, Kanamoto, Hitachi Construction Machinery, Komatsu, Nishio Rent All, Taiyo Kenki Rental, Kobelco, AKTIO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Heavy Construction Equipment Rental Market Trends and Innovations
Digital fleet management and predictive maintenance protocols are rewriting how Japanese contractors assess total equipment cost. Regulatory pressure on emissions and safety certification is accelerating technology adoption across rental portfolios.
Battery-electric drivetrains are rewriting competitive positioning in urban construction zones. Compact excavators with lithium-ion powertrains are penetrating Tokyo foundation projects where noise and emission restrictions apply. Municipal contractors are specifying zero-emission machinery for Olympic-legacy venue conversions, compressing diesel-equipment residual values in metropolitan fleet rotations.
METI's energy-efficiency benchmarks are mandating fuel-consumption disclosure across rental contracts. Infrastructure developers in the Greater Tokyo Area are embedding efficiency clauses into long-term leasing agreements. Fleet operators are responding with telematics-verified performance guarantees that align hourly rates with actual fuel economy.
Outcome-based rental agreements are displacing traditional dry-hire models in Japan's heavy equipment sector. Contractors are prioritizing uptime commitments over asset ownership, particularly for specialized crane deployments on rail and highway projects. Kanamoto's same-day service network and Hitachi's integrated diagnostics are setting performance standards that smaller regional lessors struggle to match.
Japan Heavy Construction Equipment Rental Market Segmentation
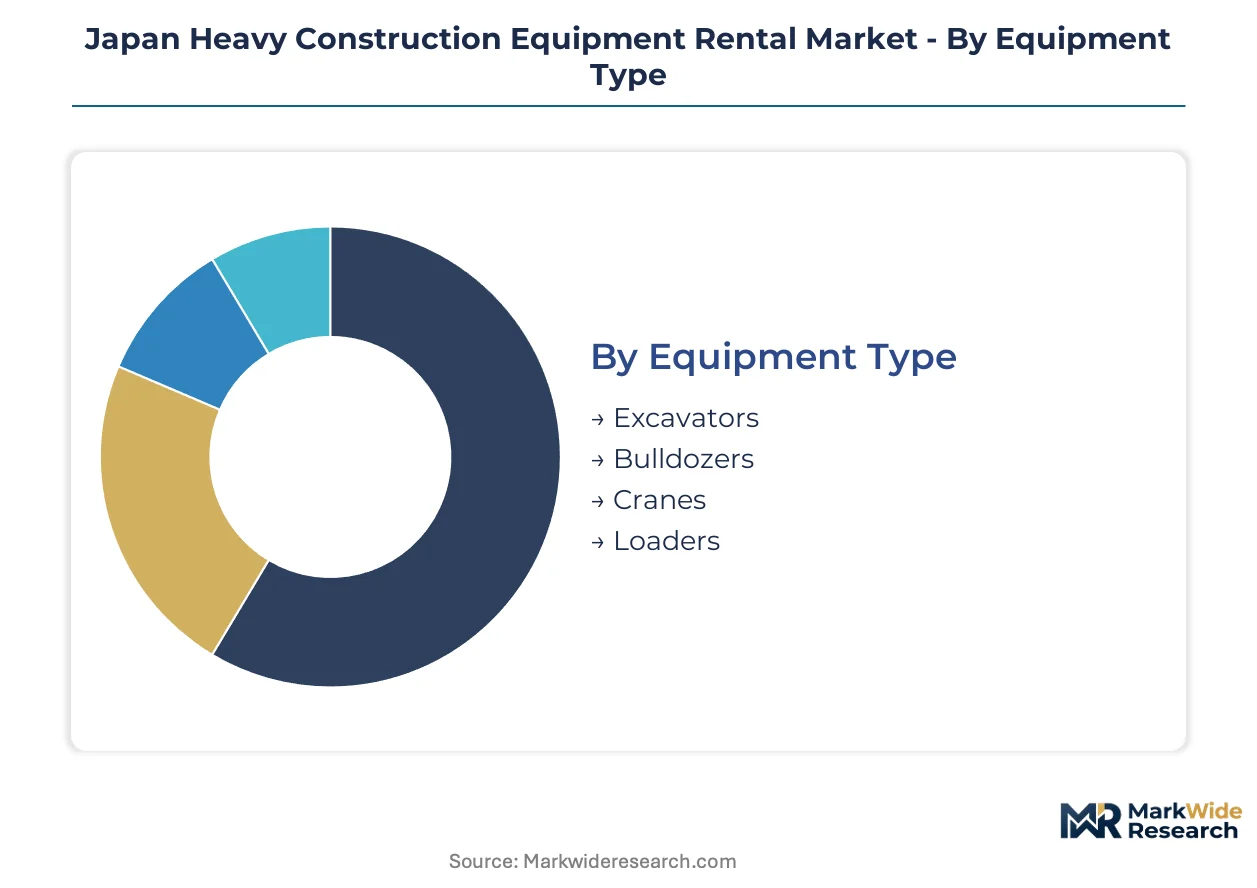
Equipment segmentation in Japan's rental market directly shapes fleet renewal economics and regulatory compliance pathways. Rental operators structure procurement and depreciation schedules around distinct equipment lifecycles and end-use concentration patterns.
Equipment Type:
Replacement cycles vary sharply across equipment categories as METI efficiency benchmarks and the amended Construction Recycling Act force differential upgrade timelines.
- Excavators:Hydraulic machines with operating weights from ten to forty metric tons dominate rental composition through versatility across demolition, foundation work, and utility trenching. Greater Tokyo Area urban renewal density sustains hourly utilization rates above fleet averages, particularly for compact models under twenty metric tons where electrification is penetrating first.
- Cranes:Mobile and crawler configurations serve rail and highway projects across Honshu with extended boom reach requirements. Infrastructure developers expanding seismic retrofitting programs are accelerating crawler crane deployments for heavy-lift bridge segments, though skilled operator scarcity constrains rapid fleet scaling.
- Bulldozers:Tracked earthmovers with blade capacities optimized for grading and embankment work face compressed residual values as diesel-phase-out uncertainty clouds long-term leasing demand.
- Loaders:Wheel and track configurations for material handling concentrate in metropolitan subway extension sites where rapid cycle times prioritize fuel efficiency.
Volume placements concentrate in excavators; the faster expansion belongs to cranes.
End User:
Customer type determines contract structure, with infrastructure specialists driving long-term leasing and commercial builders favoring flexible short-term arrangements.
- Infrastructure Developers:Public works contractors managing rail corridors, highway expansions, and flood-resilient transport networks command multi-year leasing agreements with uptime guarantees. METI energy-efficiency disclosure requirements are embedding fuel-performance clauses into standard contract templates.
- Construction Firms:Private-sector builders across Osaka and Nagoya metropolitan zones prioritize maintenance-inclusive packages that transfer downtime risk to lessors. Kanamoto's same-day service commitments are reshaping procurement expectations in this segment.
- Government Contractors:Prefectural and municipal agencies specify JIS-compliant equipment with telematics integration for Olympic-legacy venue conversions and disaster recovery mobilization.
- Mining Companies:Surface extraction operators in limited domestic quarrying applications require high-horsepower configurations facing stranded-asset exposure under carbon neutrality roadmaps.
Revenue concentration sits with infrastructure developers; construction firms are gaining share fastest through maintenance-bundle adoption.
Service Type:
Contract duration and risk allocation structures are pivoting as outcome-based models displace traditional dry-hire economics.
- Long-Term Rental:Multi-year agreements spanning metropolitan subway extensions and river embankment reinforcement projects absorb predictable demand with fixed-rate structures. Fleet operators balance depreciation schedules against residual value compression from electrification timelines.
- Short-Term Rental:Daily and weekly arrangements capture margin premiums during typhoon rehabilitation windows and emergency seismic response deployments. Rapid-deployment service commitments command pricing power in disaster recovery corridors.
- Leasing:Finance-lease structures with ownership transfer options appeal to government contractors with capital budget constraints and extended project horizons.
- Maintenance Services:Bundled uptime guarantees with telematics-verified performance metrics are displacing unbundled service arrangements across Greater Tokyo Area contractor portfolios.
Contract value concentrates in long-term rental; maintenance-inclusive bundles are climbing the fastest.
Deployment Mode:
Service delivery configuration shapes depot network investment and technician dispatch economics across Japan's prefectural geography.
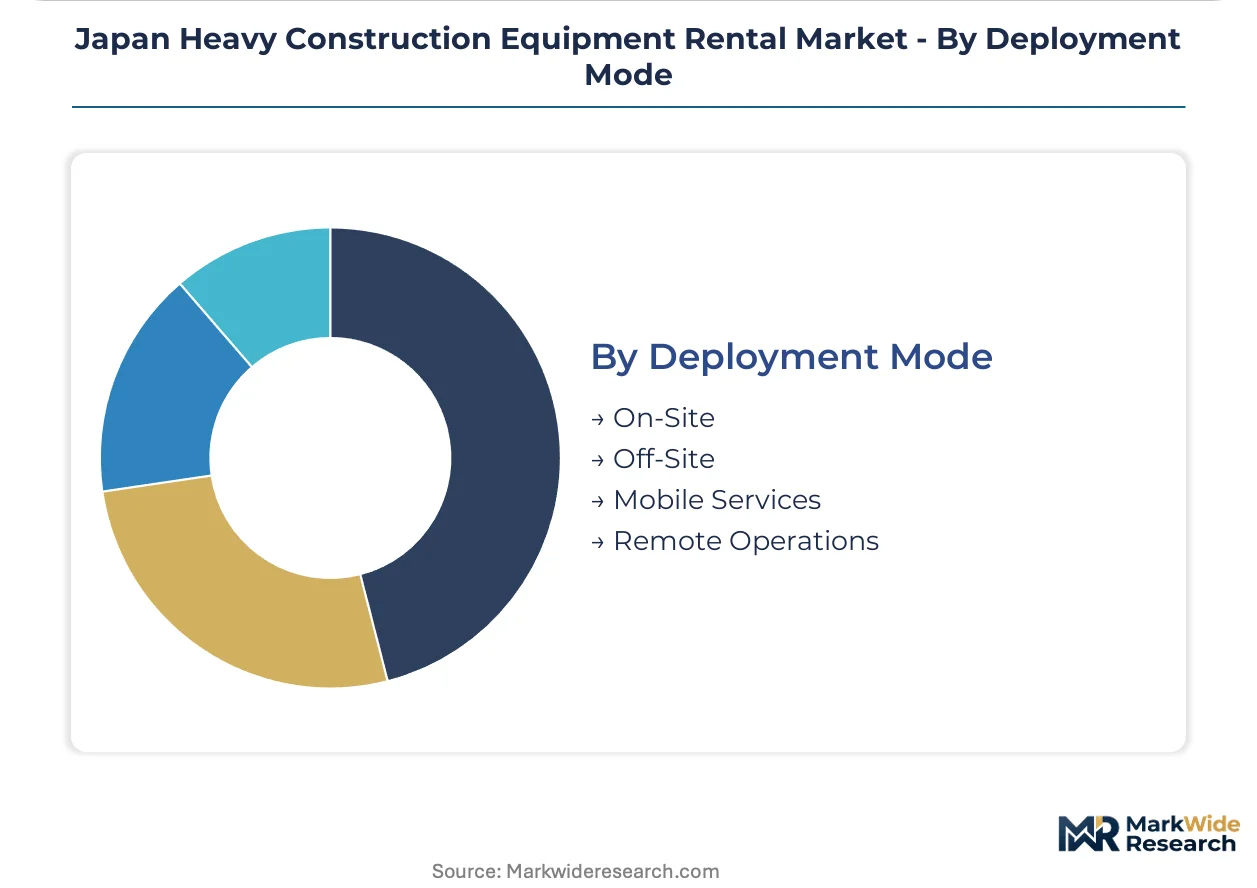
- On-Site:Equipment stationed at continuous construction locations with dedicated maintenance support dominates metropolitan subway extension and highway corridor projects. Depot proximity to Honshu infrastructure corridors determines competitive positioning.
- Mobile Services:Rapid-deployment technicians with portable diagnostic equipment serve disaster recovery windows and emergency retrofitting mobilizations. Fleet operators with nationwide depot networks capture premium pricing through guaranteed response times.
- Off-Site:Centralized yard locations with transport coordination apply to standardized equipment categories with lower utilization urgency.
- Remote Operations:Telematics-enabled diagnostics and KOMTRAX-style platform integration are embedding remote monitoring as a standard feature rather than upsell across premium contract tiers.
Deployment investment concentrates in on-site arrangements; mobile services are gaining share fastest through disaster-response specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's heavy construction equipment rental market concentrates equipment production in industrial prefectures while consumption clusters around metropolitan infrastructure corridors. Fleet deployment patterns follow Honshu's urban density gradient rather than manufacturing geography.
Kanto/Tokyo
Seismic retrofitting mandates and Olympic-legacy venue conversions drive excavator and crane utilization across Greater Tokyo. METI energy-efficiency benchmarks force fleet operators toward electrified compact equipment below twenty metric tons. Urban renewal density in central Tokyo sustains premium rental rates for zero-emission machinery in confined foundation work.
Kansai/Osaka
Metropolitan subway extensions and river embankment reinforcement projects absorb predictable long-term leasing demand. Maintenance-inclusive contracts are displacing traditional dry-hire arrangements as contractors adopt total-cost-of-ownership models. Osaka-based construction firms prioritize uptime guarantees over asset ownership for specialized deployments.
Chubu/Nagoya
Highway corridor expansions and rail infrastructure projects anchor crawler crane demand across Aichi Prefecture. JIS emission compliance standards and Ministry of Health, Labour and Welfare operator certification protocols elevate fleet renewal thresholds. Nagoya's industrial logistics zones sustain loader utilization for material handling at metropolitan construction sites.
Kyushu
Typhoon rehabilitation windows generate concentrated short-term rental demand with rapid-deployment service premiums. Disaster recovery mobilizations command pricing power through guaranteed technician response times. Fukuoka's depot networks capture margin concentration during emergency seismic response deployments.
Tohoku
Flood-resilient transport corridor investments sustain bulldozer and excavator leasing for embankment reinforcement. Prefectural governments prioritize climate-adaptive infrastructure with multi-year equipment stationing at continuous construction locations. Sendai's reconstruction legacy maintains elevated public works equipment density.
Japan Heavy Construction Equipment Rental Market Competitive Landscape
Top-tier vendors anchor nationwide depot networks with same-day service commitments, while regional specialists concentrate on prefecture-level rapid-response capabilities. The market structures around three tiers: integrated OEM-lessors with telematics platforms, independent rental chains with maintenance bundling, and local operators serving disaster-recovery niches. Dominant competitive moves include telematics integration into standard lease terms and electrified fleet procurement ahead of regulatory phase-out timelines.
Within the integrated OEM-lessor tier, Hitachi Construction Machinery and Komatsu anchor premium positioning through remote diagnostics platforms that embed uptime guarantees into contract structures. Kanamoto represents the independent rental chain archetype with its nationwide depot network enabling rapid-deployment service commitments across prefectures. Nishio Rent All occupies a position among regional specialists concentrating on maintenance-inclusive packages that transfer downtime risk to lessors.
| Leading Market Players |
|---|
| Nikken Corporation |
| Rent Corporation |
| Kanamoto |
| Hitachi Construction Machinery |
| Komatsu |
| Nishio Rent All |
| Taiyo Kenki Rental |
| Kobelco |
| AKTIO Corporation |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive maintenance networks anchors competitive positioning for Japan's heavy equipment rental operators, concentrating pricing power with depot-dense providers who bundle technician dispatch guarantees into hourly rate structures. Kanamoto's nationwide service commitments and Hitachi's integrated telematics platforms demonstrate how vertical control over uptime delivery translates into premium contract capture across metropolitan infrastructure corridors.
Pricing Analysis
Cost-down pressure on standard-tier rentals accelerates as METI energy-efficiency disclosure requirements force fleet operators to absorb telematics investment without full rate recovery. Three-tier pricing structure across premium telematics-inclusive, standard maintenance-bundled, and economy dry-hire levels separates Hitachi and Komatsu's diagnostic-embedded offerings from regional lessors. Infrastructure developers show lowest price sensitivity due to uptime-critical project timelines, while small construction firms in Osaka and Nagoya drive hardest bargain on hourly rates.
Supply Chain Analysis
Single-source vulnerability sits with domestic OEM dependency for JIS-compliant machinery, as Japan's emission standards and Ministry of Health, Labour and Welfare certification protocols block grey-market alternatives. Equipment manufacturing concentrates in Japan, with critical hydraulic components and precision-engineered undercarriages drawing from domestic specialty suppliers and select German and South Korean component sources. Tariff exposure on steel alloys and semiconductor-dependent control systems elevates fleet procurement risk. Distribution runs through regional depot networks with technician dispatch radii determining service coverage economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's heavy construction equipment rental market is consolidating around telematics-enabled service capabilities, with METI regulatory pressure and electrification timelines forcing sub-scale operators toward exit or acquisition.
For Market Incumbents: Acquire electrified compact excavator fleets below twenty metric tons to preempt Tokyo's zero-emission foundation work specifications. Deepen backward integration into predictive maintenance software by licensing or developing proprietary diagnostics platforms that match Komatsu's KOMTRAX standard. Defensive positioning requires same-day service radius compression in Greater Tokyo Area before Kanamoto extends depot density further. For New Entrants and Emerging Players: Battery-electric drivetrain specialization offers entry wedge into urban renewal segments where noise and emission restrictions exclude diesel incumbents. Target short-term disaster recovery rental in Kyushu and Tohoku where rapid-deployment capabilities command premium pricing and incumbent depot coverage remains thinner. Go-to-market angle should emphasize guaranteed technician response times under maintenance-inclusive contracts that transfer downtime risk from contractors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated OEM-lessors seeking regional depot networks, with financial sponsor roll-up strategies viable for maintenance-bundled independent chains. Long-term viability favors operators with electrified fleet exposure and telematics platform integration. Signal to watch is METI's diesel-equipment phase-out timeline announcement, which would accelerate stranded-asset risk for legacy fleet holders and trigger acquisition discounting.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Fleet Procurement | Battery-powered excavators penetrate Tokyo's confined foundation work where emission restrictions apply. |
| Telematics Platform Integration | Remote diagnostics embedding uptime guarantees displaces traditional dry-hire contract economics. |
| Maintenance-Inclusive Contract Expansion | Total-cost-of-ownership models transfer downtime risk and lock in multi-year revenue streams. |
| Depot Network Densification | Same-day service commitments in Greater Tokyo Area capture premium pricing from infrastructure developers. |
| Disaster Recovery Specialization | Rapid-deployment capabilities in Kyushu command margin premiums during typhoon rehabilitation windows. |
Research Methodology
Trade association filings, METI energy-efficiency benchmark disclosures, and JIS standard documentation formed the secondary backbone, cross-referenced with primary interviews involving fleet operations directors at rental chains, procurement managers at infrastructure developers, maintenance technicians at regional depots, and regulatory compliance officers at OEMs. Bottom-up equipment fleet sizing triangulated against top-down public works budget allocation analysis validated market scope across the analysis window.
Historical utilization rate trends and replacement cycle patterns informed projection modeling across equipment type, end-user category, service contract structure, and deployment mode dimensions. CAGRs were derived from segmented demand elasticity analysis incorporating seismic retrofitting program timelines, Olympic-legacy venue conversion schedules, and electrification adoption curves. Forecast inputs included prefectural construction permit data and METI machinery shipment statistics.
Several conditions sit outside the modeled scope, including specific carbon neutrality enforcement dates for diesel equipment and potential JIS standard revisions. Forecasts reflect documented assumptions regarding public works budget continuity and skilled operator certification pipeline capacity. Deviation in METI's phase-out timeline announcement or major seismic event frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Submerged Arc Welding Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
4-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Piles Turner Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
US Welding Consumables Market