
 Tobacco Alternative Gum Market | 2026-2036
Tobacco Alternative Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Tobacco Alternative Gum Market Analytics
Asset-light contract manufacturing and white-label licensing is rewriting competitive economics in tobacco alternative gum. Fertin Pharma leverages its Danish manufacturing base to supply private-label brands across European pharmacies. Johnson & Johnson sustains premium positioning through clinical-channel relationships and regulatory dossier depth. ITC Limited anchors South Asian distribution with pan-India retail coverage and paan-masala crossover brand equity.
Tobacco alternative gum comprises chewable polymer bases—typically gum acacia, polyol plasticizers, and active payloads such as nicotine polacrilex, caffeine, or herbal extracts—delivered via buccal absorption for rapid systemic uptake without pulmonary exposure. Sugar-free formulations lead volume as dental health claims broaden addressable demand beyond cessation into general wellness. Online retail represents the fastest-growing distribution channel, though pharmacies still capture the highest margin pool due to pharmacist consultation attachment and reimbursement eligibility.
The FDA regulates nicotine gum as an over-the-counter drug under monograph standards, while the EMA and national EU regulators enforce the Tobacco Products Directive and MDR classification for higher-dose formats. REACH compliance for flavoring chemistry and the EU Green Deal packaging mandates are forcing reformulation of synthetic cooling agents and single-use blister formats. Stakeholders must monitor whether the FDA extends Deeming Rule enforcement to novel non-nicotine functional gums, as that threshold determination will reshape which entrants require pre-market authorization and clinical substantiation.
Market Dynamics
Workplace wellness mandates and tightening nicotine labeling rules are compressing demand toward non-nicotine functional formulations, while contract manufacturing economics fragment brand ownership from production capacity.
Growth Catalysts
- Employer-sponsored cessation coverage:Large North American corporations now subsidize gum-based nicotine replacement therapy through health benefit plans, converting occupational health budgets into recurring procurement contracts.
- REACH compliance deadlines:ECHA enforcement of synthetic cooling agent restrictions is accelerating reformulation toward botanical extract bases that bypass chemical registration thresholds.
- Polyol plasticizer advances:New sorbitol-xylitol blends extend chew duration from 15 to 30 minutes, improving nicotine bioavailability curves and patient adherence metrics.
Market Restraints
- Gum acacia supply volatility:Sudan and Chad supply 80% of pharmaceutical-grade gum acacia; political instability creates raw material price spikes that contract manufacturers cannot pass through in white-label agreements.
- FDA Deeming Rule uncertainty:The agency's pending classification of non-nicotine functional gums as either cosmetics or drugs creates pre-market authorization risk that freezes R&D pipelines.
- Pouch nicotine substitution:Oral nicotine pouches deliver faster buccal absorption without mastication fatigue, capturing switchers from dual-use smokers who find gum texture repetitive.
Strategic Opportunities
- Indian pharmacy modernization:CDSCO's streamlined OTC notification pathway allows foreign manufacturers to bypass clinical trial requirements for sub-4mg nicotine polacrilex formats.
- Caffeine-adaptogen convergence:Combining L-theanine and ginseng with caffeine payloads targets productivity-focused consumers in professional services sectors.
- Direct-to-employer distribution:Bypassing pharmacy markup through corporate wellness platform integrations captures subscription revenue with 40% lower customer acquisition cost.
Industry Challenges
- Flavor chemist scarcity:Reformulation of synthetic cooling agents under REACH requires rare expertise in natural terpene extraction that European flavor houses monopolize.
- Blister-to-sachet conversion capex:EU Green Deal packaging mandates force retooling of thermoforming lines to paper-based sachets, stranding $2-4 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobacco Alternative Gum Market |
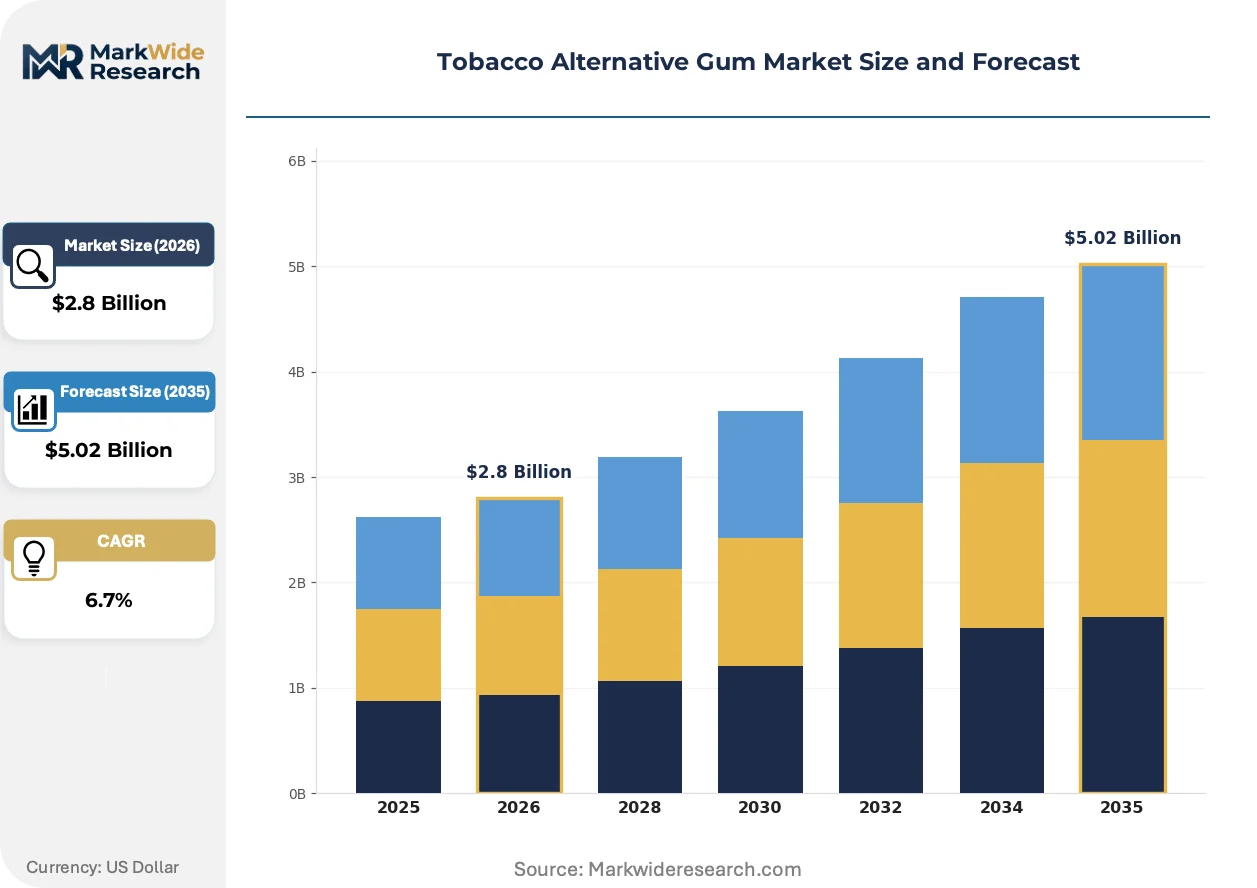
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caffeinated Gum, Herbal Gum, Nicotine-Free Gum, Sugar-Free Gum Distribution Channel: Convenience Stores, Online Retail, Pharmacies, Supermarkets Target Customer: Health-Conscious Consumers, Smokers Looking to Quit, Athletes, Casual Users Flavor Profile: Mint, Fruit, Spicy, Coffee |
| Companies Covered | British American Tobacco, Johnson & Johnson, Novartis AG, Perrigo Company, Philip Morris International, GlaxoSmithKline, Pfizer, Fertin Pharma, ITC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobacco Alternative Gum Market Evolving Landscape
Digital therapeutics integration and polymer science advances are redefining efficacy claims beyond simple nicotine delivery, while regulatory arbitrage between drug and food classifications creates formulation strategy divergence.
Microencapsulated nicotine polacrilex using ethyl cellulose coatings enables burst-lag-burst release profiles that mimic cigarette nicotine spikes more accurately than conventional ion-exchange resins. Smoking cessation clinics in Germany and the United Kingdom are prescribing these formats as first-line therapy. This pharmacokinetic precision is virtualizing the clinical trial endpoint from abstinence rates to withdrawal symptom severity curves.
The FDA's 2023 proposal to extend Deeming Rule enforcement to novel non-nicotine functional gums would reclassify caffeine and herbal extract products as tobacco products requiring pre-market authorization. Manufacturers currently marketing these as dietary supplements face dossier preparation costs exceeding $500,000 per SKU. Small European white-label suppliers are responding by withdrawing from US distribution rather than absorbing compliance overhead.
Subscription-based employer procurement is displacing pharmacy reimbursement as the dominant channel for smoking cessation aids. Benefits administrators at US Fortune 500 companies now contract directly with manufacturers for 12-month employee enrollment programs. This bypasses pharmacist consultation attachment but requires manufacturers to maintain HIPAA-compliant adherence tracking infrastructure.
Tobacco Alternative Gum Market Segmentation
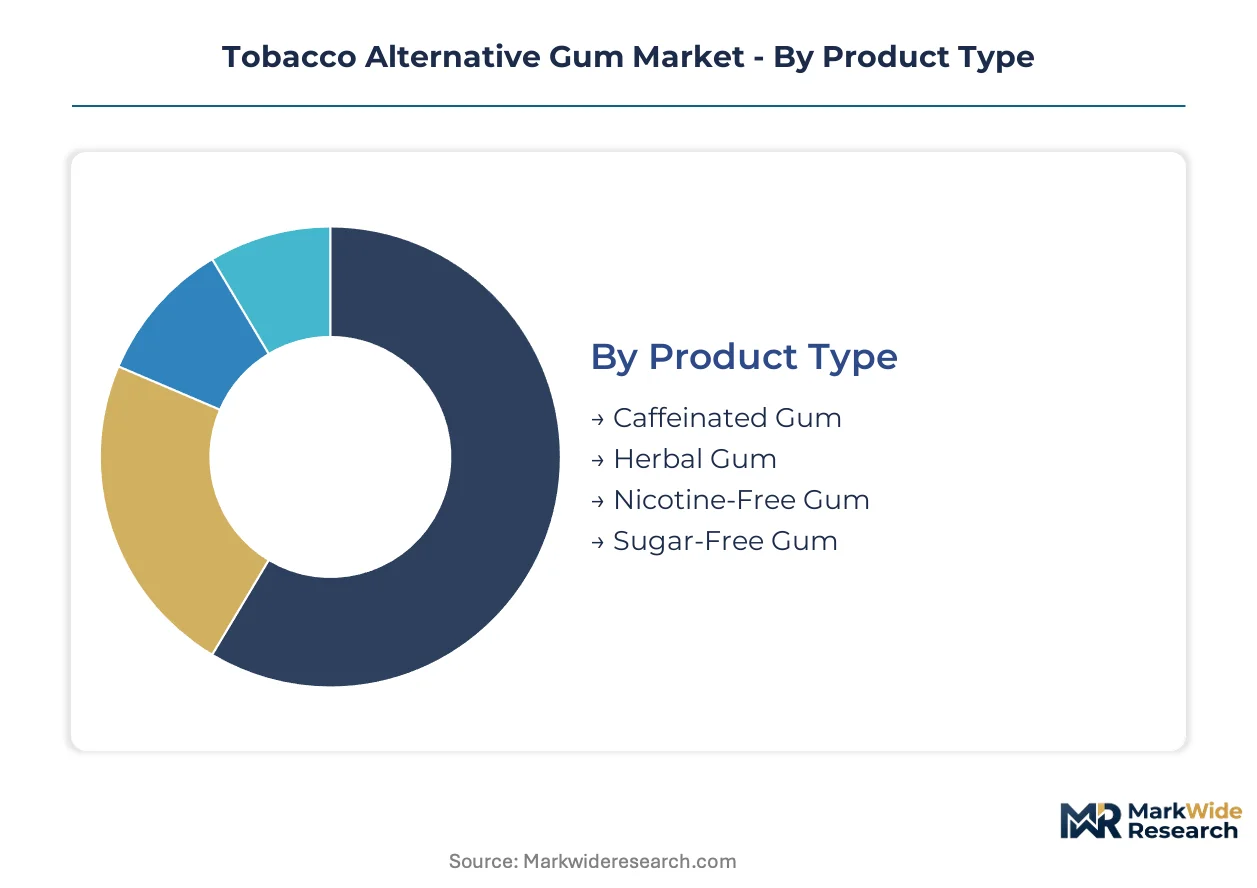
Segmentation in tobacco alternative gum reveals how formulation chemistry, channel economics, and consumer psychographics fragment addressable demand. Manufacturers must align polymer science capabilities with regulatory classification boundaries that differ sharply across nicotine and non-nicotine payloads.
Product Type:
Mature nicotine replacement formats coexist with emerging functional wellness variants, creating divergent margin profiles and clinical substantiation requirements.
- Nicotine-Free Gum:Polymer bases deliver caffeine, L-theanine, or adaptogen payloads without drug classification burdens. German and UK employers now subsidize these through wellness budgets as cessation adjacencies.
- Sugar-Free Gum:Sorbitol-xylitol plasticizer blends extend chew duration while supporting dental health claims that broaden addressable demand beyond smokers into general wellness consumers.
- Caffeinated Gum:Rapid buccal absorption targets productivity-focused professionals in financial and consulting sectors where pouch bans restrict alternatives.
- Herbal Gum:Botanical extracts from ginseng and valerian root appeal to consumers avoiding synthetic actives, though ECHA REACH compliance constrains terpene sourcing.
Nicotine-Free Gum retains volume leadership; Caffeinated Gum holds the steepest expansion curve.
Distribution Channel:
Channel selection determines margin capture and regulatory exposure, with pharmacy reimbursement eligibility creating stark price tiering against direct procurement models.
- Pharmacies:Pharmacist consultation attachment supports premium pricing and reimbursement eligibility for nicotine polacrilex formats in Germany, the United Kingdom, and the United States.
- Online Retail:Subscription mechanics and HIPAA-compliant adherence tracking enable direct-to-employor contracts that bypass pharmacy markup and capture recurring revenue.
- Convenience Stores:Impulse placement captures casual users seeking immediate gratification, though limited SKU depth restricts functional gum penetration.
- Supermarkets:Mass merchandising drives volume for sugar-free wellness variants with broad demographic appeal and lower per-unit margins.
Pharmacies dominate value capture; Online Retail is climbing the fastest.
Target Customer:
Customer archetypes map directly to payload chemistry and chew duration specifications, with occupational health budgets creating institutional demand distinct from individual purchase patterns.
- Smokers Looking to Quit:Clinical-channel relationships and cessation program enrollment drive adherence-focused formulations with bioavailability curves mimicking cigarette nicotine spikes.
- Health-Conscious Consumers:Sugar-free and herbal variants attract wellness-oriented buyers prioritizing clean-label ingredients over functional efficacy claims.
- Athletes:Caffeine polacrilex formats with rapid absorption target pre-workout and endurance segments where mastication fatigue is acceptable trade-off.
- Casual Users:Flavor-forward mint and fruit profiles support social and stress-relief use cases with lower repeat purchase frequency.
Smokers Looking to Quit anchor revenue concentration; Athletes are gaining share fastest.
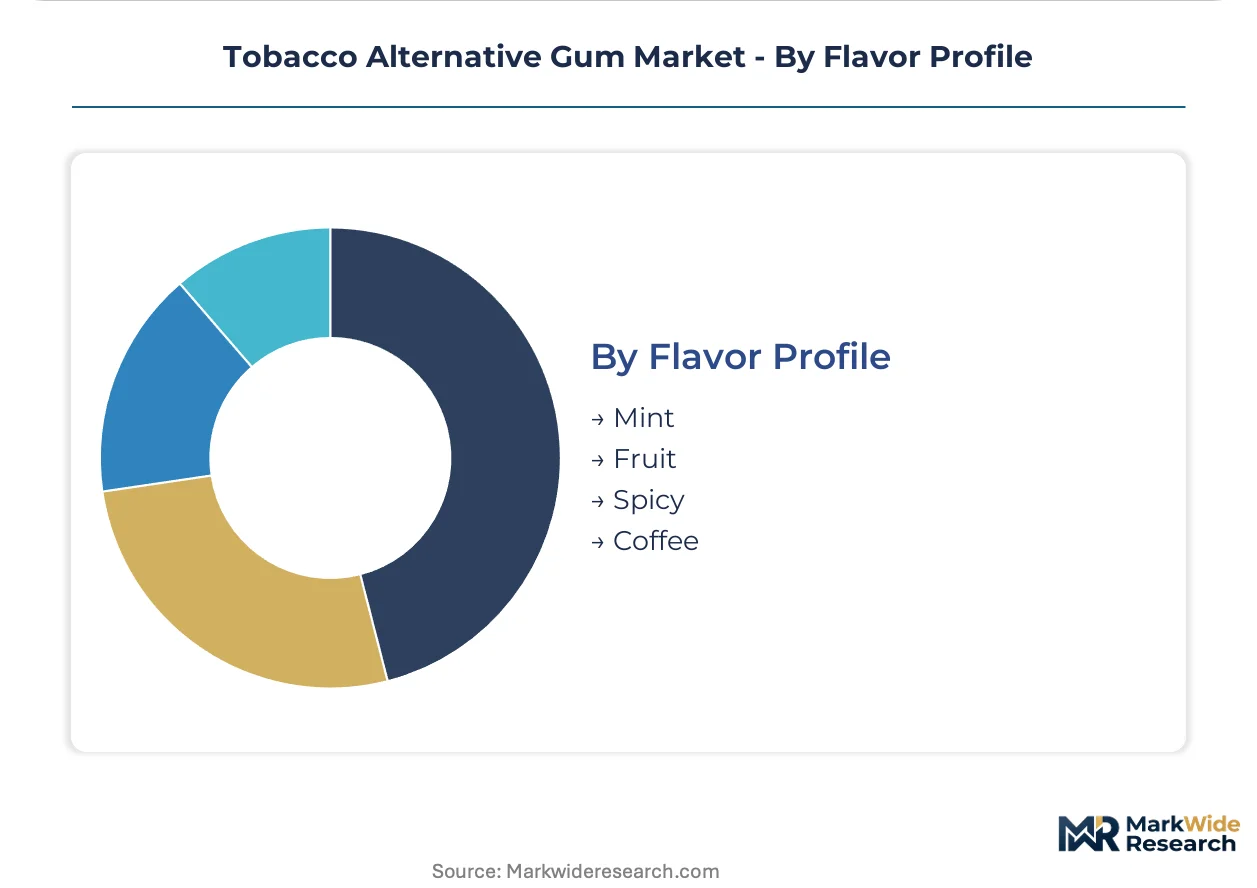
Flavor Profile:
Flavor chemistry determines regulatory compliance burden and sensory fatigue thresholds, with natural extract sourcing becoming critical under EU Green Deal packaging and REACH reformulation mandates.
- Mint:Menthol and synthetic cooling agent bases face ECHA restriction deadlines, accelerating botanical terpene extraction investments by European flavor houses.
- Fruit:Citrus and berry profiles dominate youth-appeal segments and sugar-free formulations, though stability challenges in polymer matrices limit shelf life.
- Coffee:Caffeine synergy and adult palate positioning support workplace consumption contexts, particularly in United States corporate wellness programs.
- Spicy:Cinnamon and ginger extracts target niche Ayurvedic crossover demand in India, where paan-masala flavor equity transfers to gum formats.
Mint maintains volume leadership; Coffee shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored cessation coverage concentrates procurement power among Fortune 500 benefits administrators in the United States, German statutory health insurers, and UK National Health Service trusts. These institutional buyers drive volume commitments that reshape manufacturing location decisions and regulatory filing priorities.
United States
Corporate wellness platforms at major employers now contract directly with manufacturers for 12-month smoking cessation programs. The FDA regulates nicotine gum as an over-the-counter drug under monograph standards, while pending Deeming Rule proposals threaten to reclassify non-nicotine functional formats. New Jersey and North Carolina host contract manufacturing clusters serving pharmacy and direct-to-employer channels.
Germany
Statutory health insurance funds reimburse nicotine polacrilex formats prescribed through smoking cessation clinics. The EMA enforces Tobacco Products Directive classification for higher-dose formats alongside MDR compliance requirements. Cologne and Hamburg anchor distribution networks supplying pharmacy chains across the federal states.
United Kingdom
NHS trusts procure gum-based cessation aids through centralized frameworks that favor clinical-channel suppliers with regulatory dossier depth. National smoking ban enforcement and employer wellness mandates compress demand toward non-nicotine alternatives. London and Manchester concentrate white-label manufacturing serving both domestic and export markets.
India
CDSCO's streamlined OTC notification pathway allows foreign manufacturers to bypass clinical trial requirements for sub-4mg nicotine polacrilex formats. Paan-masala flavor equity transfers to gum formats through ITC Limited's pan-India retail coverage. Mumbai and Delhi-NCR serve as import gateways for pharmaceutical-grade gum acacia formulations.
Denmark
Fertin Pharma leverages its Danish manufacturing base to supply private-label brands across European pharmacies. REACH compliance deadlines for synthetic cooling agents accelerate reformulation toward botanical extract bases. Copenhagen anchors Nordic distribution while serving as a regulatory filing hub for EMA centralized procedures.
Tobacco Alternative Gum Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin pools. Pharmacy reimbursement eligibility favors incumbents with clinical-channel relationships and regulatory dossier depth, while contract manufacturers capture volume through white-label agreements with thin pass-through economics. Three archetypes dominate: vertically integrated pharma conglomerates with cessation therapy franchises, asset-light contract manufacturers serving private-label demand, and regional specialists leveraging flavor equity from adjacent oral care traditions. Competitive moves concentrate on M&A to secure polymer science capabilities and strategic partnerships to bypass pharmacy markup through direct-to-employer distribution.
Among vertically integrated pharma conglomerates, Johnson & Johnson and GlaxoSmithKline occupy positions anchored by clinical-channel relationships and OTC drug monograph expertise. Novartis AG and Pfizer exemplify the regulatory-heavy archetype with dossier depth across multiple nicotine replacement formats. Fertin Pharma represents the contract manufacturing tier, leveraging Danish production capacity to supply private-label demand across European pharmacy networks. ITC Limited anchors South Asian positioning through paan-masala flavor equity and pan-India retail coverage that transfers to gum formats.
| Leading Market Players |
|---|
| British American Tobacco |
| Johnson & Johnson |
| Novartis AG |
| Perrigo Company |
| Philip Morris International |
| GlaxoSmithKline |
| Pfizer |
| Fertin Pharma |
| ITC Limited |
| Others |
Value Network & Pricing Analysis
Gum acacia supply volatility from Sudan and Chad determines both margin compression in white-label contract tiers and the geographic clustering of polymer manufacturing capacity around European and North American formulators with inventory hedging programs.
Pricing Analysis
Cost-plus contracts with gum acacia indexation dominate white-label manufacturing agreements between Danish and German contract manufacturers and European pharmacy chains. Three-tier pricing structure across premium, standard, and economy levels separates clinical-channel nicotine polacrilex from direct-to-employer subscription formats and private-label pharmacy generics. Price differentiation hinges on pharmacist consultation attachment and reimbursement eligibility versus volume scale in corporate wellness procurement. Pricing pressure stems from oral nicotine pouch substitution eroding gum adherence rates among dual-use smokers.
Supply Chain Analysis
Extended payment terms from European pharmacy chains to contract manufacturers strain working capital and favor larger formulators with supply-chain finance facilities. Pharmaceutical-grade gum acacia draws from Sudan, Chad, and limited Indian cultivation; polyol plasticizers rest on Chinese and Thai sorbitol-xylitol production. Single-source vulnerability concentrates in Sudanese gum acacia exports where political instability disrupts raw material flows without short-term substitution. Distribution runs through pharmacy wholesale networks in Germany and the United Kingdom, with direct-to-employer platforms capturing subscription volume in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's pending Deeming Rule extension to non-nicotine functional gums constitutes a regulatory inflection that will bifurcate winners with pre-market authorization dossiers from losers forced into channel withdrawal.
For Market Incumbents: Harden clinical-channel relationships through smoking cessation clinic partnerships in Germany and the United Kingdom before nicotine pouch substitution erodes pharmacist consultation attachment. Deepen polymer science capabilities via acquisition of microencapsulation specialists to secure burst-lag-burst release patent estates against generic erosion. For New Entrants and Emerging Players: Build out direct-to-employer distribution platforms targeting United States Fortune 500 benefits administrators with HIPAA-compliant adherence tracking infrastructure. Capture share in Indian pharmacy modernization via CDSCO streamlined OTC notification for sub-4mg nicotine polacrilex formats before incumbent dossier depth solidifies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors contract manufacturers with REACH-compliant botanical extraction capabilities and white-label pharmacy relationships. Long-term viability centers on polymer science IP and regulatory dossier depth rather than brand equity. Watch FDA Deeming Rule finalization as the signal distinguishing investable drug-classification assets from stranded dietary supplement inventory.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | ECHA synthetic cooling agent restrictions force botanical terpene extraction investments by European flavor houses. |
| Direct-to-Employer Platform Launch | Corporate wellness procurement bypasses pharmacy markup and captures recurring subscription revenue with lower acquisition cost. |
| Microencapsulation Patent Acquisition | Burst-lag-burst release profiles mimic cigarette nicotine spikes and secure clinical-channel prescribing preference. |
| Indian OTC Notification Filing | CDSCO streamlined pathway allows foreign manufacturers to bypass clinical trial requirements for sub-4mg formats. |
| Blister-to-Sachet Line Conversion | EU Green Deal packaging mandates force retooling investment that strands non-compliant thermoforming capacity. |
Research Methodology
A standing panel of regulatory affairs directors, pharmacy procurement managers, contract manufacturing executives, and employer benefits administrators provided ongoing calibration across primary interview cycles and secondary validation. FDA filings, EMA centralized procedure databases, CDSCO OTC notifications, and REACH registration dossiers anchored source triangulation. Bottom-up volume builds from polymer base consumption and top-down expenditure flows from statutory health insurance reimbursement data were cross-referenced for convergence.
Scenario-bracketing around FDA Deeming Rule timing and gum acacia supply disruption severity framed the analytical envelope across the projection horizon. Segmentation dimensions modeled include product type chemistry, distribution channel economics, and target customer psychographics alongside regional regulatory classification clusters. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs incorporated employer-sponsored cessation coverage enrollment rates and ECHA enforcement intensity for synthetic cooling agents.
Stress conditions across Sudanese gum acacia export volumes, FDA classification timing, and oral nicotine pouch substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding statutory health insurance reimbursement continuity and REACH compliance deadline adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Global CBD Beverages Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Low Fat Protein Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Health and Wellness Foods Market