
 Mediterranean Lentil Crisps and Inclusion Bases Market | 2026-2036
Mediterranean Lentil Crisps and Inclusion Bases Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Lentil Crisps and Inclusion Bases Market Insights
Subscription-based replenishment models for snack boxes is broadening recurring revenue streams beyond one-off retail purchases. Saffron Road leverages direct-to-consumer channels to sustain brand loyalty in ethnic and better-for-you segments. General Mills anchors mainstream shelf presence through established grocery networks. Biena Snacks specializes in pulse-forward formulations that differentiate on protein density and clean ingredient decks.
Mediterranean lentil crisps and inclusion bases comprise extruded or baked snack matrices formulated from dehulled lentil flour, typically containing 30-50% pulse content by weight, with inclusion bases serving as textured add-ins for bakery and confectionery applications. Lentil Crisps dominate current production volumes due to established extrusion infrastructure and consumer familiarity, while Inclusion Bases capture expanding margin pools as bakery manufacturers reformulate for protein fortification. The Flavor Profile dimension shows Herb Infused and Savory Sea Salt variants leading velocity in European retail, with Spicy Mediterranean gaining traction in North American specialty channels.
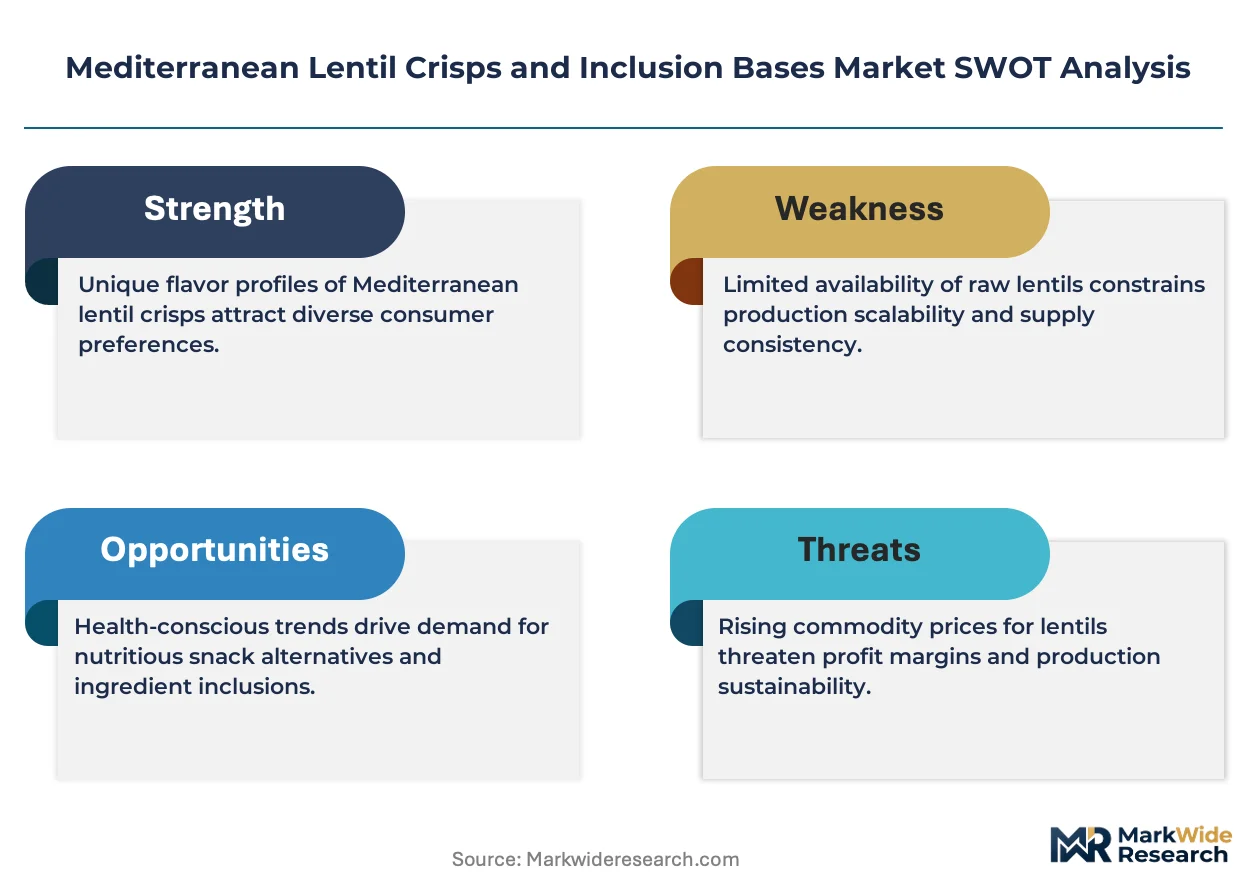
EFSA sets maximum contaminant thresholds for acrylamide in pulse-based extruded snacks, compelling manufacturers to validate low-temperature processing protocols. REACH compliance governs migration limits for packaging substrates used in Stand-up Pouch and Resealable Bag formats across EU member states. FDA GRAS self-determination pathways shape market entry timing for novel lentil protein isolates in the United States. Stakeholders must monitor evolving front-of-pack labeling mandates that could recalibrate formulation investments across regional portfolios.
Market Dynamics
EFSA's tightening acrylamide thresholds for pulse-based extruded snacks are forcing manufacturers to abandon high-temperature processing, triggering capital redeployment toward low-temperature extrusion and infrared drying systems across Mediterranean production facilities.
Growth Catalysts
- EU Novel Food Streamlining:EFSA's 2023 guidance on pulse protein safety data requirements is accelerating approval timelines for lentil inclusion bases in bakery applications. Spanish manufacturers report faster market entry for protein-fortified formulations.
- Clean-Label Bakery Reformulation:Artisan and industrial bakeries in Italy are substituting wheat flour with lentil inclusion bases to meet front-of-pack nutritional scoring mandates. This ingredient swap delivers protein density without synthetic additives.
- Extrusion Infrastructure Maturation:Twin-screw extrusion technology originally deployed for cereal processing is automating lentil crisp production with precise moisture control. Equipment suppliers in Germany and France report expanded order backlogs from Mediterranean snack converters.
Market Restraints
- Lentil Supply Concentration:Premium dehulled red lentil varieties concentrate in Canadian prairie growing regions and Turkish Aegean coastal zones. Climate volatility in these belts creates input cost instability for Mediterranean processors.
- Acrylamide Compliance Burden:EFSA's maximum contaminant thresholds for extruded pulse snacks mandate continuous inline monitoring systems. Smaller Italian and Spanish producers face disproportionate validation costs versus integrated multinationals.
- Packaging Migration Constraints:REACH compliance for flexible packaging substrates used in stand-up pouches limits supplier pools. Resealable bag converters report extended qualification timelines for bio-based film alternatives.
Strategic Opportunities
- Portuguese Market Underpenetration:Lentil crisp retail velocity in Portugal trails Spain and Italy by significant margins. Local distribution partnerships with Continente and Pingo Doce chains offer first-mover positioning.
- Confectionery Protein Fortification:Inclusion bases are penetrating chocolate and nougat segments as manufacturers respond to EU-wide sugar reduction targets. French confectioners lead formulation trials for lentil-derived texturants.
- Direct-to-Consumer Subscription Models:Specialty snack brands are bypassing traditional grocery slotting fees through curated delivery boxes. This channel captures recurring revenue with higher margin retention than mass retail.
Industry Challenges
- Low-Temperature Process Engineering Talent:Extrusion operators with expertise in infrared and microwave drying protocols remain scarce across Mediterranean production zones. Technical institutes in Bologna and Barcelona are expanding specialized training curricula.
- Legacy Equipment Retrofit Complexity:Conventional high-temperature extrusion lines require substantial modification to meet EFSA acrylamide thresholds. Capital allocation decisions are complicated by uncertain payback periods on hybrid thermal systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Lentil Crisps and Inclusion Bases Market |
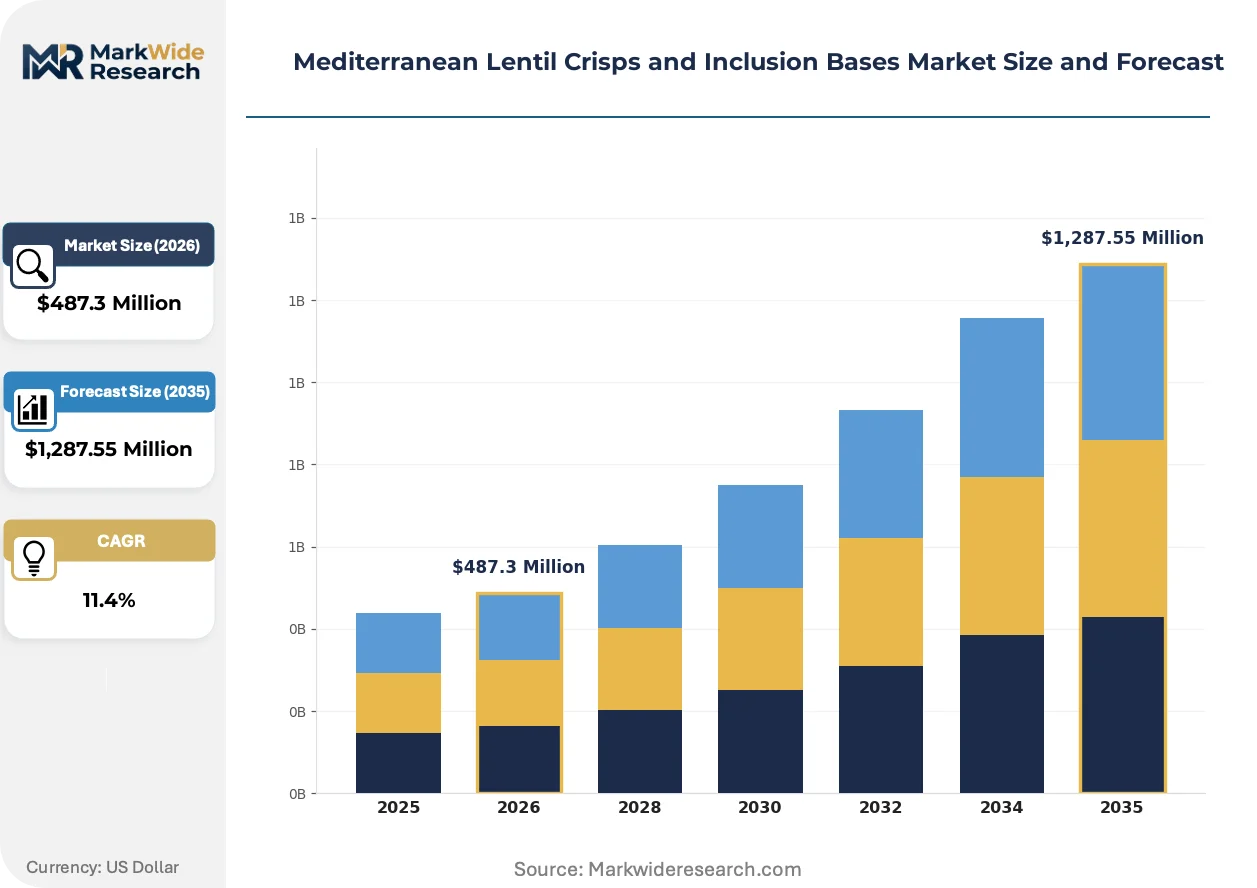
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,287.55 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lentil Crisps, Inclusion Bases, Vegetable Chips, Grain Snacks, Pulses Mix Flavor Profile: Spicy Mediterranean, Herb Infused, Tangy Citrus, Roasted Garlic, Savory Sea Salt Packaging Format: Stand-up Pouch, Resealable Bag, Bulk Pack, Single Serve, Multipack Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Convenience Stores, Foodservice Outlets |
| Companies Covered | Mediterranean Snack Foods, Saffron Road, Harvest Snaps, Biena Snacks, The Good Bean, Hippeas, Hain Celestial, General Mills, PepsiCo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Lentil Crisps and Inclusion Bases Market Trends and Innovations
Processing technology convergence with regulatory compliance mandates is compressing product development cycles while reshaping competitive differentiation around validated clean-label claims rather than flavor innovation alone.
Twin-screw extrusion with integrated infrared drying zones is automating moisture reduction in lentil crisp matrices without triggering Maillard reaction byproducts. Spanish equipment integrators are retrofitting existing cereal lines for pulse-specific thermal profiles. This automation is compressing the validation timeline for EFSA acrylamide compliance from eighteen months to under six months for reformulated products.
REACH amendments governing food-contact substances are restricting phthalate plasticizers in flexible packaging films used for Mediterranean snack distribution. German converters are accelerating migration to bio-based polyesters and coated paper laminates. Stand-up pouch formats for lentil crisps face the steepest reformulation burden given oxygen barrier requirements versus resealable bag alternatives.
Spanish and Italian retail buyers are consolidating supplier relationships around vertically integrated pulse processors with captive lentil milling and extrusion capabilities. This concentration is displacing fragmented toll-manufacturing arrangements that dominated early market development. Bakery manufacturers seeking inclusion bases now prioritize suppliers with validated low-temperature processing documentation over commodity ingredient traders.
Mediterranean Lentil Crisps and Inclusion Bases Market Segmentation
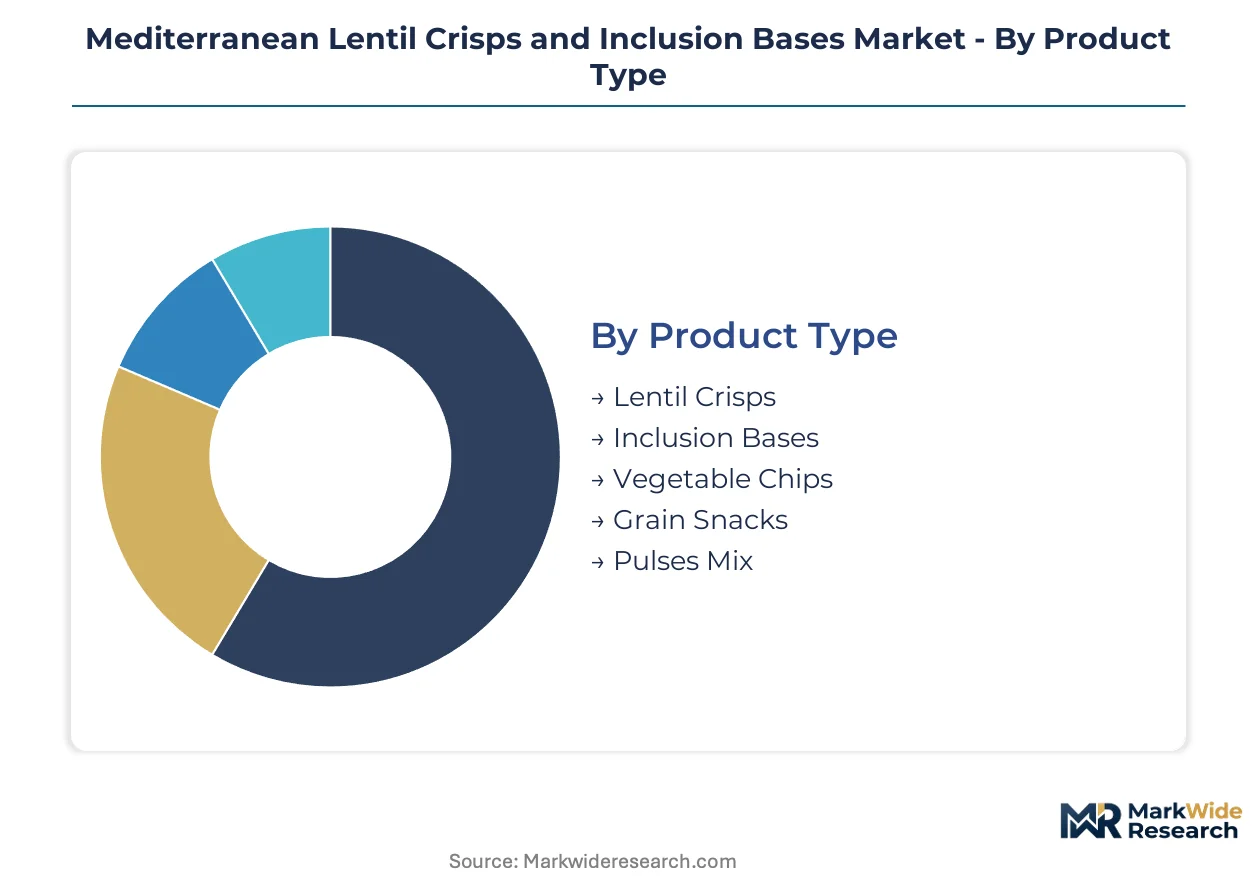
Product differentiation in Mediterranean lentil crisps hinges on validated processing claims and EFSA compliance documentation. Manufacturers compete on thermal profile verification rather than flavor novelty alone. Segment selection directly determines capital allocation for extrusion infrastructure and packaging migration costs.
Product Type:
EFSA acrylamide thresholds apply differentially across segments based on thermal processing intensity and moisture content specifications. Extruded matrices face stricter inline monitoring requirements than baked alternatives.
- Lentil Crisps:Extruded or baked matrices containing 30-50% dehulled lentil flour by weight, typically processed through twin-screw systems with infrared drying zones. Spanish and Italian retail buyers concentrate procurement here, driven by established consumer familiarity and shelf-stable logistics. EFSA validation timelines compress from eighteen to six months for reformulated low-temperature protocols.
- Inclusion Bases:Textured lentil-derived add-ins for bakery and confectionery protein fortification, requiring EU Novel Food approval pathways for novel protein isolate concentrations. Italian industrial bakeries substitute these for wheat flour to meet front-of-pack nutritional scoring mandates. Clean-label positioning captures expanding margin pools versus commodity pulse ingredients.
- Vegetable Chips:Composite formats blending lentil flour with root vegetable starches, processed at lower temperatures to mitigate acrylamide formation.
- Grain Snacks:Multigrain matrices incorporating lentil flour alongside cereal grains, common in Portuguese and Greek retail channels.
- Pulses Mix:Blended legume formats combining lentil with chickpea or fava bean flours, targeting protein density claims in French specialty stores.
Leading the category by volume: Lentil Crisps. Growing fastest: Inclusion Bases.
Flavor Profile:
Flavor selection determines thermal processing parameters, with herb-infused variants tolerating lower-temperature profiles than roasted formulations that risk Maillard reaction byproducts.
- Herb Infused:Mediterranean herb blends including rosemary, oregano, and thyme, compatible with infrared drying at sub-Maillard thresholds. Italian retail velocity leads here, supported by diet adherence patterns in Lombardy and Emilia-Romagna. Clean-label positioning aligns with EFSA-compliant processing documentation.
- Savory Sea Salt:Minimal ingredient decks featuring sea salt as primary flavorant, enabling straightforward acrylamide compliance validation. Spanish supermarkets in Madrid and Barcelona drive volume concentration. Simple formulations reduce regulatory documentation burden versus complex seasoning matrices.
- Spicy Mediterranean:Chili and paprika-forward profiles gaining traction in North American specialty channels through direct-to-consumer subscription models.
- Tangy Citrus:Lemon and orange peel formulations requiring acidulant stability testing under REACH packaging migration protocols.
- Roasted Garlic:High-temperature susceptible profile demanding modified thermal protocols to meet EFSA contaminant thresholds.
Highest margin capture: Herb Infused. Steepest expansion trajectory: Spicy Mediterranean.
Packaging Format:
REACH compliance for food-contact substances creates tiered qualification timelines, with flexible films facing stricter phthalate restrictions than rigid alternatives.
- Stand-up Pouch:Flexible laminate formats with oxygen barrier requirements, subject to steepest bio-based film reformulation burden under amended REACH guidelines. German converters report extended qualification timelines for polyester alternatives. Resealable zipper mechanisms add mechanical complexity to migration testing protocols.
- Resealable Bag:Lower barrier specifications than stand-up pouches, enabling faster adoption of coated paper laminates. French and Italian snack brands prioritize this format for premium positioning. Oxygen permeability trade-offs limit shelf-life claims versus pouch alternatives.
- Bulk Pack:Foodservice-oriented formats for bakery and confectionery manufacturers purchasing inclusion bases by weight.
- Single Serve:Portion-controlled units for convenience store distribution in Portuguese urban centers.
- Multipack:Aggregated single-serve units targeting family consumption in Spanish supermarket channels.
Dominant by production volume: Stand-up Pouch. Fastest regulatory clearance: Resealable Bag.
Distribution Channel:
Channel selection determines margin retention and EFSA documentation requirements, with foodservice outlets demanding bulk certificates versus retail's front-of-pack labeling compliance.
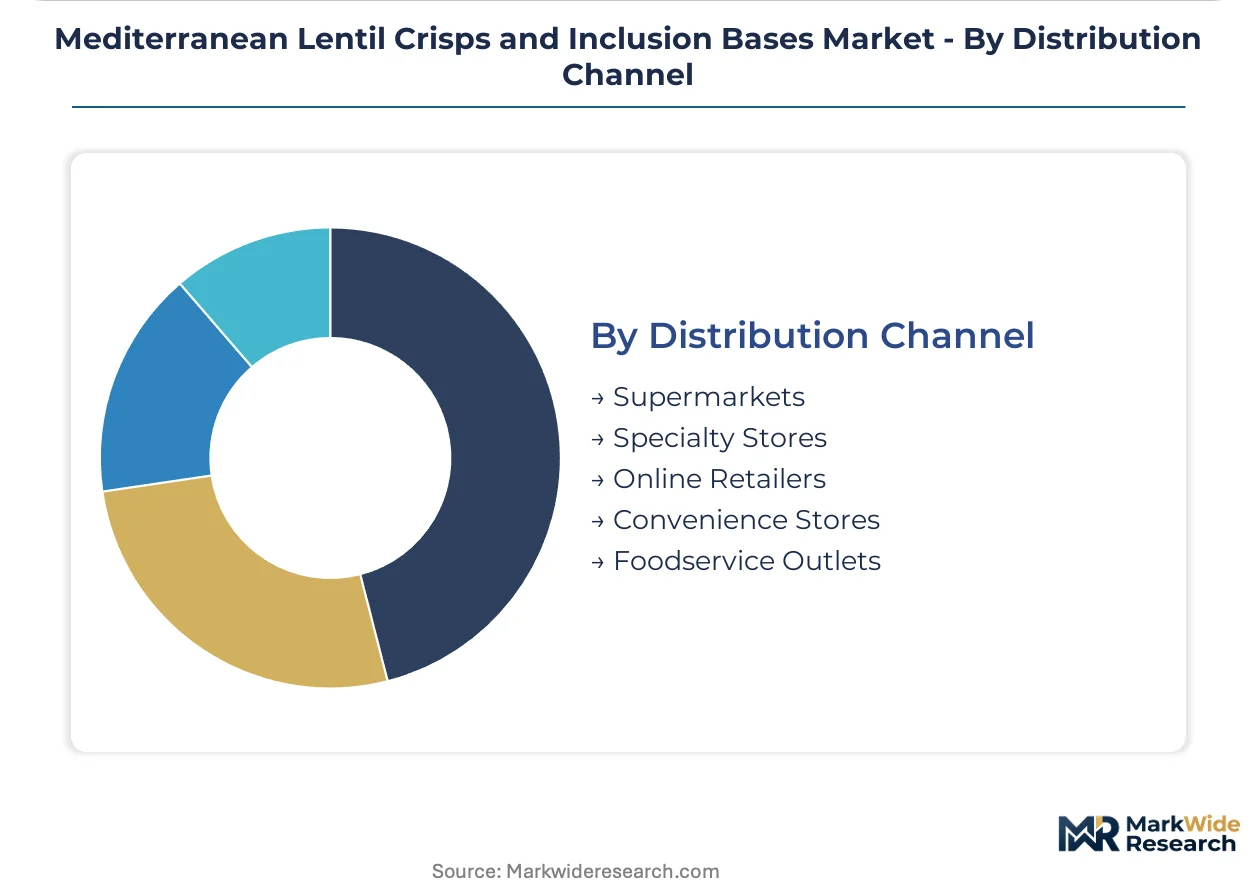
- Supermarkets:Consolidated buyer power in Spain and Italy driving supplier consolidation around vertically integrated pulse processors. Continente, Carrefour, and Coop Italia prioritize suppliers with captive lentil milling and validated low-temperature documentation. Slotting fees compress margins versus specialty channels.
- Online Retailers:Direct-to-consumer subscription models bypassing traditional grocery slotting structures. Saffron Road and comparable specialty brands capture recurring revenue with higher margin retention here. Curated delivery boxes enable protein density storytelling absent from mass retail shelf facings.
- Specialty Stores:Italian gastronomia and Spanish delicatessen channels emphasizing clean-label provenance claims.
- Convenience Stores:Single-serve format concentration in Portuguese and Greek urban locations.
- Foodservice Outlets:Bulk inclusion base procurement by artisan bakeries and industrial confectioners in France and Belgium.
Largest volume throughput: Supermarkets. Gaining share fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of lentil crisps concentrates in extrusion facilities across Spain and Italy, while consumption patterns extend into Portugal and France where Mediterranean diet adherence varies significantly. Turkish Aegean coastal zones supply premium dehulled red lentils, creating a north-south supply chain configuration.
Spain
Madrid and Barcelona supermarkets drive retail velocity for savory sea salt variants, with Continente and Carrefour consolidating procurement around vertically integrated pulse processors. EFSA acrylamide thresholds compel manufacturers in Catalonia to validate low-temperature extrusion protocols. Valencia hosts emerging equipment integrators retrofitting cereal lines for lentil-specific thermal profiles.
Italy
Lombardy and Emilia-Romagna consumers favor herb-infused formulations aligned with regional diet patterns, while industrial bakeries substitute lentil inclusion bases for wheat flour. Front-of-pack nutritional scoring mandates from Rome accelerate clean-label reformulation timelines. Bologna technical institutes are expanding specialized training curricula for infrared drying protocol expertise.
France
Parisian and Lyon-based confectioners lead formulation trials for lentil-derived texturants in chocolate and nougat segments responding to EU-wide sugar reduction targets. REACH compliance for flexible packaging substrates creates extended qualification timelines for resealable bag converters. French specialty stores emphasize clean-label provenance claims for premium positioning.
Portugal
Lisbon and Porto retail channels show underpenetration in lentil crisp velocity versus Spanish benchmarks, creating first-mover opportunities with Continente and Pingo Doce distribution partnerships. Single-serve formats dominate convenience store distribution in urban centers. Local bakery manufacturers remain untapped prospects for inclusion base procurement.
Turkey
Aegean coastal growing regions concentrate premium dehulled red lentil supply for Mediterranean processors, though climate volatility creates input cost instability. Turkish exporters face EU Novel Food documentation requirements for protein isolate concentrations entering Italian and Spanish manufacturing channels. Izmir serves as the primary consolidation point for outbound pulse shipments.
Mediterranean Lentil Crisps and Inclusion Bases Market Competitive Landscape
Top-tier vendors anchor mass retail shelf presence through established grocery networks, while specialty players capture recurring revenue through direct-to-consumer channels. The competitive structure splits between integrated multinationals with captive milling capabilities and niche pulse-forward specialists. Three archetypes dominate: vertically integrated processors with extrusion infrastructure, ethnic-focused brands leveraging subscription models, and diversified food conglomerates extending snack portfolios. Competitive moves concentrate on supplier consolidation for EFSA compliance documentation and equipment retrofit partnerships for low-temperature processing validation.
Among specialty snack specialists, Saffron Road exemplifies the direct-to-consumer archetype through curated delivery boxes that bypass traditional grocery slotting structures. Biena Snacks occupies a position within the pulse-forward formulation tier, differentiating on protein density claims and clean ingredient decks. General Mills anchors the diversified conglomerate segment, leveraging established distribution networks for mainstream retail penetration. These three represent distinct strategic postures rather than direct substitutes, with each capturing margin through channel-specific positioning rather than commodity competition.
| Leading Market Players |
|---|
| Mediterranean Snack Foods |
| Saffron Road |
| Harvest Snaps |
| Biena Snacks |
| The Good Bean |
| Hippeas |
| Hain Celestial |
| General Mills |
| PepsiCo |
| Others |
Pricing and Supply Chain Analysis
Low-temperature extrusion retrofitting across Spanish and Italian production facilities simultaneously elevates capital recovery requirements and consolidates procurement leverage around vertically integrated pulse processors with captive milling infrastructure.
Pricing Analysis
Margin tightening in standard-grade lentil crisps reflects EFSA acrylamide compliance validation costs that smaller toll-manufacturers cannot absorb. Three-tier pricing structure across premium EFSA-validated, standard clean-label, and economy conventional tiers separates buyers by certification documentation burden. Price differentiation tracks thermal processing verification level and captive supply of dehulled red lentils. Foodservice buyers purchasing bulk inclusion bases exhibit lowest price sensitivity due to reformulation cost pass-through mechanisms.
Supply Chain Analysis
Dehulled red lentil supply rests on Canadian prairie growing regions and Turkish Aegean coastal zones, with Spanish and Italian extrusion facilities constituting the primary conversion cluster. Raw material dependencies concentrate on premium lentil varieties, food-grade packaging films, and specialized twin-screw extrusion components. Single-source vulnerability in Turkish Aegean supply creates input cost instability during climate volatility events. Distribution runs through vertically integrated pulse processors delivering validated documentation direct to consolidated supermarket buyers in Madrid, Barcelona, and Milan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around EFSA compliance capabilities that eliminate fragmented toll-manufacturers unable to fund low-temperature processing validation.
For Market Incumbents: Extend captive milling infrastructure into Portuguese and Greek markets before regional competitors establish EFSA-validated extrusion capacity. Acquire smaller Italian producers facing disproportionate acrylamide monitoring costs to consolidate procurement relationships with Continente and Carrefour buyers. Prioritize backward integration into Turkish Aegean lentil sourcing to mitigate climate-driven input volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models in underpenetrated Portuguese retail channels, bypassing supermarket slotting fee structures that favor established multinationals. Target French confectionery manufacturers seeking lentil-derived texturants for sugar-reduced formulations, where EU Novel Food approval timelines create incumbent vulnerability. Emphasize protein density storytelling absent from mass retail shelf facings. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified food conglomerates seeking clean-label snack portfolio extension. Long-term viability hinges on EFSA documentation asset durability rather than flavor innovation pipelines. Acquisition target archetype: vertically integrated Spanish or Italian processors with validated low-temperature protocols and captive Aegean sourcing relationships. Watch EFSA front-of-pack labeling mandate evolution as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Extrusion Retrofit | EFSA acrylamide compliance validation compresses from eighteen to six months for reformulated Spanish and Italian product lines. |
| Captive Lentil Milling Integration | Backward control over dehulled red lentil supply secures margin retention against Turkish Aegean climate volatility. |
| Direct-to-Consumer Channel Launch | Subscription models bypass Carrefour and Coop Italia slotting fees while capturing recurring revenue with higher margin retention. |
| Portuguese Distribution Partnership | First-mover positioning with Continente and Pingo Doce addresses significant retail velocity underpenetration versus Spanish benchmarks. |
| Confectionery Texturant Development | French chocolate and nougat manufacturers prioritize lentil inclusion bases responding to EU-wide sugar reduction targets. |
Research Methodology
EFSA guidance documents, EU Novel Food approval records, and REACH packaging migration protocols formed the secondary backbone. Primary interviews with extrusion equipment integrators in Valencia, category buyers at Continente and Carrefour, regulatory affairs leads at pulse processors, and technical training directors at Bologna institutes combined with secondary validation. Customs records for Turkish-Italian lentil trade flows and Nielsen retail audit data for Spanish and Italian snack velocity completed source triangulation. Bottom-up production capacity modeling and top-down consumption pattern analysis were cross-referenced.
Historical trendline analysis of extrusion equipment deployment and EFSA validation timeline compression informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel, with thermal processing compliance tier as an industry-specific overlay. CAGRs were derived from equipment order backlog trajectories and retail buyer consolidation patterns. Forecast inputs incorporated climate volatility indices for Aegean growing regions and REACH amendment implementation schedules.
Climate shocks in Turkish Aegean supply zones, EFSA front-of-pack labeling mandate acceleration, and REACH bio-based film qualification delays are the dominant revision risks. Forecasts reflect documented assumptions regarding EFSA validation timeline continuity and supermarket buyer consolidation stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Global Snack Food Market
Snacks
Energy Bar Market
Snacks
Veggie Chips Market
Snacks
Low Fat Crackers Market
Snacks
United States Energy Bar Market
Snacks
Fruit Jerky Market
Snacks
Savoury Biscuits Market
Snacks
Seafood Snacks Market
Snacks
Asia-Pacific Popcorn Market
Snacks
Allergy-Free Snacks Market
Snacks
Grass-Fed Jerkies Market
Snacks
Spain Snack Bar Market
Snacks
Global Rice Snacks Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Protein Crisps Market
Snacks
Global Vegetable Chips Market