
 Tunnel Bakery Oven Market | 2026-2036
Tunnel Bakery Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnel Bakery Oven Market Insights
Stainless steel interior cladding is shifting toward advanced aluminized steel and ceramic-coated composites in tunnel bakery oven fabrication, cutting thermal mass and shortening heat-up cycles by meaningful margins. AMF Den Boer leverages its Dutch engineering heritage to dominate European conveyor oven installations for high-volume bread lines. Middleby Corporation sustains North American market presence through backward integration into combustion control systems and aftermarket parts networks. Sveba Dahlen specializes in compact hybrid tunnel configurations that serve artisan bakeries scaling from batch to continuous production.
A tunnel bakery oven is a continuous-process thermal processing unit employing a motorized conveyor belt to transport dough products through sequentially zoned heating chambers, typically achieving temperatures between 200°C and 300°C with precise humidity control for crust formation and crumb structure development. Conveyor ovens occupy the largest installed base across industrial bread production lines due to throughput reliability and line integration flexibility. Electric and hybrid technology segments are gaining share as food processing plants face Scope 1 emission reduction targets and volatile natural gas pricing. Infrared technology leads in pastry manufacturing applications where rapid surface browning preserves moisture content in laminated doughs.
The US Department of Energy appliance standards and EPA emissions guidelines for commercial ovens shape product development roadmaps for gas-fired tunnel systems sold into American food processing plants. EU Ecodesign requirements and F-Gas Regulation compliance for refrigerants used in proofing-integrated lines constrain market access for non-certified equipment imports. China's GB standards for commercial catering equipment and energy labeling rules under SAMR oversight create parallel certification demands for manufacturers targeting Asian bakery chains. Stakeholders must monitor how carbon border adjustment mechanisms and evolving efficiency benchmarks reshape total cost of ownership calculations across major procurement markets.
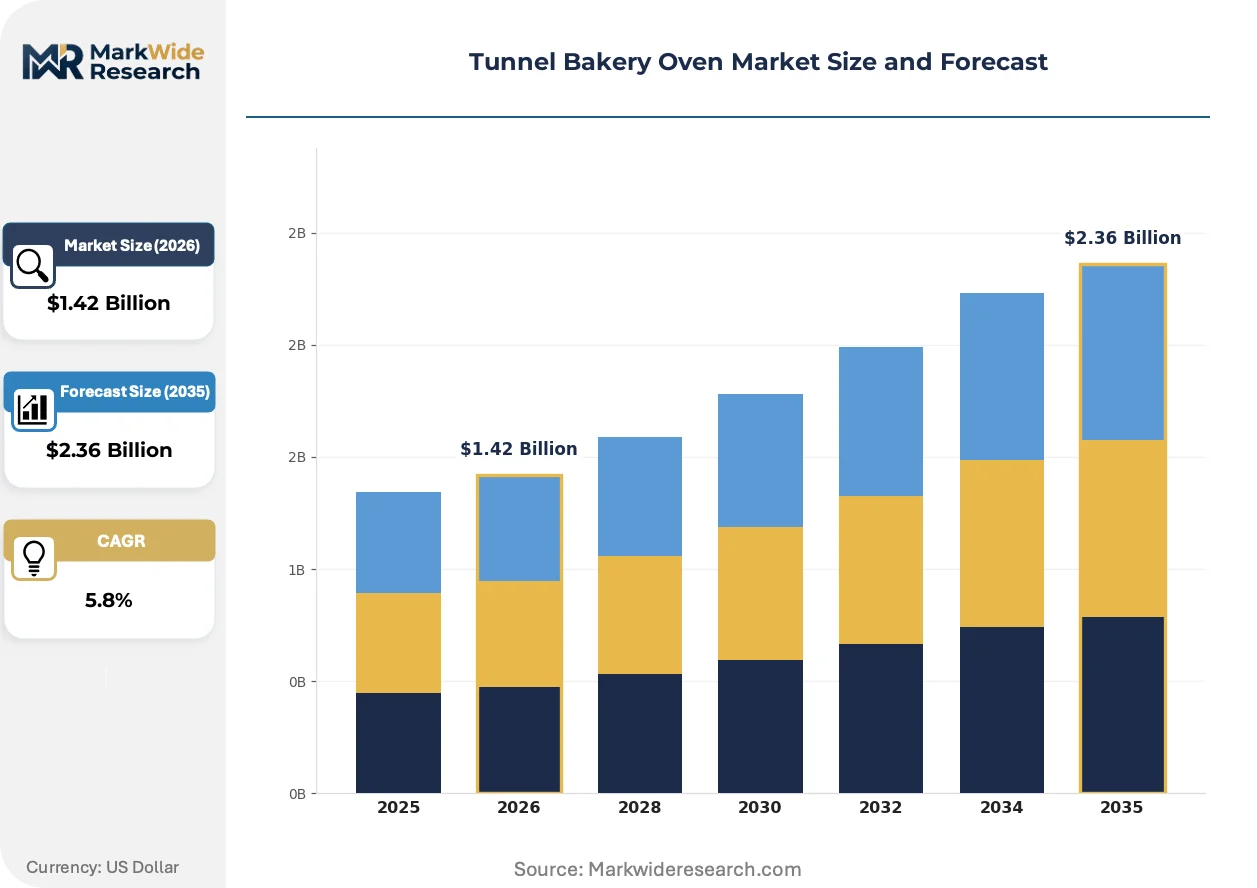
Market Dynamics
Gas-to-electric technology conversions are restructuring capital allocation across tunnel bakery oven procurement, as energy-efficiency mandates and volatile natural gas pricing compress payback periods for electric and hybrid systems in industrial bread production lines.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency benchmarks for commercial ovens are accelerating replacement cycles in European industrial baking facilities and tilting procurement toward certified electric tunnel systems.
- Clean-label bread demand:Artisan producers scaling to continuous output require automated tunnel ovens that replicate batch-oven crust characteristics at industrial throughput levels.
- Aluminized steel adoption:Advanced interior cladding materials cut thermal mass and shorten heat-up cycles, reducing energy consumption in high-volume bread lines.
Market Restraints
- Copper and nickel price volatility:Electric heating element fabrication depends on these commodity inputs, creating margin pressure for oven manufacturers during supply squeezes.
- Refrigerant compliance costs:EU F-Gas Regulation constraints on proofing-integrated tunnel lines raise certification barriers for non-European equipment imports.
- Gas infrastructure lock-in:Existing bakery plants with depreciated gas-fired tunnel ovens face stranded asset risk that slows technology transition despite operating cost advantages of electric alternatives.
Strategic Opportunities
- India bakery chain expansion:Organized retail growth and FSSAI-standardized food processing create demand for compact hybrid tunnel configurations in cities like Mumbai and Bangalore.
- Carbon border adjustment mechanisms:Emerging trade policies will penalize carbon-intensive oven imports, advantaging European and East Asian manufacturers with lower-emission product lines.
- Infrared-browning integration:Convection-infrared hybrid tunnel systems open pastry manufacturing applications where rapid surface treatment preserves laminated dough moisture content.
Industry Challenges
- Combustion control engineering scarcity:Gas-to-electric retrofits require technicians skilled in both legacy burner systems and modern induction heating, a dual competency rarely found in single candidates.
- Proofing-tunnel integration complexity:Continuous lines combining fermentation and baking stages demand precise humidity handoff engineering that extends commissioning timelines and strains project management capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnel Bakery Oven Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Ovens, Deck Ovens, Rack Ovens, Rotary Ovens Application: Bread Production, Pastry Manufacturing, Pizza Baking, Cookie Baking End User: Bakeries, Food Processing Plants, Restaurants, Supermarkets Technology: Electric, Gas, Hybrid, Infrared |
| Companies Covered | Sveba Dahlen, BABBCO, AMF Den Boer, Middleby Corporation, Rational, Blodgett, Baker's Pride, Unox, Hobart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnel Bakery Oven Market Trends and Innovations
Automation, regulatory stringency, and buyer consolidation are compressing equipment replacement cycles and reshaping how tunnel oven vendors structure service relationships with industrial bakeries.
Smart conveyor control systems using real-time thermal imaging and adaptive zone temperature modulation are automating crust consistency management across variable dough batches. Mid-sized artisan bakeries scaling to 24-hour operations adopt these systems fastest, seeking labor substitution without quality variance. The technology is automating what previously required experienced oven operators, reducing headcount dependencies in tight labor markets.
EPA emissions guidelines for commercial ovens are tightening allowable NOx and particulate outputs from gas-fired tunnel systems in American food processing plants. Manufacturers now engineer low-NOx burner architectures and pre-mix combustion chambers as standard rather than premium configurations. Gas-dependent industrial bakeries in the Midwest and Southeast face the steepest compliance retrofit obligations.
Equipment-as-a-service contracting is displacing traditional capital purchase models among North American bakery chains seeking to offload obsolescence risk. Vendors bundle maintenance, efficiency guarantees, and technology refresh rights into per-unit-baked pricing structures. This shift concentrates most rapidly among multi-site operators with standardized product portfolios and centralized procurement functions.
Tunnel Bakery Oven Market Segmentation
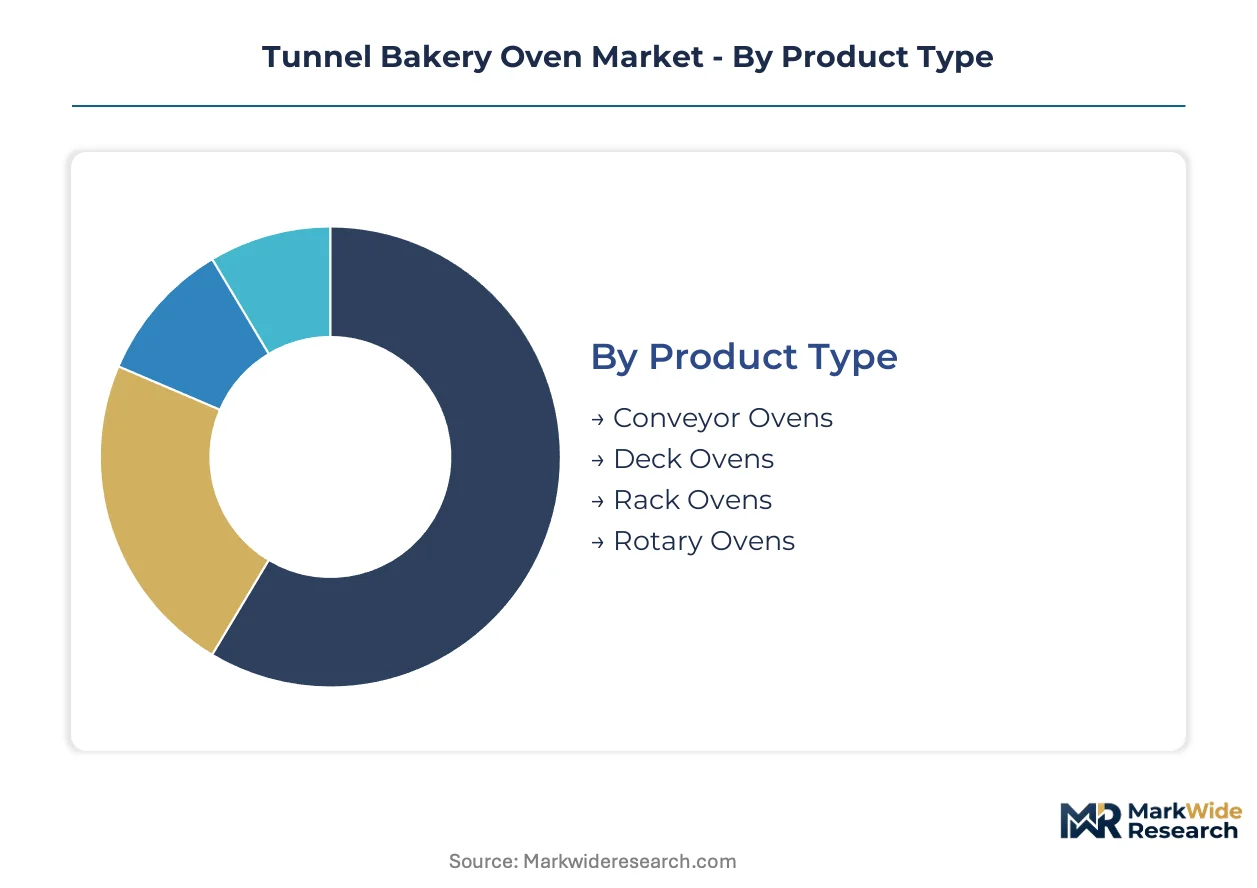
Tunnel bakery oven procurement patterns diverge sharply across production scale, thermal technology, and end-use application. Equipment specification choices cascade into energy consumption profiles, regulatory compliance obligations, and total cost of ownership calculations.
Product Type:
Volume throughput and line integration flexibility separate buyers in this category, with industrial bread producers prioritizing continuous-process reliability over batch flexibility.
- Conveyor Ovens:Motorized belt systems transport dough through sequentially zoned heating chambers at temperatures between 200°C and 300°C. German industrial baking clusters around Munich and Hamburg drive premium conveyor installations as artisan producers scale to continuous output.
- Deck Ovens:Static hearth configurations with direct thermal contact between dough and heated stone or steel surfaces. Italian and French craft bakeries favor these for sourdough production where crust development demands precise bottom-heat control.
- Rack Ovens:Rotating tray systems accommodating multiple product SKUs in single-batch cycles. Compact footprint suits North American supermarket in-store bakeries with space-constrained production environments.
- Rotary Ovens:Circular hearth designs with radial heat distribution for uniform baking of rounded loaves. Turkish and Middle Eastern flatbread producers deploy these for high-volume pita and lavash output.
Conveyor ovens lead volumes today; hybrid configurations combining conveyor mechanics with zone-specific thermal technologies are gaining share fastest.
Application:
Moisture retention requirements and surface browning kinetics dictate equipment selection, with laminated dough applications demanding fundamentally different heat transfer physics than lean bread formulations.
- Bread Production:Lean dough systems requiring precise humidity control for crust formation and crumb structure development. Clean-label demand from German and US consumers drives automated tunnel capacity expansion.
- Pastry Manufacturing:Laminated dough applications where rapid surface browning must preserve butter layer integrity. Infrared technology integration accelerates in French and Austrian croissant production lines.
- Pizza Baking:High-temperature, short-duration thermal processing for thin-crust products. Italian equipment manufacturers dominate this segment with stone-hearth conveyor hybrids.
- Cookie Baking:Controlled spread and snap development through precise temperature ramping. US commercial bakeries standardize on gas-fired tunnel systems for oatmeal and chocolate chip varieties.
Bread production commands the largest installed base; pastry manufacturing applications are expanding most quickly as European laminated dough exports climb.
End User:
Capital intensity and technical staffing capabilities create distinct procurement tiers, from multinational food processors to independent artisan operations.
- Bakeries:Independent and chain operations spanning craft to industrial scale. EU Ecodesign Directive compliance costs accelerate replacement cycles in French and Polish baking cooperatives.
- Food Processing Plants:High-volume, SKU-diverse manufacturing with 24-hour operational requirements. US Midwest and Southeast facilities face EPA emissions retrofit obligations for gas-fired tunnel lines.
- Restaurants:Front-of-house or back-of-house production with space and ventilation constraints. Compact hybrid tunnel configurations from Sveba Dahlen penetrate this tier.
- Supermarkets:In-store production with labor substitution priorities and brand differentiation through freshness claims. North American chains adopt equipment-as-a-service contracting fastest.
Food processing plants anchor equipment volumes; supermarkets are climbing fastest as fresh bakery competition intensifies in organized retail.
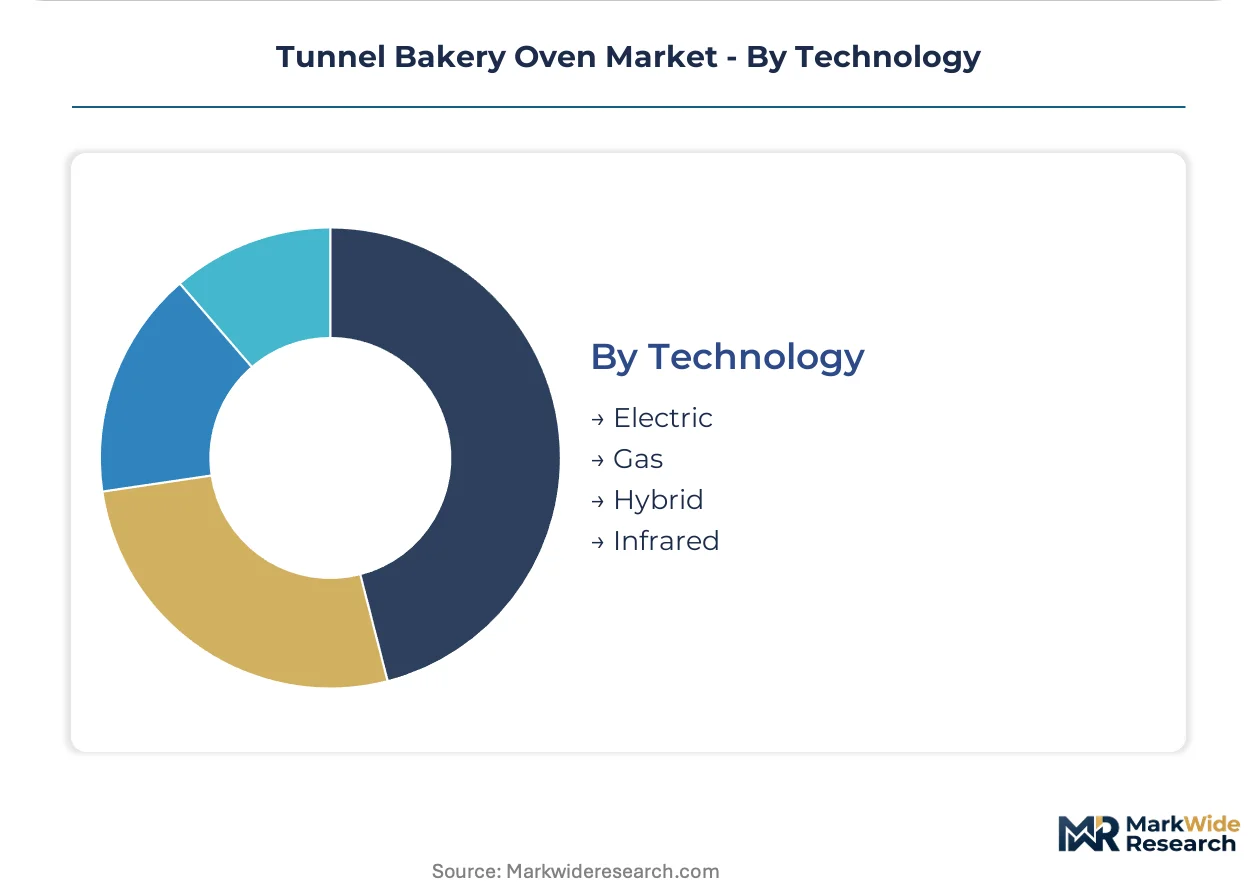
Technology:
Energy source selection now hinges on regulatory trajectory and carbon accounting rather than fuel cost alone, reshaping technology mix across installation geographies.
- Electric:Resistance or induction heating elements with precise zone control and zero direct emissions. EU Ecodesign efficiency benchmarks and Scope 1 reduction targets accelerate adoption in Netherlands and Denmark.
- Gas:Natural gas or propane combustion systems with established infrastructure and lower capital cost. Stranded asset risk accumulates in existing US and UK bakery plants with depreciated gas-fired installations.
- Hybrid:Dual-fuel or dual-heat-source configurations optimizing energy cost and regulatory compliance. Sveba Dahlen specializes in compact hybrid tunnel systems for artisan scaling transitions.
- Infrared:Radiant heat transfer for rapid surface treatment without convective moisture loss. Pastry manufacturers in France and Japan integrate infrared browning modules into convection tunnel lines.
Gas technology retains the largest installed base; electric systems are expanding most quickly as carbon border adjustment mechanisms reshape import economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial baking clusters around Munich and Hamburg anchor premium tunnel oven procurement, with artisan producers scaling automated capacity to meet clean-label bread demand across Europe.
United States
Midwest and Southeast food processing plants drive gas-fired tunnel oven replacement cycles as EPA emissions guidelines tighten allowable NOx outputs. The Department of Energy appliance standards reshape product development roadmaps for commercial oven manufacturers. Chicago and Detroit industrial baking corridors concentrate retrofit demand among depreciated infrastructure operators.
Germany
EU Ecodesign Directive efficiency benchmarks accelerate certified electric tunnel system adoption among industrial baking cooperatives. The F-Gas Regulation constrains proofing-integrated line imports from non-European equipment manufacturers. Munich and Hamburg baking clusters command premium procurement for high-volume bread production lines.
France
Artisan croissant and laminated dough exports climb, driving infrared-browning module integration into convection tunnel lines. ANSM food processing equipment standards shape domestic certification requirements for oven fabricators. Paris and Lyon industrial zones concentrate pastry manufacturing capacity expansion.
India
FSSAI-standardized food processing creates demand for compact hybrid tunnel configurations as organized retail bakery chains expand. The PLI scheme for food processing machinery offers capital cost support for domestic manufacturing scale-up. Mumbai and Bangalore urban markets concentrate procurement from scaling artisan-to-industrial transitions.
Japan
METI energy efficiency standards and dual carbon goals accelerate electric heating element adoption in commercial baking equipment. JIS certification requirements create parallel compliance demands for European and Chinese oven imports. Osaka and Nagoya industrial corridors anchor high-volume bread and snack production line investment.
Tunnel Bakery Oven Market Competitive Landscape
Global majors compete with regional champions across thermal technology specialization, with market structure consolidating around three distinct capability tiers. European engineering heritage dominates premium conveyor installations, while North American players leverage backward integration into combustion control systems. Strategic archetypes separate into full-line system integrators, component specialists, and compact hybrid configurators. Competitive moves concentrate on geographic expansion through distribution partnerships and technology licensing for electric heating architectures.
Within the European engineering tier, AMF Den Boer and Sveba Dahlen occupy positions reflecting Dutch and Swedish fabrication heritage respectively. Middleby Corporation anchors North American presence through in-house production of control systems and aftermarket parts networks. These three exemplify how regional capability concentrations map to distinct procurement market access strategies across gas-to-electric transition cycles.
| Leading Market Players |
|---|
| Sveba Dahlen |
| BABBCO |
| AMF Den Boer |
| Middleby Corporation |
| Rational |
| Blodgett |
| Baker's Pride |
| Unox |
| Hobart |
| Others |
Pricing and Supply Chain Analysis
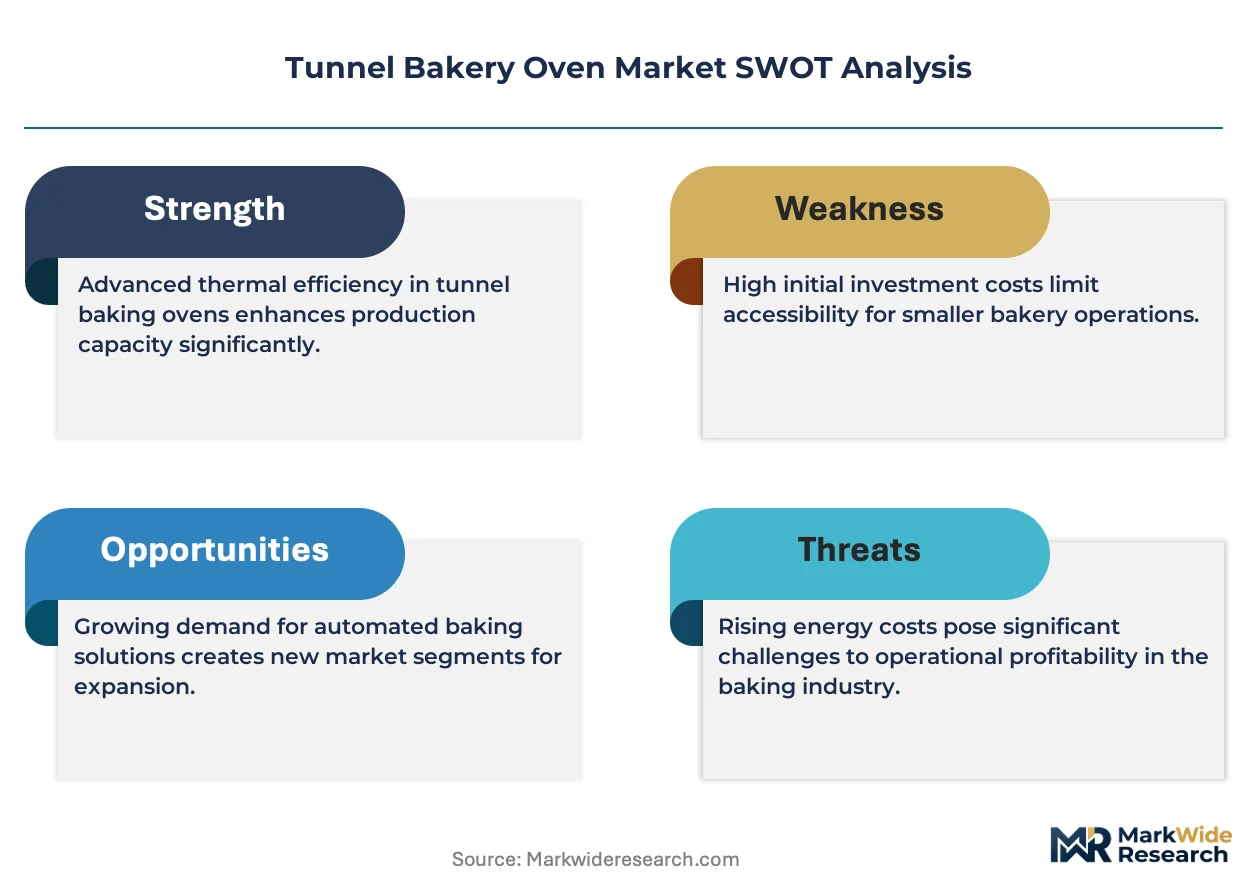
EU Ecodesign Directive efficiency benchmarks gate qualified supply for premium-tier tunnel bakery oven procurement, restricting market access to certified European and East Asian manufacturers while compressing margins for non-compliant imports facing carbon border adjustment exposure.
Pricing Analysis
Input-cost pass-through from copper and nickel volatility directly pressures electric heating element fabrication, forcing manufacturers to absorb margin compression or escalate contract pricing. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified electric systems from depreciated gas-fired units and compact hybrid configurations. Price differentiation centers on CE marking tier and after-sales service bundling. Cost compression in the standard tier intensifies because commodity supply squeezes coincide with buyer consolidation among North American bakery chains. Food processing plants with 24-hour operational requirements show least price sensitivity; independent artisan bakeries scaling from batch production exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Freight cost escalation from Dutch and Swedish fabrication hubs to Indian and Southeast Asian end-markets reshapes total landed cost calculations for compact hybrid tunnel configurations. Manufacturing concentrates in Germany, the Netherlands, and Sweden for premium conveyor systems; China supplies standardized components and proofing-integrated line subassemblies. Raw material dependencies draw from aluminized steel sheet, ceramic-coated composites, and precision induction heating elements. Single-source vulnerability concentrates in European-engineered combustion control systems. Distribution runs through manufacturer-direct sales for large food processing plants and specialized equipment distributors serving artisan bakery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tunnel bakery oven market functions as a stable compounder, with regulatory-mandated replacement cycles providing predictable demand visibility across European and North American industrial baking infrastructure.
For Market Incumbents: Acquire aftermarket parts and service networks to lock in recurring revenue streams and defend against equipment-as-a-service entrants. Deepen backward integration into induction heating element production to offset copper and nickel price volatility. Prioritize certification investment for EU Ecodesign and EPA emissions compliance to maintain access to replacement cycle demand in Midwest and Southeast US food processing corridors.
For New Entrants and Emerging Players: Compact hybrid tunnel configurations for scaling artisan bakeries represent the most penetrable buyer archetype, with India and Southeast Asian organized retail chains offering white-space expansion. Target Mumbai and Bangalore urban markets where FSSAI-standardized food processing creates first-mover advantages. Pursue technology licensing partnerships with established European engineering houses to bypass JIS and GB certification barriers in Japan and China.
For Investors and Strategic Acquirers: Roll-up economics work for regional combustion control specialists because gas-to-electric transition demand creates fragmented acquisition targets with complementary technical capabilities. The 5-10 year viability window favors platforms consolidating electric heating engineering and proofing-tunnel integration expertise. Watch carbon border adjustment mechanism implementation timing as the critical inflection signal for import-competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Heating Technology Licensing | Accelerates market entry for manufacturers lacking in-house induction engineering capabilities. |
| Equipment-as-a-Service Contracting | Shifts revenue recognition from capital sales to recurring per-unit-baked pricing among North American chains. |
| Aluminized Steel Supply Agreement | Secures thermal mass reduction materials from Dutch and Swedish metallurgical suppliers. |
| Proofing-Tunnel Integration Partnership | Combines fermentation and baking stages for French and Austrian laminated dough exporters. |
| Aftermarket Parts Network Expansion | Captures stranded asset service demand from depreciated gas-fired installations in UK plants. |
Research Methodology
Bottom-up bakery and food processing plant modeling reconciled against top-down equipment manufacturer production tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads capture operational requirements and replacement cycle timing. Secondary validation draws from EU Ecodesign compliance registries, EPA emissions filings, SEC 10-K equipment manufacturer disclosures, and customs trade data for oven component imports. Triangulation between demand-side capacity planning and supply-side order backlogs ensures consistency across volume and value estimates.
Historical trendline analysis of industrial baking capacity expansion and energy-efficiency retrofit cycles anchors the projection framework. Segmentation modeling spans product type, thermal technology, application, and end-user scale across the analysis window. CAGRs derive from fitted growth curves applied to certified equipment adoption rates and regulatory deadline impacts. Industry-specific forecast inputs include EU carbon border adjustment mechanism implementation schedules and FSSAI standardization timelines for Indian food processing infrastructure.
Underlying measurement precision varies by segment; electric and hybrid technology segments carry tighter precision than depreciated gas-fired installed base estimates. Forecasts reflect assumptions about regulatory enforcement consistency and commodity price stability that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bakery Conditioner Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Sweet Biscuits Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Bakery Fats Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Pastry Dough Market
Bakery Products
Marzipan Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
South America Ice Cream Market
Bakery Products
Flatbread Market
Bakery Products
Pastries Market